
 Global Nanoemulsion Market | 2026-2036
Global Nanoemulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanoemulsion Market Foresight
Project finance for continuous manufacturing lines is narrowing the competitive field in nanoemulsion production, favoring firms with access to long-dated capital pools. Croda International PLC leverages its lipid excipient vertical to sustain formulation leadership across pharmaceutical and personal care segments. BASF SE anchors European supply through its high-pressure homogenization infrastructure, while Ascendia Pharmaceuticals specializes in nanosol technology for injectable therapeutics.
Nanoemulsions are thermodynamically stable dispersions with droplet sizes typically below 200 nanometers, engineered through high-energy methods such as microfluidization or ultrasonic homogenization to enhance solubility and controlled release of hydrophobic actives. Oil-in-Water formulations dominate pharmaceutical applications due to superior patient tolerability and scalable sterile processing, while Water-in-Oil architectures command premium positioning in dermal cosmeceuticals where prolonged occlusion drives efficacy. Multiple Emulsions represent the fastest-evolving frontier, attracting investment from drug manufacturers seeking programmable release kinetics for biologics.
FDA, EMA, and REACH collectively govern nanoemulsion commercialization through divergent toxicity testing mandates and labeling requirements that shape development timelines and market access strategies. The FDA's nanotechnology guidance demands extensive characterization data, while REACH imposes substance-by-substance registration burdens on nanoscale ingredients entering European supply chains. Stakeholders must monitor evolving regulatory convergence on particle size distribution metrics and stability testing protocols to anticipate compliance costs and geographic prioritization.
Market Dynamics
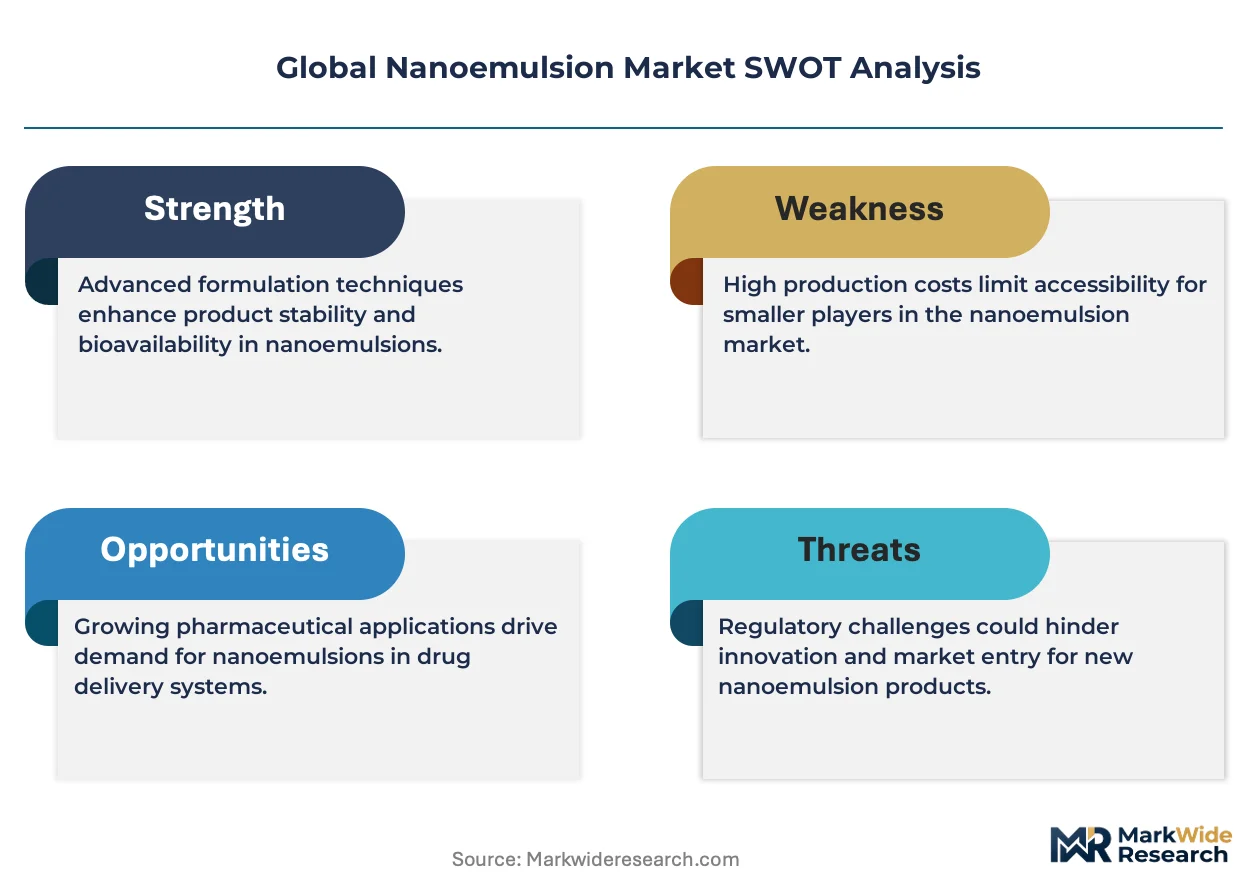
Continuous manufacturing scale-up requirements are concentrating nanoemulsion production among capital-rich contract manufacturers, while FDA and EMA divergence on stability testing protocols fragments regulatory strategy across development pipelines.
Growth Catalysts
- Injectable biologics expansion:Parenteral drug developers are prioritizing nanoemulsion carriers for hydrophobic APIs, with sterile processing capabilities becoming a decisive supplier selection criterion.
- REACH nanomaterial registration frameworks:European substance-by-substance disclosure mandates are accelerating investment in characterization infrastructure, favoring early-compliant formulation houses.
- High-pressure homogenization advances:Equipment manufacturers have reduced energy inputs per batch by refining microfluidization chamber geometries, improving process economics for mid-scale pharma clients.
Market Restraints
- Phospholipid supply concentration:Egg and soybean lecithin sourcing clusters in Argentina and Ukraine, exposing formulators to agricultural volatility and geopolitical disruption.
- Thermodynamic stability thresholds:Droplet coalescence during freeze-thaw cycles limits shelf-life claims, constraining distribution to cold-chain-capable channels.
- EMA-FDA divergence on particle sizing:Inconsistent acceptance criteria for dynamic light scattering data force duplicate method validation, extending IND-to-NDA timelines.
Strategic Opportunities
- Indian CDMO capacity buildout:CDSCO's streamlined nanoformulation approval pathways and PLI scheme incentives are attracting Western pharma outsourcing for Phase III materials.
- Ophthalmic nanoemulsion platforms:Topical ocular delivery of corticosteroids and immunosuppressants remains underdeveloped relative to dermal and parenteral segments.
- Microfluidic process analytical technology integration:Real-time droplet size monitoring using in-line PAT sensors is compressing batch release timelines from weeks to days.
Industry Challenges
- Formulation scientist scarcity:Cross-disciplinary expertise spanning colloid chemistry, sterile processing, and regulatory science commands premium compensation, constraining mid-tier firm hiring.
- Technology transfer complexity:Scale-dependent shear rate profiles between R&D homogenizers and production units frequently destabilize droplet distributions, requiring costly re-validation.
- Excipient master file coordination:Multi-supplier lipid sourcing complicates Type II DMF maintenance, with supplier change notifications triggering CMC review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanoemulsion Market |
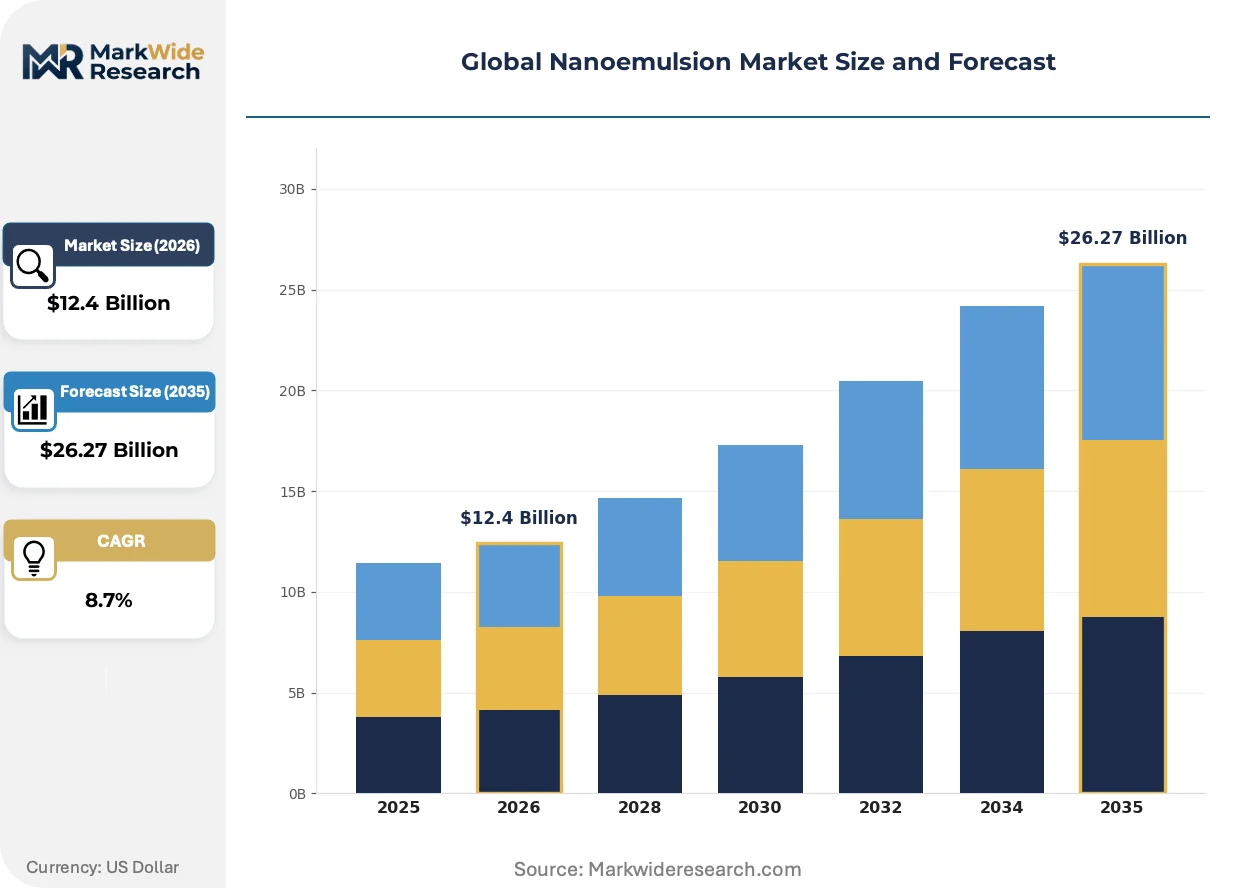
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-in-Water, Water-in-Oil, Bi-continuous, Multiple Emulsions Application: Pharmaceuticals, Cosmetics, Food & Beverages, Agrochemicals, Nutraceuticals End User: Drug Manufacturers, Personal Care Brands, Food Processors, Crop Protection Firms Packaging Type: Glass Bottles, Plastic Containers, Dropper Bottles, Sachets |
| Companies Covered | Covaris Inc., Ascendia Pharmaceuticals, Allergan plc, Croda International PLC, Latitude Pharmaceuticals Inc., AbbVie Inc., IDEX Corporation, BASF SE, AstraZeneca Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanoemulsion Market Shifts & Advancements
Digital twin modeling of emulsification kinetics is compressing formulation development cycles, while regulatory pressure on nanomaterial characterization is reshaping analytical service demand.
Microfluidic reactor platforms are virtualizing traditional batch homogenization by enabling precise control over droplet formation through laminar flow mixing. Parenteral drug developers in Boston and Basel are piloting these systems for clinical-scale GMP production. The technology is virtualizing capital allocation patterns, with equipment spend shifting from large-volume tanks toward modular, skid-mounted units that reduce cleanroom footprint.
REACH's 2023 nanomaterial registration updates impose expanded toxicological dossier requirements on oil-phase ingredients below 100 nanometers. Formulators must now submit dissolution kinetics and biodistribution studies for each new chemical entity. European pharmaceutical sponsors are responding by front-loading characterization work during preclinical phases, extending early development timelines but reducing late-stage regulatory risk.
Hospital procurement consortia are consolidating nanoemulsion sourcing for oncology supportive care, replacing fragmented distributor relationships with direct manufacturer contracts tied to sterility assurance metrics. This concentration is most visible in United States academic medical centers, where pharmacy and therapeutics committees now mandate single-source agreements for high-risk injectable emulsions to standardize adverse event traceability.
Global Nanoemulsion Market Segmentation
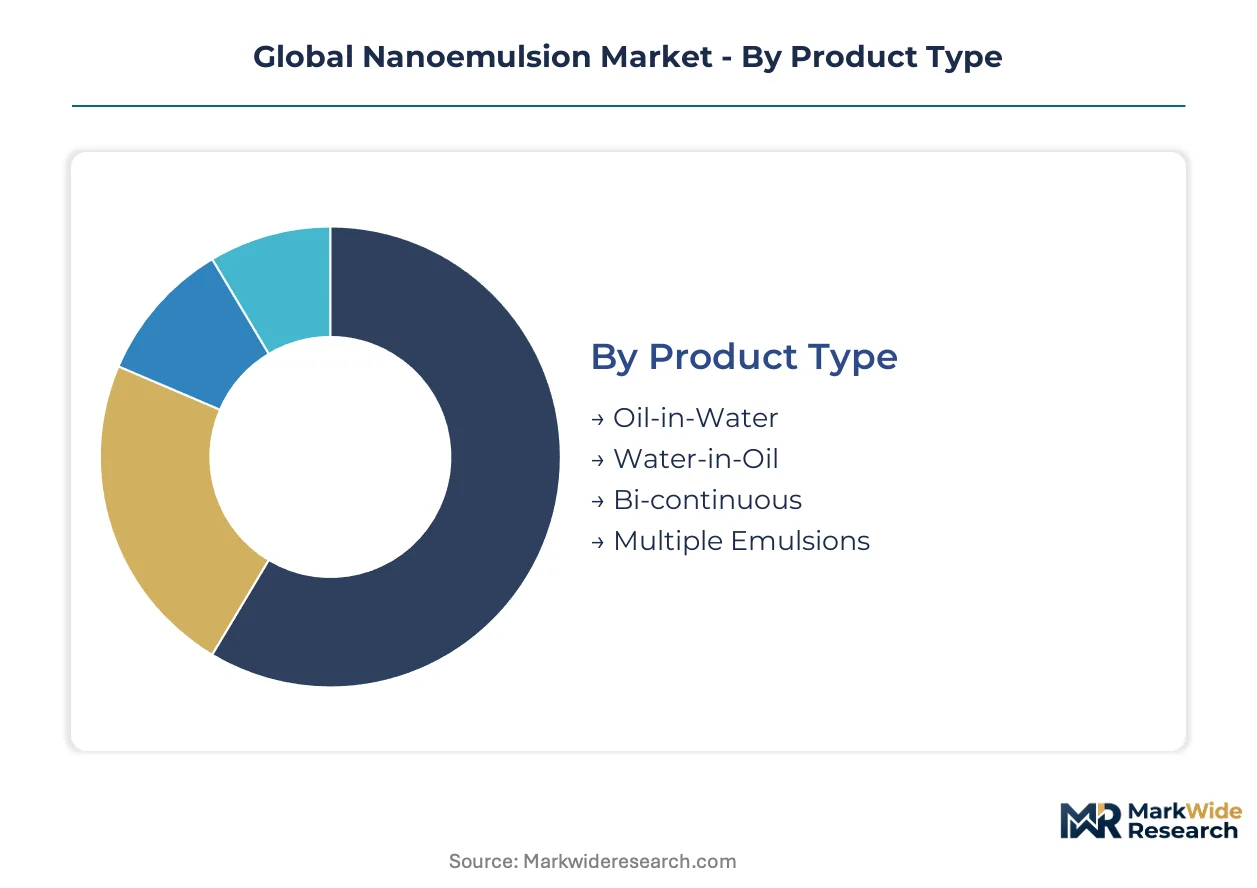
Nanoemulsion formulation architectures dictate manufacturing infrastructure requirements, regulatory pathways, and margin structures. Application-driven demand patterns reveal divergent growth trajectories across therapeutic, cosmetic, and agricultural end-uses.
Product Type:
Formulation architecture determines energy input requirements, stability profiles, and commercial scalability across production scales.
- Oil-in-Water:Hydrophobic actives disperse within aqueous continuous phases, enabling sterile filtration and intravenous administration. Demand concentrates in United States parenteral drug manufacturing, driven by FDA approvals for oncology supportive care emulsions requiring narrow droplet size distributions.
- Water-in-Oil:Aqueous droplets suspend within lipid continuous phases, creating occlusive films for dermal delivery. Personal care brands in France and Germany command premium positioning for ceramide-loaded night treatments exploiting prolonged skin retention kinetics.
- Bi-continuous:Interpenetrating aqueous and oil domains accommodate simultaneous hydrophilic and lipophilic actives. Nutraceutical manufacturers in Japan leverage this architecture for dual-release omega-3 and polyphenol formulations.
- Multiple Emulsions:Compartmentalized water-oil-water structures enable programmable release profiles for biologics. Boston and Basel drug developers pilot these systems for peptide therapeutics requiring pulsatile delivery kinetics.
Oil-in-Water holds installed capacity. Multiple Emulsions is rotating up the share rankings.
Application:
End-use sectors impose distinct purity grades, stability specifications, and channel access requirements on nanoemulsion suppliers.
- Pharmaceuticals:Injectable and topical drug delivery dominates value capture, with EMA nanomaterial registration mandates and FDA sterility guidelines shaping development economics. United States biotech clusters drive demand for lipid nanoparticle mRNA carriers.
- Cosmetics:Dermal anti-aging and sun care applications exploit nanoemulsion optical clarity and sensorial profiles. Korean beauty brands lead formulation innovation for cushion compact and serum architectures.
- Food & Beverages:Bioactive encapsulation for beverages and fortified oils addresses solubility limitations of carotenoids and vitamins. Brazilian and Argentine processors adopt high-pressure homogenization for omega-3 emulsified juices.
- Agrochemicals:Pesticide and fertilizer nanoemulsions improve foliar adhesion and controlled release. Indian crop protection firms respond to Central Insecticides Board registration pathways for nanoscale active ingredients.
- Nutraceuticals:Dietary supplement applications emphasize gastric stability and lymphatic absorption enhancement. Australian manufacturers target TGA-listed complementary medicines with curcumin and coenzyme Q10 nanoemulsions.
Pharmaceuticals commands premium pricing tiers. Food & Beverages is expanding most quickly in production volume terms.
End User:
Customer scale and vertical integration depth determine contract manufacturing versus captive production decisions.
- Drug Manufacturers:Large pharmaceutical sponsors and emerging biotechs outsource sterile nanoemulsion production to CDMOs with validated high-pressure homogenization lines. United States and Swiss sponsors prioritize facilities with FDA and Swissmedic dual inspections.
- Personal Care Brands:Multinational cosmetics houses and indie beauty labels source from specialized excipient suppliers. French and Italian brands emphasize sustainable palm-free lipid sourcing certifications.
- Food Processors:Dairy, beverage, and functional food manufacturers integrate homogenization for texture modification and nutrient delivery. New Zealand and Irish dairy cooperatives lead clean-label nanoemulsion adoption for infant formula lipids.
- Crop Protection Firms:Agricultural chemical companies reformulate existing actives into nanoemulsion concentrates for improved rainfastness. Brazilian and Chinese firms navigate divergent national pesticide registration frameworks.
Drug Manufacturers concentrate outsourced spend. Food Processors is gaining share fastest among vertically integrating customer segments.
Packaging Type:
Primary container selection governs sterility assurance, light protection, and patient administration ergonomics.
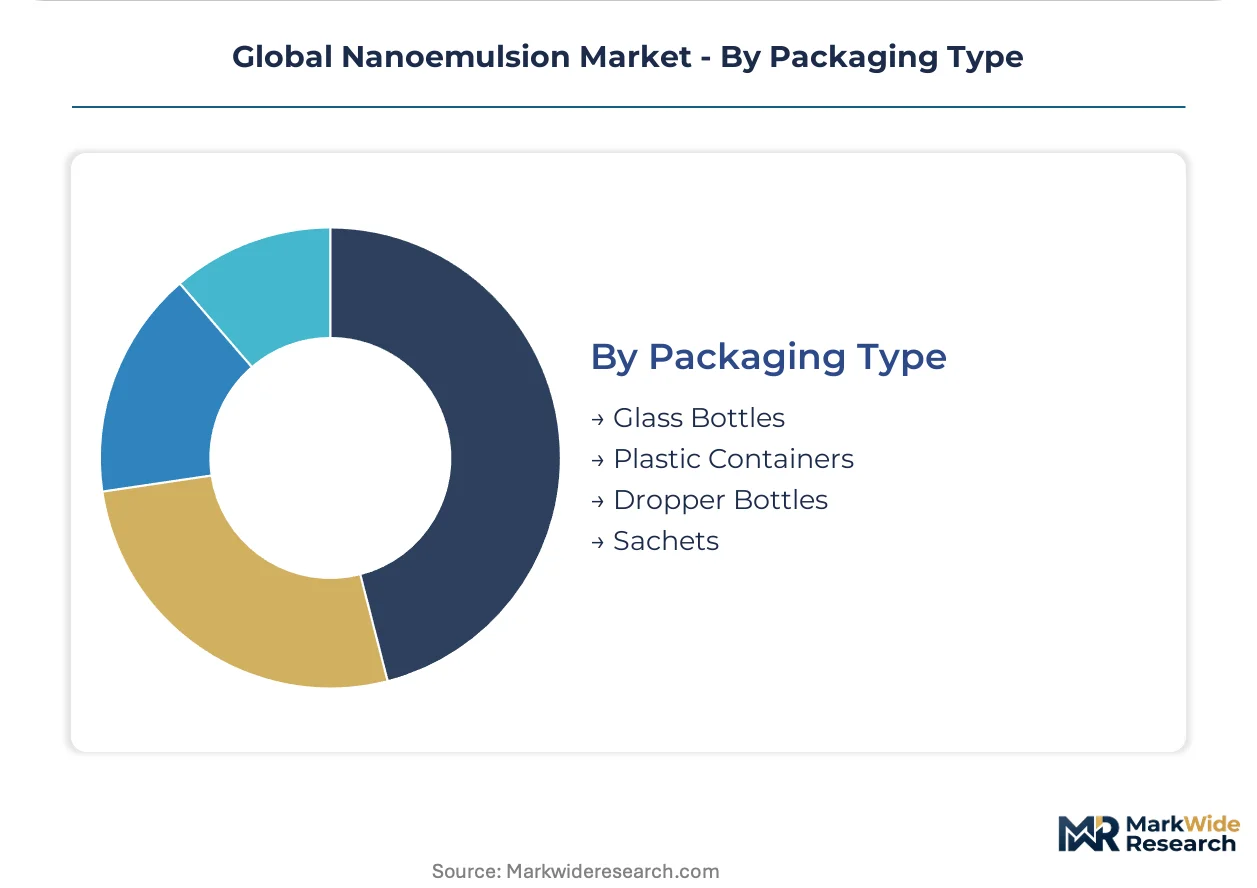
- Glass Bottles:Type I borosilicate vials dominate parenteral oncology emulsions, with United States hospital consortia mandating break-resistant coated glass for high-value injectables.
- Plastic Containers:Cyclic olefin polymer and polyethylene terephthalate bottles serve oral and topical over-the-counter applications. German and Japanese packaging converters lead barrier coating technologies.
- Dropper Bottles:Precision dosing formats target ophthalmic and pediatric liquid formulations. Italian and French cosmetic brands specify calibrated pipette assemblies for serum positioning.
- Sachets:Unit-dose flexible pouches enable emerging market access and travel-size cosmetics. Indian and Indonesian converters scale form-fill-seal lines for nutraceutical single-serve formats.
Glass Bottles anchors sterile pharmaceutical capacity. Sachets is climbing the fastest in unit volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's streamlined nanoformulation approval pathways and PLI scheme incentives are attracting Western pharmaceutical outsourcing to Indian CDMOs. FDA nanotechnology guidance and EMA nanomaterial registration mandates are reshaping development timelines across major markets. REACH's 2023 nanomaterial registration updates impose expanded toxicological dossier requirements on oil-phase ingredients below 100 nanometers.
United States
FDA approvals for nanoemulsion-based therapeutics drive demand concentration, with Boston and San Francisco biotech clusters channeling significant R&D investment into lipid nanoparticle mRNA carriers. The agency's nanotechnology guidance demands extensive characterization data for IND submissions. Hospital procurement consortia in academic medical centers now mandate single-source agreements for high-risk injectable emulsions.
Germany
BASF SE anchors European supply through high-pressure homogenization infrastructure serving pharmaceutical and personal care segments. REACH imposes substance-by-substance registration burdens on nanoscale ingredients entering European supply chains. Frankfurt and Ludwigshafen chemical clusters coordinate lipid excipient sourcing for sterile formulation houses.
India
CDSCO's streamlined nanoformulation approval pathways and PLI scheme incentives are attracting Western pharma outsourcing for Phase III materials. The regulator's alignment with ICH guidelines accelerates clinical trial approvals for nanoemulsion-based generics. Hyderabad and Ahmedabad CDMO clusters are building validated high-pressure homogenization lines for parenteral drug manufacturing.
Switzerland
Swissmedic dual-inspected facilities attract United States and European sponsors seeking sterile nanoemulsion production for injectable biologics. The regulator's convergence with EMA stability testing protocols reduces duplicate method validation burdens. Basel drug developers pilot multiple emulsion systems for peptide therapeutics requiring pulsatile delivery kinetics.
Japan
PMDA guidelines on nanomaterial-containing pharmaceuticals shape local development economics for ocular and dermal delivery systems. METI funding for continuous manufacturing infrastructure supports microfluidic reactor adoption. Tokyo and Osaka nutraceutical manufacturers leverage bi-continuous architectures for dual-release omega-3 and polyphenol formulations.
Global Nanoemulsion Market Competitive Landscape
On the supply side, the industry is consolidating around capital-rich contract manufacturers with validated continuous processing lines and dual-inspected GMP facilities. High-pressure homogenization equipment manufacturers and lipid excipient suppliers occupy adjacent positions in the value chain. Three strategic archetypes dominate: integrated chemical conglomerates with excipient verticals, specialized nanosol technology firms, and sterile-focused CDMOs. Competitive moves center on capacity expansion in Indian and Swiss facilities and technology licensing for microfluidic process analytical technology.
Among the named participants, Croda International PLC and BASF SE represent integrated chemical conglomerates with lipid excipient verticals sustaining formulation leadership across pharmaceutical and personal care segments. Ascendia Pharmaceuticals occupies a specialist position in nanosol technology for injectable therapeutics. These three exemplify how supply-side concentration favors firms with backward integration into excipient sourcing or proprietary nanosol platforms.
| Leading Market Players |
|---|
| Covaris Inc. |
| Ascendia Pharmaceuticals |
| Allergan plc |
| Croda International PLC |
| Latitude Pharmaceuticals Inc. |
| AbbVie Inc. |
| IDEX Corporation |
| BASF SE |
| AstraZeneca Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors transmit energy cost volatility from European lipid excipient hubs to downstream sterile formulation houses, compressing margins for mid-tier CDMOs while amplifying pricing power for BASF SE and Croda International PLC with captive phospholipid supply.
Pricing Analysis
Certification level creates the primary spread between FDA-validated sterile nanoemulsions and cosmetic-grade alternatives. Three-tier pricing structure across GMP-certified, ISO-registered, and unregistered formulation levels reflects sterility assurance investment and regulatory filing burden. Pricing pressure stems from hospital procurement consortia consolidating to single-source agreements for high-risk injectables. Generic drug manufacturers exhibit highest price sensitivity, while orphan disease sponsors accept premium positioning for validated lipid nanoparticle carriers.
Supply Chain Analysis
Export-control restrictions on high-pressure homogenization equipment limit technology transfer to Indian and Chinese CDMOs, preserving European and North American equipment manufacturer dominance. Supply concentrates in Germany, Switzerland, and the United States for sterile formulation capacity, while Argentina and Ukraine anchor phospholipid raw material sourcing. Egg and soybean lecithin dependencies expose formulators to agricultural commodity swings. Single-source vulnerability runs through Ukrainian lecithin processing clusters disrupted by geopolitical conflict. Distribution runs through direct manufacturer contracts with hospital consortia, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary expertise spanning colloid chemistry, sterile processing, and regulatory science commands premium compensation, constraining mid-tier firm hiring and amplifying returns for integrated players with in-house capability depth.
For Market Incumbents: Entrench formulation leadership through backward integration into phospholipid excipient sourcing, mirroring Croda International PLC's lipid vertical strategy. Expand high-pressure homogenization capacity in Swissmedic dual-inspected Basel facilities to capture United States and European sponsor outsourcing. Neutralize emerging Indian CDMO threats by front-loading EMA nanomaterial registration dossiers ahead of REACH enforcement waves.
For New Entrants and Emerging Players: Ophthalmic nanoemulsion platforms for corticosteroid and immunosuppressant delivery represent the most penetrable white space, with topical ocular development lagging dermal and parenteral segments. Target CDSCO-aligned Indian CDMO partnerships for Phase III material production, leveraging PLI scheme incentives and streamlined approval pathways. Pursue microfluidic process analytical technology licensing to compress batch release timelines against incumbent batch homogenization economics.
For Investors and Strategic Acquirers: Sterile-focused CDMOs with validated continuous manufacturing lines and dual-inspected GMP facilities present the most defensible acquisition profile across the projection horizon. Monitor EMA-FDA convergence signals on particle sizing acceptance criteria as inflection indicator for regulatory burden reduction and valuation multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Homogenization Capacity Expansion | BASF SE's Ludwigshafen infrastructure anchors European sterile supply security. |
| Dual-Inspection GMP Facility Certification | Swissmedic-FDA alignment reduces duplicate validation for Boston biotech sponsors. |
| Microfluidic PAT Technology Licensing | Real-time droplet monitoring compresses release timelines from weeks to days. |
| Phospholipid Excipient Backward Integration | Croda International PLC's lipid vertical insulates against Argentine supply volatility. |
| CDSCO-Aligned Indian CDMO Partnership | Hyderabad clusters capture Western Phase III outsourcing via PLI incentives. |
Research Methodology
Initial hypotheses were tested against primary input from sterile formulation scientists, regulatory affairs directors at EMA and FDA submission teams, hospital pharmacy and therapeutics committee members, and high-pressure homogenization equipment engineers, then refined against secondary validation from FDA nanotechnology guidance documents, EMA nanomaterial registration frameworks, CDSCO approval pathway records, and REACH substance dossier requirements. Bottom-up capacity modeling at individual CDMO facilities triangulated against top-down demand aggregation across therapeutic applications.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning formulation architecture, application sector, end-user vertical integration depth, and regional regulatory cluster. CAGRs derived from installed capacity expansion announcements, sponsor pipeline disclosure patterns, and excipient consumption trajectory analysis. Forecast inputs incorporated phospholipid price index movements and continuous manufacturing adoption curves.
Practitioners should monitor EMA-FDA regulatory convergence timelines, Indian PLI scheme extension decisions, and phospholipid supply disruption indicators for early signals of forecast deviation. Material shifts in REACH nanomaterial enforcement intensity or high-pressure homogenization equipment export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market