
 Nanoscale Chemicals Market | 2026-2036
Nanoscale Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoscale Chemicals Market Foresight
PhD-level nanomaterial chemists and process engineers is reorganizing competitive dynamics as foundries and specialty chemical houses compete for scarce talent pools. BASF leverages its Ludwigshafen integrated research complex to sustain captive development of high-purity nanoparticle precursors. American Elements anchors North American supply through vertical control of rare-earth nanomaterial refining. SkySpring Nanomaterials specializes in catalog-scale production of metallic nanopowders for research and pilot manufacturing.
Nanoscale chemicals comprise engineered substances with at least one dimension between one and one hundred nanometers, typically synthesized through sol-gel processing, chemical vapor deposition, or mechanical milling to achieve quantum-confinement effects and surface-area-driven reactivity. These formulations serve as functional additives, catalysts, and structural reinforcements across precision manufacturing. Nanoparticles dominate current revenue as mature metal-oxide platforms feed established coating and electronics lines, while nanocomposites represent the fastest-expanding margin pool as automotive and aerospace OEMs qualify hybrid organic-inorganic systems for lightweighting. Nanotubes occupy a narrower but defensible niche where conductivity specifications command premium pricing from cable and thermal-management suppliers.
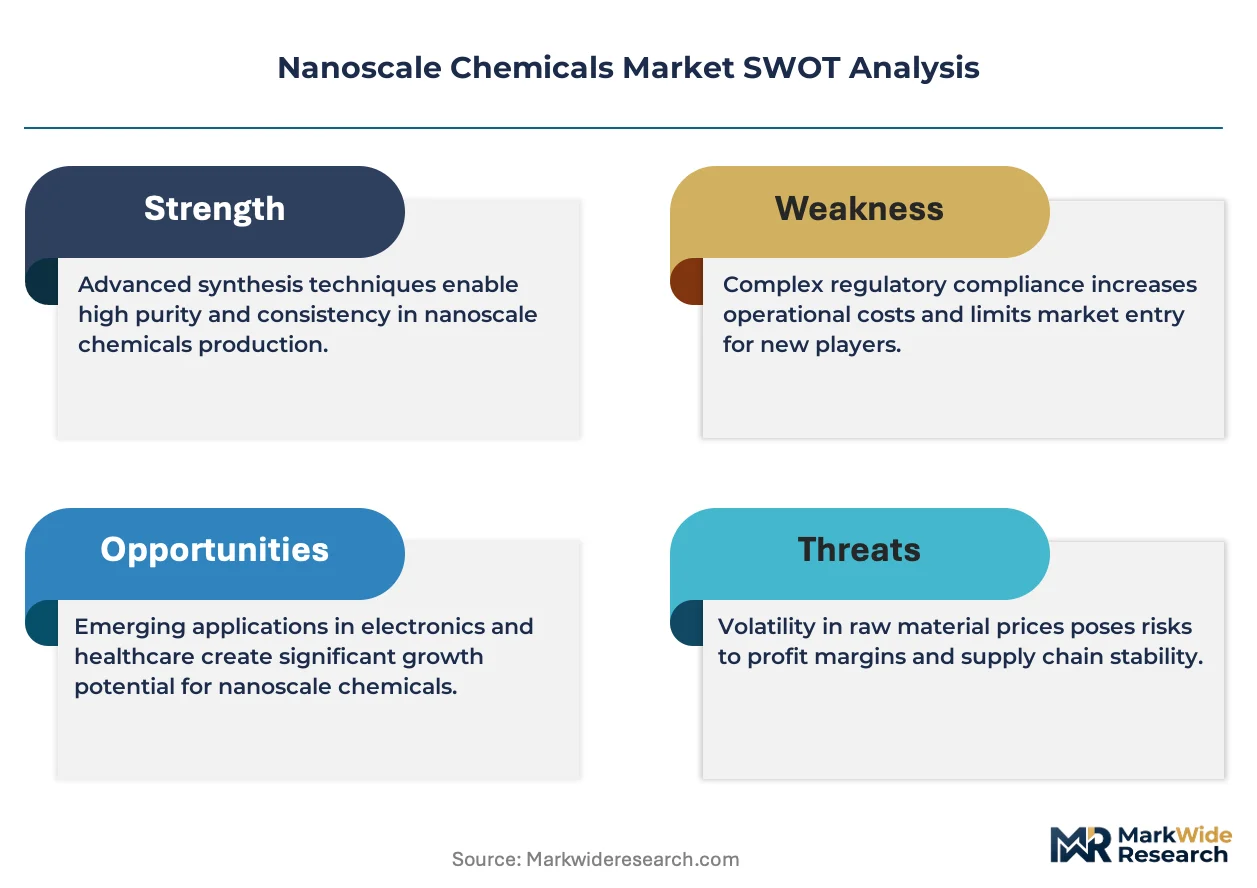
EPA emission standards and OSHA workplace exposure limits in the United States constrain facility siting and handling protocols for dry nanopowder operations, while REACH registration requirements in Europe mandate extensive toxicological dossiers for nanoscale substance imports. China's GB standards and NMPA oversight impose additional testing burdens on cross-border chemical shipments. Stakeholders must monitor evolving classification thresholds that could resegment product lines across regulatory jurisdictions.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are consolidating procurement of atomic-precision chemical precursors, compressing supplier margins while elevating purity specifications that only captive R&D complexes can satisfy.
Growth Catalysts
- REACH nanomaterial registration thresholds:European ECHA mandates are accelerating toxicological dossier standardization, forcing marginal suppliers to exit and concentrating volume among compliant producers.
- EV battery thermal management:Automotive OEMs in Germany and Japan are qualifying nanocomposite coolant additives for next-generation cell architectures.
- Sol-gel processing scale-up:Continuous-flow reactor deployment is reducing batch-to-batch variability for metal-oxide nanoparticle production.
Market Restraints
- Rare-earth oxide feedstock volatility:Chinese export quota fluctuations for lanthanide precursors destabilize cost forecasting for phosphor and catalyst manufacturers.
- Dry nanopowder handling infrastructure:OSHA respirable exposure limits mandate capital-intensive containment systems that exclude smaller compounders.
- Surface functionalization yield ceilings:Silane coupling efficiency plateaus at 85% for high-aspect-ratio nanotubes, constraining conductivity-per-cost ratios.
Strategic Opportunities
- Indian pharmaceutical nanocarrier adoption:CDSCO fast-track pathways for lipid-nanoparticle drug delivery systems are opening formulation partnerships with domestic API producers.
- Carbon nanotube-conductive polymer hybrids:Cable manufacturers are piloting co-extruded shielding materials that displace metal braid in aerospace harnesses.
- US Inflation Reduction Act clean chemistry incentives:Domestic nanomaterial production tax credits are reshoring precursor synthesis from Asian contract manufacturers.
Industry Challenges
- Atomic-layer deposition technician scarcity:Foundry expansion in Hsinchu and Pyeongtaek has exhausted regional vacuum-coating specialist pools.
- Multi-jurisdictional substance notification:Divergent China GB standards, EU REACH annex revisions, and EPA SNUR updates impose parallel compliance costs on single-SKU exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoscale Chemicals Market |
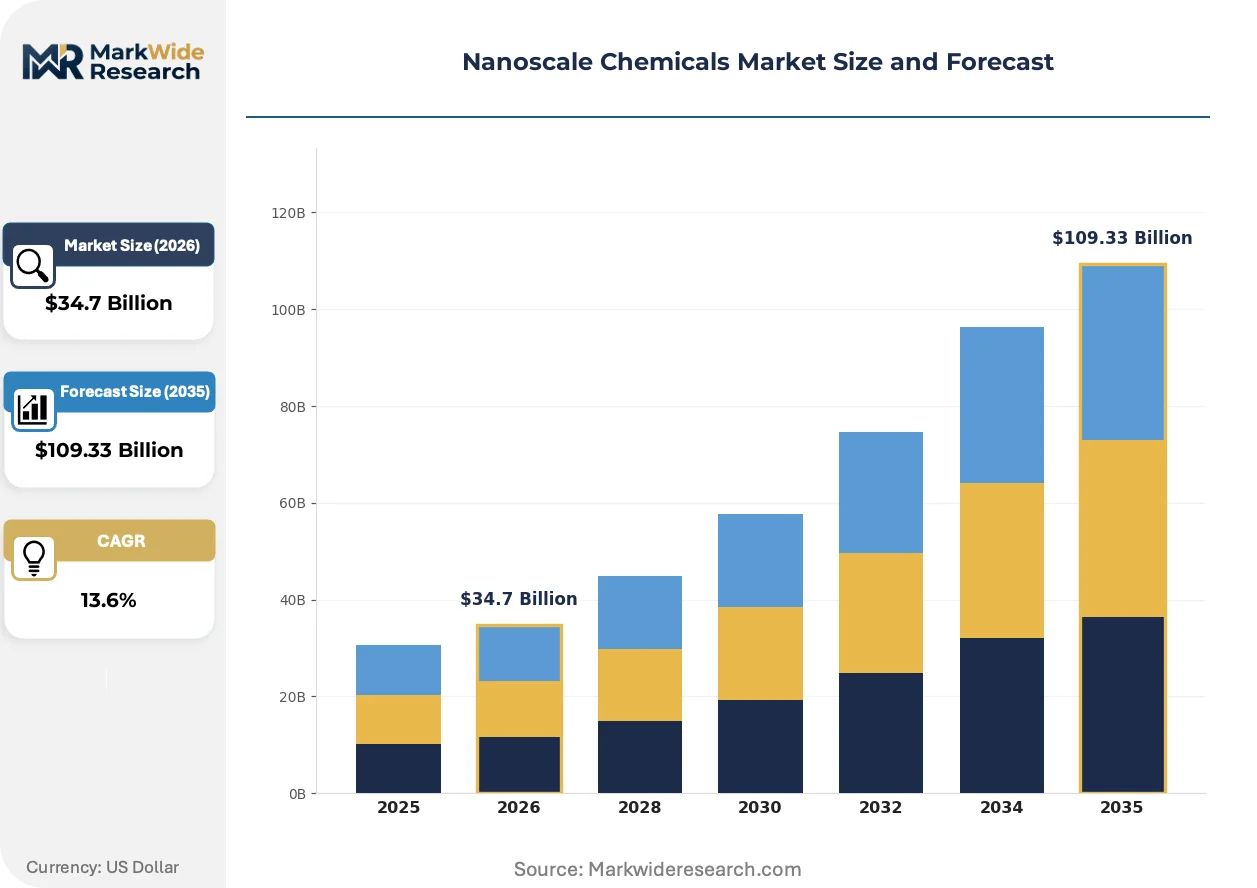
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $109.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Nanotubes, Nanocomposites, Nanosheets Application: Electronics, Coatings, Plastics, Textiles End User: Healthcare, Automotive, Aerospace, Agriculture Delivery Mode: Liquid, Powder, Gas, Emulsion |
| Companies Covered | NanoComposix, American Elements, Nanophase Technologies, eSpin Technologies, Nanosys, SABIC, BASF, SkySpring Nanomaterials, XG Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoscale Chemicals Market Shifts & Advancements
Process intensification and regulatory harmonization are compressing development cycles for nanomaterial applications, while end-user consolidation is rewriting procurement specifications.
Plasma-enhanced chemical vapor deposition for boron nitride nanotubes is fragmenting thermal interface material supply chains. Data center operators in Singapore and Ireland are qualifying hexagonal BN greases for 800G optical transceiver cooling. Legacy alumina and zinc oxide formulations are losing socket share as thermal conductivity specifications tighten.
China's GB/T 37625 nanomaterial labeling standards are mandating traceable particle-size distribution reporting for all cross-border shipments. Importers must now submit transmission electron microscopy batch records to customs authorities. European specialty chemical distributors are restructuring their China-facing product lines to segregate compliant and non-compliant SKUs.
Specification-driven vendor consolidation is concentrating foundry chemical procurement among three qualified suppliers per precursor category. Samsung and TSMC are enforcing dual-source requirements that paradoxically reduce total supplier count while fragmenting volume allocation. Taiwan's Hsinchu Science Park now hosts dedicated technical service teams from every major precursor house.
Nanoscale Chemicals Market Segmentation
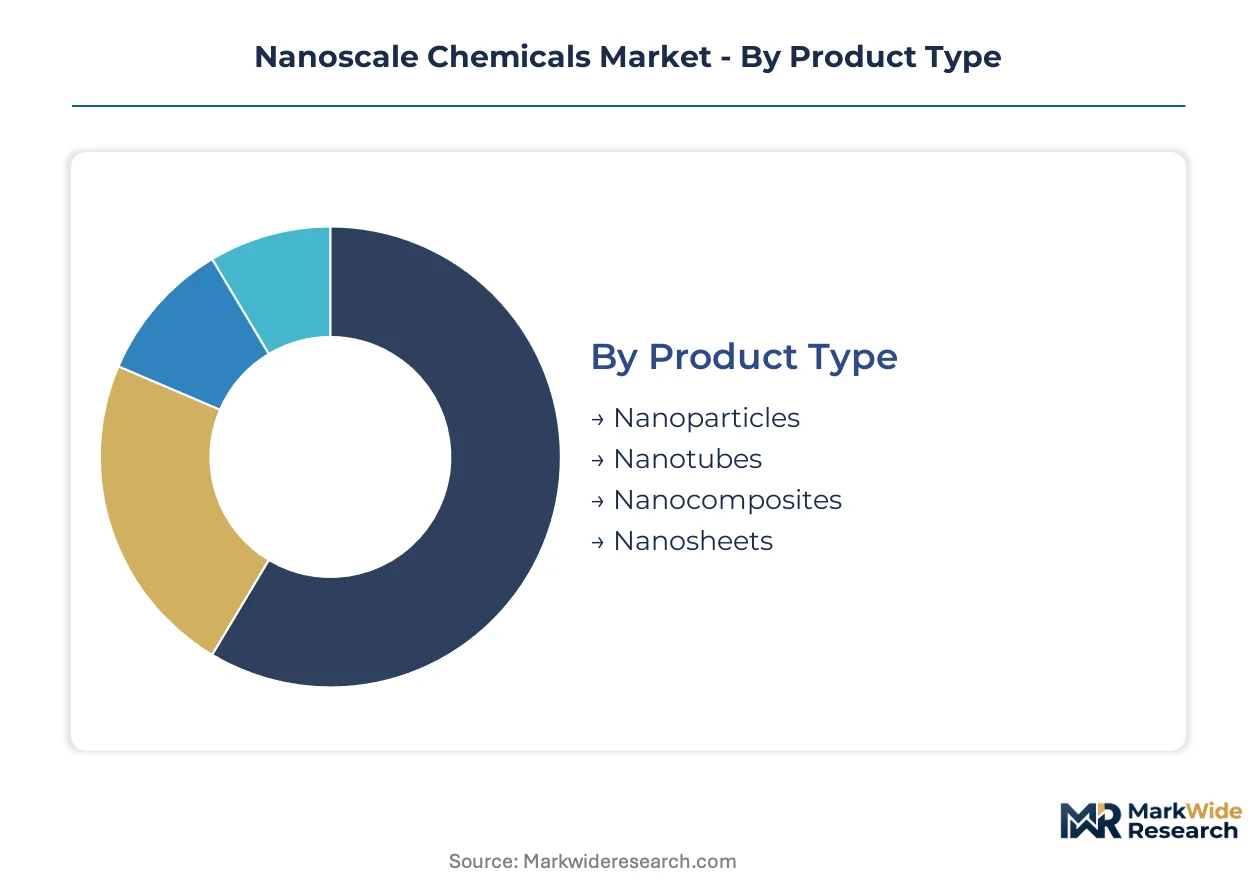
Segmentation in nanoscale chemicals reveals how atomic-precision requirements fragment procurement across divergent end-use specifications. Each dimension—product architecture, application interface, delivery physics, and customer industry—imposes distinct purity, handling, and regulatory compliance burdens that reshape supplier economics.
Product Type:
Export-led segments dominate revenue, with nanoparticles and nanotubes feeding East Asian semiconductor foundries and automotive supply chains, while nanocomposites and nanosheets serve more regionally anchored coating and construction markets.
- Nanoparticles:Metal-oxide spheres and quantum dots synthesized through sol-gel or flame pyrolysis, typically 10-100nm with controlled surface charge. Demand concentrates in Hsinchu and Pyeongtaek foundries where atomic-layer deposition precursors must meet sub-ppm metallic contamination thresholds; ECHA REACH dossier requirements now exclude non-compliant importers from European coating markets.
- Nanotubes:Single-walled and multi-walled carbon or boron nitride cylinders with aspect ratios exceeding 1000:1, delivering anisotropic thermal and electrical conductivity. German automotive OEMs in Stuttgart and Wolfsburg are qualifying hexagonal boron nitride nanotube greases for 800G optical transceiver cooling; plasma-enhanced chemical vapor deposition bottlenecks constrain supply elasticity.
- Nanocomposites:Hybrid organic-inorganic matrices dispersing nanoparticles into polymer, ceramic, or metallic hosts for structural reinforcement.
- Nanosheets:Two-dimensional materials including graphene, transition metal dichalcogenides, and exfoliated clays with sub-nanometer thickness.
Nanoparticles hold the largest share; momentum sits with nanocomposites as automotive lightweighting specifications tighten.
Application:
Cost tiering separates segments: electronics commands premium pricing for atomic-precision precursors, while coatings and plastics compete on volume-scale efficiency, and textiles occupy a developing mid-tier.
- Electronics:Semiconductor fabrication, printed circuit board metallization, and display phosphors requiring 99.999% purity metal-organic precursors. Taiwan's TSMC and South Korea's Samsung enforce dual-source procurement that fragments volume among qualified suppliers while elevating technical service requirements.
- Coatings:Anti-corrosion, self-cleaning, and optical functional layers deposited via spray, dip, or vapor processes. German industrial coating houses are consolidating nanoscale titanium dioxide procurement for photovoltaic anti-reflective layers; EPA emission standards constrain dry powder handling infrastructure in North American facilities.
- Plastics:Polymer nanocomposites enhancing barrier properties, flame retardancy, and mechanical strength for packaging and automotive components.
- Textiles:Antimicrobial, UV-blocking, and conductive fiber treatments using silver nanoparticles or carbon nanotube dispersions.
Electronics generates the highest margins; coatings deliver volume scale.
End User:
Customer type dictates regulatory exposure: healthcare faces the most stringent toxicological dossier requirements, aerospace demands qualification longevity, automotive emphasizes cost-volume optimization, and agriculture navigates emerging ecological risk frameworks.
- Healthcare:Drug delivery nanocarriers, diagnostic contrast agents, and antimicrobial medical device coatings. India's CDSCO fast-track pathways for lipid-nanoparticle formulations are attracting formulation partnerships with domestic API producers in Hyderabad and Ahmedabad.
- Automotive:Battery thermal management fluids, lightweight structural composites, and catalytic exhaust treatments. Japanese OEMs in Nagoya and Toyota City are qualifying nanocomposite coolant additives for solid-state cell architectures; rare-earth oxide feedstock volatility from Chinese export quotas destabilizes phosphor cost forecasting.
- Aerospace:Radar-absorbing materials, thermal protection systems, and conductive shielding harnesses.
- Agriculture:Precision nutrient delivery, pesticide nanoencapsulation, and soil remediation agents.
Healthcare commands premium pricing; automotive offers expansion velocity.
Delivery Mode:
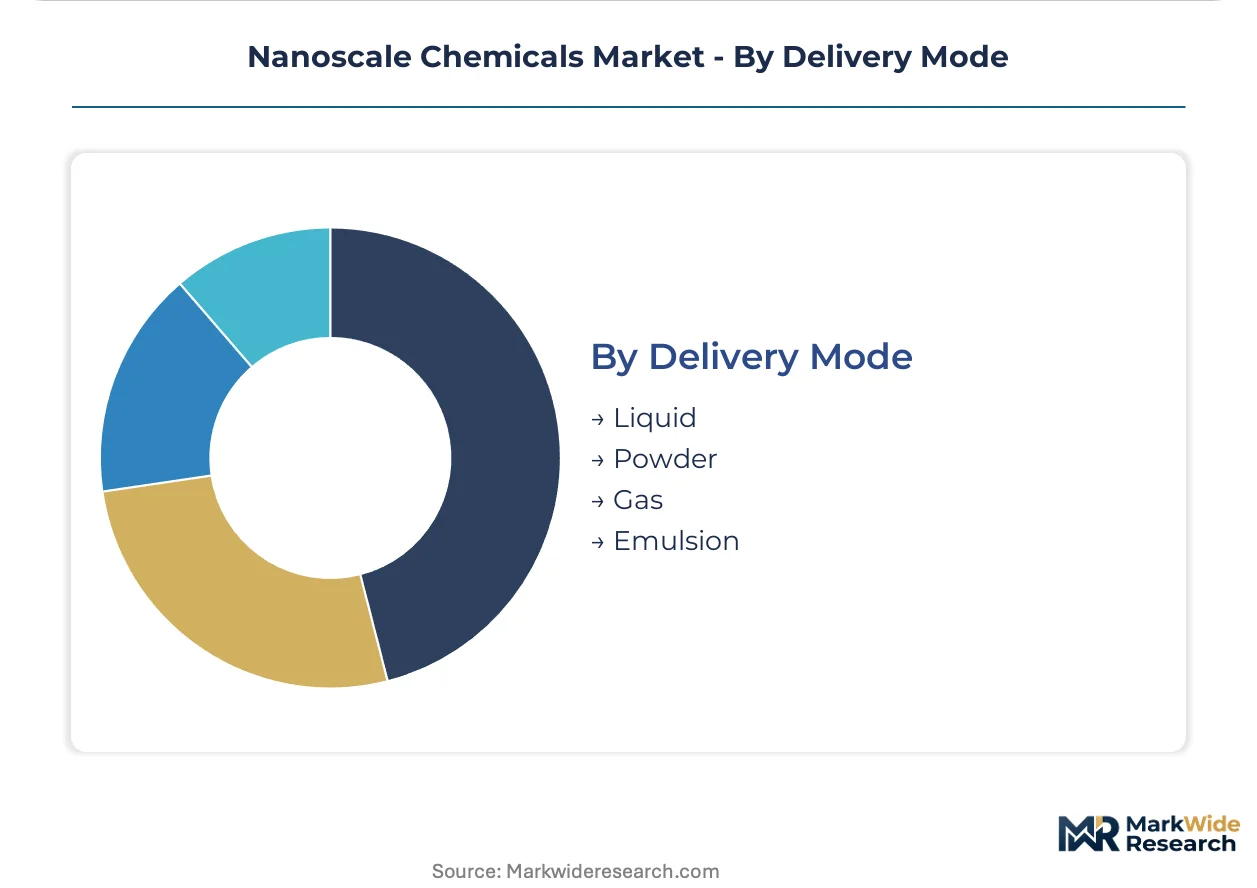
Volume concentration favors liquid dispersions for foundry chemical delivery, while powder handling requires capital-intensive containment that excludes smaller compounders; gas-phase and emulsion formats serve narrower specialty niches.
- Liquid:Colloidal suspensions, sol-gel precursors, and dissolved metal-organic complexes enabling precise dosing and continuous-flow processing. Continuous-flow reactor deployment in Ludwigshafen and Pasadena is reducing batch-to-batch variability for metal-oxide nanoparticle production.
- Powder:Dry nanopowders requiring specialized containment for OSHA respirable exposure limit compliance. Dry powder handling infrastructure mandates exclude smaller compounders from North American markets; surface functionalization yield ceilings at 85% for high-aspect-ratio nanotubes constrain conductivity-per-cost ratios.
- Gas:Aerosolized precursors for chemical vapor deposition and atomic layer deposition processes.
- Emulsion:Oil-in-water or water-in-oil dispersions stabilizing hydrophobic nanoparticles for textile and agricultural applications.
Liquid dominates procurement volume; powder commands specification premiums where containment infrastructure exists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA oversight in the United States anchors regulatory stringency for nanoscale chemical emissions, while ECHA REACH dossier requirements in Europe and China's GB standards collectively reshape cross-border trade flows for engineered nanoparticles.
United States
Domestic battery thermal management projects and semiconductor reshoring initiatives drive procurement of high-purity nanoparticle precursors. OSHA respirable exposure limits for dry nanopowder handling constrain facility siting in industrial corridors. Texas and Arizona industrial clusters host emerging precursor synthesis operations serving domestic foundry expansion.
Germany
Automotive OEM qualification programs for nanocomposite coolant additives and lightweight structural materials anchor demand growth. EU REACH annex revisions mandate updated toxicological dossiers for nanoscale substance imports. Stuttgart and Wolfsburg engineering centers coordinate supplier qualification for next-generation EV architectures.
South Korea
Foundry expansion in Pyeongtaek and Yongin concentrates procurement of atomic-layer deposition precursors for advanced node semiconductor fabrication. MFDS oversight of nanomaterial-containing consumer products adds compliance layers for domestic formulation houses. Samsung's dual-source requirements fragment volume allocation among qualified chemical suppliers.
China
Domestic rare-earth nanomaterial refining capacity and GB/T 37625 labeling standards for cross-border shipments reshape export economics. NMPA oversight of pharmaceutical nanocarriers imposes additional testing burdens on lipid-nanoparticle formulations. Yangtze River Delta chemical parks consolidate metal-oxide nanoparticle production for electronics and coatings.
India
CDSCO fast-track pathways for lipid-nanoparticle drug delivery systems attract formulation partnerships with domestic API producers. BIS certification requirements for imported nanomaterials create entry barriers for non-compliant suppliers. Hyderabad and Ahmedabad pharmaceutical clusters host technical collaboration programs between nanocarrier specialists and generic drug manufacturers.
Nanoscale Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in nanoscale chemicals, with captive R&D complexes commanding premium positions in foundry precursor supply. The specialist tier fragments across catalog-scale metallic nanopowder producers, nanocomposite formulators, and regional rare-earth refiners. Strategic archetypes include integrated chemical conglomerates with Ludwigshafen-style research campuses, rare-earth vertical specialists, and catalog-scale nanopowder houses. Competitive moves concentrate on dual-source qualification enforcement by semiconductor foundries and continuous-flow reactor deployment for batch consistency.
Among Germany-based integrated chemical conglomerates, BASF anchors the premium-tier vector through its Ludwigshafen research complex. American Elements represents North American rare-earth vertical specialists with upstream control over nanomaterial refining operations. SkySpring Nanomaterials exemplifies catalog-scale metallic nanopowder houses serving research and pilot manufacturing demand.
| Leading Market Players |
|---|
| NanoComposix |
| American Elements |
| Nanophase Technologies |
| eSpin Technologies |
| Nanosys |
| SABIC |
| BASF |
| SkySpring Nanomaterials |
| XG Sciences |
| Others |
Supply & Pricing Matrix
Boron nitride nanotube substitution for legacy alumina thermal greases simultaneously redraws procurement geography toward plasma-enhanced chemical vapor deposition specialists and compresses margin premiums for incumbent oxide suppliers. Foundry dual-source mandates fragment volume allocation while elevating technical service costs that suppliers must absorb.
Pricing Analysis
Long-term offtake contracts dominate foundry precursor procurement, though spot markets persist for research-grade nanopowders. Pricing stratifies across semiconductor-grade, industrial-grade, and laboratory-grade tiers, with purity certification from ECHA REACH dossiers commanding substantial premiums. Cost compression in metal-oxide nanoparticles is intensifying because continuous-flow reactor deployment standardizes output quality. Automotive OEMs exhibit highest price sensitivity due to volume-scale procurement, while semiconductor foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of rare-earth oxide feedstocks characterizes prudent procurement given Chinese export quota volatility, contrasting with just-in-time delivery for liquid colloidal precursors. Supply concentrates in China, South Korea, and Germany, with German automotive qualification programs anchoring European demand. The chain draws from lanthanide mining concentrates, metal-organic precursor synthesis, and surface functionalization chemistries. Single-source vulnerability pervades boron nitride nanotube supply due to plasma-enhanced chemical vapor deposition bottlenecks. Distribution runs through dedicated technical service teams at science parks rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward semiconductor foundries as TSMC and Samsung consolidate procurement among shrinking qualified supplier pools per precursor category. This concentration elevates technical service burdens and compresses margins for chemical houses.
For Market Incumbents: Shield market position by deepening captive R&D complexes for atomic-precision precursor development and securing dual-source qualification status at expanding Pyeongtaek and Hsinchu facilities. Surface functionalization yield ceilings threaten conductivity-per-cost ratios for nanotube suppliers, making backward integration into rare-earth oxide refining a critical defensive lever against Chinese quota volatility.
For New Entrants and Emerging Players: Lead with CDSCO-aligned lipid-nanoparticle formulation partnerships targeting Indian pharmaceutical clusters in Hyderabad and Ahmedabad, where fast-track regulatory pathways reduce entry barriers. Carbon nanotube-conductive polymer hybrids for aerospace cable shielding represent the most penetrable white-space segment, with co-extrusion process expertise as the essential go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with catalog-scale metallic nanopowder houses serving research demand, where consolidation with continuous-flow reactor specialists offers scale economics. The five-to-ten year viability window favors platforms with REACH dossier compliance already filed. Watch for Inflation Reduction Act clean chemistry incentive thresholds as the signal indicating reshoring inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Mitigates Chinese export quota exposure for phosphor and catalyst manufacturers. |
| Continuous-Flow Reactor Deployment | Reduces batch-to-batch variability for metal-oxide nanoparticle production at Ludwigshafen-scale facilities. |
| REACH Dossier Compliance Investment | Secures European market access as ECHA thresholds exclude marginal suppliers. |
| Dual-Source Qualification Pursuit | Enables volume allocation from Samsung and TSMC procurement consolidation. |
| Plasma-Enhanced CVD Capacity Expansion | Addresses boron nitride nanotube supply elasticity constraints for thermal interface materials. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across semiconductor foundry procurement teams, specialty chemical R&D directors, pharmaceutical formulation scientists, and automotive thermal management engineers. Secondary validation drew from ECHA REACH registration databases, SEC filings of listed chemical conglomerates, customs trade records for rare-earth oxide shipments, and ACC industry reports. Bottom-up volume modeling triangulated against top-down market sizing across nanoparticle, nanotube, nanocomposite, and nanosheet categories.
Across the analysis window, projections incorporate grade-tier segmentation spanning semiconductor-grade to laboratory-grade purity levels, end-use industry fragmentation across electronics and automotive, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating foundry capacity expansion timelines and automotive OEM qualification cycles. Forecast inputs include rare-earth oxide feedstock availability indices and plasma-enhanced chemical vapor deposition capacity utilization rates.
Forecasts assume regulatory continuity in EPA, ECHA REACH, and China GB/T regimes; material policy shifts would require re-modeling. Revision becomes warranted when semiconductor node transition timelines or Chinese rare-earth export quota severity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Graphene Aerogel Market