
 Graphene Aerogel Market | 2026-2036
Graphene Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Aerogel Market Foresight
Materials science PhD talent is rotating from semiconductor substrates toward advanced carbon nanostructures, easing formulation bottlenecks that previously constrained graphene aerogel commercialization. Aspen Aerogels leverages its legacy supercritical drying infrastructure to dominate high-temperature insulation contracts. Graphenea sustains European research partnerships that anchor its position in custom sheet production for catalysis clients. Cabot Corporation extends its carbon black distribution channels into graphene aerogel powder sales, competing on logistics scale rather than proprietary synthesis.
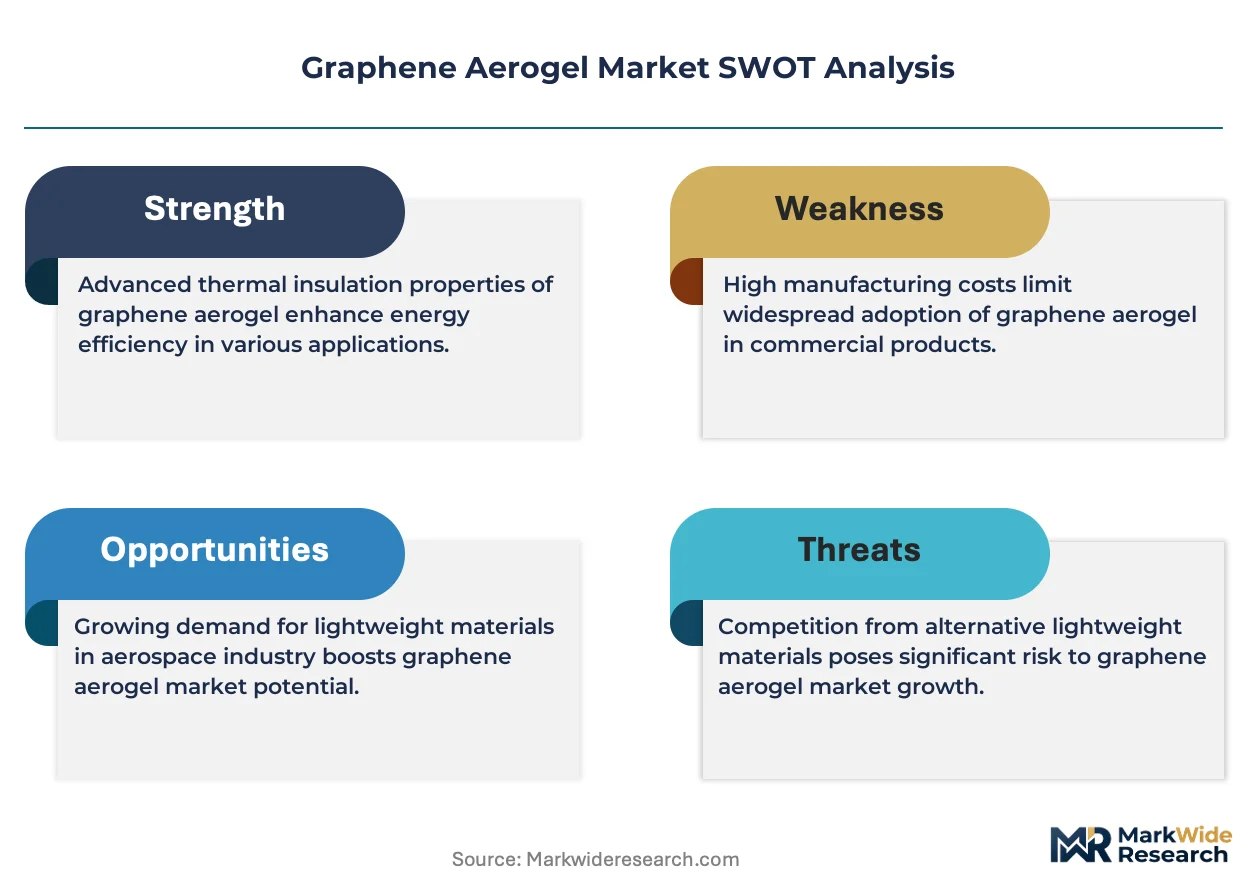
Graphene aerogel consists of a three-dimensional porous network of graphene sheets with bulk densities below 3 mg per cubic centimeter and surface areas exceeding 500 square meters per gram, manufactured through sol-gel assembly followed by supercritical CO2 drying or freeze-casting to preserve structural integrity. Its primary commercial purpose centers on thermal insulation, electrochemical energy storage, and environmental remediation where extreme porosity and electrical conductivity must coexist. Composite formulations lead current revenue contribution because hybrid matrices with polymers or ceramics resolve the mechanical fragility of pure graphene scaffolds, while sheet formats in flexible form factors capture the fastest growth trajectory as wearable electronics and conformable battery architectures mature. Oil absorption applications in granular form remain commercially nascent despite laboratory promise, with margin pools currently concentrating in catalysis-grade pellets where precious metal deposition yields premium pricing.
The EPA oversees American occupational exposure limits for graphene nanoparticles under evolving nanomaterial reporting rules, while REACH in Europe mandates registration of novel carbon allotropes above one-ton annual thresholds, shaping product development timelines and market access costs for importers. China's SAMR enforces GB standards for construction material fire ratings, directly qualifying or disqualifying graphene aerogel insulation for building retrofits. Stakeholders must monitor how regulatory divergence between these jurisdictions fragments certification requirements and whether harmonized ISO nanomaterial safety protocols emerge to simplify cross-border commercialization.
Market Dynamics
China's dual carbon goals and updated GB standards for building energy efficiency are tightening material specifications and redirecting procurement toward ultra-low-density insulators, compressing legacy mineral wool and fiberglass market share in high-performance construction segments.
Growth Catalysts
- Aerospace thermal management systems:Commercial aviation and defense contractors are qualifying graphene aerogel composites for engine compartment insulation and cryogenic fuel tank lining, with qualification cycles accelerating as FAA certification pathways for nanomaterial-containing components mature.
- REACH registration thresholds:European manufacturers exceeding one-ton annual production of novel carbon allotropes gain preferential access to industrial catalysis contracts, locking in long-term supply agreements with precious metal deposition specialists.
- Jiangsu province pilot lines:Government-backed nanomaterials corridors are scaling sheet production capacity for conformable battery architectures, concentrating technical talent and supercritical drying infrastructure in a single manufacturing cluster.
Market Restraints
- Supercritical CO2 drying energy intensity:The sol-gel manufacturing pathway consumes substantial electricity and specialized pressure vessel capacity, constraining margin expansion when energy input costs fluctuate.
- Precursor graphite supply concentration:High-purity flake graphite feedstock for graphene oxide synthesis concentrates in limited mining jurisdictions, exposing formulators to geopolitical supply disruptions and export licensing delays.
- Mechanical fragility of pure scaffolds:Unreinforced graphene aerogel structures fracture under compressive loads below 0.1 MPa, restricting deployment in load-bearing thermal insulation applications without polymer or ceramic hybridization.
Strategic Opportunities
- Wearable electronics form factors:Flexible graphene aerogel sheets enable conformable supercapacitor electrodes and thermal interface materials for curved display assemblies, with South Korean consumer electronics manufacturers advancing pilot integration programs.
- EPA nanomaterial reporting evolution:Anticipated clarification of occupational exposure limits for graphene nanoparticles will reduce regulatory uncertainty for American manufacturers, potentially accelerating facility investments currently held in permitting limbo.
- Oil absorption granular formats:Laboratory-demonstrated selectivity for hydrocarbon capture in marine spill response remains commercially nascent, offering first-mover positioning for producers achieving cost parity with polypropylene sorbent booms.
Industry Challenges
- Supercritical drying equipment scarcity:Qualified autoclave fabrication capacity for large-format aerogel production remains concentrated among legacy silica aerogel equipment suppliers, extending lead times for capacity expansion projects.
- Cross-jurisdictional certification fragmentation:Divergent fire rating protocols between China's SAMR GB standards, European CE marking requirements, and American ASTM testing methodologies force redundant qualification campaigns for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Aerogel Market |
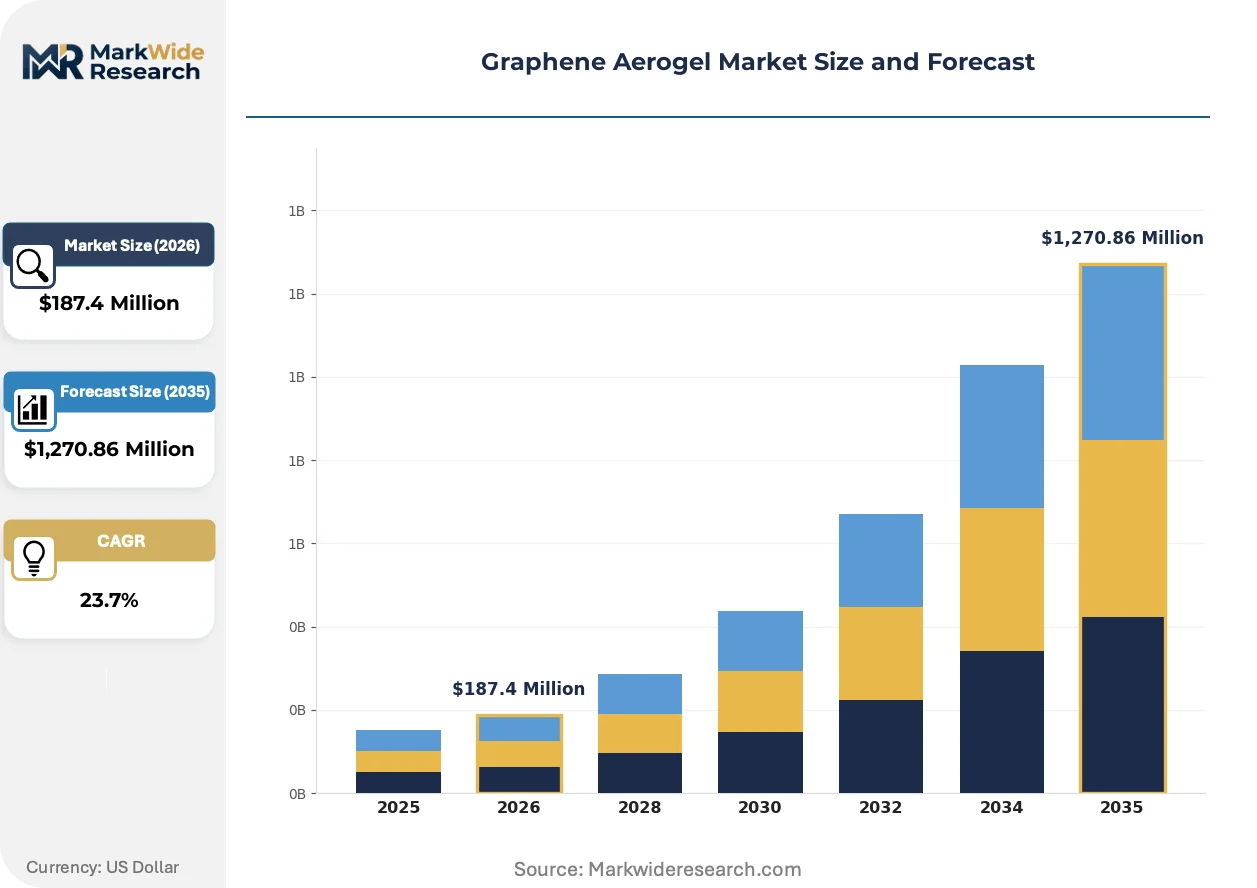
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Pellet, Sheet, Composite End Use Industry: Aerospace, Automotive, Construction, Energy Application: Insulation, Catalysis, Electronics, Oil Absorption Form: Flexible, Rigid, Granular, Coated |
| Companies Covered | Black Swan Graphene, Aspen Aerogels, NanoXplore, Graphene Composites, Cabot Corporation, Graphene Manufacturing Group, Graphenea, BASF SE, First Graphene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Aerogel Market Shifts & Advancements
Freeze-casting manufacturing protocols are gaining technical validation against supercritical drying, reshaping capital deployment strategies as producers seek to decouple capacity expansion from specialized pressure vessel investments.
Freeze-casting is supplanting traditional supercritical CO2 drying for certain sheet-format applications where directional ice crystal growth enables aligned pore structures with comparable thermal conductivity at reduced processing cost. Battery manufacturers in Germany and Japan are piloting freeze-cast electrodes for solid-state cell architectures, compressing the historical cost premium of graphene aerogel against carbon black additives. The structural consequence is a bifurcation in equipment supplier ecosystems, with freeze-casting oven vendors displacing autoclave specialists in new facility procurement decisions.
REACH registration mandates for novel carbon allotropes above one-ton annual thresholds are forcing European producers to consolidate formulation lines and document full substance characterization earlier in commercialization cycles. Industrial catalysis clients now require registration certificates as standard procurement preconditions, filtering out smaller importers lacking compliance infrastructure. The segment most affected is custom sheet production for research partnerships, where Graphenea and similar specialists absorb registration costs across premium-priced small-batch contracts.
Buyer qualification cycles for aerospace and defense applications are compressing as FAA and EASA establish precedent for nanomaterial-containing thermal protection systems through amended special conditions. Tier-one contractors are unbundling legacy qualification consulting arrangements and building in-house graphene aerogel testing capabilities to accelerate internal approval timelines. This pattern is most visible in American defense procurement, where primes compete for next-generation hypersonic vehicle insulation contracts requiring rapid material iteration.
Graphene Aerogel Market Segmentation
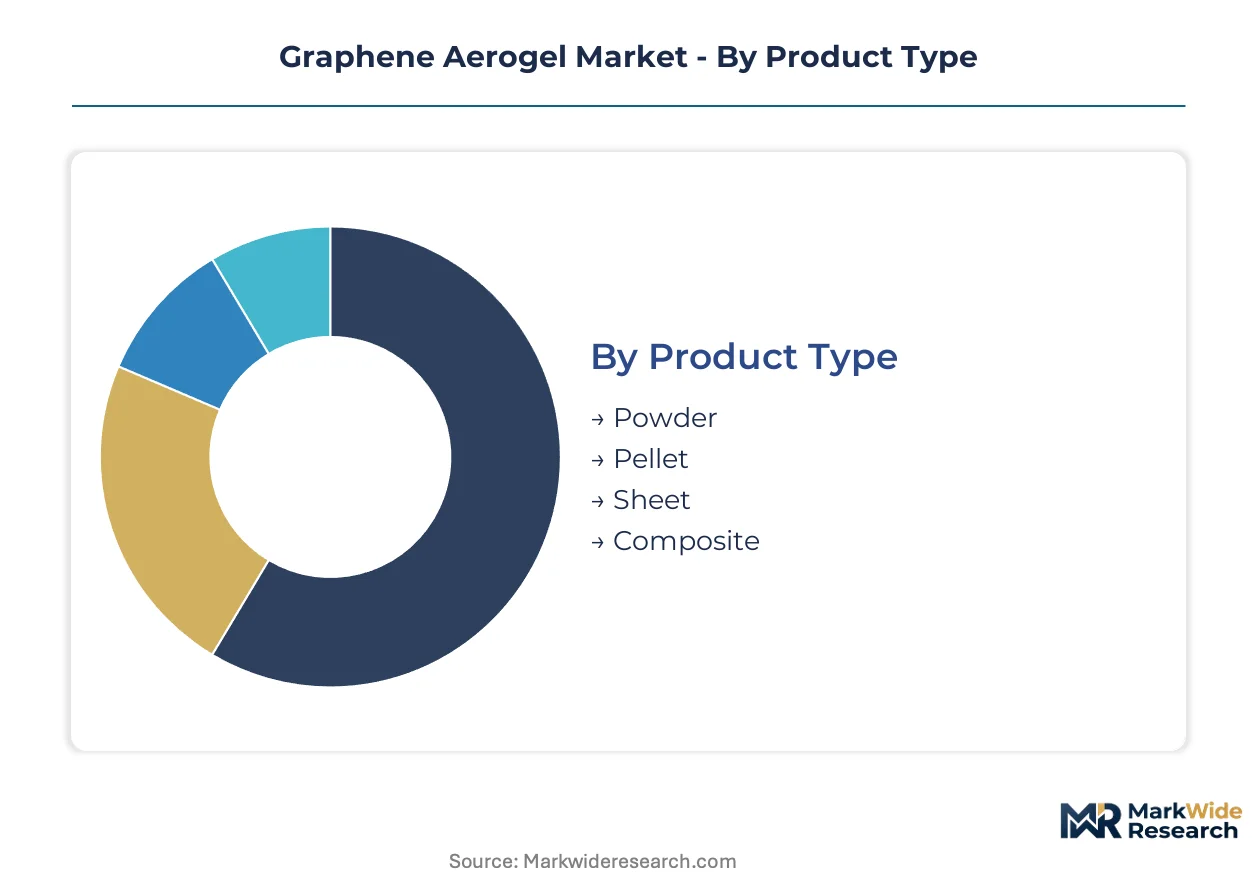
Product architecture in graphene aerogel markets fragments across physical formats, end-use specifications, and regulatory compliance tiers. Each segmentation dimension carries distinct margin structures and certification requirements that reshape competitive positioning.
Product Type:
REACH registration thresholds in Europe and EPA nanomaterial reporting rules in the United States bifurcate commercial viability across powder versus sheet formats.
- Composite:Hybrid matrices incorporating polymers or ceramics resolve the mechanical fragility of pure graphene scaffolds, enabling load-bearing thermal insulation in aerospace engine compartments. Jiangsu province pilot lines concentrate composite sheet production for conformable battery architectures.
- Sheet:Flexible form factors with directional pore structures from freeze-casting protocols capture emerging demand in wearable electronics and curved display assemblies. South Korean consumer electronics manufacturers advance pilot integration programs for conformable supercapacitor electrodes.
- Powder:Cabot Corporation leverages carbon black distribution channels for logistics-scale penetration in industrial catalysis feedstock.
- Pellet:Precious metal deposition onto catalysis-grade pellets commands premium pricing in European industrial contracts.
Established volume favors Composite; emerging adoption favors Sheet.
End Use Industry:
Cost tier differentiation separates defense-qualified insulation from construction-grade thermal barriers.
- Aerospace:FAA and EASA amended special conditions accelerate qualification cycles for nanomaterial-containing thermal protection systems in hypersonic vehicles and cryogenic fuel tank lining. Tier-one contractors build in-house testing capabilities to compress internal approval timelines.
- Energy:Solid-state battery architectures in Germany and Japan pilot freeze-cast electrodes, displacing carbon black additives in electrochemical energy storage.
- Construction:China's SAMR enforces GB standards for building material fire ratings, redirecting procurement toward ultra-low-density insulators in high-performance retrofits.
- Automotive:Thermal interface materials for electric vehicle battery packs remain commercially nascent pending OEM qualification cycles.
Margin concentration sits with Aerospace; volume scaling favors Energy.
Application:
Customer type fragmentation separates research-grade custom production from industrial commodity procurement.
- Catalysis:REACH-registered European producers consolidate formulation lines to supply precious metal deposition specialists with documented substance characterization. Industrial clients mandate registration certificates as standard procurement preconditions.
- Electronics:Conformable electrodes for flexible supercapacitors gain technical validation in South Korean and Japanese consumer electronics pilot programs.
- Insulation:Aspen Aerogels dominates high-temperature contracts through legacy supercritical drying infrastructure.
- Oil Absorption:Laboratory-demonstrated hydrocarbon selectivity for marine spill response awaits cost parity with polypropylene sorbent booms.
Revenue maturity favors Catalysis; technical momentum favors Electronics.
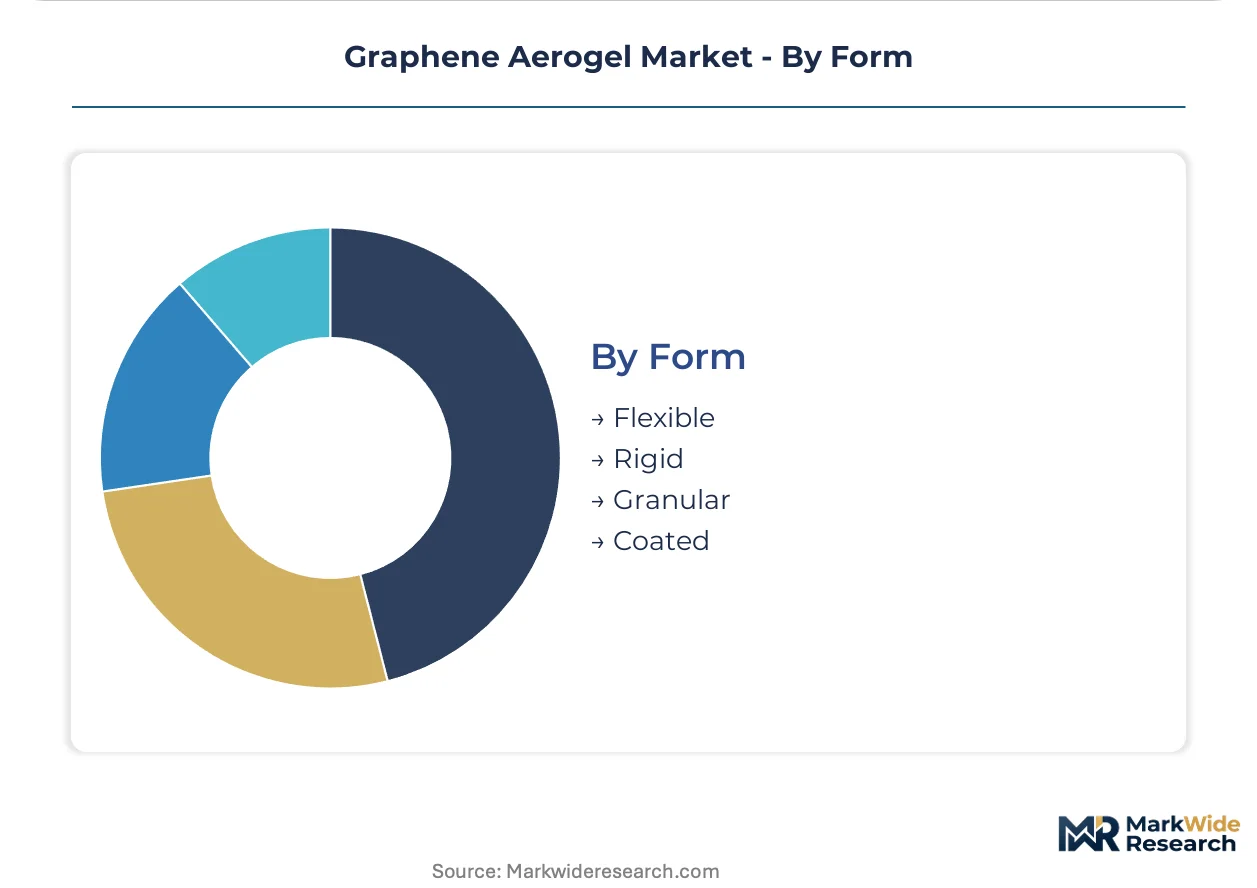
Form:
Supply concentration in supercritical drying equipment shapes manufacturing constraints across rigid versus flexible outputs.
- Flexible:Freeze-casting oven vendors displace autoclave specialists in new facility procurement decisions for sheet-format production. Directional ice crystal growth enables aligned pore structures at reduced processing cost.
- Rigid:Supercritical CO2 drying preserves structural integrity in three-dimensional porous networks for thermal management systems, though energy intensity constrains margin expansion.
- Granular:Oil absorption applications remain commercially undeveloped despite laboratory promise for hydrocarbon capture.
- Coated:Surface-modified formats for environmental remediation occupy niche research partnerships without industrial scale.
Capital deployment favors Flexible; qualification precedent favors Rigid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards for construction material fire ratings, redirecting procurement toward ultra-low-density insulators and establishing the country as the dominant geography for graphene aerogel commercialization.
China
Jiangsu province's nanomaterials corridor concentrates government-backed pilot lines scaling sheet production for conformable battery architectures. The country's dual carbon goals tighten material specifications for building retrofits. Technical talent clusters in Suzhou and Nanjing, where supercritical drying infrastructure scales for construction and energy storage applications.
United States
Aerospace thermal management systems drive qualification cycles for engine compartment insulation and cryogenic fuel tank lining. The EPA oversees evolving nanomaterial reporting rules for occupational exposure limits. Tier-one defense contractors in California and Virginia build in-house testing capabilities to accelerate hypersonic vehicle insulation contracts.
Germany
Solid-state battery manufacturers pilot freeze-cast electrodes for electrochemical energy storage, compressing cost premiums against carbon black additives. REACH mandates registration of novel carbon allotropes above one-ton annual thresholds. Industrial catalysis clients in the Ruhr region require registration certificates as standard procurement preconditions.
Japan
Battery producers advance freeze-casting protocols for solid-state cell architectures, displacing traditional supercritical drying in new facility procurement. METI oversees national energy storage material roadmaps. Manufacturing clusters in Osaka and Nagoya concentrate technical validation programs for conformable electrodes.
South Korea
Consumer electronics manufacturers advance pilot integration programs for flexible supercapacitor electrodes and thermal interface materials in curved display assemblies. The MFDS monitors nanomaterial safety protocols for wearable device applications. Seoul-based R&D centers validate sheet formats for next-generation conformable battery architectures.
Graphene Aerogel Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with legacy aerogel infrastructure holders and graphene synthesis specialists occupying distinct competitive positions. The market structure reflects bifurcation between equipment-heavy incumbents and research-anchored custom producers. Three archetypes dominate: supercritical drying infrastructure holders, carbon material distribution scale players, and research partnership specialists. Competitive moves center on freeze-casting technology licensing and backward integration into precursor graphite supply.
Among North American-integrated leaders, Aspen Aerogels exemplifies the infrastructure-holder archetype, while Cabot Corporation represents distribution-scale carbon material positioning. Graphenea anchors the European specialist tier as a research-partnership custom producer. These three occupy positions that illustrate the market's vertical segmentation without claiming exhaustive coverage of strategic approaches.
| Leading Market Players |
|---|
| Black Swan Graphene |
| Aspen Aerogels |
| NanoXplore |
| Graphene Composites |
| Cabot Corporation |
| Graphene Manufacturing Group |
| Graphenea |
| BASF SE |
| First Graphene |
| Others |
Supply & Pricing Matrix
Freeze-casting adoption is displacing supercritical CO2 drying as the dominant manufacturing pathway, simultaneously relocating production capacity toward East Asian equipment vendors and compressing processing cost premiums in sheet-format graphene aerogel. This substitution dynamic redistributes pricing power from legacy autoclave fabricators to freeze-casting oven suppliers while enabling South Korean and Japanese battery manufacturers to negotiate lower electrode input costs.
Pricing Analysis
Price spreads between European REACH-registered pellets and unregistered Asian powder feedstock exceed threefold, with registration certificates and precious metal deposition compatibility commanding premium tiers. Pricing stratifies across aerospace-qualified composites, industrial catalysis grades, and construction-standard insulation, with customization level and certification grade as primary differentiation drivers. Cost compression in construction-grade sheets is intensifying because Jiangsu province pilot lines achieve economies of scale in government-backed nanomaterials corridors. Energy storage buyers exhibit highest price sensitivity due to carbon black substitution options, while defense contractors absorb premiums for FAA-qualification documentation.
Supply Chain Analysis
Strategic stockpiling of high-purity flake graphite concentrates in China and Mozambique reflects precursor supply anxiety among graphene oxide formulators, contrasting with just-in-time supercritical drying equipment procurement that extends lead times for capacity expansion. The supply chain draws from Chinese mining jurisdictions for feedstock, German and Japanese freeze-casting equipment vendors for processing infrastructure, and South Korean consumer electronics manufacturers for sheet-format offtake. Single-source vulnerability in qualified autoclave fabrication capacity concentrates risk among legacy silica aerogel equipment suppliers. Distribution runs through carbon black distribution channels for powder formats and direct technical sales for custom sheet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in REACH registration consulting and FAA qualification documentation are expanding faster than hardware margins, as regulatory compliance becomes a recurring-revenue layer separating viable producers from commodity competitors.
For Market Incumbents: Fortify position by backward integration into precursor graphite supply and captive supercritical drying capacity in Jiangsu province, defending against freeze-casting entrants eroding technical differentiation. Lock in long-term offtake agreements with European precious metal deposition specialists before REACH registration thresholds consolidate supplier tiers. Prioritize certification investment in FAA amended special conditions for hypersonic vehicle insulation contracts. For New Entrants and Emerging Players: Anchor in oil absorption granular formats for marine spill response, the most penetrable application awaiting cost parity with polypropylene sorbent booms. Target South Korean wearable electronics manufacturers with freeze-cast flexible sheet samples, leveraging directional pore alignment as a technical wedge. Pursue technical partnership go-to-market models with consumer electronics pilot integration programs rather than direct industrial commodity sales. For Investors and Strategic Acquirers: Capital is best deployed toward research-partnership specialists with documented REACH registration infrastructure and established European industrial catalysis relationships, positioning for five-to-ten year consolidation as compliance costs filter smaller importers. Monitor freeze-casting equipment vendor acquisition activity as the inflection signal for manufacturing cost structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Casting Technology Licensing | Battery manufacturers in Germany and Japan displace carbon black additives through lower-cost electrode production. |
| REACH Registration Consolidation | European producers absorb compliance costs across premium small-batch contracts, filtering smaller importers from catalysis supply. |
| Backward Integration into Graphite Supply | Formulators in China secure high-purity flake feedstock against export licensing delays and geopolitical disruption. |
| FAA Qualification Pathway Investment | Tier-one defense contractors accelerate hypersonic vehicle insulation contracts through in-house nanomaterial testing capabilities. |
| Jiangsu Province Capacity Expansion | Government-backed pilot lines scale sheet production for conformable battery architectures and construction retrofits. |
Research Methodology
A standing panel of supercritical drying equipment engineers, graphene synthesis R&D directors, European REACH compliance consultants, and South Korean battery manufacturer procurement officers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings of carbon material distributors, ECHA registration databases, SAMR GB standard updates, and FAA special conditions amendments. Bottom-up capacity assessments across Jiangsu province pilot lines triangulated against top-down market sizing from end-use industry absorption rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including physical format, end-use industry, regulatory compliance tier, and manufacturing process technology. CAGRs were derived from slope analysis of adoption curves in aerospace qualification cycles and construction retrofit procurement patterns. Industry-specific forecast inputs incorporated supercritical drying energy cost trajectories and freeze-casting equipment vendor order backlogs.
Material uncertainties — regulatory divergence between EPA nanomaterial reporting evolution, REACH registration threshold enforcement, and SAMR fire rating updates — sit outside the modeled envelope. Forecasts reflect assumptions about FAA and EASA harmonization timelines for nanomaterial-containing components. Revision becomes warranted when freeze-casting cost parity thresholds cross supercritical drying in high-temperature insulation applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanocellulose Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Mesoporous Carbons Market