
 Nano Fillers Market | 2026-2036
Nano Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Fillers Market Foresight
Performance-grade nano filler specifications is collapsing the gap between commodity mineral additives and engineered nanomaterials in industrial formulations. DuPont de Nemours, Inc. leverages its polymer science heritage to anchor high-barrier packaging applications. Evonik Industries AG specializes in fumed silica architectures that dominate optical coatings segments. Cabot Corporation controls carbon black nano filler supply chains for tire reinforcement grades.
Nano fillers are discrete particulate materials with at least one dimension below 100 nanometers, typically surface-treated with silane coupling agents or dispersants to achieve uniform distribution in polymer matrices; they function primarily as mechanical reinforcements, barrier enhancers, or conductivity modifiers in finished goods. Nanoparticles command the largest volume position across product types due to mature titanium dioxide and zinc oxide supply infrastructure. Carbon nanotubes represent the fastest-expanding category, driven by conductivity demands in electronics and aerospace wire coatings. Graphene holds concentrated margin pools in thermal management applications for power electronics, though production scale remains constrained.
REACH registration requirements in Europe mandate exhaustive toxicological dossiers for nano-scale substances, elevating compliance costs for importers and favoring established producers with dedicated regulatory affairs capacity. The EPA in the United States enforces reporting thresholds under the Toxic Substances Control Act for new nano materials, creating friction for novel entrants. China's GB standards for nano material labeling and safety testing, administered by SAMR, shape export readiness for Asia-origin suppliers. Stakeholders must monitor evolving classification thresholds that could resegment product categories across jurisdictions.
Market Dynamics
REACH registration dossiers for nano-scale substances are elevating compliance costs for importers while favoring established producers with dedicated regulatory affairs capacity. This structural friction is compressing the supplier base and accelerating consolidation among European nano filler manufacturers.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforces CO2 reduction targets that compel OEMs to replace metal components with polymer-nano composites in structural applications.
- REACH Article 57 authorization:The regulation's nano-specific annex creates preferential market access for pre-registered suppliers with existing toxicological portfolios.
- Fumed silica architectures:Optical coatings manufacturers are specifying surface-treated nano fillers for refractive index control in display laminates.
Market Restraints
- Titanium dioxide feedstock volatility:Rutile ore supply concentrates in Australian and South African mining districts, exposing nanoparticle producers to freight and energy cost swings.
- Graphene production scale limitations:Chemical vapor deposition yields remain below industrial thresholds, constraining thermal management application rollouts.
- EPA TSCA Section 5 notification:New nano material introductions trigger 90-day review windows that delay commercialization timelines for US entrants.
Strategic Opportunities
- Eastern China manufacturing corridor:SAMR's GB standards alignment with export protocols creates regulatory arbitrage for production facilities in Jiangsu and Zhejiang provinces.
- Wire coating conductivity specifications:Aerospace cable harnesses are adopting carbon nanotube loadings to meet flame retardancy without metal shielding weight penalties.
- Battery separator ceramic coatings:EV cell manufacturers are qualifying alumina nano fillers for dendrite suppression in high-energy-density formats.
Industry Challenges
- Dispersion engineering talent scarcity:Silane coupling agent formulation expertise concentrates among aging technical specialists in German and Japanese chemical clusters.
- ISO/TS 80004 certification timelines:Nano material characterization protocols require 18-24 month validation cycles that delay customer qualification.
- Legacy compounding equipment retrofit costs:Twin-screw extruder modifications for nano filler feeding demand capital outlays that mid-tier processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Fillers Market |
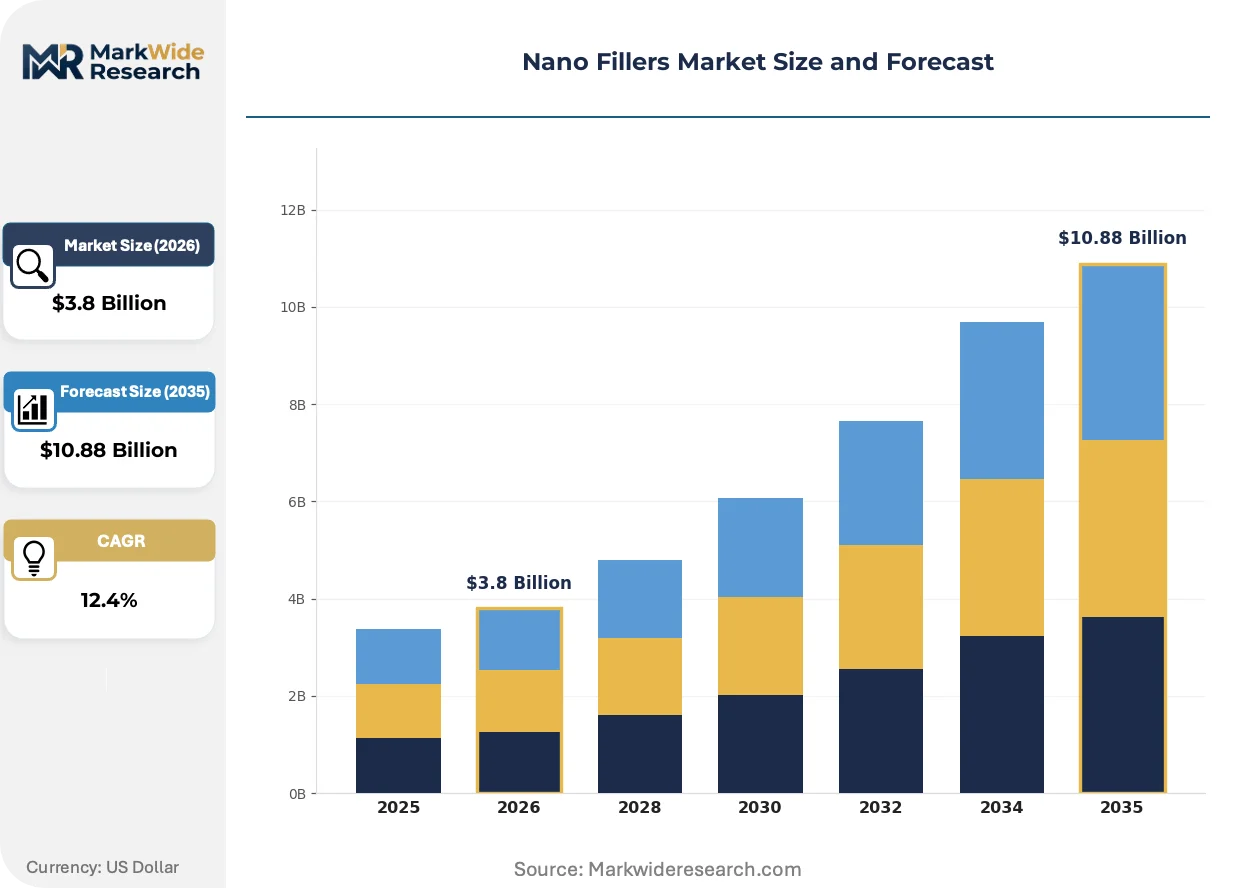
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanotubes, Nanoclays, Nanoparticles, Graphene Application: Plastics, Coatings, Composites, Textiles End User: Aerospace, Automotive, Electronics, Construction Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | DuPont de Nemours, Inc., 3M Company, Cabot Corporation, Evonik Industries AG, Henkel AG & Co. KGaA, J.M. Huber Corporation, Arkema, Nanocyl SA, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Fillers Market Shifts & Advancements
Surface functionalization chemistry is advancing faster than bulk synthesis methods, creating performance gaps between commodity mineral additives and engineered nano materials. This divergence is compressing specification windows and forcing reformulation cycles across polymer compounding.
Hybrid organic-inorganic nano filler architectures are miniaturizing reinforcement domains below the optical scattering threshold. Tire manufacturers are adopting these materials for sidewall compounds requiring both flex fatigue resistance and surface aesthetics. The technology is miniaturizing the trade-off between mechanical performance and visual quality that previously forced compound segregation.
ECHA's 2022 revised nanoform guidance expands registration obligations for surface-modified variants previously exempt under earlier REACH interpretations. Compounders must now document batch-to-batch morphology consistency. Tire and packaging segments in Germany, France, and the Netherlands are absorbing the highest compliance cost burdens.
Specification-driven procurement is consolidating buyer power among tier-one automotive and electronics OEMs. Direct contracting with nano filler producers is displacing distributor-mediated purchasing in high-volume applications. This pattern is most pronounced in Bavaria's automotive supplier cluster and Shenzhen's electronics manufacturing ecosystem.
Nano Fillers Market Segmentation
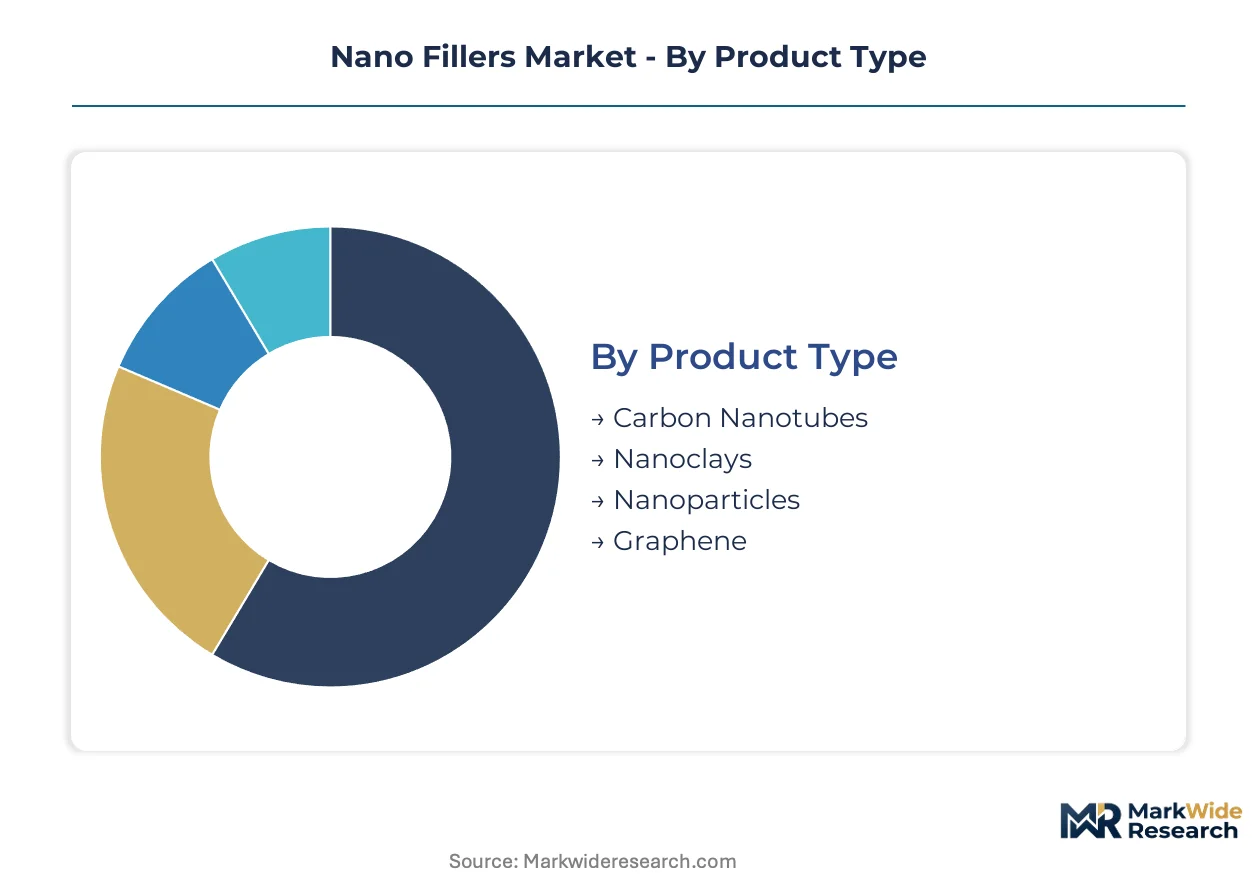
Nano filler procurement channels diverge sharply by technical complexity and volume scale. Specification-grade materials flow through direct technical partnerships, while commodity nanoparticles move via distributor networks serving mid-tier compounders.
Product Type:
Channel mix varies by synthesis complexity: carbon nanotubes and graphene move predominantly through direct sales with embedded technical service, while nanoparticles and nanoclays distribute through chemical distributors serving regional compounding houses.
- Carbon Nanotubes:Multi-walled and single-walled architectures deliver electrical conductivity and mechanical reinforcement at loadings below 5 weight percent. Aerospace wire harness manufacturers in Germany specify these for flame-retardant cable coatings that eliminate metal shielding weight. ECHA's nanoform guidance now mandates batch morphology documentation for surface-modified variants.
- Nanoparticles:Titanium dioxide and zinc oxide grades dominate volume flows through established pigment distribution channels. Jiangsu province coating manufacturers absorb the largest share, driven by architectural paint reformulations meeting GB standards for VOC reduction.
- Nanoclays:Layered silicate structures intercalate into polymer galleries for barrier enhancement. Tier-two packaging compounders source these through regional distributors lacking in-house dispersion expertise.
- Graphene:Thermal conductivity specifications in power electronics outstrip chemical vapor deposition yields. Direct contracting prevails despite supply constraints.
By volume, nanoparticles lead. By growth pace, carbon nanotubes are climbing the fastest.
Application:
Cost tier stratification separates specification-driven segments from price-sensitive commodity applications, with coatings and composites commanding premium positioning over plastics and textiles.
- Plastics:Automotive structural components in Bavaria specify nano-reinforced polyamides for metal replacement under KBA CO2 mandates. Compounders face 18-24 month ISO/TS 80004 certification cycles that delay customer qualification.
- Coatings:Optical display laminates demand surface-treated fumed silica for precise refractive index control. Shenzhen electronics manufacturers drive qualification timelines for high-barrier packaging grades.
- Composites:Wind blade and pressure vessel manufacturers specify nano-enhanced epoxies for fatigue resistance. Distribution runs through specialized advanced materials distributors with prepreg expertise.
- Textiles:UV-blocking and antimicrobial functionalities in sportswear absorb commodity zinc oxide flows. Price sensitivity limits channel margin capture.
Coatings generate the highest margin per kilogram. Plastics move the largest absolute tonnage through extrusion compounding channels.
End User:
Customer type determines technical engagement depth: aerospace and automotive OEMs embed nano filler suppliers in co-development programs, while construction procurement remains transactional through distributor intermediaries.
- Aerospace:Cable harness and interior panel specifications mandate carbon nanotube loadings for flame retardancy without weight penalties. FAA certification protocols extend material qualification timelines beyond commercial aviation norms.
- Automotive:Germany's KBA enforcement of fleet CO2 targets accelerates polymer-nano composite adoption in structural applications. Direct supplier-OEM contracting displaces distributor relationships in high-volume programs.
- Electronics:Thermal management and barrier packaging requirements concentrate demand in Shenzhen and Dongguan manufacturing clusters. SAMR's GB standards alignment creates regulatory arbitrage for qualified suppliers.
- Construction:Cementitious nano additives for strength and durability move through construction chemical distributors with limited technical support capacity.
Automotive absorbs the greatest volume. Aerospace exhibits the steepest specification premium.
Distribution Channel:
Supply concentration in synthesis expertise shapes channel power: direct sales dominate where dispersion engineering and surface functionalization determine performance, while distributors capture commodity flows.
- Direct Sales:Technical specialists co-develop silane coupling agent formulations with tier-one OEMs. German and Japanese chemical clusters concentrate this expertise among aging practitioners.
- Distributors:Regional chemical distributors serve mid-tier compounders lacking in-house nano material characterization capabilities. Inventory carrying costs limit SKU breadth.
- Retail:Limited to small-volume R&D sampling and academic procurement. Channel friction from hazardous material shipping restrictions.
- Online:Emerging for standardized nanoparticle grades with established safety documentation. SAMR's labeling requirements create compliance complexity for cross-border transactions.
Direct sales capture the highest value per transaction. Distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese nano filler exports flow predominantly into Germany's automotive supply chain and the United States electronics manufacturing base. These trade corridors concentrate value capture in coastal synthesis clusters while downstream formulation occurs near end-use assembly.
China
Jiangsu and Zhejiang provinces host the largest nanoparticle production infrastructure for titanium dioxide and zinc oxide grades. SAMR's GB standards for nano material labeling create regulatory alignment with export protocols. Dongguan electronics manufacturers drive qualification timelines for thermal management specifications in power semiconductor packaging.
Germany
Bavaria's automotive supplier cluster specifies nano-reinforced polyamides for structural metal replacement under KBA-enforced CO2 fleet targets. REACH Article 57 authorization protocols favor pre-registered suppliers with existing toxicological dossiers. Frankfurt-Rhine-Main chemical distributors are consolidating inventory positions to serve mid-tier compounders lacking in-house characterization.
United States
Aerospace wire harness manufacturers specify carbon nanotube loadings for flame-retardant cable coatings eliminating metal shielding weight. EPA TSCA Section 5 notification triggers 90-day review windows that delay commercialization for novel nano material introductions. Southeast compounding facilities are absorbing distributor-mediated flows for commodity nanoparticle grades.
Japan
Kansai region optical coating manufacturers specify surface-treated fumed silica for precise refractive index control in display laminates. METI industrial standards shape qualification protocols for nano material imports. Nagoya automotive suppliers are integrating nano clay barriers into fuel system components for permeation resistance.
South Korea
Seoul Capital Area battery manufacturers qualify alumina nano fillers for ceramic separator coatings suppressing dendrite formation in high-energy-density cells. MFDS pharmaceutical-grade nano material guidelines extend to adjacent industrial applications. Busan-Ulsan chemical complexes are expanding fumed silica capacity for regional electronics packaging demand.
Nano Fillers Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capacity and synthesis scale. The supplier base compresses around REACH dossier completion and ISO/TS 80004 certification attainment. Three archetypes dominate: diversified chemical conglomerates with polymer science heritage, fumed silica specialists with optical coatings expertise, and carbon black producers with tire reinforcement lock-in. Consolidation accelerates through M&A among European registrants and capacity expansion in eastern Chinese manufacturing corridors.
Within the diversified chemical tier, DuPont de Nemours, Inc. and Evonik Industries AG exemplify archetypes anchored in polymer science and fumed silica architectures respectively. Cabot Corporation occupies a position representing carbon black nano filler supply chain control for tire applications. These three entities sit within distinct competitive vectors: packaging barrier enhancement, optical coating precision, and rubber reinforcement durability.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| 3M Company |
| Cabot Corporation |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| J.M. Huber Corporation |
| Arkema |
| Nanocyl SA |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
Polymer-nano composite substitution for metal automotive components is redrawing supply geography toward Jiangsu synthesis clusters while compressing margin structures for legacy mineral additive suppliers. This displacement dynamic concentrates pricing power among REACH-registered producers with completed toxicological dossiers.
Pricing Analysis
Next-generation carbon nanotube specifications command substantial premiums over commodity nanoparticle grades, while legacy titanium dioxide formulations face margin erosion. Three-tier pricing structure across specification-grade, technical-grade, and commodity-grade levels separates aerospace-qualified carbon nanotubes from automotive technical grades and construction-sector mineral fillers. Pricing pressure stems from rutile ore freight volatility and energy cost swings in Australian mining districts. Construction procurement teams exhibit highest price sensitivity due to undifferentiated performance requirements, while aerospace OEMs accept premium positioning for FAA-certified material streams.
Supply Chain Analysis
Inventory cycles for surface-treated nano fillers stretch 12-16 weeks due to batch morphology validation requirements under ECHA's nanoform guidance. Supply concentrates in China, Germany, and the United States, with Jiangsu province hosting titanium dioxide infrastructure, Bavaria anchoring automotive compounding, and Southeast US facilities serving aerospace wire harness demand. Feedstock dependencies center on rutile ore, silane coupling agents, and chemical vapor deposition precursors. Single-source vulnerability runs through Australian-South African mining corridors for titanium feedstock. Distribution runs through direct technical partnerships for specification grades and regional chemical distributors for commodity flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nano fillers market represents a high-growth disruption anchored by automotive lightweighting mandates and REACH regulatory escalation. ECHA's expanded nanoform registration obligations create structural advantages for incumbent dossier-holders.
For Market Incumbents: Shield market position by accelerating backward integration into silane coupling agent production and securing captive rutile ore offtake from Australian mining districts. Prioritize ISO/TS 80004 certification completion ahead of competitor qualification cycles to lock in tier-one automotive programs. For New Entrants and Emerging Players: Technical service gaps in dispersion engineering for mid-tier packaging compounders present immediate white-space opportunity. Target Jiangsu and Zhejiang province manufacturing corridors where SAMR's GB standards alignment reduces export friction. Pursue co-development partnerships with Shenzhen electronics manufacturers for thermal management qualification programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty chemical platforms that completed REACH registration ahead of 2022 nanoform guidance expansion. Five-to-ten year viability hinges on surface functionalization chemistry capabilities and regulatory affairs capacity depth. Monitor ECHA authorization list updates as signal for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Coupling Agents | Captive supply of surface treatment chemistry locks in dispersion performance consistency for tier-one automotive programs. |
| REACH Nanoform Dossier Completion | Pre-registration under ECHA's expanded guidance secures preferential market access against delayed entrants. |
| Jiangsu Province Capacity Expansion | Proximity to Dongguan electronics clusters reduces qualification timeline friction for thermal management grades. |
| Direct OEM Technical Partnership | Co-development embedding with Bavarian automotive suppliers displaces distributor-mediated procurement in high-volume applications. |
| ISO/TS 80004 Certification Investment | Accelerated validation cycles compress 18-24 month customer qualification timelines versus competitor positioning. |
Research Methodology
Desk research of customs trade databases, SEC chemical sector filings, and ECHA registration databases preceded structured interviews with nano filler plant managers, automotive Tier 1 procurement leads, and optical coatings R&D directors. Primary fieldwork with distribution channel partners and technical compounding specialists validated secondary demand indicators. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity assumptions across the analysis window.
Variance decomposition across product type, application grade, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level elasticity modeling and input-output coefficient analysis. Forecast inputs incorporated automotive production platform schedules, REACH authorization timeline projections, and battery separator ceramic coating adoption curves.
Underlying assumptions cover sustained KBA CO2 enforcement, stable rutile ore supply corridors, and ECHA nanoform guidance implementation, with deviation risk concentrated in graphene chemical vapor deposition yield breakthroughs and EPA TSCA Section 5 notification delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanotubes Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Silver Nanoparticles Market