
 Aramid Fiber Reinforcement Materials Market | 2026-2036
Aramid Fiber Reinforcement Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Fiber Reinforcement Materials Market Outlook
Specialty chemical distribution channels serving European and East Asian industrial buyers is rewriting procurement patterns for high-performance reinforcement fibers. DuPont de Nemours Inc. leverages its Wilmington, Delaware manufacturing base and long-standing para-aramid patents to sustain premium positioning across North American defense and aerospace contracts. Teijin Limited anchors supply continuity through integrated spinning and weaving operations in Matsuyama, Japan. Hyosung Corporation competes aggressively on filament cost from its Jeonju facilities, targeting automotive tier suppliers in South Korea and Vietnam.
Aramid fiber reinforcement materials consist of aromatic polyamide filaments engineered with high tensile strength-to-weight ratios, thermal stability exceeding 400°C decomposition thresholds, and inherent flame resistance without melt-drip behavior. These properties position the materials as structural load bearers in polymer matrix composites, ballistic laminates, and electrical insulation systems where metal substitution or personnel protection is required. Para-aramid variants command the dominant value share due to their superior modulus and penetration resistance in aerospace and defense applications, while meta-aramid grades occupy stable demand in thermal insulation and fire-protective textiles where elongation and comfort properties matter more than peak strength. Blended aramid formulations represent the fastest-growing product category as compounders optimize cost-performance ratios for automotive underbody shields and industrial conveyor belting.
The U.S. Department of Commerce export controls on advanced fibers, EU REACH substance restrictions on precursor chemicals, and China's GB standards for fire safety in public transit equipment collectively shape formulation choices, testing protocols, and cross-border shipment eligibility for aramid reinforcement suppliers. Japan's METI energy-efficiency guidelines for transportation equipment indirectly accelerate aramid composite substitution for heavier metallic structures in rail and automotive platforms. Stakeholders must monitor evolving national security classifications for ballistic-grade fibers and preemptively qualify alternative precursor supply routes before regulatory friction disrupts existing procurement arrangements.
Market Dynamics
Aramid fiber reinforcement markets are restructuring around EU REACH chemical traceability mandates and the U.S. Department of Commerce export controls on ballistic-grade filaments, forcing compounders to dual-source precursor supply chains and requalify laminate formulations.
Growth Catalysts
- EU Green Deal decarbonization targets:Germany's automotive OEMs are substituting aramid composites for steel battery enclosures in electric vehicles to meet fleet weight reduction mandates.
- Ballistic protection modernization:Defense procurement offices in the United States are accelerating para-aramid laminate orders for next-generation personnel armor and vehicle shielding.
- High-speed rail expansion:Japan's METI energy-efficiency guidelines are driving aramid substitution into railcar structural panels across the Tokaido and Sanyo Shinkansen corridors.
Market Restraints
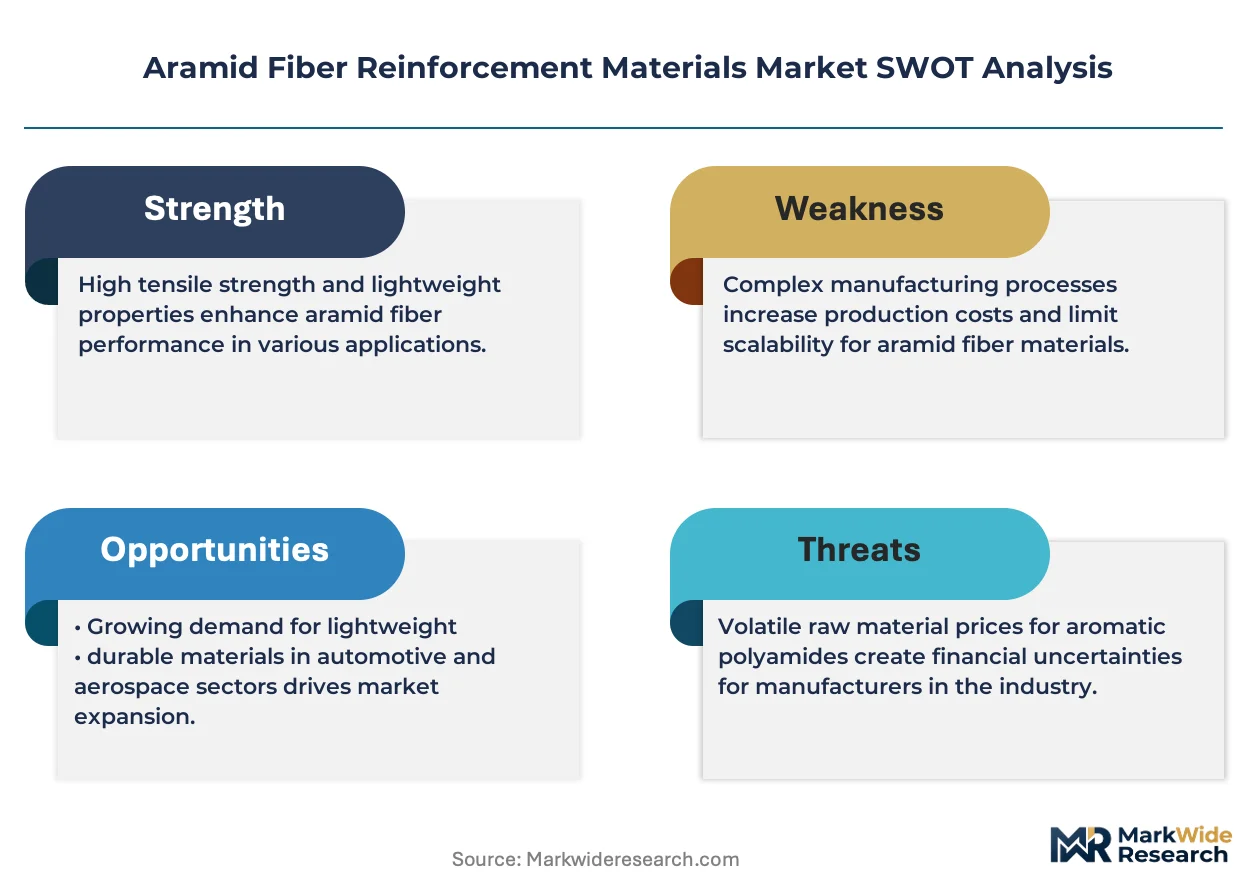
- Precursor chemical concentration:Meta-phenylenediamine and terephthaloyl chloride supply clusters in China create vulnerability to GB standards enforcement and export license delays.
- Carbon fiber substitution in aerospace:Toray and Hexcel carbon fiber prepregs are capturing wing spar and fuselage applications where modulus-to-weight ratios outweigh aramid's impact resistance.
- REACH substance restriction complexity:ECHA's evolving candidate list for Substances of Very High Concern forces reformulation of sizing agents and surface treatments used in aramid weaving.
Strategic Opportunities
- Vietnam automotive manufacturing:Hyundai and Toyota assembly plants near Haiphong are qualifying para-aramid underbody shields for Southeast Asian electric vehicle exports.
- Recyclable thermoplastic composites:Polyetheretherketone and polyphenylene sulfide matrix systems are enabling closed-loop recycling of aramid-reinforced parts for industrial conveyor belting.
- Fire safety retrofit mandates:China's GB 8624 standard for public transit interior materials is creating replacement demand for meta-aramid insulation in metro fleet refurbishments.
Industry Challenges
- Filament spinning technician scarcity:The specialized wet-spinning process for para-aramid requires operators with polymer chemistry and high-temperature handling expertise that industrial training programs are failing to replenish.
- Ballistic certification timeline compression:NIJ Level III and IV armor plate testing protocols now demand 18-24 month qualification cycles that delay contract awards and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Fiber Reinforcement Materials Market |
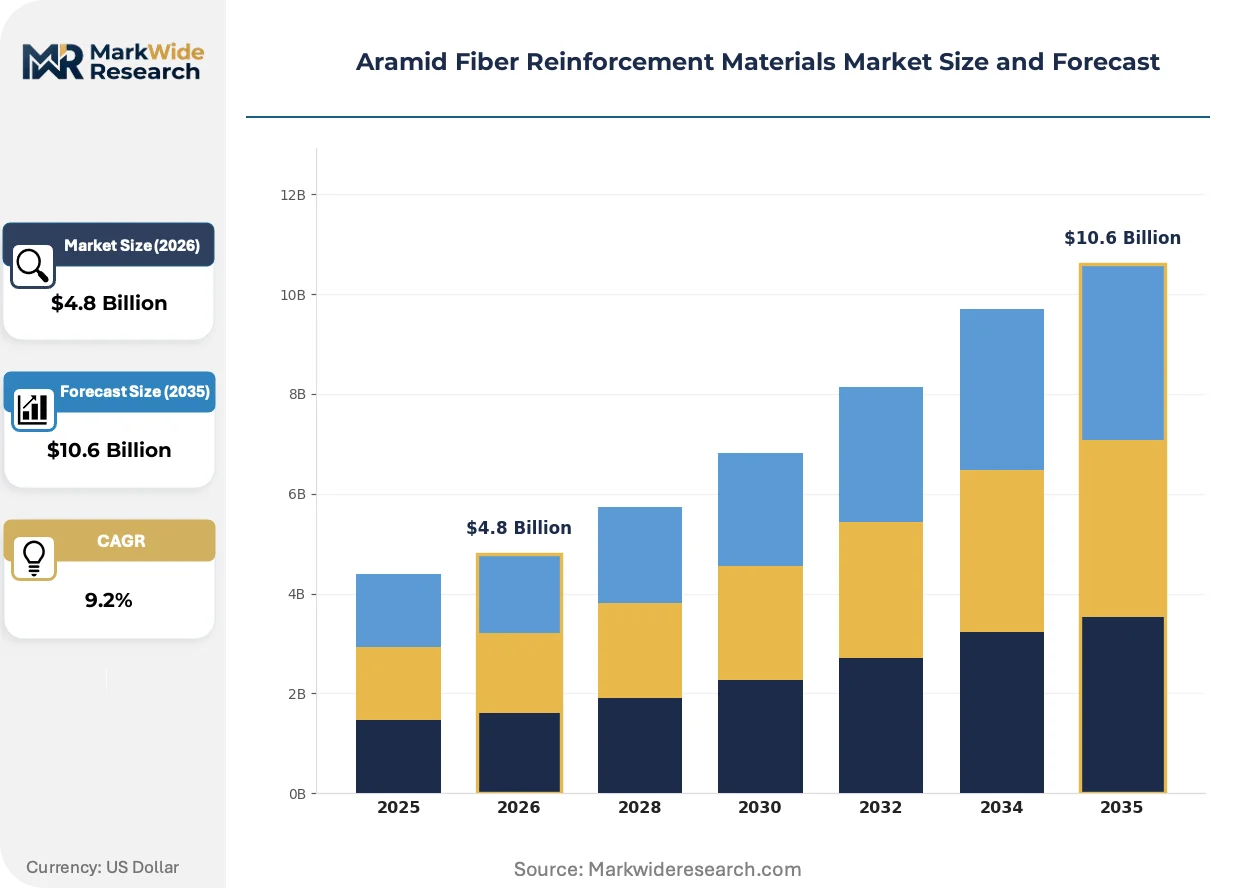
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Para-Aramid, Meta-Aramid, Blended Aramid, Others End User: Aerospace, Automotive, Marine, Electrical Form: Continuous Fiber, Roving, Fabric, Sheet Application: Composite Materials, Protective Equipment, Insulation, Ballistic Protection |
| Companies Covered | Kolon Industries, Inc., Toray Industries, Inc., DuPont de Nemours Inc., Honeywell International Inc., Huvis Corporation, Teijin Limited, Hyosung Corporation, SRO Aramid (Jiangsu) Co., Ltd., Yantai Tayho Advanced Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Fiber Reinforcement Materials Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to reshape how aramid reinforcement is formulated, qualified, and deployed across defense, transportation, and industrial end-uses.
Hybrid aramid-glass fiber fabrics are hybridizing performance characteristics for automotive underbody protection panels. Tier-one suppliers in Germany and South Korea are qualifying these interwoven constructions to meet OEM cost targets without sacrificing penetration resistance. The approach is compressing pure para-aramid volume in mid-tier vehicle platforms while preserving specification-grade positions in premium electric SUVs.
REACH substance restrictions on N-methyl-2-pyrrolidone solvent systems are forcing European fiber producers to migrate spinning operations to ionic liquid or aqueous alternatives. ECHA's 2023 update to the authorization list triggered capital commitments for solvent recovery infrastructure at Matsuyama and Wilhelmshaven facilities. Meta-aramid grades for thermal insulation are experiencing the most acute reformulation pressure due to their higher solvent dependency during polymerization.
Direct mill relationships are displacing traditional chemical distribution channels for high-modulus reinforcement buyers. Aerospace laminators in Toulouse and Wichita now contract filament supply through multi-year offtake agreements rather than spot procurement through regional distributors. The shift is most pronounced in North American defense contracts where DFARS compliance requirements mandate documented chain-of-custody from spinner to prepreg slitter.
Aramid Fiber Reinforcement Materials Market Segmentation
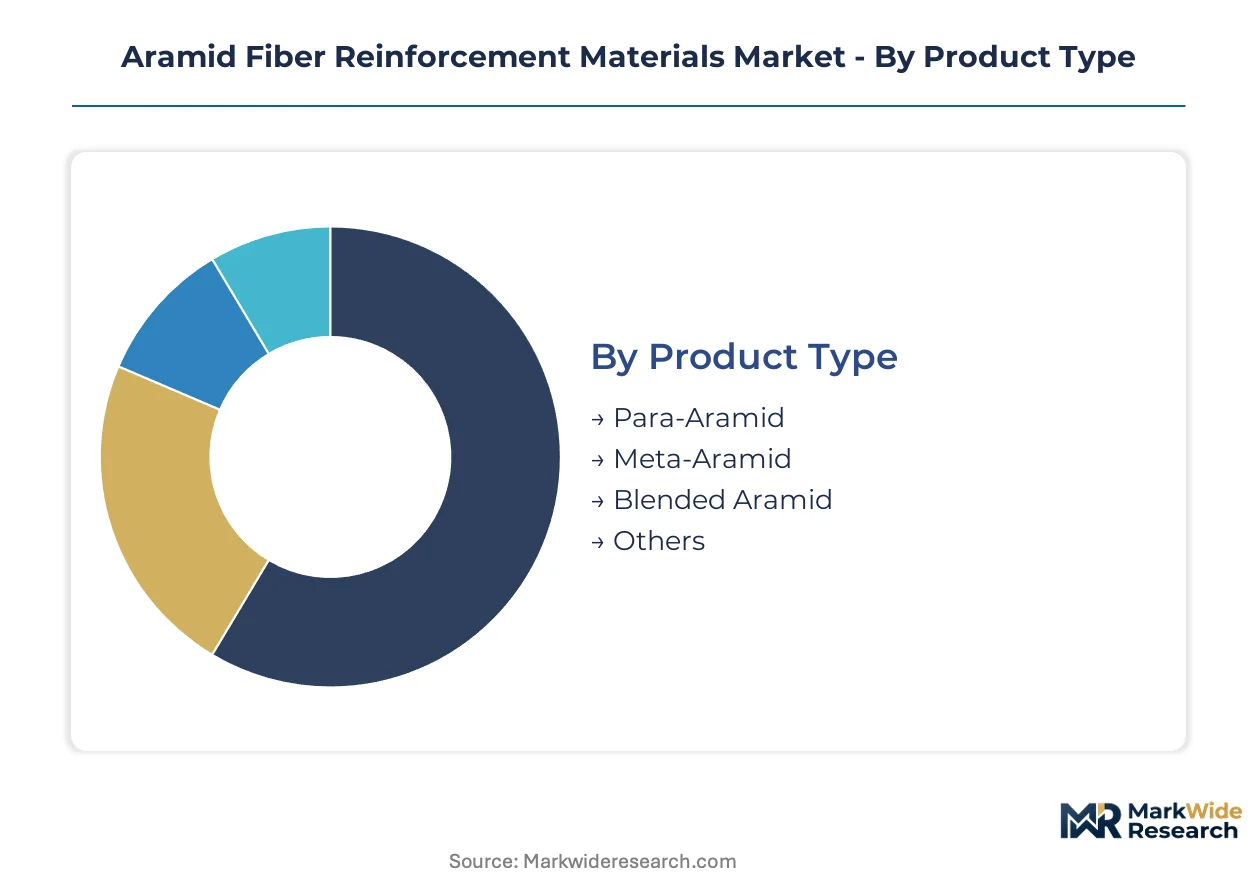
Aramid fiber reinforcement materials fragment across four structural dimensions that determine procurement patterns, formulation requirements, and margin profiles. Each segmentation axis carries distinct technical specifications, certification burdens, and supply chain configurations that shape vendor selection and compounder relationships.
Product Type:
After-sales service intensity varies sharply across aramid chemistries, with para-aramid demanding ballistic certification support and meta-aramid requiring thermal performance auditing.
- Para-Aramid:High-modulus filaments spun from poly-p-phenylene terephthalamide deliver tensile strength exceeding 2.7 GPa with decomposition thresholds above 500°C. Demand concentrates in United States defense contracts for NIJ Level III and IV armor plates, where DuPont maintains supply continuity through its Wilmington spinning operations. REACH substance restrictions on precursor chemicals are forcing European compounders to requalify laminate formulations.
- Meta-Aramid:Poly-m-phenylenediamine isophthalamide structures provide superior elongation and thermal stability without the modulus peak of para grades. Germany's automotive OEMs are integrating meta-aramid insulation into electric vehicle battery enclosures to meet EU Green Deal weight reduction mandates.
- Blended Aramid:Hybrid formulations combining para and meta chemistries optimize cost-performance ratios for industrial conveyor belting and automotive underbody shields.
- Others:Copolymer aramids and modified aromatic polyamides serve niche electrical insulation applications requiring specific dielectric properties.
By volume, Para-Aramid leads. By growth pace, Blended Aramid is ahead.
End User:
Cost tier differentiation separates specification-grade aerospace laminators from price-sensitive industrial compounders.
- Aerospace:Airframe manufacturers in Toulouse and Wichita specify high-modulus continuous fiber for primary structural components where FAA certification demands documented chain-of-custody. Carbon fiber substitution pressure from Toray and Hexcel prepregs is compressing aramid share in wing spar applications.
- Automotive:Tier-one suppliers in Germany and South Korea are qualifying para-aramid underbody shields for electric vehicle platforms. Hyundai and Toyota assembly plants near Haiphong are integrating these shields into Southeast Asian export models.
- Marine:Hull reinforcement and ballistic protection for naval vessels drive specification-grade fabric demand.
- Electrical:Transformer insulation and motor slot liners consume meta-aramid sheet and paper forms.
Aerospace commands premium pricing. Automotive is expanding most quickly.
Form:
Customer type segmentation separates direct mill relationships from distributor-dependent procurement.
- Continuous Fiber:Unidirectional tow for prepreg slitting and automated fiber placement serves aerospace laminators with multi-year offtake agreements.
- Roving:Assembled strands for pultrusion and filament winding target industrial composite manufacturers.
- Fabric:Woven constructions from plain to satin weaves provide drapability for complex mold geometries in ballistic and marine applications.
- Sheet:Pre-consolidated laminates and prepregs accelerate processing for electrical insulation and automotive panels.
Fabric leads in SKU count. Sheet is gaining share fastest.
Application:
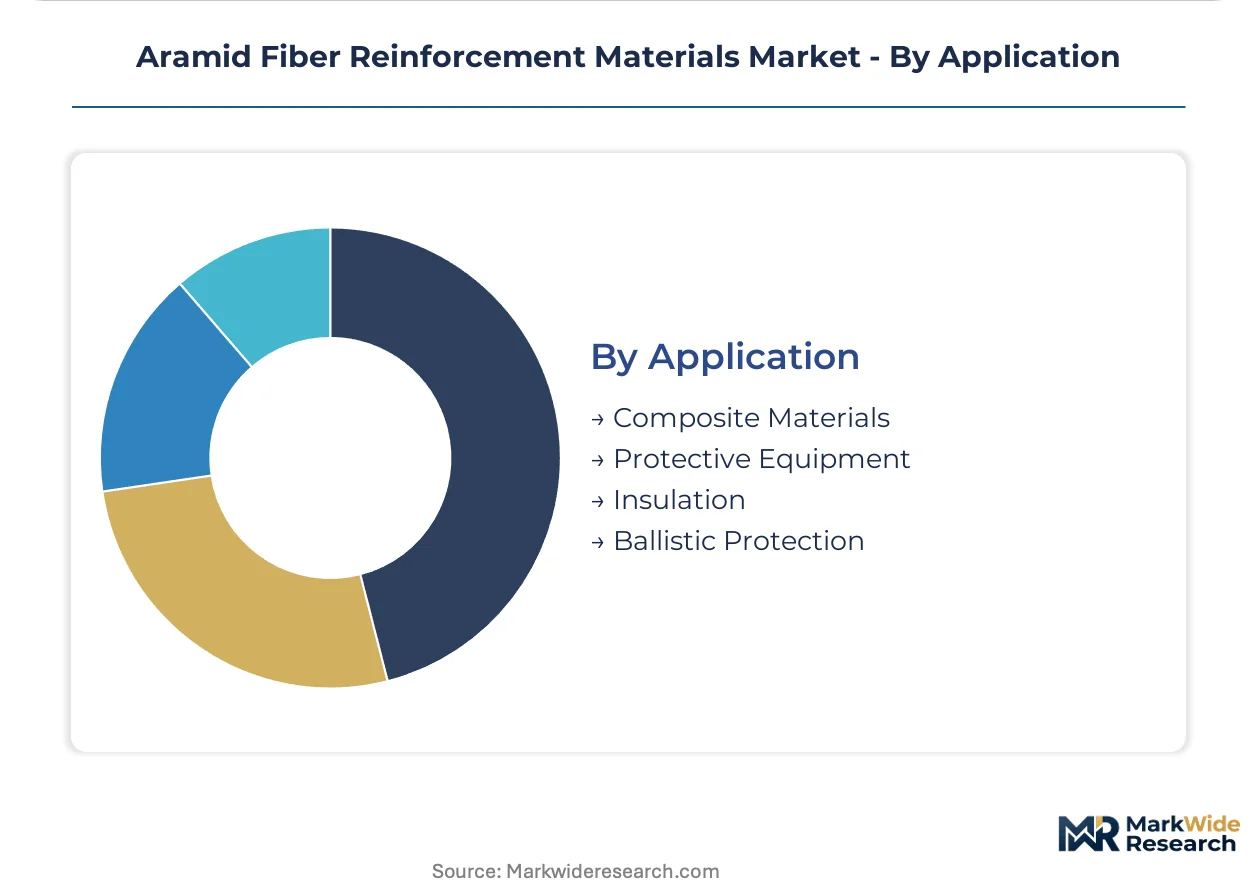
Supply concentration shapes competitive dynamics, with ballistic protection requiring certified supply chains and insulation serving fragmented industrial buyers.
- Composite Materials:Polymer matrix reinforcement for structural load-bearing components in transportation and industrial equipment. Japan's METI energy-efficiency guidelines are accelerating aramid substitution for metallic structures in rail platforms.
- Protective Equipment:Firefighter turnout gear and industrial safety apparel exploit meta-aramid thermal stability and comfort properties.
- Insulation:Electrical and thermal barrier applications in transformers, motors, and battery systems.
- Ballistic Protection:Personnel armor and vehicle shielding requiring NIJ certification and DFARS compliance documentation.
Composite Materials dominates volume. Ballistic Protection shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary European entry point for aramid precursor chemicals, while the Trans-Siberian rail link shapes supply routing into Asia-Pacific manufacturing clusters.
United States
Defense procurement offices in Arlington accelerate para-aramid laminate orders for next-generation personnel armor and vehicle shielding systems. The Department of Commerce export controls on ballistic-grade filaments force compounders to maintain dual-source precursor arrangements. Wilmington, Delaware hosts concentrated spinning operations serving North American aerospace contracts with documented chain-of-custody compliance.
Germany
Automotive OEMs in Stuttgart and Munich substitute aramid composites for steel battery enclosures in electric vehicles to meet EU Green Deal fleet weight reduction mandates. ECHA's REACH substance restrictions on N-methyl-2-pyrrolidone solvent systems trigger capital commitments for solvent recovery infrastructure at Wilhelmshaven facilities. The Ruhr industrial corridor anchors meta-aramid insulation demand for transformer and motor applications.
Japan
METI energy-efficiency guidelines for transportation equipment accelerate aramid composite substitution for heavier metallic structures across the Tokaido and Sanyo Shinkansen corridors. The Matsuyama industrial zone maintains integrated spinning and weaving operations ensuring supply continuity for domestic railcar manufacturers. Osaka-based electrical equipment producers consume meta-aramid sheet forms for high-temperature insulation systems.
China
GB 8624 fire safety standards for public transit interior materials generate replacement demand for meta-aramid insulation in metro fleet refurbishments across Beijing and Shanghai. The Yangtze River Delta concentration of precursor chemical production creates vulnerability to export license delays for meta-phenylenediamine and terephthaloyl chloride. Yantai and Jiangsu province host emerging domestic filament spinning capacity targeting industrial conveyor belting applications.
South Korea
Hyundai and Kia electric vehicle programs in Ulsan and Asan qualify para-aramid underbody shields for domestic and Southeast Asian export models. The Jeonju industrial complex anchors cost-competitive filament production targeting automotive tier suppliers. Busan port infrastructure supports precursor import flows from Chinese chemical clusters while maintaining compliance with Korean GB standard equivalency requirements for fire safety components.
Aramid Fiber Reinforcement Materials Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in filament spinning and fabric weaving operations. The vendor base concentrates around three integrated conglomerates with captive precursor supply and five mid-scale compounders dependent on merchant fiber purchases. Strategic archetypes separate patent-holding spinners with aerospace certification from cost-optimized weavers serving industrial belting and automotive panel applications. Capacity expansion and backward integration into precursor chemicals represent the dominant competitive moves as REACH compliance costs escalate.
Among Asia-Pacific-based manufacturers, Kolon Industries, Inc., Toray Industries, Inc., and Teijin Limited occupy positions spanning the value chain from polymerization through composite fabrication. These entities exemplify the integrated archetype combining spinning, weaving, and laminate qualification under single corporate structures. Their geographic dispersion across Korean, Japanese, and Thai production nodes reflects strategic hedging against regional trade friction and regulatory divergence on chemical substance restrictions.
| Leading Market Players |
|---|
| Kolon Industries, Inc. |
| Toray Industries, Inc. |
| DuPont de Nemours Inc. |
| Honeywell International Inc. |
| Huvis Corporation |
| Teijin Limited |
| Hyosung Corporation |
| SRO Aramid (Jiangsu) Co., Ltd. |
| Yantai Tayho Advanced Materials Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity warnings from Wilhelmshaven spinning facilities are compressing filament pricing power while simultaneously accelerating supplier consolidation into multi-year offtake agreements with aerospace laminators. This utilization dynamic rewards integrated producers with captive precursor supply and marginalizes merchant fiber buyers facing volatile meta-phenylenediamine cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NIJ-certified ballistic grades from industrial conveyor belting specifications and automotive panel commodity tiers. Price differentiation hinges on REACH compliance documentation and DFARS chain-of-custody certification, with aerospace laminators in Toulouse and Wichita showing minimal price sensitivity compared to cost-optimized automotive tier suppliers in Vietnam. Pricing pressure stems from carbon fiber substitution in wing spar applications where Toray prepregs capture modulus-critical contracts.
Supply Chain Analysis
Extended payment terms from Korean automotive OEMs are reshaping working capital requirements for Jeonju-based filament producers competing on cost. Supply concentrates in Japan, the United States, and Germany for para-aramid spinning, while China dominates meta-phenylenediamine and terephthaloyl chloride precursor production. Raw material dependencies rest on petrochemical feedstocks, sulfuric acid for wet-spinning coagulation, and N-methyl-2-pyrrolidone solvent systems now restricted under REACH. Single-source vulnerability in Yangtze River Delta chemical clusters threatens cross-border shipment eligibility. Distribution runs through direct mill relationships displacing traditional chemical distributors for high-modulus reinforcement buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through NIJ certification and REACH qualification creates prohibitive switching costs for incumbent compounders.
For Market Incumbents: Build regulatory moats by accelerating DFARS-compliant supply chain documentation and securing dual-source precursor arrangements before export license delays disrupt procurement. DuPont and Teijin should deepen backward integration into terephthaloyl chloride production to neutralize Chinese supply concentration risk. Capacity expansion in Vietnam positions suppliers to capture Hyundai and Toyota electric vehicle shield qualifications. For New Entrants and Emerging Players: Establish a beachhead in recyclable thermoplastic aramid composites where Polyetheretherketone matrix systems enable closed-loop processing for industrial belting. The most penetrable white space sits in Southeast Asian automotive manufacturing, where Haiphong-area assembly plants lack qualified local filament suppliers. A go-to-market angle through solvent-free spinning technologies bypasses REACH authorization bottlenecks constraining European incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated spinners with captive aerospace certification and multi-year defense contracts. Long-term viability favors entities controlling upstream precursor supply and downstream weaving operations across geographically dispersed production nodes. The signal to watch is ECHA substance list expansion accelerating consolidation pressure on solvent-dependent meta-aramid producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive supply of meta-phenylenediamine neutralizes Yangtze River Delta export license vulnerability. |
| Long-term Supply Agreement | Multi-year offtake contracts with Toulouse aerospace laminators lock in premium pricing tiers. |
| Green Manufacturing Transition | Ionic liquid spinning migration addresses ECHA N-methyl-2-pyrrolidone authorization restrictions. |
| Capacity Expansion | Jeonju facility additions target cost-competitive automotive tier supplier qualification in Vietnam. |
| Joint Venture | Thai production partnerships hedge against regional trade friction on ballistic-grade filament exports. |
Study Parameters
Operator-level perspectives from filament spinning technicians, aerospace laminator procurement leads, automotive tier supplier engineers, and chemical distribution channel managers anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation through customs trade data, SEC 10-K filings from DuPont and Teijin, ECHA substance restriction updates, and Japan METI energy-efficiency guideline releases. Bottom-up volume modeling across para-aramid, meta-aramid, and blended chemistries triangulated against top-down aerospace and automotive demand projections.
Scenario-bracketing around defense procurement acceleration, EU Green Deal fleet weight mandates, and REACH chemical traceability enforcement shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating carbon fiber substitution elasticity and ballistic protection modernization cycles.
Sensitivities concentrate around ECHA candidate list expansion, Department of Commerce export control tightening, and Chinese GB standards enforcement on public transit fire safety materials. Forecasts reflect documented assumptions on precursor supply continuity and certification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Renewable Carbon Fibers Market
Fibers
Artificial Muscle Fibers Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
High Performance Fibers for Defense Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Vinylon Market
Fibers
Fiberglass Cloth Market
Fibers
Carbon Fiber Market
Fibers
Fiber Intermediates Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Dry-Molded Fibre Market