
 Muscle Stimulator Market | 2026-2036
Muscle Stimulator Market Size, Share, and Industry Trends Forecast 2026-2036
Muscle Stimulator Market Intelligence
Direct-to-consumer e-commerce is rewriting how muscle stimulator brands reach patients and athletes outside traditional clinical procurement. OMRON Corporation leverages its established cardiovascular device distribution network to sustain shelf presence across pharmacy and medical supply channels. Zynex Medical specializes in prescription electrotherapy systems that anchor its position in physician-directed rehabilitation settings.
A muscle stimulator delivers controlled electrical impulses through electrodes placed on skin to activate motor nerves and induce muscle contraction, typically operating at frequencies between 1 Hz and 120 Hz depending on therapeutic objective. These devices serve to prevent atrophy, manage chronic pain, and accelerate recovery from musculoskeletal injury or neurological impairment. Neuromuscular electrical stimulation occupies the deepest clinical tier where hospital reimbursement and prescription requirements protect margin pools from consumer-grade commoditization. Wireless technology is displacing tethered systems in athletic training applications where freedom of movement during exercise protocols drives purchasing preference.
FDA 510(k) clearance requirements and the EU MDR classification framework shape product development timelines and market access costs for manufacturers targeting the United States and European Union. The EU AI Act and evolving cybersecurity standards for connected wearable devices add compliance layers that favor established players with dedicated regulatory affairs capacity. Stakeholders must monitor how FDA guidance on software-as-a-medical-device and EU harmonized standards for active implantable peripherals reshape competitive barriers for next-generation portable stimulator platforms.
Market Dynamics
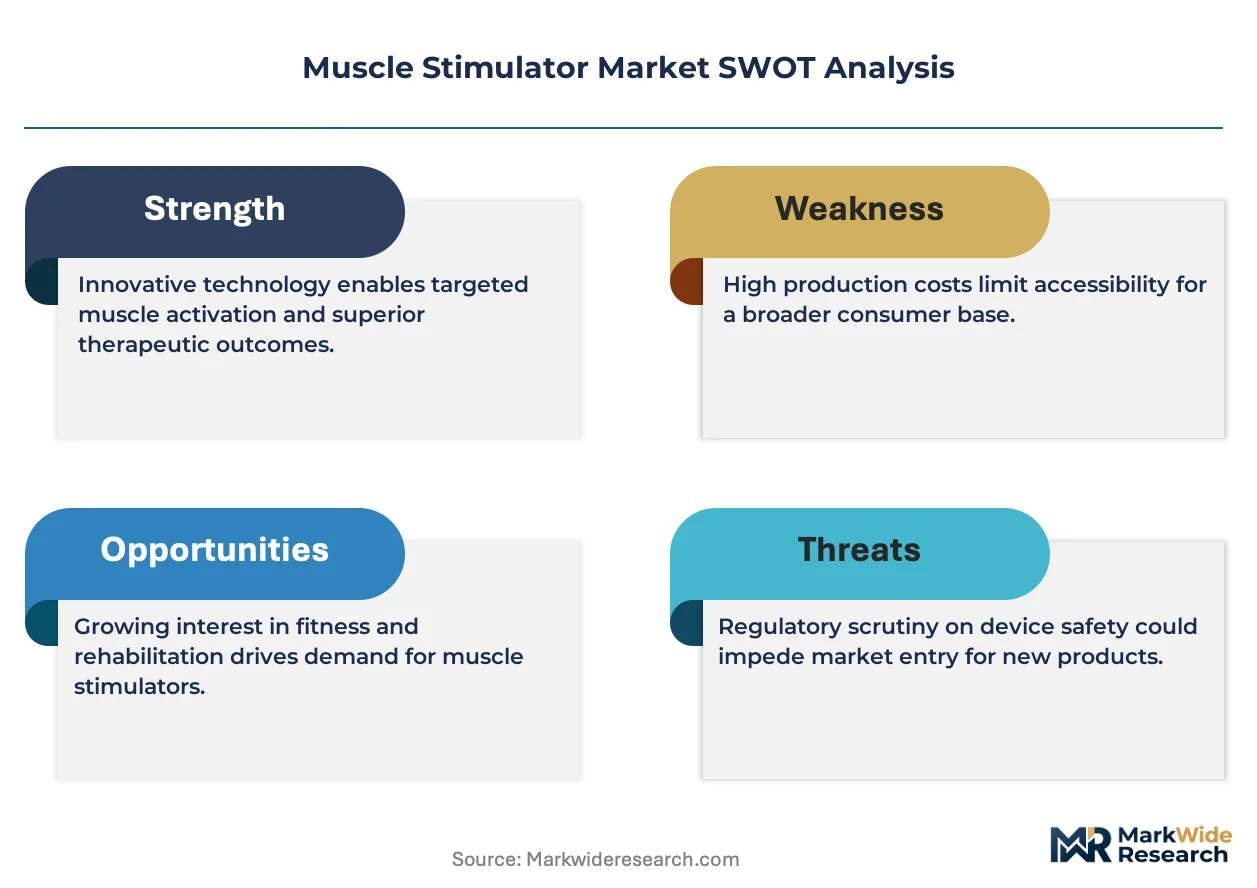
Wireless connectivity protocols and miniaturized power electronics are collapsing the cost and form-factor barriers that once separated clinical-grade muscle stimulators from consumer wellness devices, forcing incumbent manufacturers to defend margin pools across dual distribution channels.
Growth Catalysts
- Aging demographics in developed economies:Medicare reimbursement for neuromuscular electrical stimulation in post-surgical rehabilitation drives clinical procurement volumes in the United States. Physician prescribing patterns increasingly favor prescription electrotherapy for chronic pain management.
- Wearable form-factor adoption:Bluetooth Low Energy and flexible printed circuit boards enable garment-integrated stimulation systems. Professional sports teams in Germany and Australia deploy these systems for real-time muscle activation during training protocols.
- EU Medical Device Regulation harmonization:MDR Class IIa classification clarity reduces regulatory uncertainty for manufacturers seeking CE marking. This accelerates market access timelines for novel stimulation algorithms and software-upgradable hardware platforms.
Market Restraints
- Biocompatible electrode material costs:Silver-silver chloride and hydrogel conductive polymers face price volatility tied to precious metals markets. Input cost swings compress gross margins for disposable electrode consumables.
- Supply concentration in semiconductor foundries:Advanced pulse-width modulation controllers and low-noise operational amplifiers source predominantly from Taiwan and South Korea. Geopolitical friction risks interrupt component availability.
- Substitution by pharmacological pain management:Extended-release NSAID formulations and topical analgesic patches compete for chronic musculoskeletal pain cases. Payer formulary preferences in Germany and France sometimes favor drug therapy over device-based intervention.
Strategic Opportunities
- Home-use rehabilitation in Japan:METI reimbursement expansion for remote therapeutic monitoring creates white space for connected stimulator platforms. Aging population density in Tokyo and Osaka metropolitan areas concentrates addressable demand.
- Convergence with motion capture and AI:Integration of inertial measurement units and machine learning algorithms enables closed-loop stimulation responsive to movement patterns. This hybrid architecture opens athletic performance optimization applications.
- Direct-to-consumer telehealth channels:Remote prescription platforms and virtual physical therapy consultations bypass traditional durable medical equipment distribution. United States-based telehealth providers now bundle stimulator fulfillment with digital care programs.
Industry Challenges
- Embedded firmware engineering talent scarcity:Real-time signal processing expertise for closed-loop control systems commands premium compensation. Recruitment competition from automotive and aerospace sectors delays product development timelines.
- FDA 510(k) predicate device pathway complexity:Substantial equivalence determinations for software-as-a-medical-device features require extensive clinical validation. Documentation burdens extend time-to-market for algorithm-enabled products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muscle Stimulator Market |
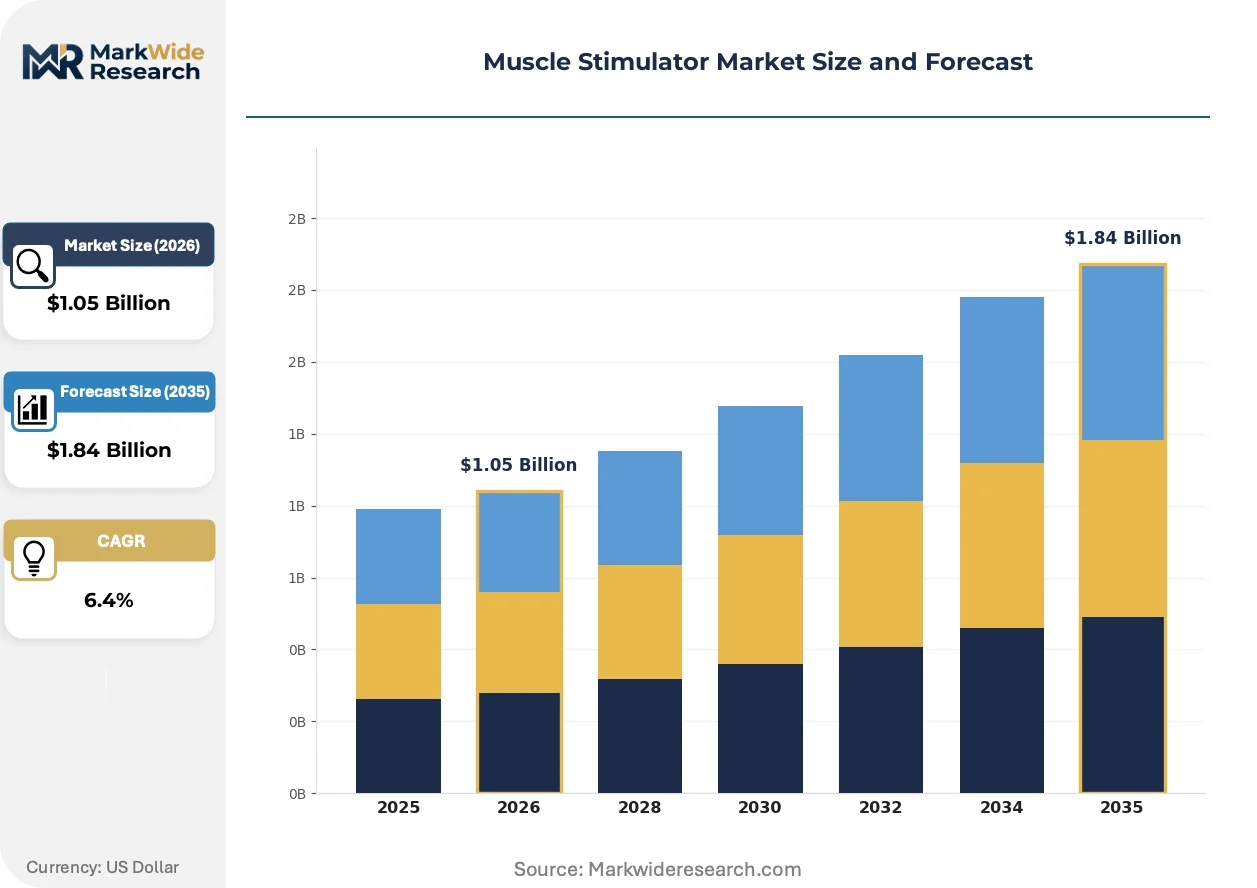
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulation, Functional Electrical Stimulation, Interferential Current Therapy, Neuromuscular Electrical Stimulation Application: Pain Relief, Muscle Recovery, Rehabilitation, Athletic Training End User: Hospitals, Sports Clinics, Home Care, Fitness Centers Technology: Electric Pulse, Wireless, Portable, Wearable |
| Companies Covered | NeuroMetrix, OMRON Corporation, Zynex Medical, DJO Global, Beurer GmbH, BioMedical Life Systems, EMS Physio, RS Medical, Zimmer MedizinSysteme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muscle Stimulator Market Strategic Shifts & Innovations
Digital health integration and personalized therapy protocols are redefining how muscle stimulation devices capture value, shifting competitive advantage from hardware specifications to data-driven treatment optimization and longitudinal patient engagement.
Cloud-connected stimulation platforms is digitizing treatment protocol management by enabling real-time parameter adjustment and adherence monitoring through smartphone interfaces. Sports medicine clinics in Australia and rehabilitation hospitals in Germany are deploying these systems to track patient compliance between supervised sessions. This architecture compresses the traditional separation between clinical oversight and home-based therapy, creating subscription revenue opportunities that offset hardware margin erosion.
The EU AI Act's risk classification framework for machine learning-enabled medical devices is tightening validation requirements for adaptive stimulation algorithms that modify output based on physiological feedback. Manufacturers must now maintain technical documentation demonstrating transparency and human oversight capabilities for AI-driven dosage adjustments. Products targeting the European market are responding by segregating deterministic safety-critical functions from probabilistic optimization layers.
Patients and athletes are purchasing stimulation hardware through specialty fitness retailers and brand-direct e-commerce rather than exclusive clinical procurement channels. This disintermediation pressures traditional durable medical equipment distributors that historically controlled physician referral flows. The United States exhibits the most pronounced channel fragmentation, where CrossFit affiliates and physical therapy direct-access clinics now stock consumer-grade units for immediate patient trial.
Muscle Stimulator Market Segmentation
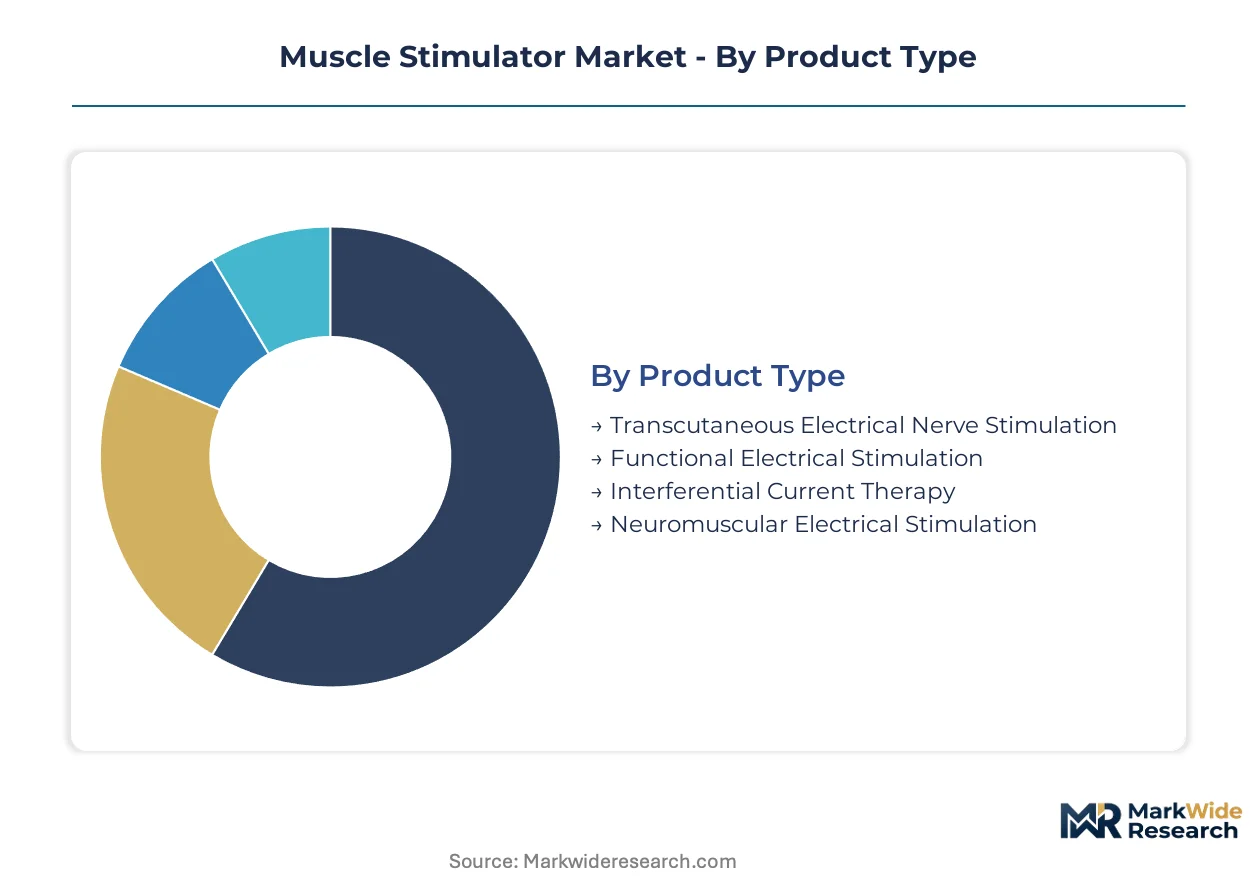
Product architecture and therapeutic intent determine how muscle stimulator manufacturers configure distribution channels and pricing tiers. Segmentation reveals where clinical reimbursement intersects with consumer purchasing power across device categories.
Product Type:
Use-case spectrum spans acute pain interruption to motor relearning protocols requiring precise waveform control.
- Neuromuscular Electrical Stimulation:Delivers high-intensity pulses above motor threshold to recruit deep muscle fibers for atrophy prevention. Demand concentrates in United States post-surgical rehabilitation where Medicare reimbursement protects margin pools from consumer-grade commoditization.
- Transcutaneous Electrical Nerve Stimulation:Operates at sensory-level frequencies to gate pain signals without muscle contraction. Home-use purchases in Germany and Australia drive volume through pharmacy retail channels bypassing prescription requirements.
- Functional Electrical Stimulation:Coordinates multi-channel sequencing to restore functional movement patterns in neurological impairment cases.
- Interferential Current Therapy:Crosses two medium-frequency currents to produce low-frequency therapeutic effects with deeper tissue penetration.
Established volume favors Transcutaneous Electrical Nerve Stimulation; emerging adoption favors Neuromuscular Electrical Stimulation.
Application:
Customer outcome expectations stratify between immediate symptomatic relief and long-term functional restoration.
- Pain Relief:Targets chronic musculoskeletal conditions through gate control or endorphin release mechanisms. Germany's statutory health insurance funds increasingly require prior drug therapy failure before device reimbursement authorization.
- Rehabilitation:Addresses motor deficit recovery following stroke, spinal cord injury, or orthopedic surgery. United States skilled nursing facilities anchor procurement volumes under bundled payment models that reward reduced readmission rates.
- Muscle Recovery:Accelerates clearance of metabolic byproducts following intense athletic exertion.
- Athletic Training:Integrates real-time activation into strength and conditioning protocols for performance enhancement.
Reimbursement stability favors Rehabilitation; direct-to-consumer velocity favors Pain Relief.
End User:
Channel economics diverge sharply between institutional procurement with extended sales cycles and impulse-driven retail transactions.
- Hospitals:Requires FDA 510(k) or EU MDR Class IIa certification for inpatient neuromuscular applications. United States health systems consolidate purchasing through group purchasing organizations that demand multi-year service contracts.
- Home Care:Bypasses clinical oversight through over-the-counter or remote prescription fulfillment models. Australia's TGA streamlined approval pathways for consumer-grade devices accelerate market access for wireless entrants.
- Sports Clinics:Purchases based on athlete retention metrics and protocol differentiation.
- Fitness Centers:Positions devices as membership retention tools with minimal clinical claims.
Margin protection favors Hospitals; volume expansion favors Home Care.
Technology:
Form-factor and connectivity specifications determine regulatory classification and distribution channel eligibility.
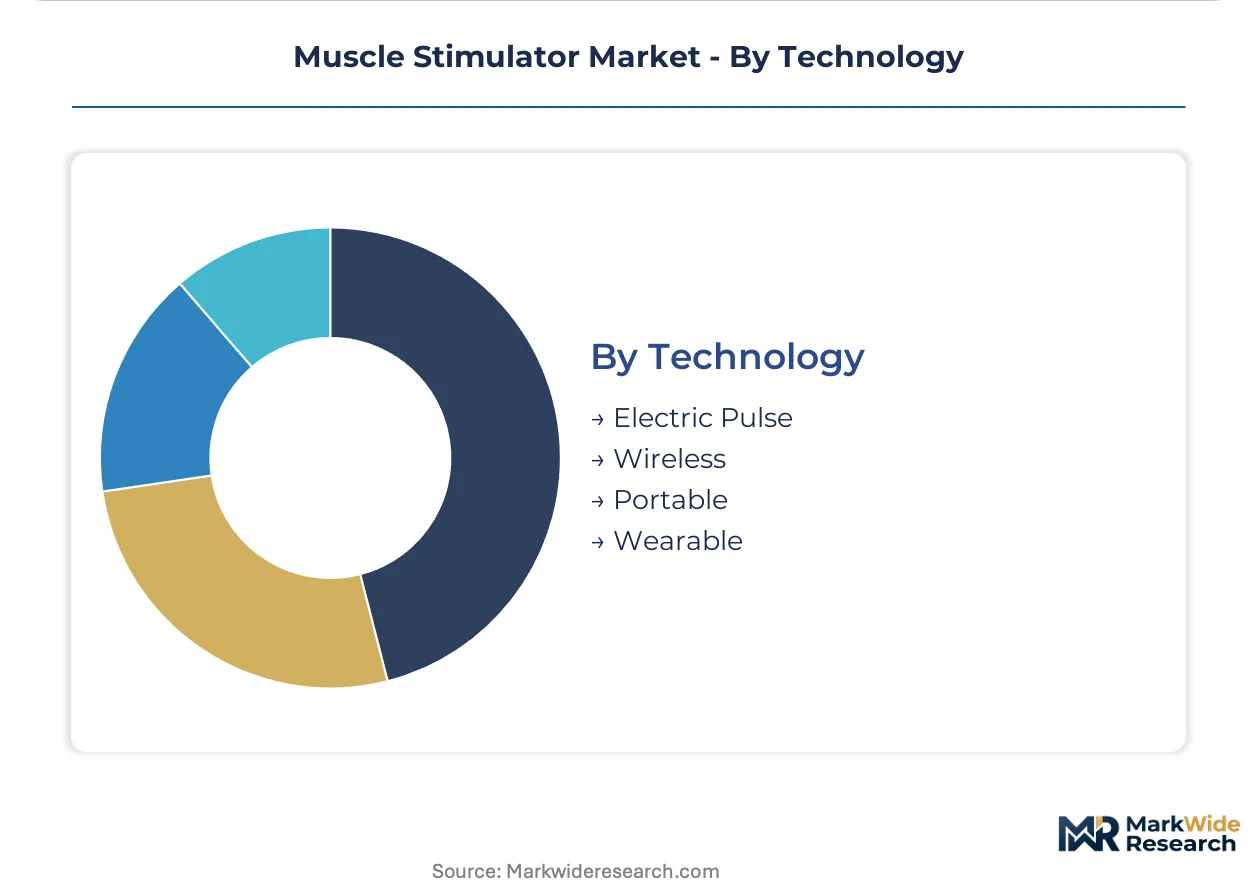
- Wearable:Integrates flexible electrodes and stretchable circuitry into compression garments for continuous ambulatory use. Professional sports teams in Germany deploy these systems for real-time muscle activation during training protocols without tethering constraints.
- Wireless:Eliminates lead wires through Bluetooth Low Energy communication with smartphone control interfaces. United States telehealth platforms bundle these devices with remote physical therapy consultations to bypass durable medical equipment distributors.
- Portable:Battery-powered handheld units with preset protocol libraries for clinical field use.
- Electric Pulse:Tethered mains-powered systems with maximum output precision for hospital settings.
Technology maturation favors Electric Pulse; steepest expansion trajectory favors Wireless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in the United States exceed reimbursement rates in Germany by substantial margins, creating a bifurcated procurement landscape where clinical-grade margins concentrate in North American health systems while European volume flows through pharmacy retail channels.
United States
Medicare reimbursement for neuromuscular electrical stimulation anchors hospital procurement volumes, with skilled nursing facilities driving bundled payment adoption. FDA 510(k) clearance requirements shape product development timelines for manufacturers targeting clinical channels. The Boston-Cambridge corridor hosts medical device engineering clusters where wearable stimulation startups partner with physical therapy direct-access clinics.
Germany
Statutory health insurance funds require prior drug therapy failure before authorizing device reimbursement, channeling demand toward over-the-counter transcutaneous units. EU MDR Class IIa classification harmonization reduces regulatory uncertainty for CE marking applicants. Sports medicine infrastructure in Munich and Cologne deploys wireless garment-integrated systems for Bundesliga athletic training protocols.
Japan
METI reimbursement expansion for remote therapeutic monitoring creates addressable demand for connected stimulator platforms in home-use rehabilitation. PMDA consultation pathways streamline approval for software-upgradable hardware targeting aging metropolitan populations. Tokyo and Osaka concentrate purchasing power where telehealth-integrated devices bypass traditional durable medical equipment distribution.
Australia
TGA streamlined approval pathways for consumer-grade wireless devices accelerate market access for Bluetooth-enabled entrants. Pharmacy retail chains and specialty fitness retailers capture patient purchases outside clinical procurement channels. Sydney and Melbourne rehabilitation hospitals pilot cloud-connected adherence monitoring systems for post-surgical recovery programs.
United Kingdom
NHS procurement frameworks favor multi-year service contracts with established electrotherapy suppliers, protecting incumbent positions in hospital settings. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines for novel stimulation algorithms. London sports medicine clinics and Manchester rehabilitation centers drive adoption of prescription electrotherapy for chronic pain management cases.
Muscle Stimulator Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying electrodes, pulse generators, and firmware modules to branded device manufacturers. The vendor base stratifies across three tiers: multinational cardiovascular device conglomerates with established distribution networks, prescription electrotherapy specialists anchored in physician-directed rehabilitation settings, and direct-to-consumer wellness brands bypassing clinical channels entirely. Two dominant competitive moves define current positioning: backward integration into biocompatible electrode manufacturing to capture consumable revenue streams, and strategic partnerships with telehealth platforms to bypass durable medical equipment distributors.
Among diversified health technology conglomerates, OMRON Corporation and Zynex Medical occupy positions representing contrasting channel strategies. OMRON exemplifies the pharmacy and medical supply channel anchor leveraging cardiovascular device infrastructure for shelf presence across retail and clinical settings. Zynex Medical represents the prescription electrotherapy specialist archetype focused on physician-directed rehabilitation with reimbursement-dependent revenue models. DJO Global sits within the orthopedic and physical therapy equipment tier where sports medicine infrastructure drives institutional procurement. These three entities illustrate how regulatory pathway selection and distribution channel alignment separate margin pools in a market where wireless technology collapses traditional hardware differentiation.
| Leading Market Players |
|---|
| NeuroMetrix |
| OMRON Corporation |
| Zynex Medical |
| DJO Global |
| Beurer GmbH |
| BioMedical Life Systems |
| EMS Physio |
| RS Medical |
| Zimmer MedizinSysteme |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundries and South Korean analog component manufacturers anchor pulse-width modulation controller supply, concentrating pricing power upstream while forcing branded device assemblers to defend margin pools through electrode consumable streams and software subscription layering.
Pricing Analysis
Configured-to-order prescription electrotherapy systems command substantial premiums over standard consumer-grade units, with FDA 510(k) certification tier and silver-silver chloride electrode quality grade driving price differentiation. Three-tier pricing structure across premium clinical, standard professional, and economy direct-to-consumer levels stratifies the market, though cost compression in the wireless wearable tier is intensifying because Bluetooth Low Energy module commoditization erodes hardware margins. Hospital procurement committees exhibit lowest price sensitivity due to Medicare reimbursement protection, while fitness center buyers and direct-to-consumer athletes demonstrate highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced pulse-width modulation controllers and low-noise operational amplifiers limit component flows from Taiwan and South Korea to non-aligned manufacturing jurisdictions. Geographic supply concentration centers on Taiwan for semiconductor fabrication, South Korea for analog integrated circuits, and China for flexible printed circuit board substrate. Silver and hydrogel polymer feedstock dependencies expose electrode manufacturers to precious metals commodity volatility. Single-source vulnerability in semiconductor foundry capacity represents the dominant structural risk. Distribution runs through durable medical equipment distributors for hospital channels, pharmacy retail chains for over-the-counter units, and direct-to-consumer e-commerce for wireless entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The muscle stimulator market exhibits cyclical recovery characteristics driven by Medicare reimbursement rate resets following post-pandemic utilization normalization, creating asymmetric return opportunities for positioned stakeholders.
For Market Incumbents: Entrench position through backward integration into biocompatible electrode manufacturing to capture recurring consumable revenue and offset hardware margin erosion from wireless commoditization. Prioritize certification investment in EU MDR Class IIa pathways to defend European hospital access against emerging software-upgradable competitors.
For New Entrants and Emerging Players: Japan's home-use rehabilitation segment offers the most penetrable white space given METI reimbursement expansion for remote therapeutic monitoring and concentrated aging population density in Tokyo-Osaka corridors. Target telehealth platform partnerships as the primary go-to-market angle to bypass entrenched durable medical equipment distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward prescription electrotherapy specialists with established physician-directed rehabilitation channels and reimbursement-dependent revenue models that demonstrate durable competitive moats. Watch FDA guidance on software-as-a-medical-device classification as the critical inflection signal for algorithm-enabled platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa certification unlocks German hospital procurement and Bundesliga sports medicine contracts. |
| Software Companion Development | Cloud-connected adherence monitoring platforms enable subscription revenue that offsets hardware margin compression. |
| Hospital System Partnership | United States GPO contract penetration protects volume through bundled payment models that reward readmission reduction. |
| Reimbursement Strategy | Medicare coding alignment for neuromuscular electrical stimulation secures prescription electrotherapy margin pools. |
| Strategic Partnership | Telehealth platform bundling bypasses traditional DME distribution and captures direct-to-consumer velocity. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and physical therapy clinic directors and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up unit demand modeling and top-down market sizing triangulation anchored value estimates across the analysis window.
Demand-supply balance dynamics shaped the analytical framework, with segmentation across product type, application, end user, and technology dimensions modeled throughout the forecast period. CAGRs derived from regression analysis of historical reimbursement trends and wireless adoption curves, incorporating semiconductor component lead time volatility and silver price trajectory assumptions as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich cardiovascular device conglomerates into prescription electrotherapy would shift outcomes. Material shifts in FDA software-as-a-medical-device guidance or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
External Pacemakers Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
C-Arms Devices Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market