
 Hearing Amplifiers Market | 2026-2036
Hearing Amplifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Amplifiers Market Intelligence
Modular product bundling is broadening buyer choice in hearing amplifiers, with retailers now pairing devices with subscription-based teleaudiology services and accessory ecosystems. Eargo leverages its direct-to-consumer channel control to sustain premium positioning in rechargeable in-canal formats. MDHearingAid competes on price-accessibility through online-only distribution, while JINGHAO anchors manufacturing scale for private-label and branded analog-to-digital transitions.
Hearing amplifiers are electronic sound-amplification devices designed for mild-to-moderate hearing loss, typically operating within frequency ranges of 200–6,000 Hz with programmable digital signal processing or basic analog circuitry; they serve consumers seeking lower-cost alternatives to prescription hearing aids. Behind-the-ear configurations dominate unit volume due to ergonomic adaptability and battery longevity, while Bluetooth-enabled digital models capture expanding margin pools from smartphone-integrated users. Rechargeable technology segments are displacing disposable battery dependence among senior and adult end users seeking reduced maintenance burden.
FDA OTC hearing aid regulations, CE marking requirements under EU MDR, and ISO 10993 biocompatibility standards collectively shape product safety thresholds and market entry pathways across North America and Europe. The FDA framework specifically enables retail pharmacy and online distribution without audiologist gatekeeping, compressing traditional channel margins. Stakeholders must monitor evolving reimbursement parity debates between OTC amplifiers and regulated hearing aids, as policy shifts will determine whether direct-to-consumer brands capture permanent share from clinic-dependent incumbents.
Market Dynamics
FDA over-the-counter hearing aid regulations are compressing traditional audiology channel margins while opening retail pharmacy and direct-to-consumer pathways for sound-amplification devices.
Growth Catalysts
- OTC Regulatory Framework:FDA regulations in the United States eliminate audiologist gatekeeping requirements, enabling pharmacy and online distribution channels to capture senior consumers seeking affordable hearing assistance.
- Rechargeable Lithium-Ion Battery Technology:Disposable battery dependence is diminishing among adult end users who prioritize reduced maintenance burden and lower lifetime operating costs.
- Aging Demographics in Developed Economies:Senior populations in the United States, Germany, and Japan are expanding the addressable market for lower-cost alternatives to prescription hearing aids.
Market Restraints
- Semiconductor Component Concentration:Digital signal processing chip supply concentrates among Taiwanese and South Korean foundries, exposing manufacturers to geopolitical disruption risk.
- Biocompatibility Certification Burden:ISO 10993 testing requirements for in-canal materials extend product development timelines and elevate compliance costs for new market entrants.
- Prescription Hearing Aid Substitution:Traditional hearing aid manufacturers are launching lower-cost digital lines that compete directly with amplifier positioning in mild-to-moderate loss segments.
Strategic Opportunities
- Teleaudiology Service Integration:Remote hearing assessment and device programming platforms enable direct-to-consumer brands to deliver clinical-grade support without physical clinic infrastructure.
- Bluetooth-Enabled Smartphone Convergence:iOS and Android hearing accessibility APIs allow amplifiers to function as wireless audio peripherals for media consumption and voice communication.
- Underserved Rural Medicare Populations:Geographic access gaps to audiology clinics in the United States interior create white space for mail-order and pharmacy-distributed amplification solutions.
Industry Challenges
- Audiologist Workforce Scarcity:Training pipeline limitations in the United States and Europe constrain the clinical support capacity needed for hybrid care models combining OTC devices with professional services.
- CE Marking Transition Under EU MDR:Medical device regulation reclassification requirements are forcing manufacturers to resubmit technical documentation and clinical evidence packages for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Amplifiers Market |
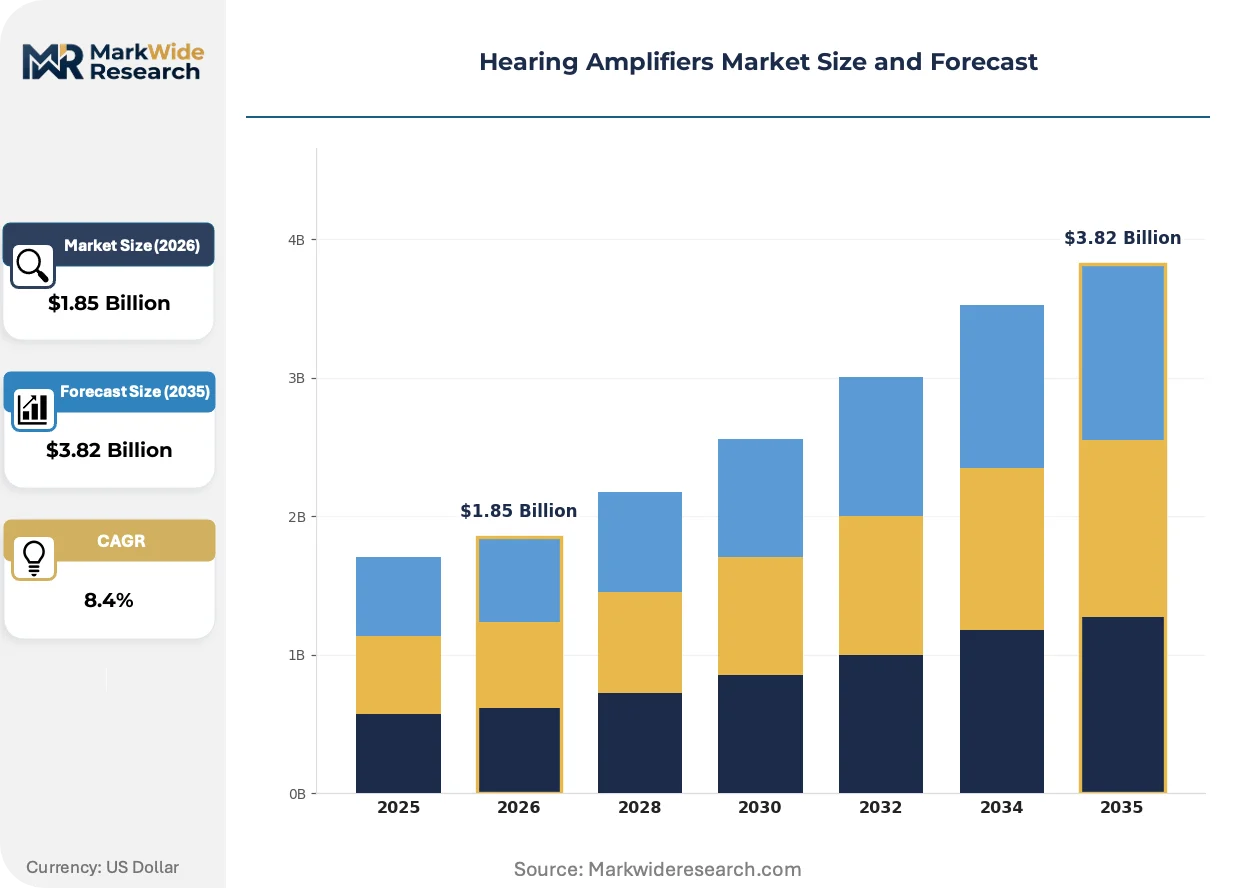
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BTE, ITE, ITC, CIC Technology: Analog, Digital, Rechargeable, Bluetooth End User: Adults, Seniors, Pediatric, Military Distribution Channel: Pharmacies, Online, Audiology Clinics, Hospitals |
| Companies Covered | Beurer, JINGHAO, Medline, Sound World Solutions, Britzgo, MDHearingAid, Eargo, InnerScope Hearing Technologies, Lucid Audio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Amplifiers Market Strategic Shifts & Innovations
Digital signal processing architectures are absorbing functions previously requiring discrete components, while regulatory frameworks and distribution channels undergo simultaneous restructuring.
Adaptive noise reduction algorithms are absorbing hardware-based directional microphone arrays in mid-tier amplifier designs. Senior users and adult professionals with mild-to-moderate hearing loss are adopting these integrated digital platforms faster than analog-to-digital transition timelines projected. The technology compression is enabling smaller in-canal form factors without sacrificing frequency response range.
CE marking requirements under EU MDR are elevating clinical evidence standards for hearing amplification devices sold in European markets. Manufacturers must now submit biocompatibility testing and post-market surveillance plans that exceed previous medical device directive thresholds. Private-label suppliers serving European audiology clinic networks are consolidating quality management systems to meet notified body expectations.
Direct-to-consumer channel preference is displacing clinic-dependent fitting workflows among price-sensitive buyers. Online hearing tests and smartphone-based self-programming applications are replacing traditional audiogram appointments for initial device selection. This behavioral shift concentrates in United States suburban markets where audiology clinic density remains below metropolitan benchmarks.
Hearing Amplifiers Market Segmentation
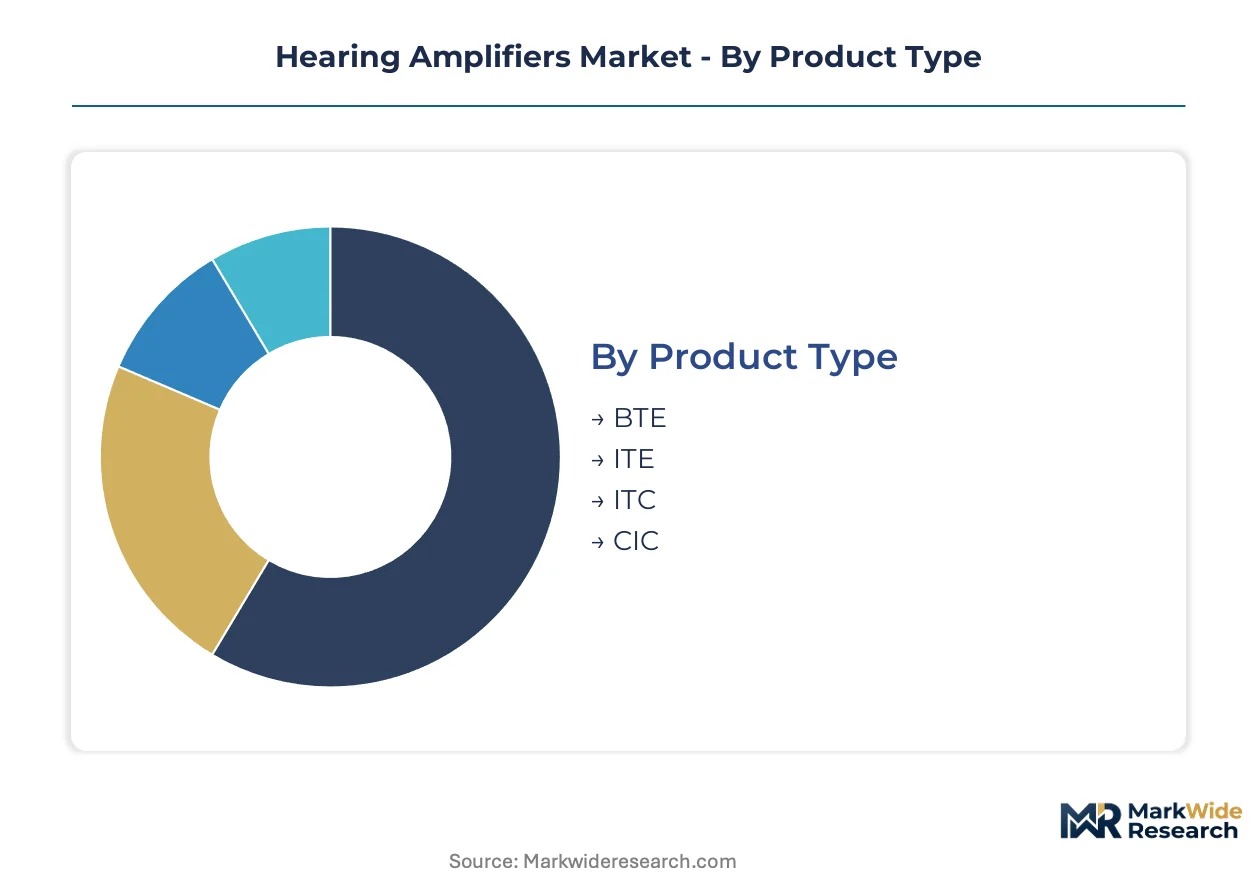
Hearing amplifier manufacturers calibrate product portfolios against distinct upgrade cycles: disposable battery models face 3-4 year replacement timelines while rechargeable platforms compress this to 2-3 years as lithium-ion degradation accelerates refresh demand. Segmentation discipline separates volume capture from margin extraction across four structural dimensions.
Product Type:
Behind-the-ear units dominate replacement volumes due to component accessibility and repairability, while in-canal formats drive upgrade frequency through cosmetic obsolescence and fit degradation.
- BTE:These devices house electronics in a casing resting behind the ear with sound delivered through tubing to an earmold. Volume concentrates among United States Medicare beneficiaries in rural counties where repair access outweighs discretion preferences. The ergonomic adaptability supports extended wear durations for agricultural and manufacturing workers.
- ITE:In-the-ear configurations fill the concha bowl with custom-molded shells. Demand clusters in German audiology networks where statutory reimbursement thresholds favor this form factor over smaller alternatives. The exposed surface area simplifies battery replacement for arthritis-limited dexterity.
- ITC:In-the-canal devices occupy the lower ear canal entrance. Japanese senior populations favor this balance of concealment and handling ease in metropolitan Tokyo and Osaka markets.
- CIC:Completely-in-canal models sit deeply within the ear canal with extraction cords. Professional services workers in United Kingdom financial districts prioritize this format for telephone headset compatibility.
Volume placements concentrate in BTE configurations; the faster expansion belongs to CIC as remote-work norms elevate discretion premiums.
Technology:
Cost-tier stratification separates entry analog circuits from premium digital platforms, with power-source architecture emerging as the decisive margin determinant.
- Digital:Programmable signal processing enables frequency-specific amplification with feedback cancellation. United States direct-to-consumer channels capture adult professionals seeking smartphone app control without audiologist appointments. The FDA OTC framework accelerates adoption through pharmacy accessibility.
- Rechargeable:Lithium-ion battery integration eliminates disposable cell procurement. Senior cohorts in Florida and Arizona retirement communities prioritize this reduction in maintenance burden and vision-dependent battery handling.
- Bluetooth:Wireless connectivity enables direct audio streaming from smartphones and televisions. North American suburban households with high streaming-media consumption drive replacement cycles here.
- Analog:Basic amplification circuitry without digital processing serves price-sensitive buyers in cash-pay markets. Private-label suppliers anchor manufacturing scale for this tier.
Rechargeable platforms command the steepest expansion trajectory; analog maintains volume anchoring in emerging market access points.
End User:
Customer-type segmentation aligns device complexity with cognitive load capacity and lifestyle noise exposure profiles.
- Seniors:Adults aged 65+ with presbycusis-related high-frequency loss constitute the dominant addressable base. United States Medicare coverage gaps for amplification devices drive demand toward sub-prescription price points. Large-button controls and telecoil compatibility dominate feature prioritization.
- Adults:Working-age users with noise-induced or early-onset loss seek occupational discretion. Professional services segments in London and New York prioritize invisible form factors for client-facing roles.
- Pediatric:Children with congenital or early-acquired hearing impairment require durable, tamper-resistant housings. This segment concentrates in specialist hospital networks with audiology department integration.
- Military:Service members require hearing protection with selective amplification for situational awareness. Department of Defense procurement specifications drive ruggedization standards.
Senior placements anchor volume scale; adult professional segments climb the fastest as workplace accommodation awareness spreads.
Distribution Channel:
Channel configuration determines service bundling economics and customer acquisition cost structures.
- Online:Direct-to-consumer platforms enable self-selection with remote programming support. United States suburban markets with audiology clinic deserts concentrate here. Teleaudiology integration reduces return rates through virtual fitting assistance.
- Pharmacies:Retail drugstore placement leverages foot traffic from prescription pickup routines. CVS and Walgreens storefronts in United States secondary cities capture impulse consideration from senior shoppers.
- Audiology Clinics:Professional fitting services with in-person verification attract buyers seeking clinical validation. German statutory health insurance reimbursement pathways reinforce this channel's persistence in European markets.
- Hospitals:Acute care and outpatient ENT departments serve post-diagnosis immediate needs. Pediatric and sudden hearing loss cases concentrate here for specialist oversight.
Online channels scale volume fastest; audiology clinics retain margin concentration through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in Chinese component clusters while consumption gravity pulls toward aging populations in developed economies. The United States and Germany anchor demand through regulatory-enabled direct-to-consumer channels, whereas Japan and the United Kingdom sustain clinic-integrated distribution models.
United States
Senior populations in Florida and Arizona retirement communities drive rechargeable device adoption. FDA OTC regulations eliminate audiologist gatekeeping, enabling CVS and Walgreens pharmacy distribution alongside online direct-to-consumer platforms. Dallas-Fort Worth and Phoenix metropolitan areas concentrate teleaudiology service providers addressing rural Medicare access gaps.
Germany
Statutory health insurance reimbursement thresholds shape audiology clinic demand for in-the-ear configurations. EU MDR CE marking requirements force manufacturers to resubmit technical documentation with elevated biocompatibility evidence. Munich and Berlin audiology networks consolidate quality management systems to meet notified body expectations under reclassification rules.
Japan
Metropolitan Tokyo and Osaka senior populations favor in-the-canal devices balancing concealment with handling ease. METI standards govern electromagnetic compatibility for Bluetooth-enabled models. Nagoya industrial clusters supply precision miniaturization components for completely-in-canal form factors targeting professional services workers.
United Kingdom
London financial district professionals prioritize completely-in-canal models for telephone headset compatibility. The Medicines and Healthcare products Regulatory Agency aligns post-market surveillance with EU MDR transition timelines. Manchester and Birmingham audiology clinics retain margin concentration through service bundling despite online channel growth.
China
Zhengzhou and Shenzhen manufacturing hubs anchor private-label production for analog-to-digital transitions. NMPA medical device classification distinguishes regulated hearing aids from consumer amplification devices. Shanghai and Beijing urban consumers drive demand for smartphone-integrated Bluetooth models through e-commerce platforms.
Hearing Amplifiers Market Key Industry Players
The competitive structure tilts toward direct-to-consumer specialists with channel control advantages over clinic-dependent incumbents. FDA OTC regulations compress traditional audiology margins while opening retail pharmacy pathways. Two strategic archetypes dominate: rechargeable in-canal specialists leveraging teleaudiology integration, and price-accessibility players capturing online-only distribution. Competitive moves concentrate on M&A for teleaudiology platforms and geographic expansion into pharmacy retail networks.
Among direct-to-consumer specialists, Eargo and MDHearingAid exemplify divergent positioning strategies within the same regulatory framework. Eargo represents the premium rechargeable segment with controlled channel economics, while MDHearingAid occupies the price-accessibility tier through online-only distribution. JINGHAO anchors manufacturing-scale supply for private-label and branded transitions, sitting within the production-heavy archetype serving multiple downstream positioning strategies.
| Leading Market Players |
|---|
| Beurer |
| JINGHAO |
| Medline |
| Sound World Solutions |
| Britzgo |
| MDHearingAid |
| Eargo |
| InnerScope Hearing Technologies |
| Lucid Audio |
| Others |
Cost & Logistics Intelligence
United States Medicare beneficiary concentration in rural counties sustains per-unit transactional pricing for behind-the-ear configurations, while rechargeable lithium-ion platforms command subscription-anchored bundles through direct-to-consumer channels.
Pricing Analysis
Cost-down pressure on analog tiers accelerates because private-label manufacturers in Zhengzhou and Shenzhen compete for audiology clinic procurement contracts. Three-tier pricing structure across premium rechargeable, standard digital, and economy analog levels separates Eargo's teleaudiology-integrated bundles from MDHearingAid's online-only accessibility plays. FDA OTC regulatory compliance costs widen spreads between certified and uncertified entrants. Senior cohorts in Florida retirement communities exhibit highest price sensitivity, whereas London financial district professionals absorb premiums for completely-in-canal discretion.
Supply Chain Analysis
Dual-sourcing mandates from United States direct-to-consumer brands now require qualification of Taiwanese and South Korean foundries for digital signal processing chips alongside Chinese assembly partners. Lithium-ion battery cells, biocompatible silicone earmolds, and precision miniaturization components feed from Nagoya industrial clusters and Shenzhen electronics hubs. Single-source vulnerability concentrates in Taiwanese semiconductor foundries exposed to geopolitical disruption. Distribution runs through pharmacy retail networks, audiology clinic service bundling, and direct-to-consumer platforms with teleaudiology integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA over-the-counter hearing aid regulations erect a cost-of-compliance moat that rewards players with pre-positioned quality management systems and notified body relationships, while filtering out capital-constrained entrants lacking ISO 10993 biocompatibility documentation.
For Market Incumbents: Anticipate prescription hearing aid manufacturer encroachment into mild-to-moderate loss segments by accelerating teleaudiology platform integration and locking pharmacy retail exclusivity. Backward integration into lithium-ion battery cell procurement mitigates South Korean foundry concentration risk. Certification investment in EU MDR CE marking pathways preserves European audiology clinic access against reclassification disruption. For New Entrants and Emerging Players: Smartphone-based self-programming applications offer a technology-first wedge against incumbent clinic-dependent workflows. Underserved rural Medicare populations in United States interior states represent the most penetrable geography, with mail-order amplification addressing audiology clinic deserts. Pharmacy retail partnerships with CVS and Walgreens storefronts provide immediate channel credibility without proprietary infrastructure buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor rechargeable platform specialists with captive teleaudiology capabilities in United States suburban markets. Long-term viability hinges on reimbursement parity outcomes between OTC amplifiers and regulated hearing aids. The signal to monitor is FDA enforcement discretion on marketing claims that blur device classification boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Teleaudiology Platform Acquisition | Remote fitting capabilities reduce return rates for Eargo and MDHearingAid direct-to-consumer shipments. |
| Pharmacy Retail Network Expansion | CVS and Walgreens storefronts capture senior foot traffic from prescription pickup routines in secondary cities. |
| Rechargeable Battery Supply Agreement | Lithium-ion cell procurement contracts with South Korean suppliers anchor manufacturing scale for private-label transitions. |
| EU MDR CE Marking Pathway | Notified body submission preserves German statutory health insurance reimbursement access for in-the-ear configurations. |
| Bluetooth Smartphone Integration | iOS and Android hearing accessibility APIs position amplifiers as wireless audio peripherals for streaming-media households. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, and Medicare reimbursement databases, complemented by interviews with audiology clinic directors, biomedical engineers at hearing device manufacturers, pharmacy retail category managers, and teleaudiology platform developers. Secondary sources included CMS Medicare claims data, hospital procurement databases, and customs records for component trade flows. Bottom-up unit shipment estimates triangulated against top-down spending analysis across the projection horizon.
Cross-referencing historical adoption curves with panel input from industry stakeholders shaped the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-user demographic, and distribution channel configuration. CAGRs derived from fitted growth curves incorporating rechargeable battery replacement cycle compression and FDA OTC regulatory acceleration. Forecast inputs captured aging demographic trajectories in United States, German, and Japanese markets alongside semiconductor supply availability assumptions.
Several conditions sit outside the modeled scope, including sudden FDA reclassification of amplification devices, geopolitical disruption of Taiwanese foundry operations, and Medicare reimbursement expansion to cover OTC categories. Forecasts reflect documented assumptions on regulatory stability and supply chain continuity. Deviation in FDA enforcement posture on direct-to-consumer marketing claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
ENT Disorder Treatment Market
ENT
Global Audiological Devices Market
ENT
Nasal Polyps Treatment Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Surgical ENT Devices Market
ENT
Global Sinusitis Treatment Market
ENT
Global ENT Workstations Market
ENT
Interventional ENT Devices Market
ENT
ENT Examination Chair Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
North America Hearing Aid Market
ENT
Acute Sinusitis Market
ENT
Electrolarynx Market
ENT
Denmark Hearing Aids Market
ENT
Hearing Implants Market