
 Surgical Amniotics Market | 2026-2036
Surgical Amniotics Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Amniotics Market Insights
Asset-light leasing models for biologic tissue processing equipment is reconfiguring capital requirements for mid-sized competitors entering the Surgical Amniotics Market. MiMedx Group leverages its vertically integrated tissue bank network to sustain cost advantages across membrane preparation. Smith & Nephew competes through its established orthobiologics distribution infrastructure in North American hospital systems. Organogenesis Holdings differentiates by specializing in living cell-based therapies adjacent to amniotic product lines.
Surgical amniotics comprise preserved human amniotic membrane and fluid derivatives, typically dehydrated or cryopreserved at thicknesses of 20–100 microns for grafting applications in soft tissue repair. These biologic materials function primarily as natural scaffolds that reduce inflammation and promote epithelialization during wound healing procedures. Amniotic membrane products lead the product type landscape due to established reimbursement codes and surgical familiarity, while amniotic matrix formulations represent the fastest-growing segment as clinicians seek three-dimensional graft options for complex defects. Within therapy areas, wound care applications anchor current volume, though orthopedics commands premium pricing for sports medicine interventions.
The FDA's HCT/P regulations under 21 CFR Part 1271 govern product classification, while the EMA's Advanced Therapy Medicinal Products framework shapes European market access requirements. ISO 13485 quality management standards and AATB accreditation protocols further constrain supplier eligibility, effectively filtering market participants by compliance capability. Stakeholders must monitor evolving FDA guidance on minimal manipulation criteria, as reclassification decisions could reshape competitive boundaries for existing product portfolios.
Market Dynamics
Minimal manipulation criteria under 21 CFR Part 1271 are bifurcating the Surgical Amniotics Market into HCT/P-compliant tissue processors and manufacturers facing biologics license application requirements. This regulatory pressure concentrates competitive advantage among vertically integrated tissue banks with established AATB accreditation.
Growth Catalysts
- Orthopedic surgical center expansion:Ambulatory facilities in the American Southwest are integrating amniotic grafts into outpatient tendon repair protocols, reducing hospital admission costs while accelerating patient recovery timelines.
- FDA's HCT/P pathway:The 21 CFR Part 1271 framework permits streamlined market entry for minimally manipulated amniotic membrane products, bypassing lengthy premarket approval processes required for cellular therapies.
- Dehydrated membrane technology:Room-temperature stable graft formats eliminate cold chain logistics burdens, enabling distribution through standard medical supply channels rather than specialized biologics couriers.
Market Restraints
- Donor tissue supply concentration:AATB-accredited tissue banks cluster in the United States, creating geographic dependency for international manufacturers seeking compliant raw material sourcing.
- Reimbursement code fragmentation:CMS coding variability across Medicare Administrative Contractors creates payment uncertainty for wound care applications, particularly in non-hospital settings.
- Synthetic scaffold substitution:Polymer-based wound matrices from collagen and hyaluronic acid competitors offer standardized pricing and unlimited supply scalability absent donor constraints.
Strategic Opportunities
- Three-dimensional matrix formulations:Amniotic-derived hydrogels and particulate grafts address complex defect geometries inaccessible to standard membrane sheets, opening orthopedic and dental surgical applications.
- EMA ATMP framework navigation:Early engagement with European regulators on combined product classification could secure first-mover positioning in living cell-amniotic hybrid therapies.
- Direct-to-physician digital platforms:E-commerce channels targeting sports medicine specialists bypass traditional orthobiologics distributor markups, capturing margin previously allocated to middlemen.
Industry Challenges
- AATB accreditation bottlenecks:Tissue bank certification timelines extend 18-24 months, constraining capacity expansion for processors seeking to enter the amniotic supply chain.
- Cryopreservation infrastructure capex:Controlled-rate freezers and liquid nitrogen storage systems require substantial capital deployment, disadvantaging smaller entrants against established tissue bank networks.
- Minimal manipulation interpretation variance:Evolving FDA guidance on processing thresholds creates compliance uncertainty, forcing portfolio reconfiguration as classification boundaries shift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Amniotics Market |
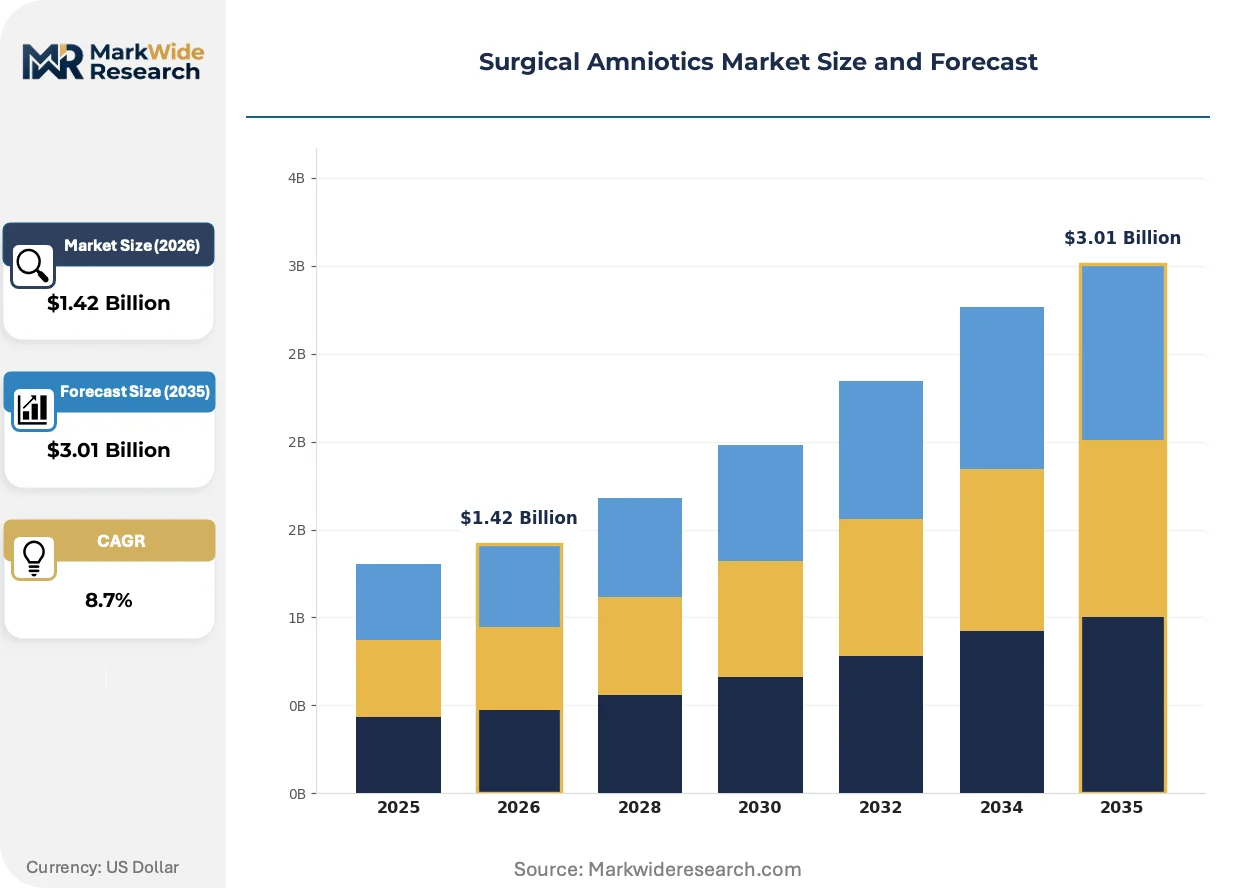
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amniotic Membrane, Amniotic Fluid, Amniotic Matrix, Amniotic Patch Therapy Area: Orthopedics, Ophthalmology, Wound Care, Cosmetic Surgery Application: Tissue Regeneration, Surgical Repair, Reconstruction, Pain Management End User: Hospitals, Clinics, Surgical Centers, Research Institutions |
| Companies Covered | MiMedx Group, Smith & Nephew, Organogenesis Holdings, Integra LifeSciences, Stryker, Amnio Technology, Skye Biologics, Applied Biologics, Amniox Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Amniotics Market Trends and Innovations
Digital traceability systems and advanced processing methods are compressing quality assurance cycles while expanding the addressable surgical population for amniotic-derived grafts. These developments are restructuring competitive requirements around data infrastructure rather than tissue procurement scale alone.
Blockchain-enabled chain-of-custody platforms is digitizing donor traceability from collection through implantation, creating immutable records that satisfy both FDA donor eligibility documentation and hospital risk management requirements. Large academic medical centers in California and Texas are piloting these systems for high-volume orthopedic programs. The technology is compressing audit preparation timelines from weeks to hours while reducing liability exposure from documentation gaps.
EMA's Advanced Therapy Medicinal Products framework is reclassifying certain amniotic fluid-derived formulations as combination products, triggering centralized marketing authorization requirements that favor multinational manufacturers with established European regulatory affairs capabilities. German and French notified bodies are interpreting cell viability thresholds inconsistently, fragmenting market access timelines across member states. Manufacturers with existing ATMP experience are accelerating MDR technical documentation preparation to capture specialist hospital accounts.
Hospital value analysis committees are consolidating vendor rosters for biologic grafts, replacing individual surgeon preference cards with system-level contracts tied to episode-of-care outcomes data. Integrated delivery networks in Florida and Arizona are implementing this consolidated sourcing for outpatient wound care centers. The shift concentrates purchasing volume among three to four suppliers per metropolitan area, elevating clinical evidence requirements for contract retention.
Surgical Amniotics Market Segmentation
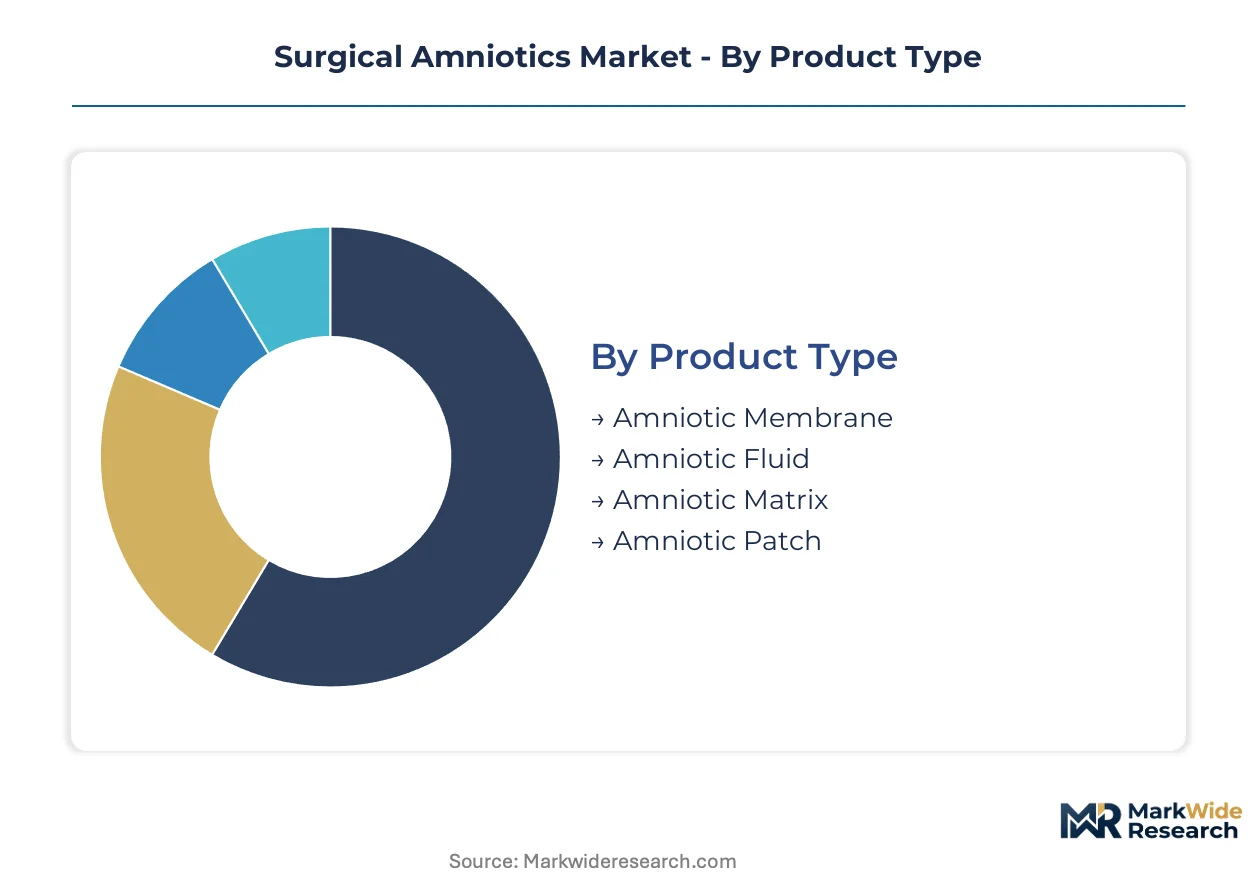
Surgical amniotics segment along four dimensions that determine reimbursement pathways, regulatory classification, and procurement channel selection. Each category reflects distinct clinical workflows and capital intensity requirements that reshape vendor competitive priorities.
Product Type:
Product formats span preserved membrane sheets to injectable fluid preparations, with processing complexity dictating shelf stability and distribution economics.
- Amniotic Membrane:Dehydrated or cryopreserved sheets measuring 20–100 microns thickness serve as natural scaffolds for epithelialization. Hospital wound care departments in Texas and Arizona account for concentrated procurement volume, driven by established CPT reimbursement codes and surgeon familiarity with graft handling protocols.
- Amniotic Matrix:Three-dimensional hydrogel and particulate formulations address complex defect geometries in orthopedic tendon repair. Ambulatory surgical centers across the American Southwest are expanding adoption for outpatient sports medicine procedures, displacing synthetic alternatives in rotator cuff and Achilles interventions.
- Amniotic Fluid:Injectable preparations derived from processed amniotic fluid support soft tissue regeneration through cytokine and growth factor content.
- Amniotic Patch:Pre-cut membrane configurations sized for specific anatomical applications reduce operative preparation time in ophthalmic and dental surgeries.
The dominant share belongs to Amniotic Membrane, while Amniotic Matrix is closing the gap fastest.
Therapy Area:
Therapeutic focus determines pricing power, with orthopedic applications commanding premium positioning against commoditized wound care segments.
- Orthopedics:Sports medicine applications leverage amniotic grafts for tendon and ligament repair, with procedures concentrated in outpatient surgical centers. Florida and California healthcare systems are consolidating vendor contracts around episode-of-care outcomes data, elevating clinical evidence requirements for contract retention.
- Wound Care:Diabetic foot ulcer and burn applications anchor current procedural volume, though CMS coding variability across Medicare Administrative Contractors creates payment uncertainty in non-hospital settings.
- Ophthalmology:Corneal repair and ocular surface reconstruction utilize thin membrane grafts for epithelial defect coverage.
- Cosmetic Surgery:Aesthetic applications for scar revision and facial rejuvenation represent emerging demand with limited reimbursement coverage.
Orthopedics captures the highest average selling prices, while Wound Care maintains the largest procedure count.
Application:
Clinical use cases range from structural repair to biologic modulation, with functional claims shaping FDA classification pathways.
- Surgical Repair:Direct grafting applications in tendon, ligament, and fascial reconstruction dominate current utilization. Academic medical centers in California are piloting blockchain-enabled chain-of-custody systems for high-volume orthopedic programs, compressing audit preparation timelines.
- Tissue Regeneration:Scaffold-mediated healing applications emphasize extracellular matrix deposition and angiogenesis. The FDA's minimal manipulation criteria under 21 CFR Part 1271 govern whether products qualify for streamlined HCT/P classification or face biologics license application requirements.
- Reconstruction:Complex defect coverage in dental and maxillofacial procedures utilizes three-dimensional matrix formulations.
- Pain Management:Anti-inflammatory applications leverage amniotic fluid cytokine profiles for joint injection therapies.
Surgical Repair generates the majority of current revenue, though Tissue Regeneration is expanding most quickly as processing technologies advance.
End User:
Procurement authority concentrates in integrated delivery networks and ambulatory facility chains, displacing individual surgeon preference-based purchasing.
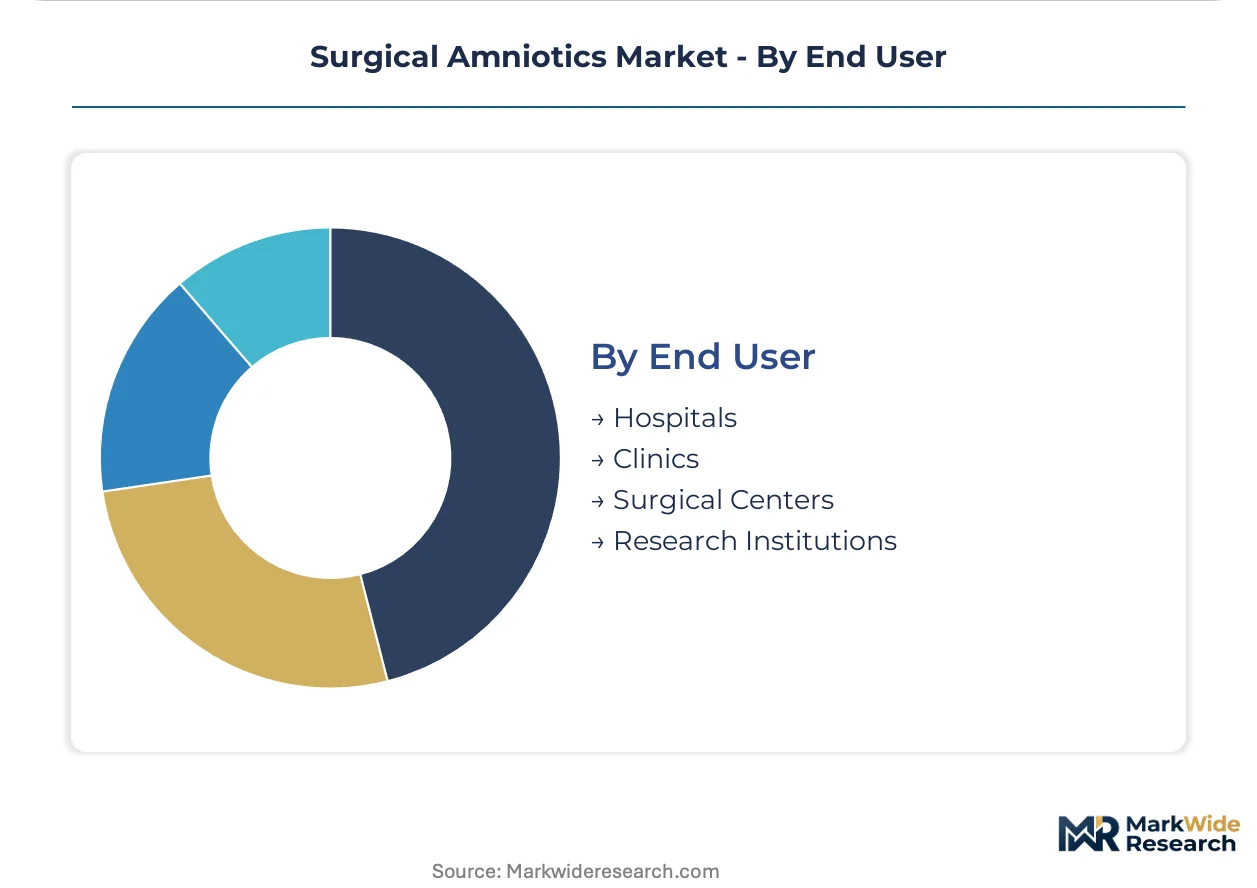
- Hospitals:Inpatient surgical departments and affiliated wound care centers maintain bulk purchasing agreements with tiered pricing tied to volume commitments. Value analysis committees in Florida hospital systems are consolidating vendor rosters to three or four suppliers per metropolitan area.
- Surgical Centers:Ambulatory facilities in the American Southwest cluster around major metropolitan hospital systems, integrating amniotic grafts into outpatient protocols to reduce admission costs and accelerate recovery timelines.
- Clinics:Office-based wound care and pain management practices drive demand for room-temperature stable graft formats that eliminate cold chain logistics.
- Research Institutions:Academic medical centers pilot novel applications and generate clinical evidence for commercial expansion.
Hospitals retain the largest procurement volume, while Surgical Centers are gaining share fastest through outpatient procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's HCT/P pathway under 21 CFR Part 1271 has concentrated amniotic tissue processing infrastructure in the United States, while EMA's ATMP framework creates divergent compliance requirements across European markets. Reimbursement variability and tissue bank accreditation standards further fragment regional competitive dynamics.
United States
Orthopedic surgical centers in Texas and Arizona are expanding outpatient tendon repair protocols using dehydrated membrane grafts. The FDA's minimal manipulation criteria govern whether products qualify for streamlined HCT/P classification or face biologics license application requirements. AATB-accredited tissue banks cluster in the American Southwest, supplying raw material to membrane processors nationwide.
Germany
Specialist hospital accounts in Bavaria and North Rhine-Westphalia are piloting combined cell-amniotic hybrid therapies under early EMA engagement. The MDR technical documentation requirements favor manufacturers with existing ATMP regulatory affairs capabilities. Notified bodies in Berlin and Munich are interpreting cell viability thresholds inconsistently, fragmenting market access timelines.
United Kingdom
NHS value analysis committees are consolidating vendor rosters for biologic grafts around episode-of-care outcomes data. The MHRA's post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining certain approval pathways. London academic medical centers are piloting blockchain-enabled chain-of-custody systems for high-volume orthopedic programs.
Switzerland
Swissmedic's centralized marketing authorization requirements attract multinational manufacturers seeking premium-market positioning. The country's reimbursement framework for advanced wound care products supports pricing premiums for dehydrated membrane formats. Basel and Zurich hospital systems are implementing consolidated sourcing for outpatient wound care centers.
Japan
PMDA's regenerative medicine regulatory framework is evaluating amniotic-derived products under accelerated approval pathways for rare indications. Sports medicine specialists in Tokyo and Osaka are adopting three-dimensional matrix formulations for rotator cuff repair. METI's industrial policy supports domestic tissue processing infrastructure development.
Surgical Amniotics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Vertically integrated tissue banks with AATB accreditation hold procurement advantages through captive supply of compliant raw materials. Three strategic archetypes dominate: membrane processors leveraging dehydration technology, matrix formulators targeting orthopedic applications, and fluid-derived product specialists navigating injectable regulatory pathways. Competitive moves concentrate on backward integration into tissue bank networks and direct-to-physician digital platform deployment.
Within the integrated tissue bank tier, MiMedx Group and Smith & Nephew exemplify contrasting approaches to supply chain control. MiMedx Group represents the vertically integrated archetype with in-house membrane preparation capabilities, while Smith & Nephew occupies a position leveraging established orthobiologics distribution infrastructure. Organogenesis Holdings anchors the living cell-based therapy adjacent segment, sitting within the specialist tier that differentiates through cellular product expertise rather than amniotic membrane scale.
| Leading Market Players |
|---|
| MiMedx Group |
| Smith & Nephew |
| Organogenesis Holdings |
| Integra LifeSciences |
| Stryker |
| Amnio Technology |
| Skye Biologics |
| Applied Biologics |
| Amniox Medical |
| Others |
Pricing and Supply Chain Analysis
AATB-accredited tissue banks in Texas and Arizona control raw membrane supply, translating donor tissue scarcity into premium pricing power for dehydrated graft formats across outpatient surgical networks.
Pricing Analysis
Certification level (FDA HCT/P-grade versus biologics license pathway) creates the primary spread between streamlined market entry and capital-intensive approval timelines. Three-tier pricing structure across premium cryopreserved, standard dehydrated, and economy particulate formats stratifies by shelf stability and handling complexity. Cost compression in the economy tier is intensifying because synthetic scaffold competitors offer unlimited supply scalability. Ambulatory surgical centers exhibit highest price sensitivity due to episode-of-care budget constraints, while academic medical centers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Contract manufacturing for membrane processing concentrates among AATB-accredited tissue banks in the United States, with secondary capacity emerging in Germany and Switzerland for European market access. Raw material sourcing draws from hospital-based donor collection networks, cryopreservation infrastructure, and specialized biologics couriers. Single-source vulnerability runs through the geographic clustering of accredited tissue banks in the American Southwest. Distribution runs through orthobiologics distributors and direct-to-physician digital platforms targeting sports medicine specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Surgical Amniotics Market rewards participants who control accredited tissue supply and navigate FDA minimal manipulation criteria, with AATB certification serving as the critical bottleneck asset.
For Market Incumbents: Build regulatory data moats by deepening clinical evidence portfolios for orthopedic outcomes and securing exclusive tissue bank partnerships. Defensive priorities center on locking in AATB-accredited supply agreements before certification timelines extend further, while expanding dehydration technology capacity to displace cryopreserved alternatives in ambulatory settings. Synthetic scaffold substitution from polymer-based competitors threatens commoditized wound care segments, elevating the urgency of orthopedic premium positioning. For New Entrants and Emerging Players: Establish a beachhead in three-dimensional matrix formulations for complex tendon defects, where clinical unmet need outpaces incumbent R&D focus. White-space targets include amniotic-derived hydrogels for dental maxillofacial reconstruction and direct-to-physician digital platforms bypassing traditional distributor markups. The most penetrable entry point sits in sports medicine ambulatory centers in Florida and California, where consolidated vendor contracts have not yet fully closed. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA HCT/P pathway advantages concentrate returns among vertically integrated tissue processors with captive supply. Acquisition targets should display AATB accreditation, established hospital GPO contracts, and dehydration technology infrastructure. The signal to watch is evolving FDA guidance on minimal manipulation thresholds, which could reclassify existing product portfolios and reshape competitive boundaries abruptly.| Strategic Initiative | Industry Significance |
|---|---|
| AATB Accreditation Investment | Eighteen-month certification timelines filter competitors and secure compliant raw material access. |
| Dehydration Technology Scale-Up | Room-temperature stability eliminates cold chain costs and expands ambulatory surgical center reach. |
| Hospital System Partnership | Integrated delivery network contracts in Florida and Arizona consolidate purchasing volume among select suppliers. |
| Direct-to-Physician Platform | E-commerce channels capture margin previously allocated to orthobiologics distributor intermediaries. |
| EMA ATMP Early Engagement | European regulatory affairs capabilities secure first-mover positioning in living cell-amniotic hybrid therapies. |
Research Methodology
The analysis maps amniotic membrane, matrix, fluid, and patch sub-sectors, each validated through interviews with tissue bank operations directors, orthopedic surgeons, hospital procurement managers, and regulatory affairs specialists. Primary fieldwork combined with secondary validation from FDA 510(k) filings, AATB accreditation databases, CMS reimbursement code repositories, and hospital GPO contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue assessments across the analysis window.
Assumptions held regulatory classification pathways and reimbursement stability constant while varying orthopedic procedure migration rates and synthetic substitution elasticity. Segmentation dimensions modeled include product format, therapy area, application function, and end-user facility type. CAGRs derived from logarithmic trend fitting across historical volume data and elasticity-adjusted adoption curves, with inputs including ambulatory surgical center expansion rates and AATB accreditation pipeline visibility.
Stress conditions across FDA reclassification probability, donor tissue supply disruption, and synthetic scaffold pricing aggression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding minimal manipulation criteria stability and Medicare Administrative Contractor coding convergence. Quarterly review of FDA guidance releases, AATB accreditation queue depth, and hospital value analysis committee vendor consolidation velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Global Hemostats Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Ultrasound Conductivity Gels Market