
 Medical Bionic Implant/Artificial Organs Market | 2026-2036
Medical Bionic Implant/Artificial Organs Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Bionic Implant/Artificial Organs Market Analysis
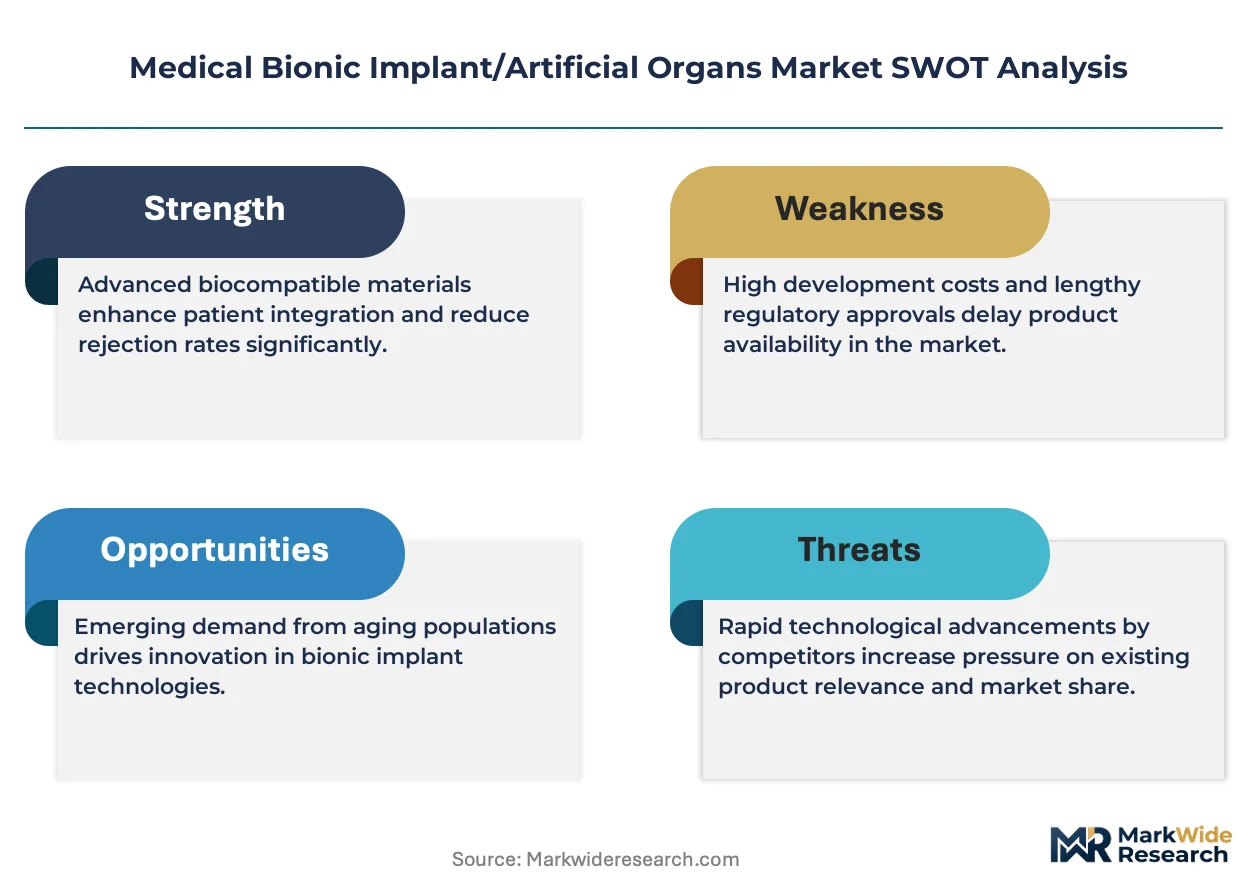
A shortage of certified biomedical engineers specializing in neuro-electrode interfaces is unwinding near-term manufacturing capacity across the sector. Medtronic plc leverages its integrated cardiac rhythm management infrastructure to sustain leadership in implantable pulse generators. Boston Scientific Corporation anchors its competitive position through deep specialization in spinal cord stimulation systems. Zimmer Biomet Holdings Inc. competes aggressively in orthopedic bionics with advanced myoelectric prosthetic platforms.
Medical bionic implants and artificial organs comprise electromechanical devices and engineered biological constructs that replace or augment native physiological functions, typically incorporating platinum-iridium electrode arrays, titanium housings, and hermetic ceramic feedthroughs sealed under inert atmosphere. These systems restore motor, sensory, or metabolic capacity in patients with irreversible organ failure or traumatic injury. Cardiac implants command the largest revenue pool due to established reimbursement and repeat intervention requirements, while neural prosthetics represent the fastest-expanding segment driven by brain-computer interface breakthroughs. Bioelectronics technology captures disproportionate R&D investment relative to its current revenue contribution, signaling future margin migration toward closed-loop neuromodulation systems.
FDA premarket approval pathways, EU MDR technical documentation requirements, and ISO 14708 active implantable device standards collectively elevate barriers to market entry while accelerating consolidation among well-capitalized manufacturers. Japan's PMDA Sakigake designation system compresses review timelines for novel bionic devices, redirecting early commercialization flows toward Tokyo and Osaka medical centers. Stakeholders must monitor reimbursement parity between bionic restoration and conventional surgical intervention as the decisive variable for category penetration.
Market Dynamics
FDA breakthrough device designations and EU MDR compliance timelines are compressing product development cycles while concentrating manufacturing among vertically integrated suppliers with captive regulatory affairs capabilities. This structural acceleration favors incumbents with established quality management systems and predicate device portfolios.
Growth Catalysts
- PMDA Sakigake designation:Japan's accelerated review pathway redirects early commercialization flows toward Tokyo and Osaka medical centers, compressing time-to-revenue for novel neural prosthetics.
- Brain-computer interface breakthroughs:Electrocorticography electrode arrays with platinum-iridium interfaces are expanding addressable populations beyond spinal cord injury to stroke rehabilitation.
- Aging hospital populations:Cardiac rhythm management device replacement cycles are shortening as implantable pulse generator battery depletion intersects with extended patient longevity.
Market Restraints
- Platinum-iridium supply concentration:Electrode array feedstock dependence on South African and Russian mining operations creates input cost volatility and forced substitution risk.
- ISO 14708 certification timelines:Active implantable device standard compliance requires 18-24 month validation cycles that structurally delay market entry for mid-cap manufacturers.
- Biomedical engineer scarcity:Neuro-electrode interface specialization shortages constrain manufacturing capacity expansion regardless of capital availability.
Strategic Opportunities
- Closed-loop neuromodulation convergence:Integration of sensing electrodes with adaptive algorithms creates margin migration toward autonomous therapeutic adjustment systems.
- Myoelectric prosthetic platforms:Pattern recognition control systems are opening upper-limb restoration applications previously served by passive mechanical devices.
- Reimbursement parity expansion:Germany's Diagnosis-Related Group recalibration for bionic restoration versus conventional surgical intervention unlocks category penetration in orthopedic segments.
Industry Challenges
- Hermetic ceramic feedthrough validation:Titanium housing-to-ceramic bonding integrity testing requires specialized vacuum furnace infrastructure that concentrates production among three qualified suppliers.
- EU MDR technical documentation:Clinical evidence requirements for legacy device recertification are diverting R&D resources toward compliance rather than next-generation platform development.
- Neural signal processing talent:Firmware engineers with real-time biosignal filtering expertise command premium compensation that erodes project economics for mid-stage developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Bionic Implant/Artificial Organs Market |
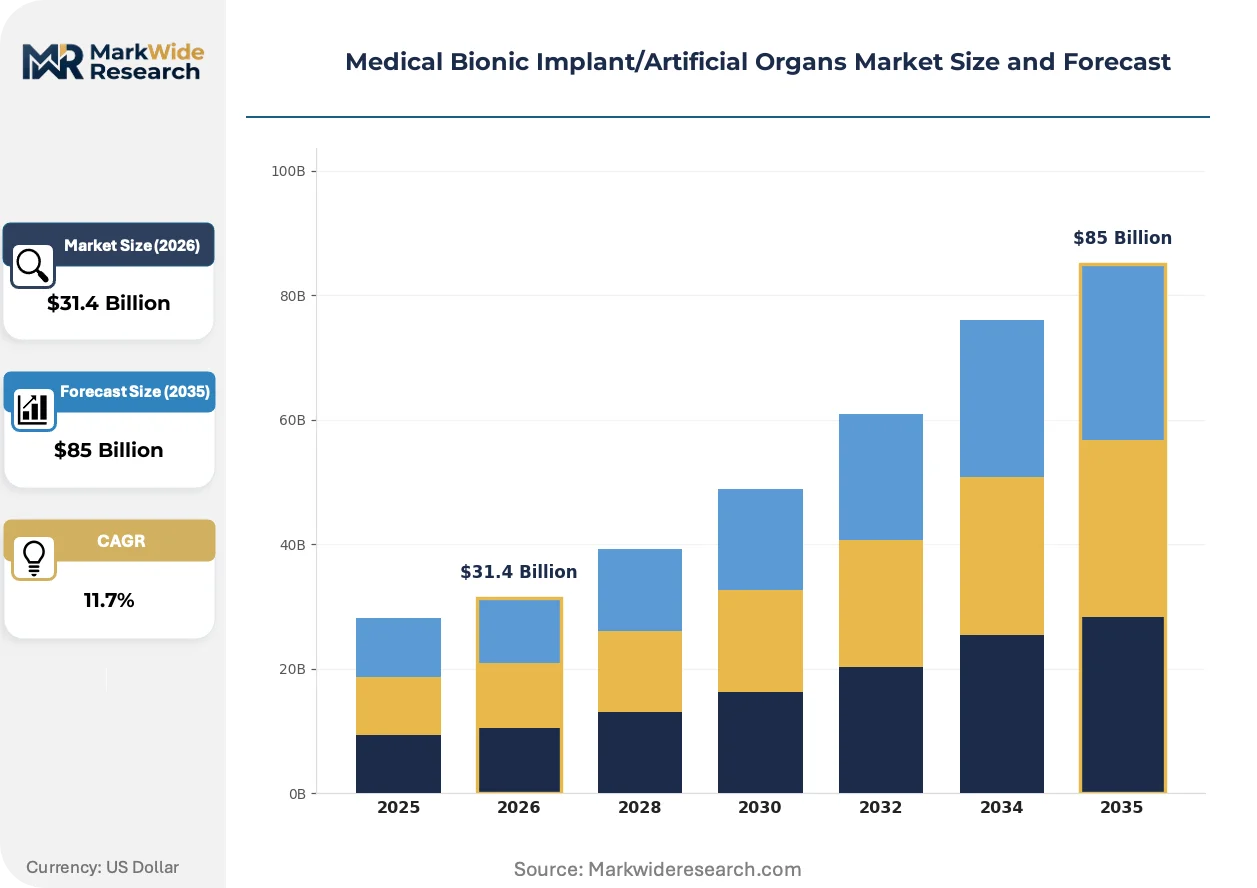
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Cochlear Implants, Neural Prosthetics, Orthopedic Implants Technology: Bioelectronics, Biocompatible Materials, 3D Printing, Wireless Communication Application: Organ Replacement, Pain Management, Sensory Rehabilitation, Mobility Assistance End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Research Institutions |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Zimmer Biomet Holdings Inc., Edwards Lifesciences Corporation, Cochlear Ltd., Ekso Bionics Holdings Inc., Abiomed Inc., Ottobock SE & Co. KGaA, Berlin Heart GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Bionic Implant/Artificial Organs Market Emerging Trajectories
Bioelectronics technology captures disproportionate R&D investment relative to current revenue contribution, signaling a fundamental reallocation of technical resources toward electrochemical sensing and closed-loop therapeutic delivery.
Platinum-iridium alloy electrodes with sputtered iridium oxide coatings are displacing pure platinum interfaces in deep brain stimulation applications. Academic medical centers in the United States are adopting these modified arrays at twice the pace of community hospitals. This materials transition is displacing legacy electrode suppliers lacking thin-film deposition capabilities and compressing procurement cycles toward single-source qualification agreements.
EU MDR technical documentation requirements for active implantable devices now mandate post-market clinical follow-up studies with five-year surveillance horizons. Manufacturers must establish European Authorized Representatives with liability exposure, consolidating regulatory affairs functions among larger corporate entities. Cardiac implant segments face the steepest compliance cost escalation as predicate device pathways narrow and notified body capacity concentrates in Germany and the Netherlands.
Hospital procurement committees are consolidating vendor relationships for implantable pulse generators around integrated cardiac rhythm management portfolios. Independent sales representatives for spinal cord stimulation systems are losing access to catheterization laboratory purchasing authority as integrated delivery networks centralize contracting. This concentration is most visible in Japan, where university hospital alliances in Tokyo and Osaka have reduced qualified neural prosthetic suppliers from twelve to four over three years.
Medical Bionic Implant/Artificial Organs Market Segmentation
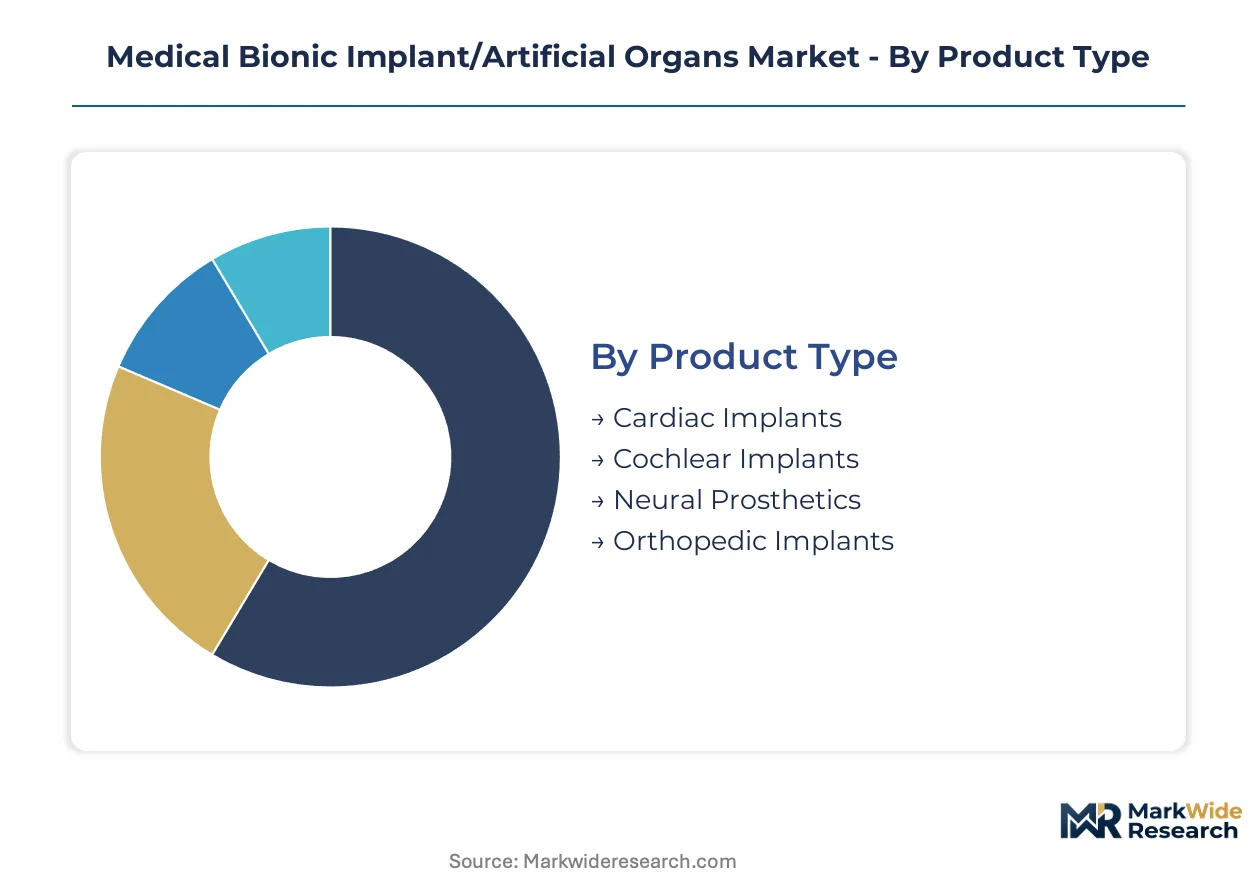
Medical bionic implant segmentation reveals divergent substitution pressures across therapeutic domains. Cardiac rhythm management devices face entrenched competition from pharmacological alternatives, while neural prosthetics encounter limited functional substitutes for spinal cord injury restoration.
Product Type:
Cardiac implants confront the most acute substitution pressure from catheter ablation and pharmaceutical rhythm control, whereas neural prosthetics operate in near-monopoly positions for motor restoration.
- Cardiac Implants:Implantable pulse generators and cardiac resynchronization therapy devices incorporate lithium-iodine batteries and titanium housings. Demand concentrates in United States academic medical centers where extended patient longevity accelerates replacement cycles. Reimbursement parity with surgical intervention determines category penetration.
- Neural Prosthetics:Brain-computer interfaces and spinal cord stimulation systems deploy platinum-iridium electrode arrays with hermetic ceramic feedthroughs. Adoption clusters in German university hospitals following EU MDR recertification of predicate devices. FDA breakthrough designations compress development timelines for stroke rehabilitation applications.
- Cochlear Implants:Multichannel electrode arrays stimulate auditory nerve fibers through transcutaneous inductive coupling.
- Orthopedic Implants:Myoelectric prosthetic platforms integrate pattern recognition control systems for upper-limb restoration.
Cardiac implants retain volume leadership; neural prosthetics hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium bioelectronics platforms from commoditized biocompatible material supply.
- Bioelectronics:Closed-loop neuromodulation systems merge sensing electrodes with adaptive algorithms for autonomous therapeutic adjustment. R&D investment disproportionately concentrates here despite current revenue contribution. Japanese PMDA Sakigake designations redirect early commercialization toward Tokyo medical centers.
- Biocompatible Materials:Titanium alloys, platinum-iridium compositions, and medical-grade silicones form the structural substrate for all active implantables. Supply concentrates among three qualified suppliers with vacuum furnace infrastructure for hermetic ceramic feedthrough validation.
- 3D Printing:Patient-specific orthopedic bionics and surgical guides reduce operative time for complex reconstructions.
- Wireless Communication:Bluetooth Low Energy and proprietary inductive protocols enable remote device monitoring and parameter adjustment.
Bioelectronics commands premium pricing tiers; wireless communication is expanding most quickly through remote patient monitoring mandates.
Application:
Volume concentration in organ replacement reflects established reimbursement, while mobility assistance applications scale through pattern recognition breakthroughs.
- Organ Replacement:Artificial hearts, ventricular assist devices, and total artificial hearts restore circulatory function in end-stage heart failure. United States integrated delivery networks centralize procurement around cardiac rhythm management portfolios. Battery depletion intersects with patient longevity to shorten replacement intervals.
- Mobility Assistance:Myoelectric upper-limb prosthetics and exoskeleton platforms leverage surface electromyography for intuitive control. German Diagnosis-Related Group recalibration unlocks category penetration through reimbursement parity with conventional surgical intervention.
- Pain Management:Spinal cord stimulation and dorsal root ganglion therapy interrupt nociceptive signaling for chronic refractory conditions.
- Sensory Rehabilitation:Cochlear and retinal implants restore auditory and visual function through neural interface technology.
Organ replacement maintains revenue concentration; mobility assistance gains share fastest through myoelectric platform advancement.
End User:
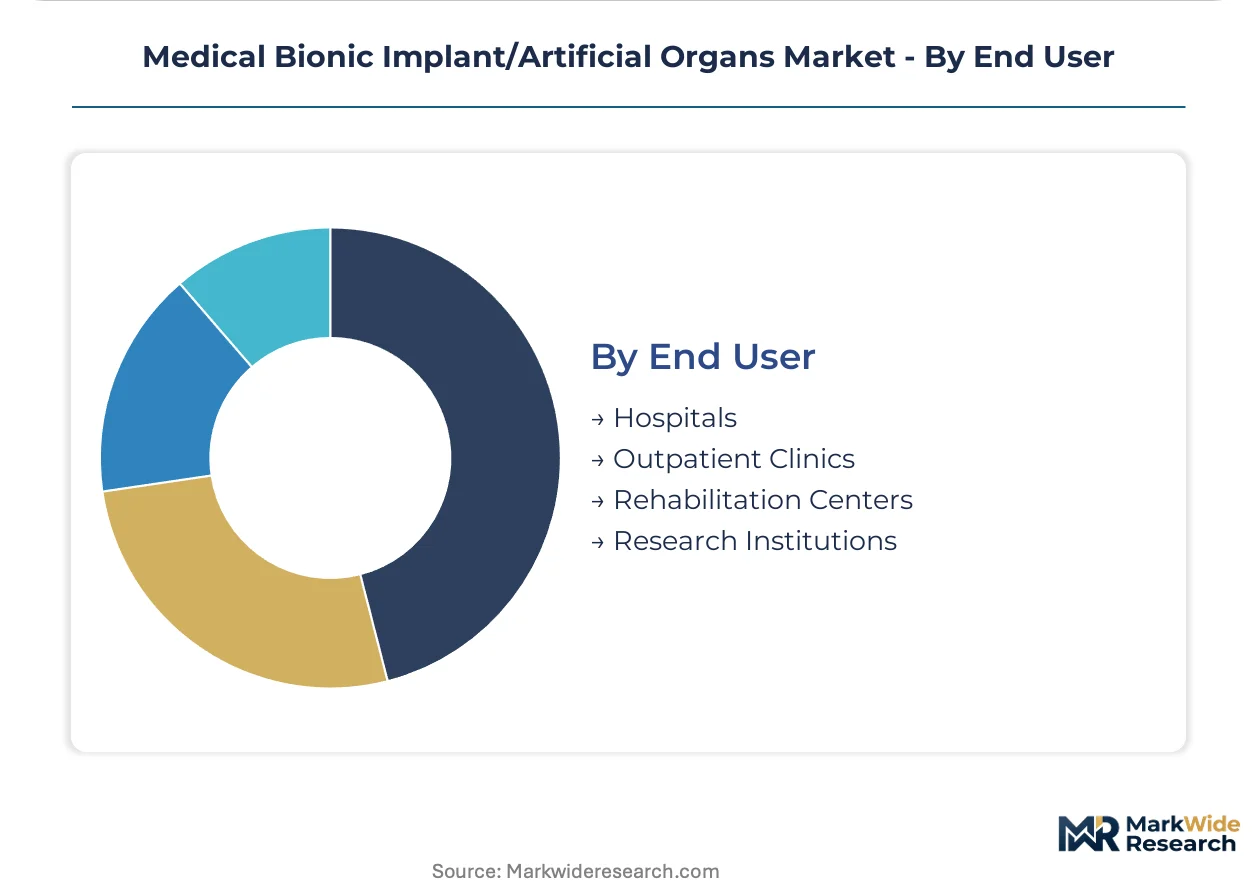
Procurement authority consolidation favors hospital-based volume concentration over fragmented outpatient channels.
- Hospitals:Academic medical centers and integrated delivery networks command catheterization laboratory purchasing authority for implantable pulse generators. Japan's university hospital alliances in Tokyo and Osaka reduced qualified neural prosthetic suppliers from twelve to four. EU MDR technical documentation requirements mandate five-year post-market surveillance.
- Rehabilitation Centers:Specialized facilities for spinal cord injury and stroke recovery drive adoption of brain-computer interface systems. Outpatient migration of device programming and follow-up care expands addressable site population.
- Outpatient Clinics:Independent cardiology and pain management practices perform generator replacements and parameter adjustments.
- Research Institutions:Academic medical centers conduct clinical trials for novel electrode materials and closed-loop algorithms.
Hospitals anchor procurement volume; rehabilitation centers are climbing the fastest as care migrates beyond acute settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography, while PMDA Sakigake designations in Japan and EU MDR compliance timelines in Germany reshape competitive positioning across the sector.
United States
Academic medical centers in Boston and the Research Triangle drive cardiac rhythm management procurement as integrated delivery networks centralize purchasing authority. FDA breakthrough device designations compress development timelines for neural prosthetics targeting stroke rehabilitation. Minneapolis and Framingham host concentrated manufacturing infrastructure for implantable pulse generators.
Germany
University hospital alliances in Munich and Heidelberg anchor EU MDR recertification activity for predicate neural prosthetic devices. Diagnosis-Related Group recalibration for bionic restoration versus conventional surgical intervention unlocks orthopedic segment penetration. The notified body capacity concentration in Berlin and Munich accelerates compliance cost escalation for cardiac implant segments.
Japan
PMDA Sakigake designation redirects early commercialization flows toward Tokyo and Osaka medical centers for novel brain-computer interface systems. Aging demographics intersect with extended patient longevity to shorten implantable pulse generator replacement intervals. The university hospital alliance consolidation reduced qualified neural prosthetic suppliers from twelve to four over three years.
Switzerland
Swissmedic oversight of active implantable medical devices concentrates quality management system certification among well-capitalized manufacturers with predicate device portfolios. Geneva and Zurich host specialized regulatory affairs capabilities serving EU MDR technical documentation requirements. Hermetic ceramic feedthrough validation infrastructure concentrates production among qualified suppliers in the Basel region.
Australia
TGA approval pathways for cochlear and retinal implants support sensory rehabilitation device commercialization from Sydney and Melbourne research clusters. Remote patient monitoring mandates expand wireless communication adoption through Bluetooth Low Energy protocols. The national prosthetics program reimbursement parity determines myoelectric platform penetration in upper-limb restoration.
Medical Bionic Implant/Artificial Organs Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cardiac rhythm management portfolios commanding catheterization laboratory purchasing authority. The specialist tier fragments across neural prosthetics, orthopedic bionics, and ventricular assist devices. Three archetypes dominate: diversified cardiovascular conglomerates, neuro-electrode interface specialists, and myoelectric prosthetic platform developers. Competitive moves concentrate on regulatory affairs capability acquisition and five-year post-market surveillance infrastructure buildout.
Among diversified cardiovascular conglomerates, Medtronic plc and Boston Scientific Corporation occupy positions anchoring integrated cardiac rhythm management infrastructure. Zimmer Biomet Holdings Inc. exemplifies the orthopedic bionics archetype with myoelectric prosthetic platform specialization. These three entities represent the tier capable of absorbing EU MDR compliance cost escalation while redirecting R&D resources toward closed-loop neuromodulation convergence.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Zimmer Biomet Holdings Inc. |
| Edwards Lifesciences Corporation |
| Cochlear Ltd. |
| Ekso Bionics Holdings Inc. |
| Abiomed Inc. |
| Ottobock SE & Co. KGaA |
| Berlin Heart GmbH |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month ISO 14708 certification timelines concentrate manufacturing among three qualified suppliers with captive vacuum furnace infrastructure, amplifying pricing power for hermetic ceramic feedthrough validation while compressing margins for mid-cap electrode array developers lacking backward integration into titanium housing production.
Pricing Analysis
United States academic medical centers pay premiums of 15-25% above German university hospital procurement levels for identical implantable pulse generator specifications, reflecting catheterization laboratory purchasing authority concentration and integrated delivery network vendor consolidation. Three-tier pricing structure across premium bioelectronics platforms, standard biocompatible material substrates, and economy-grade passive prosthetics separates FDA breakthrough-designated neural interfaces from EU MDR legacy recertification products. Cost compression in standard-tier biocompatible materials is intensifying because South African platinum-iridium feedstock volatility forces substitution toward sputtered iridium oxide coatings. Rehabilitation centers exhibit the highest price sensitivity due to Diagnosis-Related Group reimbursement constraints, while academic medical centers absorb premium pricing for closed-loop neuromodulation systems.
Supply Chain Analysis
Strait of Hormuz transit risk concentrates titanium sponge feedstock vulnerability for hermetic housing production, with three qualified suppliers in Germany, Switzerland, and the United States controlling vacuum furnace infrastructure for ceramic feedthrough validation. Platinum-iridium electrode arrays draw from South African mining operations and Russian refining capacity, with medical-grade silicone encapsulation anchored in Japanese and German chemical processing clusters. Single-source vulnerability in thin-film iridium oxide deposition equipment creates forced substitution risk for legacy electrode suppliers. Distribution runs through integrated delivery network centralized contracting in the United States, university hospital alliances in Japan, and GPO-mediated procurement in German orthopedic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as brain-computer interface breakthroughs redirect addressable populations from spinal cord injury toward stroke rehabilitation, compressing development timelines and expanding reimbursement eligibility for neural prosthetic platforms.
For Market Incumbents: Consolidate regulatory affairs capabilities through European Authorized Representative acquisition with liability exposure, defending against EU MDR compliance cost escalation that structurally disadvantages mid-cap competitors. Deepen backward integration into platinum-iridium electrode array manufacturing to offset South African feedstock volatility, while redirecting R&D resources from legacy device recertification toward closed-loop neuromodulation algorithm development.
For New Entrants and Emerging Players: Firmware engineering talent scarcity in real-time biosignal filtering creates immediate service-layer opportunity for contract algorithm development partnerships with mid-stage neural prosthetic developers. Target rehabilitation center outpatient migration for spinal cord stimulation programming services, penetrating through Bluetooth Low Energy remote monitoring capabilities that incumbent cardiac rhythm management portfolios under-serve. Pursue Japanese PMDA Sakigake designation pathway to compress time-to-revenue for novel electrocorticography applications.
For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because ISO 14708 certification infrastructure and five-year post-market surveillance databases compound competitive moats faster than R&D expenditure alone. Acquisition focus should center on neuro-electrode interface specialists with predicate device portfolios and existing notified body relationships in Germany or the Netherlands. Monitor reimbursement parity between bionic restoration and conventional surgical intervention as the decisive inflection signal for category penetration velocity in orthopedic and mobility assistance segments.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses premarket approval timelines for stroke rehabilitation neural interfaces targeting brain-computer integration. |
| EU MDR Technical Documentation Buildout | Establishes five-year post-market surveillance infrastructure mandatory for active implantable device recertification. |
| PMDA Sakigake Pathway Pursuit | Redirects early commercialization flows toward Tokyo and Osaka university hospital alliances for novel electrode arrays. |
| Hermetic Feedthrough Validation Investment | Captures vacuum furnace capacity concentration among three qualified suppliers for titanium-ceramic bonding integrity. |
| Closed-Loop Algorithm Development | Merges sensing electrodes with adaptive therapeutic adjustment systems, capturing disproportionate R&D margin migration. |
Methodological Framework
A spread of perspectives from biomedical engineers specializing in neuro-electrode interfaces, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads with EU MDR notified body experience converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filing databases, EU MDR technical documentation repositories, CMS Medicare reimbursement schedules, and Japanese PMDA Sakigake designation records. Bottom-up demand modeling across implantable pulse generator replacement cycles and top-down market sizing through cardiac rhythm management portfolio revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product type, technology platform, therapeutic application, and end-user procurement authority across the projection horizon. Analytical framework derived CAGRs through intersection of aging demographic penetration curves, reimbursement pathway maturation velocity, and regulatory timeline compression effects. Industry-specific forecast inputs incorporated platinum-iridium supply concentration risk premiums and biomedical engineer scarcity constraints on manufacturing capacity expansion.
Underlying assumptions cover FDA breakthrough designation sustain rates, EU MDR notified body capacity availability, and PMDA Sakigake review timeline compression, with deviation risk concentrated in platinum-iridium feedstock disruption and neural signal processing talent compensation inflation. Practitioners should keep alternative scenarios live as reimbursement parity negotiations between bionic restoration and conventional surgical intervention evolve across German, United States, and Japanese health technology assessment frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Europe C-Arms Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Oxygen Generator Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Transportable Ventilator Market