
 Global Medical Device Contract Manufacturing Market | 2026-2036
Global Medical Device Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Contract Manufacturing Market Outlook
Cleanroom capacity in Costa Rica and Malaysia is expanding as medical device contract manufacturers build FDA-registered facilities outside traditional high-cost zones. Jabil Inc. leverages vertical integration across plastics molding and final assembly to capture orthopedic device programs. Integer Holdings Corporation anchors cardiovascular catheter production through dedicated wire-forming and extrusion capabilities. Flex Ltd. competes on regulatory infrastructure, maintaining notified-body relationships across multiple EU member states.
Medical device contract manufacturing covers the outsourced production of finished instruments, subassemblies, and sterile components under the design owner’s regulatory filing, typically requiring ISO 13485 quality systems, validated processes, and traceable supply chains for patient-contacting products. Its primary purpose is to let OEMs convert fixed manufacturing overhead into variable costs while accessing specialized process technologies without capital deployment. Injection molding and CNC machining dominate current revenue contribution due to their applicability across diagnostics and surgical device housings, while 3D printing represents the fastest-growing technology segment as patient-specific orthopedic implants gain reimbursement traction. OEM end users command the largest contract value pools because they bundle design transfer, regulatory support, and scaled production under single-source agreements.
FDA quality system regulation and EU MDR frame product liability and post-market surveillance obligations, compelling contract manufacturers to maintain redundant regulatory staff across jurisdictions. ISO 13485 certification operates as a baseline market-access filter, with notified-body shortages in Europe extending supplier qualification timelines. China NMPA registration requirements for imported devices add a third compliance layer for brands serving that market. Stakeholders must monitor how FDA digital health pre-certification and EU AI Act risk classification reshape contract scope for software-enabled devices.
Market Dynamics
EU MDR compliance deadlines and FDA quality system intensification are compressing supplier qualification timelines while fragmenting manufacturing footprints across Costa Rica, Malaysia, and Eastern Europe.
Growth Catalysts
- EU MDR transition:Device OEMs accelerate outsourcing to contract manufacturers with notified-body relationships already established, bypassing 12-18 month qualification bottlenecks.
- 3D printing for patient-specific implants:Orthopedic device brands seek additive manufacturing partners as personalized implant reimbursement codes expand across US and German healthcare systems.
- Costa Rica cleanroom expansion:FDA-registered facilities in the San Jose corridor attract cardiovascular catheter programs seeking proximity to US markets without domestic labor costs.
Market Restraints
- Notified-body scarcity:European MDR designation backlogs extend supplier audit queues, freezing new program launches for mid-tier OEMs without existing partnerships.
- Specialized polymer feedstock concentration:Medical-grade PEEK and implantable-grade silicone supply concentrates among three German and US chemical suppliers, exposing contract manufacturers to input cost volatility.
- ISO 13485 certification timelines:Third-party audit capacity constraints stretch initial certification from six to fourteen months, blocking market entry for emerging contract manufacturers.
Strategic Opportunities
- Malaysia electronics-to-medical pivot:Existing semiconductor cleanroom infrastructure in Penang converts to FDA-registered device assembly, capturing diagnostic instrument programs relocating from China.
- Software-enabled device convergence:Contract manufacturers integrating embedded firmware validation capture digital health programs requiring combined hardware-software regulatory filings under FDA pre-certification pathways.
- Indian PLI scheme for medical devices:Domestic manufacturing incentives attract orthopedic implant assembly for export to Middle East and African markets underserved by established contract manufacturers.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization study backlogs at accredited laboratories delay design validation for implantable device programs.
- Design transfer documentation:OEM intellectual property protection protocols clash with contract manufacturer process validation requirements, extending technology transfer timelines.
- Multi-jurisdiction regulatory staffing:Simultaneous FDA, EU MDR, and China NMPA compliance requires redundant quality assurance headcount, compressing operating margins for mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Contract Manufacturing Market |
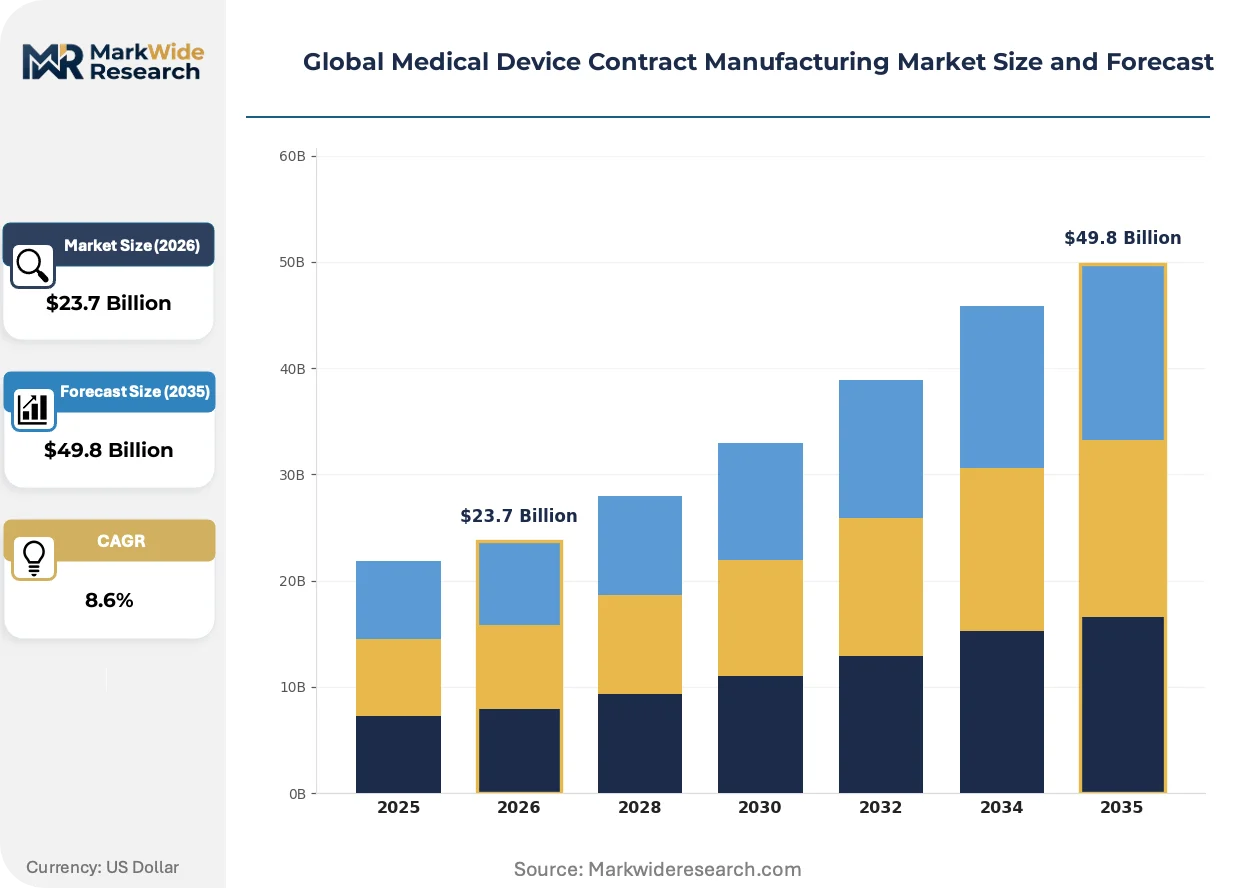
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Surgical Devices, Cardiovascular Devices, Orthopedic Devices Technology: Injection Molding, 3D Printing, CNC Machining, Laser Cutting End User: Hospitals, Clinics, Laboratories, OEMs Application: Therapeutic, Monitoring, Surgical, Rehabilitation |
| Companies Covered | Jabil Inc., Flex Ltd., Integer Holdings Corporation, Sanmina Corporation, TE Connectivity Ltd., Celestica Inc., Plexus Corp., Gerresheimer AG, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Contract Manufacturing Market Strategic Shifts
Process automation and digital thread technologies are compressing validation cycles while regulatory convergence around software-enabled devices redefines contract scope boundaries.
Continuous manufacturing is electrifying pharmaceutical-device combination product assembly, enabling real-time release testing that collapses batch validation from weeks to hours. Biologic delivery device OEMs in Massachusetts and Basel corridors adopt these lines fastest. The technology is electrifying competitive positioning for contract manufacturers with PAT-enabled infrastructure, separating them from batch-oriented competitors.
EU AI Act risk classification for software-as-medical-device is forcing contract manufacturers to embed algorithmic validation into quality systems previously focused on hardware. High-risk diagnostic imaging AI requires notified-body scrutiny of training data provenance and drift monitoring protocols. Cardiology software developers in Germany and France now prioritize contract partners with established AI quality management documentation.
Hospital procurement consolidation is compressing supplier tiers, with IDN-owned GPOs demanding single-source accountability across design, regulatory filing, and aftermarket service. This pattern concentrates contract value with vertically integrated manufacturers capable of absorbing liability across the full device lifecycle. The shift is most visible in US orthopedic and cardiovascular segments where health system mergers reduced qualified vendor pools by half.
Global Medical Device Contract Manufacturing Market Segmentation
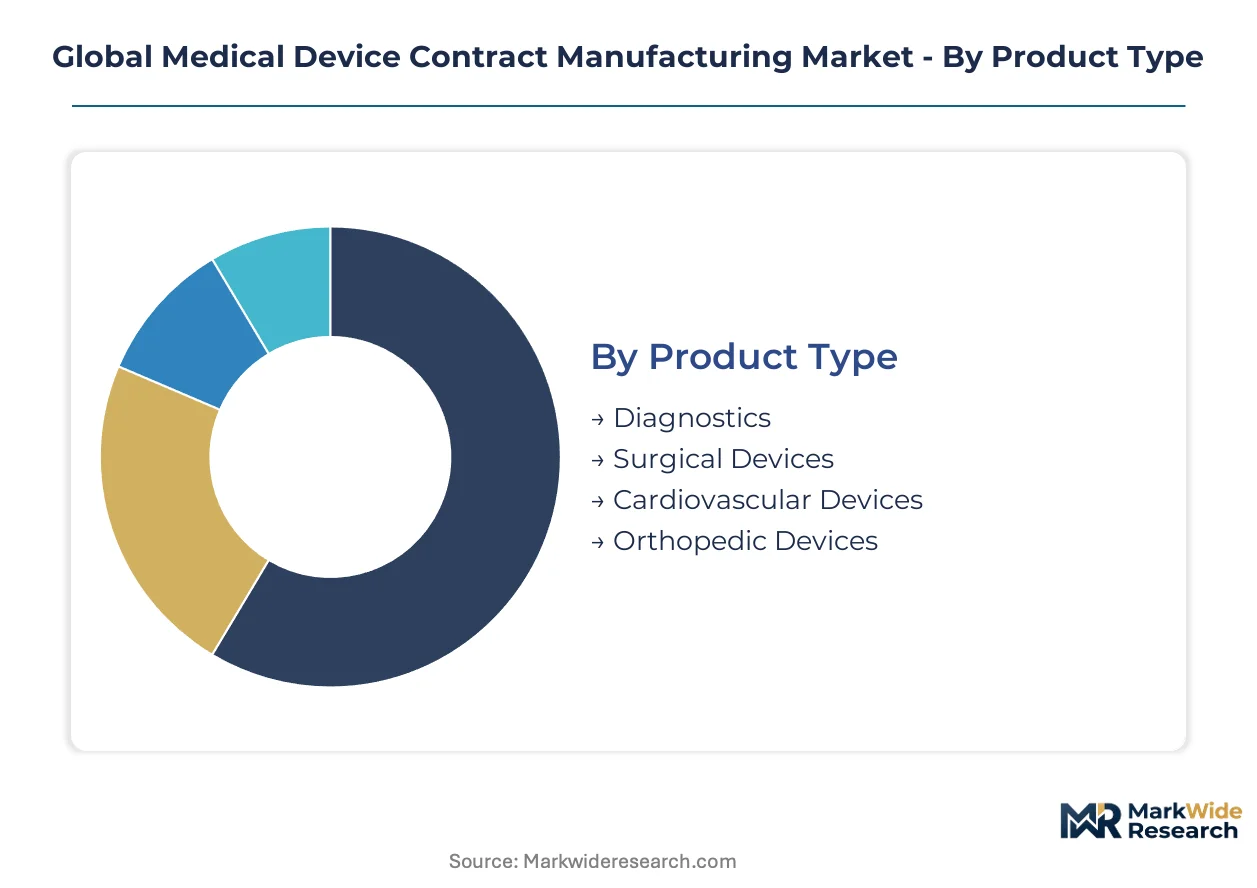
Medical device contract manufacturing segments diverge sharply in capital requirements, with cleanroom infrastructure and regulatory compliance systems creating steep barriers between commodity assembly and implantable device production. Understanding these structural divides reveals where contract manufacturers earn sustainable margins versus competing on volume.
Product Type:
Capital intensity peaks with implantable cardiovascular and orthopedic devices, where validated sterile processes and biocompatibility documentation demand multi-million-dollar facility investments before first revenue.
- Diagnostics:Reagent cassette and test strip assembly operates at lower capital thresholds, with modular cleanroom pods sufficient for most IVD programs. Demand concentrates in Massachusetts and California clusters where molecular diagnostic startups outsource entire manufacturing footprints to avoid FDA 510(k) facility inspections.
- Surgical Devices:Electrosurgical instruments and laparoscopic tool assemblies require precision metalworking validated to ISO 13485, with German and Chinese contract manufacturers capturing the bulk of reusable instrument programs through hardened steel supply relationships.
- Cardiovascular Devices:Catheter and stent delivery systems demand the highest per-square-foot capital deployment among all segments.
- Orthopedic Devices:Implantable joint and spine hardware requires titanium and PEEK machining capabilities with extensive biocompatibility testing documentation.
Surgical devices absorb the bulk of installed capacity; cardiovascular devices are expanding most quickly as electrophysiology and structural heart programs multiply.
Technology:
Process technology selection determines which contract manufacturers can bid on Class II versus Class III device programs, with additive manufacturing creating new qualification pathways previously closed to traditional subtractive shops.
- Injection Molding:Medical-grade thermoplastic and liquid silicone rubber molding dominates high-volume disposable production, with multi-cavity tooling amortized across millions of units. US and German molders with FDA-registered facilities capture insulin pen and inhaler device contracts through validated process control systems.
- 3D Printing:Powder-bed fusion and material extrusion for patient-specific cranial implants and surgical guides represent the steepest technology investment trajectory. German orthopedic brands now require contract partners with ISO/ASTM 52901 quality systems and traceable powder lots.
- CNC Machining:Titanium and cobalt-chrome milling for implantable hardware requires 5-axis centers with coolant filtration systems.
- Laser Cutting:Nitinol and stainless steel tube processing for stent and catheter shaft production demands femtosecond systems.
Injection molding retains the largest installed equipment base; 3D printing is gaining share fastest as personalized implant reimbursement expands.
End User:
Customer type shapes contract scope, with OEMs bundling design transfer and regulatory filing support while hospital procurement drives standardization and cost compression.
- OEMs:Device brands outsource complete manufacturing responsibility including design history file maintenance and post-market surveillance. US and EU MDR compliance requirements push mid-tier OEMs toward contract manufacturers with redundant notified-body relationships.
- Hospitals:IDN procurement consolidation demands single-source accountability across device lifecycle, favoring contract manufacturers with field service and refurbishment capabilities.
- Clinics:Outpatient surgical centers source reprocessed single-use devices through third-party sterilizers.
- Laboratories:Reference labs and pathology groups contract for custom consumable production at smaller volumes.
OEMs command the largest contract value pools; hospitals are consolidating supplier tiers fastest through GPO standardization mandates.
Application:
Application focus determines regulatory pathway complexity, with therapeutic devices facing the steepest clinical evidence requirements and monitoring devices shifting toward software-enabled validation.
- Therapeutic:Drug delivery and implantable stimulator programs require extensive biocompatibility documentation and sterilization validation. Swiss and Irish contract manufacturers anchor this segment through FDA and EMA dual-inspected facilities.
- Surgical:Powered and manual instrument production spans the widest capital intensity range from commodity kits to robotic surgery accessories.
- Monitoring:Wearable and implantable sensors integrate hardware-software validation under FDA digital health pre-certification.
- Rehabilitation:Prosthetic and orthotic device assembly operates at lower regulatory barriers with shorter design cycles.
Therapeutic applications absorb the most regulatory staffing investment; monitoring is climbing the fastest as remote patient monitoring reimbursement codes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer feedstock concentration in Germany and the United States anchors contract manufacturing investment decisions across three continents. FDA-registered cleanroom capacity clusters near Boston, San Jose, and Basel reduce supplier qualification timelines for cardiovascular catheter programs. EU MDR compliance costs and NMPA registration requirements reshape geographic expansion priorities for device OEMs.
United States
Minneapolis and Boston medical technology corridors concentrate electrophysiology catheter and orthopedic implant outsourcing demand. FDA 510(k) facility inspections and quality system regulation intensification push mid-tier OEMs toward established contract partners with redundant regulatory staff. Jabil Inc. and Integer Holdings Corporation anchor domestic capacity through vertically integrated plastics molding and wire-forming operations.
Germany
Freiburg and Tuttlingen surgical instrument clusters drive precision metalworking demand for reusable laparoscopic tools. EU MDR notified-body relationships and CE marking infrastructure attract cardiovascular device programs seeking bypassed qualification bottlenecks. Gerresheimer AG exemplifies specialized glass and polymer conversion capabilities serving diagnostic and drug delivery segments.
China
Yangtze River Delta electronics manufacturing bases pivot toward FDA-registered device assembly for export markets. NMPA registration requirements for imported devices add compliance layers for brands serving domestic healthcare systems. Shanghai and Suzhou cleanroom expansions capture diagnostic instrument programs relocating from higher-cost Asian supply bases.
Costa Rica
San Jose corridor cleanroom capacity expansion attracts cardiovascular catheter production seeking proximity to US markets without domestic labor costs. Free trade zone incentives and established medical device supplier ecosystems reduce facility qualification timelines for electrophysiology programs. FDA-registered facilities operated by Flex Ltd. and others anchor regional contract manufacturing growth.
Malaysia
Penang semiconductor cleanroom infrastructure converts to FDA-registered device assembly, capturing diagnostic instrument programs relocating from China. Existing electronics manufacturing services capabilities and established logistics corridors to ASEAN markets support rapid regulatory qualification. Plexus Corp. and regional competitors leverage backward integration into plastics molding for disposable device production.
Global Medical Device Contract Manufacturing Market Competitive Environment
Global majors compete with regional champions across regulatory infrastructure and specialized process technologies. The vendor base concentrates among three tiers: vertically integrated electronics manufacturers with medical divisions, pure-play device specialists with dedicated cleanroom assets, and regional fabricators serving single-country markets. Strategic archetypes include scale-driven platform players, niche technology specialists in additive manufacturing or laser processing, and geography-focused compliance facilitators. Dominant competitive moves encompass notified-body relationship acquisition in Europe and cleanroom capacity expansion in Costa Rica and Malaysia.
Among US-based diversified manufacturers, Jabil Inc., Flex Ltd., and Integer Holdings Corporation occupy positions spanning electronics assembly through implantable device production. Jabil represents the vertically integrated archetype combining plastics molding with final assembly. Flex exemplifies regulatory infrastructure depth through multi-jurisdiction notified-body relationships. Integer anchors specialized cardiovascular and orthopedic capabilities through dedicated wire-forming and extrusion assets. These three entities illustrate how scale, compliance breadth, and process specialization define competitive positioning in outsourced medical device production.
| Leading Market Players |
|---|
| Jabil Inc. |
| Flex Ltd. |
| Integer Holdings Corporation |
| Sanmina Corporation |
| TE Connectivity Ltd. |
| Celestica Inc. |
| Plexus Corp. |
| Gerresheimer AG |
| Nipro Corporation |
| Others |
Value Chain & Pricing Dynamics
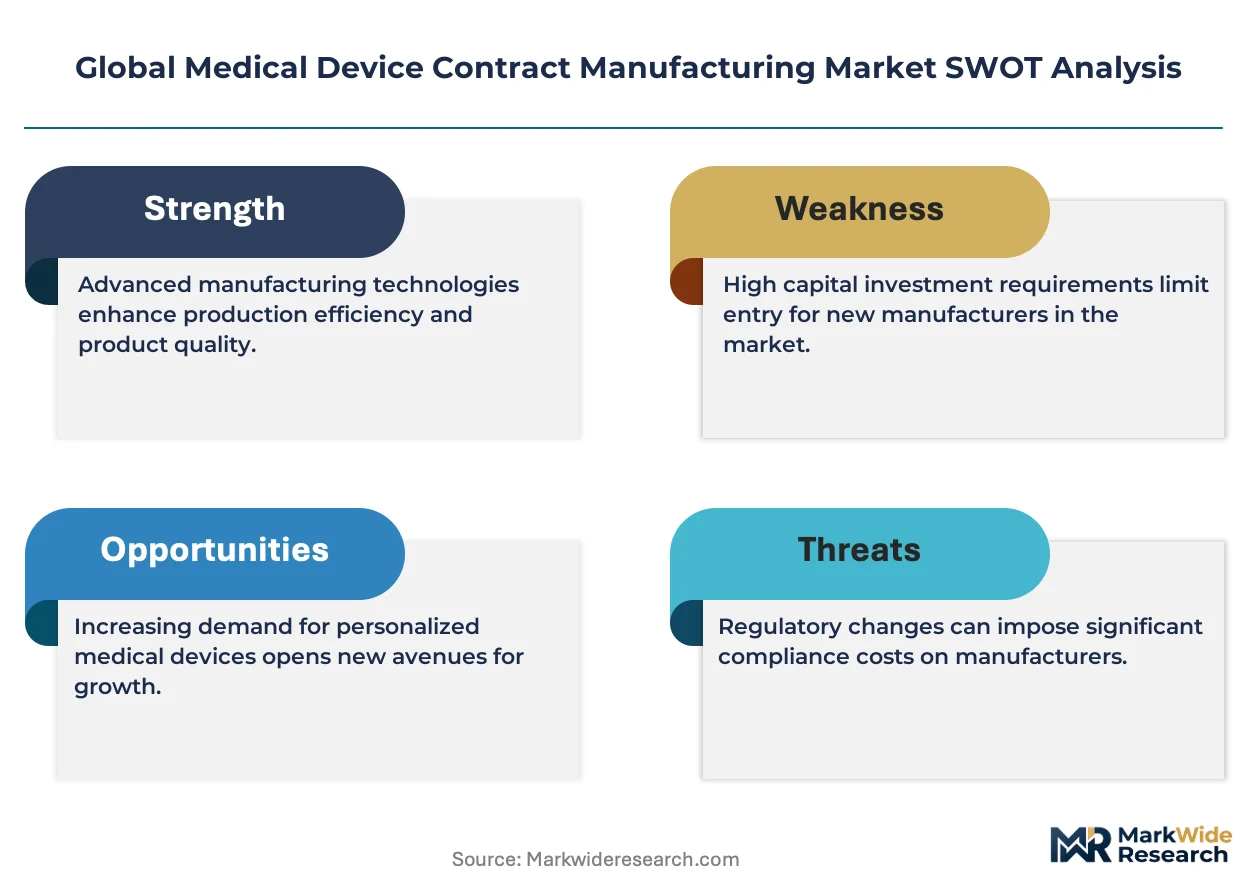
Certification-grade divergence between ISO 13485-validated cleanroom facilities and commodity assembly operations manifests in both pricing stratification and supply chain tiering, with FDA-registered capacity commanding premium contract values while standard electronics manufacturing services compete on unit economics. This bifurcation concentrates procurement power among OEMs bundling regulatory filing support, forcing mid-tier contract manufacturers to absorb compliance overhead or exit implantable device segments entirely.
Pricing Analysis
Warranty and post-market surveillance bundling separates premium contract manufacturers from transactional assembly providers, with multi-year service agreements now standard for cardiovascular catheter programs. Three-tier pricing structure across premium, standard, and economy levels reflects cleanroom classification, biocompatibility documentation depth, and notified-body relationship breadth. Cost compression in standard diagnostic assembly is intensifying because Malaysian and Costa Rican capacity expansion erodes labor arbitrage advantages. Hospital procurement through consolidated GPOs demonstrates highest price sensitivity, while early-stage OEMs prioritize regulatory risk transfer over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Malaysia anchor hub-and-spoke fulfillment patterns for sterile components requiring temperature-controlled logistics. Medical-grade PEEK and implantable-grade silicone feedstock concentrates among German and US chemical suppliers, creating single-source vulnerability for cardiovascular and orthopedic device programs. Tariff exposure on precision-machined titanium components from China amplifies input cost volatility for implantable hardware manufacturers. Distribution runs through OEM-direct channels for Class III devices, while diagnostic consumables leverage distributor networks serving hospital IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines and FDA quality system intensification are consolidating the vendor base, eliminating mid-scale contract manufacturers unable to sustain redundant regulatory staffing across jurisdictions. This pressure favors vertically integrated platform players with established notified-body relationships.
For Market Incumbents: Hedge against notified-body scarcity by acquiring CE marking infrastructure in Germany and Switzerland before audit queue extensions freeze new program launches. Deepen backward integration into medical-grade polymer compounding to offset feedstock concentration risk among German and US suppliers. Prioritize Costa Rican and Malaysian cleanroom expansion to capture cardiovascular catheter programs relocating from higher-cost US facilities.
For New Entrants and Emerging Players: The premium-to-economy price gap in software-enabled device assembly offers entry traction for contract manufacturers with embedded firmware validation capabilities. Target diagnostic instrument programs relocating from China to Penang's converted semiconductor cleanrooms. Pursue hospital system partnerships in US orthopedic segments where IDN consolidation has halved qualified vendor pools, offering single-source accountability as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play device specialists possessing dedicated wire-forming and extrusion assets given structural shortages in cardiovascular catheter manufacturing capacity. Long-term viability over the next decade hinges on regulatory infrastructure breadth rather than scale alone. Monitor FDA digital health pre-certification pathway expansion as the inflection signal for software-enabled device contract manufacturing valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified-body relationship acquisition in Germany bypasses 12-18 month EU MDR qualification bottlenecks. |
| Hospital System Partnership | IDN procurement consolidation demands single-source accountability across device lifecycle and aftermarket service. |
| Software Companion Development | FDA digital health pre-certification enables combined hardware-software regulatory filings for AI-enabled diagnostics. |
| Backward Integration | Captive medical-grade polymer compounding reduces exposure to German and US feedstock concentration. |
| Reimbursement Strategy | Patient-specific orthopedic implant reimbursement codes in US and German systems accelerate 3D printing adoption. |
Study Parameters
FDA 510(k) filings, EU MDR notified-body registration databases, and GPO contract award records formed the secondary backbone, supplemented by customs data tracking medical-grade polymer trade flows. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at device OEMs validated demand assumptions and qualification timeline estimates. Bottom-up facility capacity modeling and top-down OEM outsourcing spend analysis were triangulated to derive market sizing.
Historical trendline analysis across cleanroom capacity expansion, regulatory staff deployment, and program launch frequency informed the projection framework. Segmentation modeling incorporated product type, process technology, end-user category, and application focus across the analysis window. CAGRs were derived from regression analysis of outsourcing intensity trends and OEM capital expenditure patterns, with specific inputs from ISO 13485 certification timeline data and notified-body audit capacity constraints.
Inputs from FDA registration databases and EU MDR notified-body directories were available through the study window; gaps in private OEM outsourcing contract values introduce uncertainty bands around revenue estimates. Forecasts reflect documented assumptions regarding MDR transition deadlines and digital health regulatory pathway evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Nasal Implant Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Cervical Fusion Market
Medical Devices
Biological Microscope Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Surgical Monitors Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Fixed and Mobile C-Arms Market