
 Multiexperience Development Platforms Market | 2026-2036
Multiexperience Development Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Multiexperience Development Platforms Market Intelligence
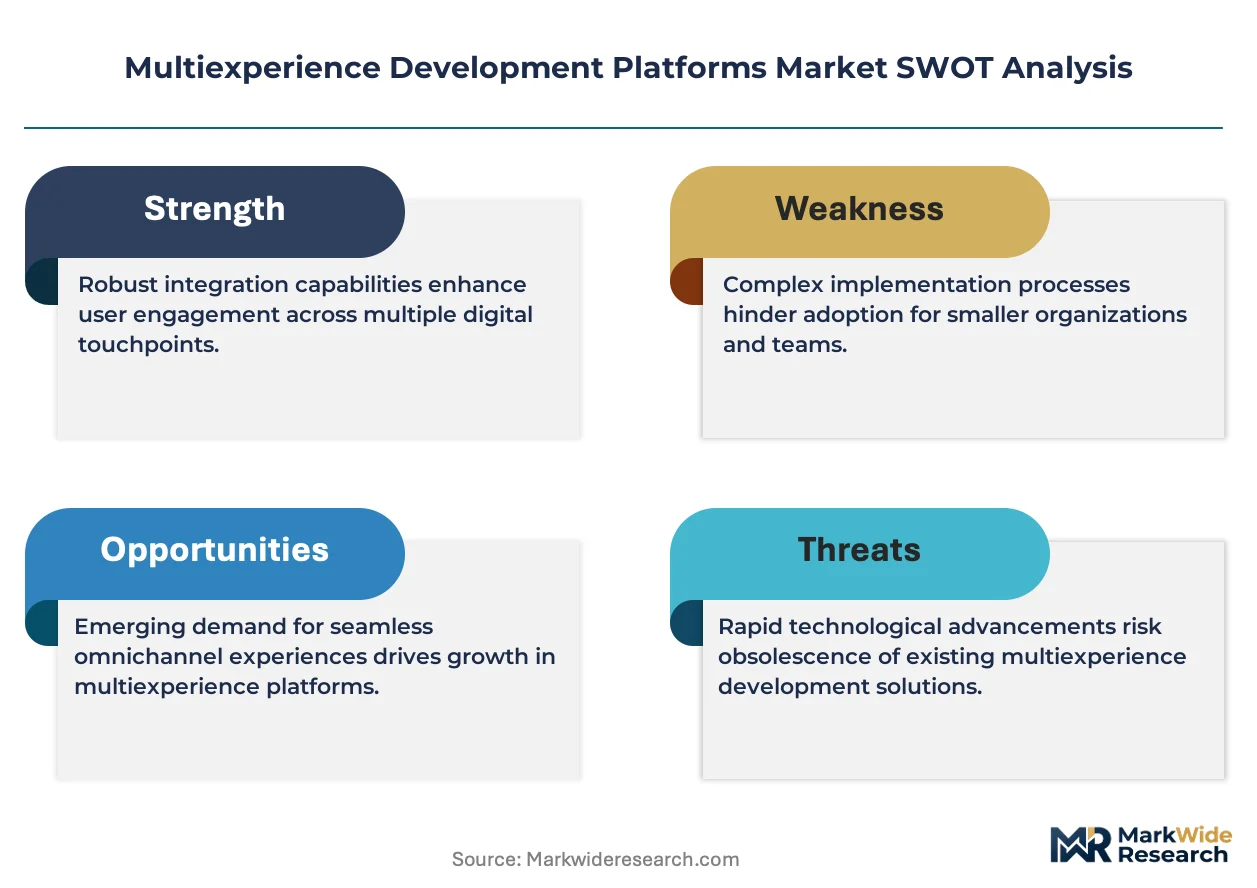
North American cloud infrastructure capacity is expanding to support low-latency multiexperience orchestration. Microsoft leverages its Azure ecosystem to anchor enterprise-grade deployment pipelines across hybrid environments. Salesforce sustains competitive pressure through deep CRM-native integration with voice and messaging channels. Adobe differentiates via creative-cloud adjacency and design-to-deployment workflow unification.
Multiexperience development platforms unify application creation across mobile, web, wearable, and immersive touchpoints through centralized backend services and reusable component libraries. These systems employ API-first architectures and real-time synchronization protocols to deliver consistent functionality regardless of interface modality. Cloud-based deployment models capture the dominant margin pool as enterprises abandon on-premises maintenance overhead. AI Integration within the technology stack represents the fastest-expanding configuration, though AR/VR modules remain concentrated in training and simulation use cases. Customer Experience applications lead volume demand, while Field Operations shows emergent traction in industrial IoT contexts.
The EU AI Act imposes risk-tiered obligations on automated decision systems embedded in customer-facing platforms, compelling vendors to embed audit trails and human oversight mechanisms. In the United States, the SEC and FTC are scrutinizing algorithmic transparency in financial services interfaces, tightening procurement criteria for regulated institutions. ISO standards for human-centered design and accessibility are gaining contractual weight in enterprise RFP processes. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud delivery architectures and force regional infrastructure replication.
Market Dynamics
The EU AI Act's risk-tiered obligations are forcing vendors to rearchitect their orchestration layers around auditability and human-in-the-loop governance, compressing deployment timelines for financial services and healthcare interfaces.
Growth Catalysts
- Algorithmic Accountability Mandates:The EU AI Act and emerging SEC scrutiny on automated decision systems in banking interfaces are compelling institutions to procure platforms with embedded compliance tooling.
- Industrial IoT Field Operations:Manufacturing and energy sectors are deploying AR-enabled maintenance workflows through unified development frameworks to reduce equipment downtime.
- API-First Architecture Standardization:Enterprise IT modernization budgets are prioritizing reusable component libraries that synchronize real-time data across mobile, web, and immersive touchpoints.
Market Restraints
- Cross-Border Data Localization:Fragmented sovereignty requirements in Germany, France, and India are forcing redundant regional infrastructure replication, inflating cloud operational overhead.
- Specialized Talent Scarcity:Shortages of engineers proficient in both immersive interface design and backend microservices architecture are elongating implementation cycles.
- Legacy System Entrenchment:Mainframe-dependent financial institutions face prohibitive integration costs when connecting centralized orchestration layers to cobol-based core banking systems.
Strategic Opportunities
- Brazilian Financial Inclusion:Underpenetrated banking digitization in Latin America's largest economy creates demand for voice-first and low-bandwidth interface platforms.
- Convergence of Generative AI and AR:Real-time procedural content generation for immersive training environments represents unclaimed white space in industrial and healthcare simulation markets.
- India's PLI Scheme for Electronics:Domestic manufacturing incentives are attracting platform vendors to establish local delivery centers for wearable and embedded device orchestration.
Industry Challenges
- Multimodal Accessibility Certification:ISO standards for human-centered design are gaining contractual weight in enterprise RFPs, requiring expensive redesign cycles for voice and gesture interfaces.
- Hybrid Environment Complexity:Synchronizing state across on-premises legacy nodes and elastic cloud orchestration layers demands specialized site reliability engineering capabilities that most enterprises lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiexperience Development Platforms Market |
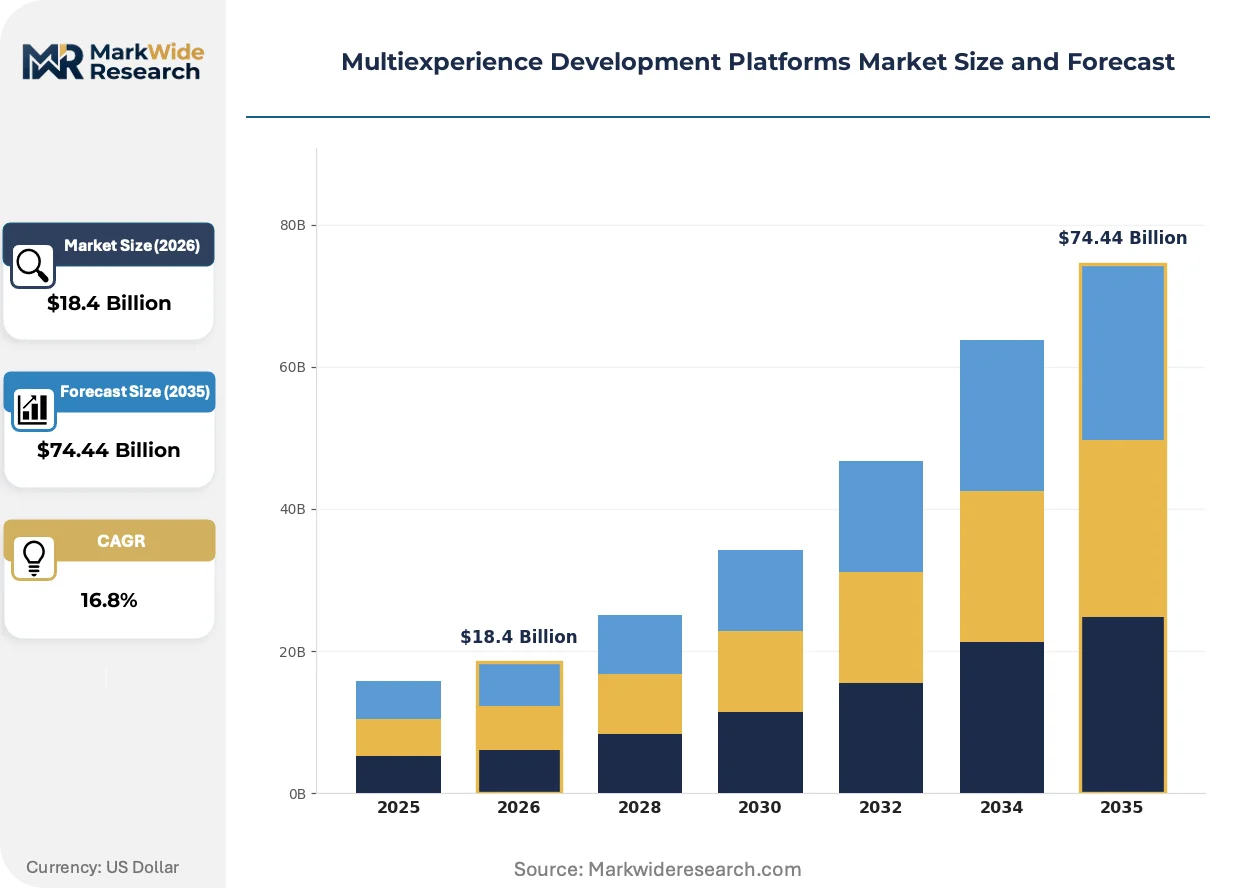
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $74.44 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Technology: AI Integration, Voice Recognition, AR/VR, Chatbots, Gesture Control Application Area: Customer Experience, Employee Engagement, Product Design, Field Operations, Training & Simulation End User Segment: Financial Services, Manufacturing Units, Telecommunications Providers, Educational Institutions, Government Agencies |
| Companies Covered | Adobe, Sitecore, Salesforce, Contentful, Acquia, Microsoft, Optimizely, Progress, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiexperience Development Platforms Market Strategic Shifts & Innovations
Generative AI capabilities are embedding directly into development workflows, shifting competitive advantage from runtime performance to design-time productivity and automated interface generation.
Edge-deployed AI inference engines are expanding into manufacturing floor operations and remote healthcare diagnostics, where millisecond latency requirements preclude cloud round-trips. Automotive and medical device manufacturers are piloting these architectures for predictive maintenance and surgical assistance workflows. The structural consequence is a bifurcation in vendor roadmaps between centralized cloud-native platforms and distributed edge-orchestration stacks.
The EU AI Act's conformity assessment procedures are mandating documentation trails for training data provenance and model versioning in customer-facing automation. Platform vendors must now embed model cards and bias detection dashboards as standard product features. Financial services procurement teams in Frankfurt and Paris are requiring these capabilities as table stakes for vendor shortlisting.
Enterprise buyers are consolidating vendor relationships around full-stack platform providers rather than assembling point solutions for each interface modality. This concentration is displacing specialized mobile development shops and standalone AR tool vendors in favor of unified backend services. The shift is most pronounced in United States healthcare systems and German automotive supply chains, where procurement teams prioritize single-vendor accountability for cross-channel experience consistency.
Multiexperience Development Platforms Market Segmentation
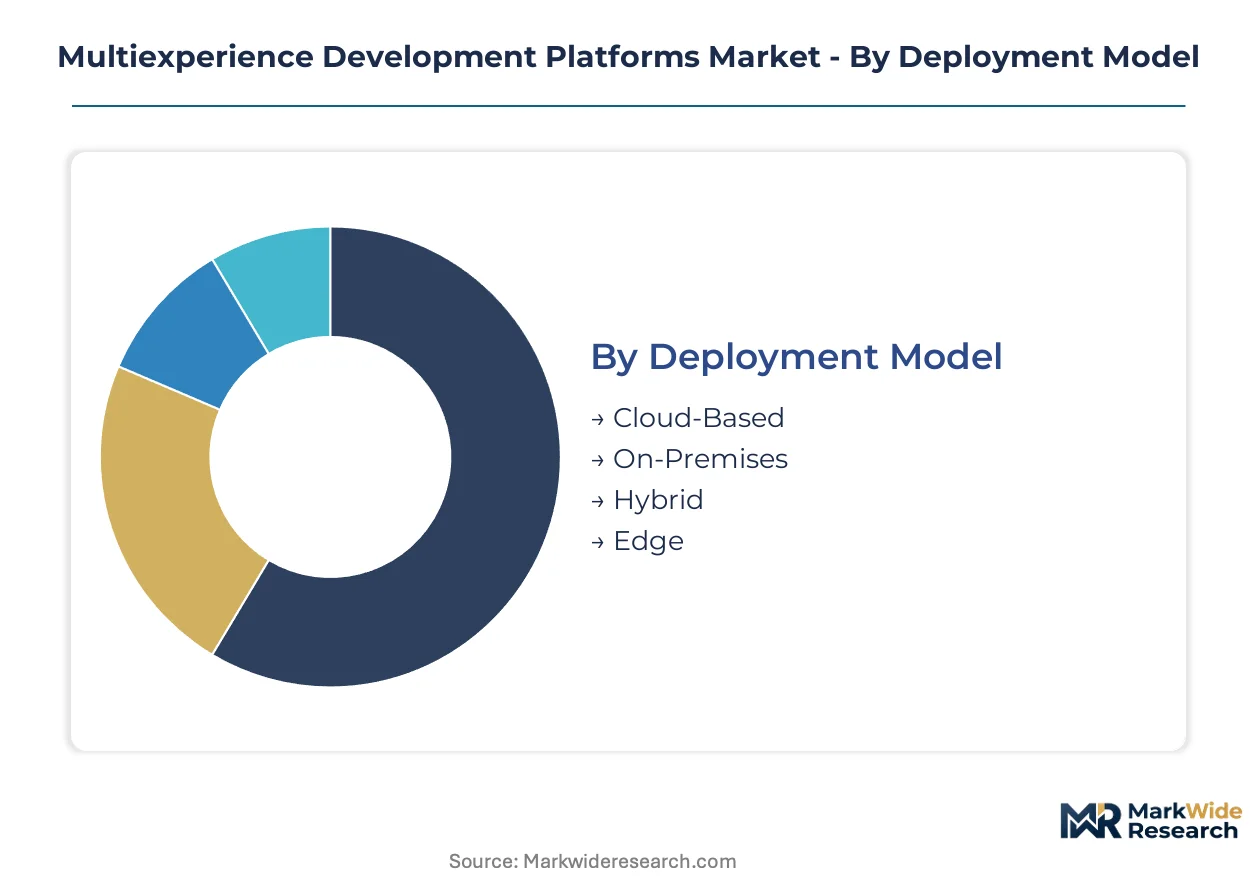
Multiexperience development platforms fragment across four critical dimensions that determine procurement priorities and architectural trade-offs. Deployment models dictate infrastructure ownership and operational overhead. Technology stacks differentiate competitive positioning through interface modality coverage. Application areas and end-user segments reveal where enterprise budgets concentrate and compliance requirements intensify.
Deployment Model:
Platform refresh cycles accelerate as enterprises abandon on-premises maintenance burdens for consumption-based alternatives.
- Cloud-Based:Fully managed infrastructure with elastic scaling and API-first service orchestration. Financial services institutions in the United States prioritize this model to satisfy SEC scrutiny on operational resilience while avoiding capital expenditure spikes.
- Hybrid:Split workloads across private data centers and public cloud nodes with unified orchestration layers. German automotive manufacturers favor this architecture to retain sensitive design data on-premises while leveraging cloud analytics for customer-facing interfaces.
- On-Premises:Self-hosted infrastructure requiring dedicated site reliability engineering. Defense contractors and classified government facilities mandate this model for air-gapped security compliance.
- Edge:Distributed compute nodes deployed at manufacturing floors, retail locations, or remote field sites. Energy sector maintenance crews in remote geographies deploy these for millisecond-latency AR guidance without cloud dependency.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Edge deployments.
Technology:
Capability gaps between legacy interface modalities and emerging immersive standards drive replacement demand across enterprise technology estates.
- AI Integration:Embedded machine learning for predictive personalization, natural language understanding, and automated decision support. EU AI Act compliance tooling now bundles bias detection dashboards and model versioning trails as standard procurement requirements in Frankfurt and Paris.
- AR/VR:Spatial computing interfaces for immersive training, remote assistance, and 3D product visualization. Industrial IoT maintenance workflows in manufacturing units show emergent traction as equipment downtime reduction becomes a board-level metric.
- Voice Recognition:Hands-free interaction layers for field operations and accessibility compliance. Telecommunications providers integrate these into customer service automation to deflect call center volume.
- Chatbots:Text-based conversational interfaces with escalation protocols to human agents. Banking institutions deploy these for routine transaction queries while reserving live staff for complex advisory services.
- Gesture Control:Touchless interaction paradigms for sterile environments and manufacturing safety zones. Healthcare surgical suites pilot these for hands-free access to imaging data during procedures.
Revenue gravity centers on AI Integration; steepest expansion trajectory appears in AR/VR modules.
Application Area:
Functional specialization determines platform configuration complexity and integration depth with existing enterprise systems.
- Customer Experience:Unified touchpoints across mobile, web, voice, and messaging channels with synchronized state management. Retail banking institutions in the United States allocate the largest modernization budgets here to reduce churn and cross-sell penetration.
- Field Operations:AR-enabled maintenance workflows, remote expert assistance, and IoT-integrated diagnostics. Energy and manufacturing sectors deploy these to compress mean-time-to-repair metrics for critical infrastructure.
- Employee Engagement:Internal portals, training systems, and collaboration tools with multi-modal access. Educational institutions adopt these to support hybrid learning environments with accessibility compliance.
- Product Design:Collaborative 3D modeling, digital twin integration, and immersive review sessions. Automotive supply chains use these to compress design iteration cycles with distributed engineering teams.
- Training & Simulation:Procedural rehearsal environments for high-risk scenarios without physical exposure. Healthcare systems and aviation operators mandate these for credentialing and recertification programs.
Procurement volume dominates Customer Experience; Field Operations climbs the fastest as industrial IoT investment accelerates.
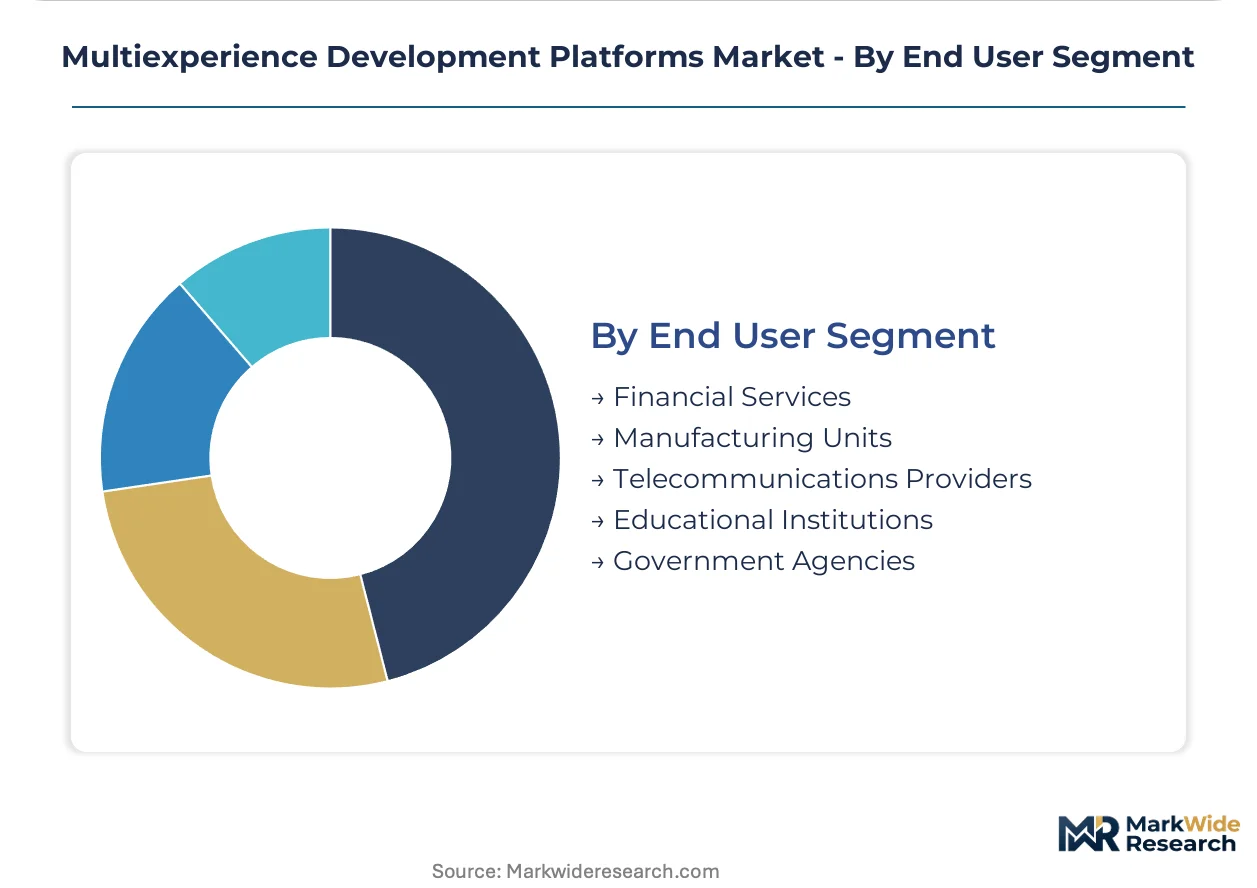
End User Segment:
Vertical-specific compliance regimes and workflow complexity shape platform customization requirements and sales cycle duration.
- Financial Services:Banks, insurers, and asset managers requiring audit trails for automated decisions and human-in-the-loop governance. SEC and EU AI Act obligations compress vendor shortlisting criteria around embedded compliance tooling.
- Manufacturing Units:Discrete and process manufacturers integrating AR maintenance, digital twins, and shop-floor IoT. German automotive supply chains and Japanese electronics producers lead deployment maturity.
- Telecommunications Providers:Network operators modernizing customer service automation and field technician support. Brazilian operators invest in voice-first interfaces for low-bandwidth environments.
- Educational Institutions:Universities and vocational training centers deploying immersive learning environments. Indian technical institutes leverage PLI scheme incentives for wearable device orchestration.
- Government Agencies:Federal, state, and municipal entities with accessibility mandates and security classifications. Defense and healthcare administration segments show strongest budget commitment.
Financial Services captures the largest contract values; Manufacturing Units gain share fastest through industrial IoT convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density in the United States anchors the geography for multiexperience platform deployment, with enterprise IT modernization budgets concentrating in financial services and healthcare clusters.
United States
SEC scrutiny on algorithmic transparency in banking interfaces drives procurement of platforms with embedded compliance tooling. Financial services institutions in New York and Chicago prioritize omnichannel architecture investments to satisfy operational resilience mandates. The Boston healthcare corridor deploys these systems for patient-facing automation with human-in-the-loop governance.
Germany
Automotive supply chains demand hybrid deployment models to retain sensitive design data on-premises while leveraging cloud analytics. The EU AI Act imposes risk-tiered obligations on automated decision systems, compelling Frankfurt financial institutions to require audit trails and model versioning. Bavarian manufacturing clusters pilot AR-enabled maintenance workflows for equipment downtime reduction.
United Kingdom
London-based financial services firms accelerate adoption of unified development frameworks to streamline cross-channel customer experiences. GDPR and emerging algorithmic accountability standards reshape compliance requirements for intelligent experience platforms. The Thames Valley technology corridor concentrates vendor delivery centers serving European enterprise clients.
India
The PLI scheme for electronics attracts platform vendors to establish local delivery centers for wearable and embedded device orchestration. Domestic manufacturing incentives accelerate deployment of voice-first interfaces for low-bandwidth environments. Bengaluru and Hyderabad host engineering talent pools for backend microservices architecture development.
Brazil
Underpenetrated banking digitization creates demand for voice-first and low-bandwidth interface platforms in Latin America's largest economy. Telecommunications providers invest in customer service automation to deflect call center volume. São Paulo financial institutions modernize legacy infrastructure through API-first architecture standardization.
Multiexperience Development Platforms Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue edge-orchestration specialization and generative AI integration. The vendor base concentrates around full-stack platform providers displacing point-solution assemblers. Three archetypes dominate: cloud-native hyperscalers with hybrid deployment pipelines, CRM-anchored specialists with deep customer data integration, and creative-tool adjacent vendors with design-to-deployment workflow unification. Competitive moves center on strategic partnerships for regulatory compliance tooling and geographic expansion into underpenetrated financial services markets.
Within the cloud-native hyperscaler tier, Microsoft and Salesforce exemplify divergent anchoring strategies. Microsoft leverages Azure ecosystem integration for enterprise-grade hybrid deployment pipelines. Salesforce occupies a position defined by CRM-native convergence with voice and messaging channels. Adobe sits within the creative-adjacent archetype, differentiating through design-to-deployment workflow unification and creative-cloud proximity.
| Leading Market Players |
|---|
| Adobe |
| Sitecore |
| Salesforce |
| Contentful |
| Acquia |
| Microsoft |
| Optimizely |
| Progress |
| SAP |
| Others |
Cost & Logistics Intelligence
Cloud-native hyperscaler tier divergence separates premium managed-service bundles from commodity infrastructure rentals, with the former commanding sustained margin premiums through embedded compliance tooling while the latter faces relentless cost compression from elastic compute commoditization. This bifurcation manifests in supply chain configurations where full-stack platform vendors maintain captive engineering centers in talent-dense clusters, whereas price-competitive entrants draw from distributed contractor networks.
Pricing Analysis
Warranty and service-bundling decisions distinguish enterprise-grade platform procurement from self-managed deployments, with SOC 2 audit guarantees and EU AI Act compliance documentation now standard inclusions for financial services buyers in Frankfurt and New York. Pricing stratifies across premium, standard, and economy tiers according to deployment complexity and human-in-the-loop governance depth. Cost compression in the economy tier intensifies because hyperscalers leverage existing cloud infrastructure overhead to absorb platform licensing into compute consumption bundles. Regulated banking institutions exhibit lowest price sensitivity due to procurement criteria weighting auditability over unit cost, while mid-market retailers remain most responsive to per-seat licensing discounts.
Supply Chain Analysis
Workforce availability constraints in Bengaluru, Hyderabad, and Warsaw shape platform engineering capacity, with these clusters feeding backend microservices development for vendors serving European and North American enterprise clients. Supply draws from specialized talent pools proficient in immersive interface design and API-first architecture, alongside GPU compute resources for AI inference workloads. Single-source vulnerability concentrates in NVIDIA-dependent training infrastructure for generative AI features. Distribution runs through direct enterprise sales teams for large financial services contracts, supplemented by hyperscaler marketplace listings for developer-led adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity assessment burden erects a compliance moat that favors incumbent vendors with embedded audit tooling, raising capital requirements for new entrants seeking regulated financial services procurement eligibility.
For Market Incumbents: Anchor defensive positioning through backward integration into edge-orchestration hardware partnerships, insulating against emerging specialized entrants targeting manufacturing floor deployments. Expand certification investment in ISO human-centered design standards to capture healthcare accessibility mandates. Consolidate channel control by absorbing standalone AR tool vendors before they achieve critical mass in industrial IoT maintenance workflows. For New Entrants and Emerging Players: Launch via embedded finance partnerships with Brazilian neobanks seeking voice-first interface platforms for underpenetrated rural banking digitization. Target energy sector field operations in remote geographies where millisecond-latency AR guidance commands premium pricing absent hyperscaler competition. Prioritize generative AI integration for procedural content generation in healthcare simulation markets as the most penetrable white-space application. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler tuck-in acquisitions seeking edge-orchestration capabilities and generative AI feature stacks. Long-term viability favors vendors with demonstrated EU AI Act compliance tooling traction in Frankfurt and Paris procurement cycles. Monitor SEC algorithmic transparency enforcement intensity as the critical inflection signal for financial services platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Tooling Integration | Embedded audit trails satisfy Frankfurt procurement criteria for banking automation platforms. |
| Edge-Orchestration Capability Buildout | Distributed compute nodes address manufacturing floor latency requirements beyond cloud reach. |
| Generative AI Workflow Embedding | Automated interface generation shifts competitive advantage from runtime to design-time productivity. |
| Hybrid Deployment Pipeline Expansion | Split workload architectures retain German automotive design data on-premises while leveraging cloud analytics. |
| Brazilian Financial Inclusion Partnership | Voice-first platforms capture underpenetrated banking digitization in Latin America's largest economy. |
Research Approach
SEC filings, hyperscaler capex disclosures, and EU regulatory databases formed the secondary backbone for this analysis, supplemented by customs records tracking cloud infrastructure equipment flows. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists validated architectural adoption patterns and vendor shortlisting criteria. Bottom-up and top-down triangulation reconciled enterprise deployment counts with aggregate platform revenue disclosures.
Bottom-up modeling of deployment volumes across cloud, hybrid, on-premises, and edge configurations anchored the analytical framework, cross-referenced against top-down IT modernization budget allocations from financial services and manufacturing verticals. Segmentation dimensions included deployment model, organization size, vertical compliance intensity, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves applied to vendor-reported customer acquisition trajectories, with AI integration penetration and AR/VR module attach rates serving as key forecast inputs across the projection horizon.
EU AI Act enforcement delays, SEC algorithmic transparency rule finalization, and cross-border data localization mandate fragmentation are the dominant revision risks to modeled adoption timelines. Forecasts reflect documented assumptions regarding compliance cost pass-through elasticity and enterprise cloud migration velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
RIP Color Management Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Software Repository Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Global Product Management Software Market
Software & Services
Enterprise Search Software Market