
 Global E-Filing Platforms Market | 2026-2036
Global E-Filing Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Filing Platforms Market Foresight
API-first architecture is realigning platform economics as RESTful interfaces displace legacy XML batch protocols. InfoTrack leverages deep integrations with county court systems across multiple states. FileTime anchors its position through specialized probate and civil filing workflows in Texas and Florida. Green Filing competes on price-transparent subscription tiers for solo practitioners and small law offices.
E-filing platforms are web-based software systems that enable electronic submission, routing, and tracking of legal documents, tax returns, and regulatory filings through encrypted HTTPS channels with digital signature authentication and audit trail generation. Cloud-Based deployment leads segment share as law firms and government agencies abandon on-premises server maintenance; Hybrid configurations are gaining fastest among mid-size corporate legal departments managing sensitive intellectual property registration workflows. Software as a Service dominates offering revenue due to recurring subscription economics, while Platform as a Service attracts large court systems requiring custom workflow development.
The United States Federal Courts' CM/ECF system, the EU e-CODEX cross-border framework, and India's NIC e-Courts project each mandate electronic filing standards that reshape vendor certification requirements and procurement eligibility. The SEC's EDGAR modernization and HIPAA administrative simplification rules extend compliance-driven demand into corporate disclosure and healthcare documentation channels. Stakeholders must monitor which jurisdictions will mandate real-time API submission versus batch upload acceptance, as this technical threshold determines platform redevelopment costs and competitive exclusion.
Market Dynamics
Court-mandated digital submission channels are forcing law firms and government agencies to abandon paper-based workflows, creating irreversible infrastructure lock-in that favors platforms with pre-certified judicial integrations.
Growth Catalysts
- CM/ECF Mandates:The United States Federal Courts' Case Management/Electronic Case Files system requires electronic submission for all civil and criminal cases, eliminating paper filing options and creating guaranteed platform demand.
- Cloud Migration:Law firms are abandoning on-premises servers for SaaS deployments, reducing IT overhead while enabling remote access to filing systems from any jurisdiction.
- EU e-CODEX:The European cross-border e-justice framework standardizes electronic filing protocols across member states, opening procurement opportunities for certified platform vendors.
Market Restraints
- Certification Bottlenecks:Each U.S. state court system maintains independent vendor approval processes, fragmenting market entry and extending sales cycles to 18-24 months.
- Legacy System Entrenchment:County-level court IT infrastructure in rural jurisdictions remains dependent on decades-old mainframe architectures resistant to API integration.
- Data Sovereignty Requirements:Germany's GDPR implementation and India's data localization mandates prevent cloud-hosting of sensitive legal documents on foreign servers, complicating multi-territory platform architecture.
Strategic Opportunities
- Probate Workflow Specialization:Texas and Florida court systems process the highest U.S. probate volumes, creating niche demand for platforms with automated estate inventory and creditor notice modules.
- Healthcare-HIPAA Convergence:Administrative simplification rules extend e-filing requirements into medical claims and prior authorization workflows, opening adjacent revenue streams beyond legal markets.
- API-First Monetization:Platform vendors can license RESTful interfaces to practice management software vendors, capturing recurring integration fees without direct end-user acquisition costs.
Industry Challenges
- Judicial IT Talent Scarcity:State court systems lack in-house engineering capacity to evaluate API security protocols, delaying vendor certification timelines and increasing implementation failure rates.
- Multi-Jurisdictional Compliance:Platforms serving cross-border law firms must simultaneously satisfy SEC EDGAR formatting rules, EU e-CODEX metadata standards, and India's NIC e-Courts XML schemas.
- Digital Signature Fragmentation:Incompatible e-signature standards across U.S. state bars, EU qualified signature frameworks, and India's Controller of Certifying Authorities create document rejection risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Filing Platforms Market |
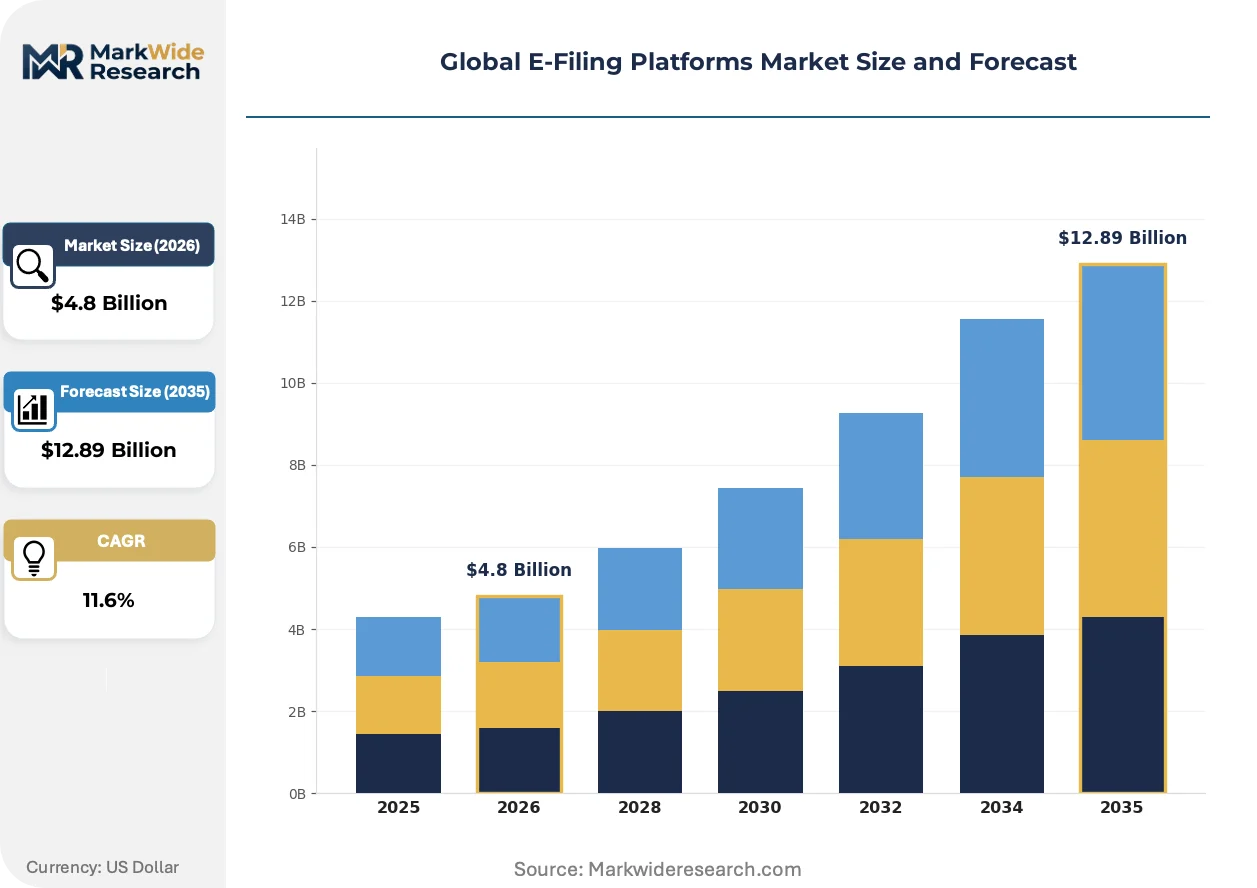
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Virtual Desktop Infrastructure Offering: Software as a Service, Platform as a Service, On-Demand Services, Subscription, Licensed Software Use Case: Tax Filing, Legal Documentation, Corporate Compliance, Personal Finance Management, Intellectual Property Registration End User: Government Agencies, Law Firms, Accountants, Small Businesses, Educational Institutions |
| Companies Covered | InfoTrack, One Legal, File & Serve Xpress, Doxpop, Green Filing, US Legal PRO, Cenifax Courts, FileTime, Internet Case Filing System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Filing Platforms Market Shifts & Advancements
RESTful API architecture is consolidating platform economics by displacing legacy XML batch protocols, while regulatory mandates in multiple jurisdictions accelerate technical standardization and reshape competitive barriers.
Blockchain-based audit trails are consolidating document integrity verification for high-stakes litigation filings. AmLaw 200 firms and Fortune 500 legal departments are adopting distributed ledger timestamping to establish immutable chain-of-custody records. This compression of evidentiary authentication costs is forcing mid-tier platforms to license third-party verification modules rather than build proprietary cryptography stacks.
India's NIC e-Courts project mandates real-time API submission for all district court filings, rejecting legacy batch upload protocols entirely. This regulatory compression eliminates vendors lacking synchronous integration capabilities from national procurement eligibility. Platform providers are responding by establishing Mumbai and Bangalore development centers to maintain localized infrastructure compliance.
Subscription unbundling is fragmenting traditional all-inclusive pricing models. Solo practitioners in the United States are rejecting bundled feature tiers, instead selecting modular components for specific practice areas like immigration or small claims. This behavioral shift concentrates price competition at the low end while enabling premium pricing for specialized workflow automation in complex commercial litigation segments.
Global E-Filing Platforms Market Segmentation
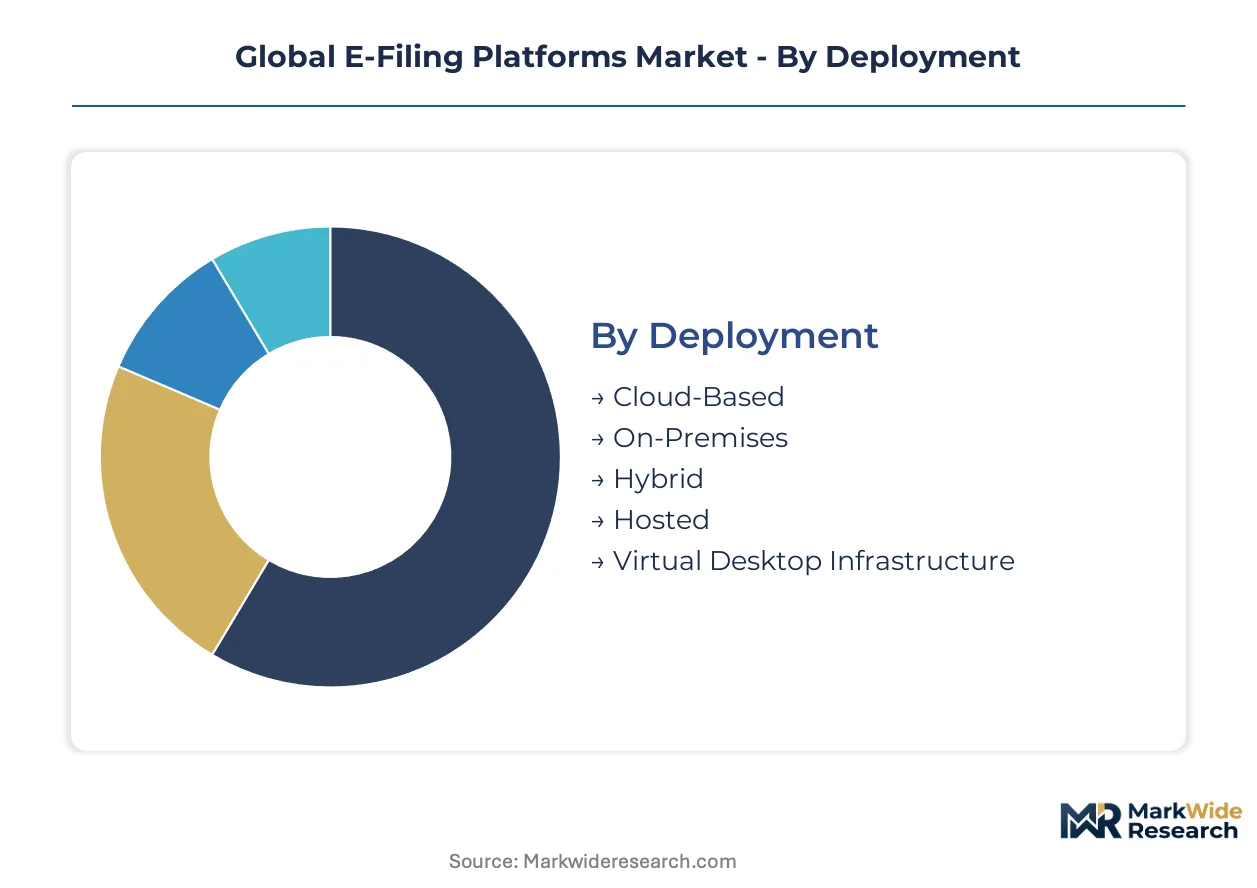
E-filing platform purchasing decisions hinge on jurisdictional compliance requirements, IT infrastructure maturity, and workflow complexity. Deployment architecture determines certification eligibility with specific court systems, while offering models align with organizational scale and customization needs.
Deployment:
IT budget constraints and data sovereignty rules drive architecture selection across buyer segments.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead while enabling remote access from any jurisdiction. Demand concentrates among solo practitioners and small law firms in the United States where CM/ECF mandates require rapid deployment without capital expenditure.
- Hybrid:Split configurations keep sensitive case metadata on local servers while routing public filings through cloud gateways. Germany's GDPR implementation and India's data localization mandates force this architecture among corporate legal departments managing cross-border intellectual property portfolios.
- On-Premises:Dedicated server installations persist in county court systems with decades-old mainframe dependencies resistant to API migration.
- Hosted:Single-tenant managed deployments serve mid-size law firms requiring customization without in-house DevOps capacity.
- Virtual Desktop Infrastructure:Centralized desktop streaming enables secure document preparation from unsecured endpoints, gaining traction among court-appointed attorneys and legal aid organizations.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations.
Offering:
Recurring revenue economics and integration depth shape vendor business model selection.
- Software as a Service:Subscription platforms deliver pre-configured filing workflows through web browsers with automatic compliance updates. Law firms across Texas and Florida probate courts favor this model for predictable cost structures and zero infrastructure ownership.
- Platform as a Service:Customizable API layers enable large court systems to build jurisdiction-specific workflows atop vendor infrastructure. India's NIC e-Courts project and EU e-CODEX implementations require this flexibility for national procurement eligibility.
- On-Demand Services:Per-transaction pricing accommodates sporadic filers such as individual taxpayers and small claims litigants.
- Subscription:Fixed-term contracts with tiered feature access dominate mid-market legal practices seeking volume discounts.
- Licensed Software:Perpetual license sales persist in government agencies with capital budget cycles incompatible with recurring expenditure.
Revenue concentrates in SaaS; Platform as a Service claims the steepest expansion trajectory among state-level implementations.
Use Case:
Regulatory mandate intensity and document complexity differentiate workflow requirements.
- Legal Documentation:Court-mandated electronic submission for civil, criminal, and appellate filings requires real-time case management integration and audit trail generation. Federal and state court systems across the United States drive this segment through CM/ECF and analogous state-level mandates.
- Tax Filing:Individual and corporate income tax submission platforms must reconcile with IRS e-file specifications and state revenue department schemas. India's GST Network and Germany's ELSTER system enforce technical compliance standards that reshape vendor certification.
- Corporate Compliance:SEC EDGAR modernization and EU CSRD disclosure requirements extend e-filing into financial reporting and sustainability documentation channels.
- Intellectual Property Registration:Patent and trademark filing workflows integrate with USPTO, EPO, and national IP office systems.
- Personal Finance Management:Individual wealth tracking and estate planning tools connect to probate court filing requirements.
Transaction volume clusters in Legal Documentation; Tax Filing gains share fastest as emerging economies digitize revenue collection.
End User:
Organizational scale and technical sophistication determine feature requirements and price sensitivity.
- Law Firms:AmLaw 200 practices and regional boutiques require matter management integration, multi-jurisdictional compliance, and advanced workflow automation. Demand concentrates in litigation-heavy practices across New York, California, and Texas state courts.
- Government Agencies:Federal, state, and municipal courts mandate platform procurement through formal RFP processes with 18-24 month sales cycles. Certification requirements vary independently across all 50 U.S. state court systems.
- Accountants:CPA firms and tax preparation services need seasonal scalability and IRS-authorized e-file provider status.
- Small Businesses:Limited technical staff drives preference for turnkey solutions with minimal configuration.
- Educational Institutions:University legal clinics and research centers require low-cost access for training and pro bono casework.
Revenue aggregates with Law Firms; Government Agencies represent the longest contract values despite extended procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform demand concentrates in jurisdictions with active judicial digitization mandates and established cloud infrastructure. The United States, Germany, and India each enforce distinct compliance frameworks that reshape vendor certification requirements and procurement eligibility.
United States
Federal and state court systems drive platform adoption through mandatory electronic submission protocols. The CM/ECF system administered by the Administrative Office of the U.S. Courts eliminates paper filing options for civil and criminal cases. Texas and Florida court clusters process the highest probate volumes, creating specialized demand for estate inventory automation.
Germany
Corporate legal departments and mid-size law firms accelerate hybrid deployment adoption to satisfy data sovereignty constraints. GDPR implementation and national data localization rules prevent foreign cloud hosting of sensitive legal documents. The Frankfurt and Munich legal centers concentrate platform procurement for cross-border intellectual property portfolios.
India
The NIC e-Courts project mandates real-time API submission for all district court filings, rejecting legacy batch upload protocols entirely. This regulatory compression eliminates vendors lacking synchronous integration capabilities from national procurement. Mumbai and Bangalore development centers anchor localized infrastructure compliance for platform providers.
United Kingdom
Commercial litigation practices and financial services legal departments sustain demand for SEC EDGAR-compliant disclosure workflows. The HM Courts & Tribunals Service digitization program extends electronic filing requirements across civil and family courts. London's Square Mile concentration drives premium-tier platform adoption for complex cross-border matters.
Australia
State-level court modernization programs in New South Wales and Victoria create procurement opportunities for certified platform vendors. The Federal Court's eLodgment system mandates electronic submission for corporate and intellectual property matters. Sydney and Melbourne legal clusters concentrate demand for practice management integration.
Global E-Filing Platforms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with SaaS-native vendors capturing volume while legacy system integrators retain government agency relationships. The vendor base organizes into three tiers: national-scale platforms with multi-jurisdictional certification, regional specialists with court-specific workflow depth, and price-transparent entrants targeting solo practitioners. Consolidation pressure intensifies as certification timelines extend and development costs rise for real-time API architectures. Dominant competitive moves include strategic partnerships with practice management software vendors and geographic expansion through court system certification acquisition.
Within the national-scale tier, InfoTrack and FileTime occupy positions anchored by deep judicial integrations across multiple U.S. state court systems. Green Filing exemplifies the price-competitive archetype, sitting within subscription tiers designed for cost-sensitive solo practitioners and small law offices. These three entities represent distinct strategic postures: integration depth, workflow specialization, and pricing transparency.
| Leading Market Players |
|---|
| InfoTrack |
| One Legal |
| File & Serve Xpress |
| Doxpop |
| Green Filing |
| US Legal PRO |
| Cenifax Courts |
| FileTime |
| Internet Case Filing System |
| Others |
Supply & Pricing Matrix
India's data localization mandates under the NIC e-Courts project gate both qualified supply and premium-tier pricing access, as vendors must maintain Mumbai and Bangalore development centers to achieve synchronous API certification eligibility.
Pricing Analysis
Volume concentrates in cloud-based SaaS subscriptions for solo practitioners and small law firms, while margins accrue to hybrid deployment specialists serving corporate legal departments with GDPR-compliant data sovereignty requirements. Price differentiation centers on certification grade—CM/ECF pre-certification commands premium positioning—and geographic delivery cost for localized infrastructure. Pricing pressure stems from subscription unbundling as solo practitioners reject bundled tiers for modular components. Small law offices exhibit highest price sensitivity; AmLaw 200 practices show lowest sensitivity due to matter management integration requirements.
Supply Chain Analysis
Dual-sourcing requirements from government agencies and large court systems mandate multi-supplier qualification, forcing vendors to maintain redundant API integration teams across certification jurisdictions. Software development concentrates in the United States, India, and Germany where judicial digitization programs create talent demand. Raw material dependencies include cloud compute infrastructure, cryptographic libraries for digital signature verification, and court system API documentation. Supply chain risk centers on single-source vulnerability where state-level certification bottlenecks create 18-24 month vendor lock-in. Distribution runs through direct sales to government agencies and channel partnerships with practice management software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where platform vendors pursue backward integration into court system API infrastructure to secure certification exclusivity and pricing power.
For Market Incumbents: Acquire court system API certification portfolios to consolidate multi-jurisdictional coverage and defend against SaaS-native entrants with faster deployment cycles. Invest in localized development centers in India and Germany to satisfy data sovereignty mandates and preempt regulatory exclusion. CM/ECF certification depth remains the priority defensive lever. For New Entrants and Emerging Players: The EU e-CODEX cross-border framework in Europe opens a window for specialized workflow vendors to capture procurement opportunities in member states lacking incumbent saturation. Target probate automation modules in Texas and Florida where estate inventory volumes exceed platform capacity. Pursue API-first monetization through practice management software licensing to bypass direct end-user acquisition costs. For Investors and Strategic Acquirers: Extended state court certification timelines exceeding 18 months is the leading indicator that consolidation pressure will intensify as development costs rise for real-time API architectures. Platform vendors with pre-certified judicial integrations across multiple U.S. states represent the most defensible acquisition profile. Watch for India's NIC e-Courts procurement decisions as the signal for which synchronous integration capabilities will dominate cross-border expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | RESTful architecture displaces XML batch protocols across CM/ECF and EU e-CODEX implementations. |
| Geographic Certification Expansion | State-level court system approvals in Texas and Florida unlock probate workflow specialization revenue. |
| Hybrid Deployment Infrastructure | Split cloud-local configurations satisfy Germany's GDPR and India's data localization mandates. |
| Practice Management Integration | Strategic partnerships with legal software vendors capture recurring fees without direct acquisition costs. |
| Blockchain Audit Trail Licensing | Third-party verification modules address AmLaw 200 demand for immutable chain-of-custody records. |
Research Methodology
SEC EDGAR filings, EU e-CODEX implementation reports, and India's NIC e-Courts procurement documents formed the secondary backbone, supplemented by trade data from legal technology associations and court system vendor certification records. Primary interviews with state court IT administrators, legal practice management software executives, and corporate legal department procurement officers provided operational validation. Bottom-up segment sizing triangulated against top-down judicial digitization budget allocations across the United States, Germany, and India.
Historical trendline analysis of electronic filing mandate adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, offering model, use case complexity, and end-user organizational scale. CAGRs derived from judicial digitization program timelines and cloud migration penetration curves. Forecast inputs incorporated API certification backlog durations and state-level procurement cycle lengths.
The model assumes a particular technology adoption path where real-time API submission displaces batch upload protocols; alternative pathways for legacy XML integration persistence would alter the outlook. Forecasts reflect assumptions regarding certification timeline compression and cloud infrastructure cost trajectories. Deviation in judicial IT talent availability or data sovereignty regulation enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Software Defined Application and Infrastructure Market