
 Enterprise Search Software Market | 2026-2036
Enterprise Search Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Search Software Market Intelligence
Subscription-based indexing and query orchestration is pivoting from perpetual licenses toward consumption-metered SaaS tiers. Elastic leverages its open-core distribution to sustain developer mindshare across DevOps environments. Coveo anchors its position in commerce and service-cloud integrations, while Glean specializes in generative AI augmentation for workplace knowledge retrieval.
Enterprise search software comprises platforms that ingest, index, and retrieve structured and unstructured data across repositories using inverted indices, vector embeddings, and natural language processing pipelines with sub-second query latency targets. The primary commercial purpose centers on surfacing actionable information to reduce employee search time and accelerate decision workflows. Cloud-based deployment leads in new bookings as IT departments prioritize elastic scalability and reduced datacenter overhead, while API integration captures the fastest expansion as developers embed search into proprietary applications and customer-facing portals.
GDPR in Europe, HIPAA in the United States, and ISO 27001 globally shape product roadmaps by mandating audit trails, access controls, and data residency options that vendors must certify before procurement approval. The SEC's cybersecurity disclosure rules for public companies further tighten requirements for search platforms handling financial records and internal communications. Stakeholders must monitor how retrieval-augmented generation architectures evolve under emerging AI liability frameworks to assess compliance exposure and platform upgrade cycles.
Market Dynamics
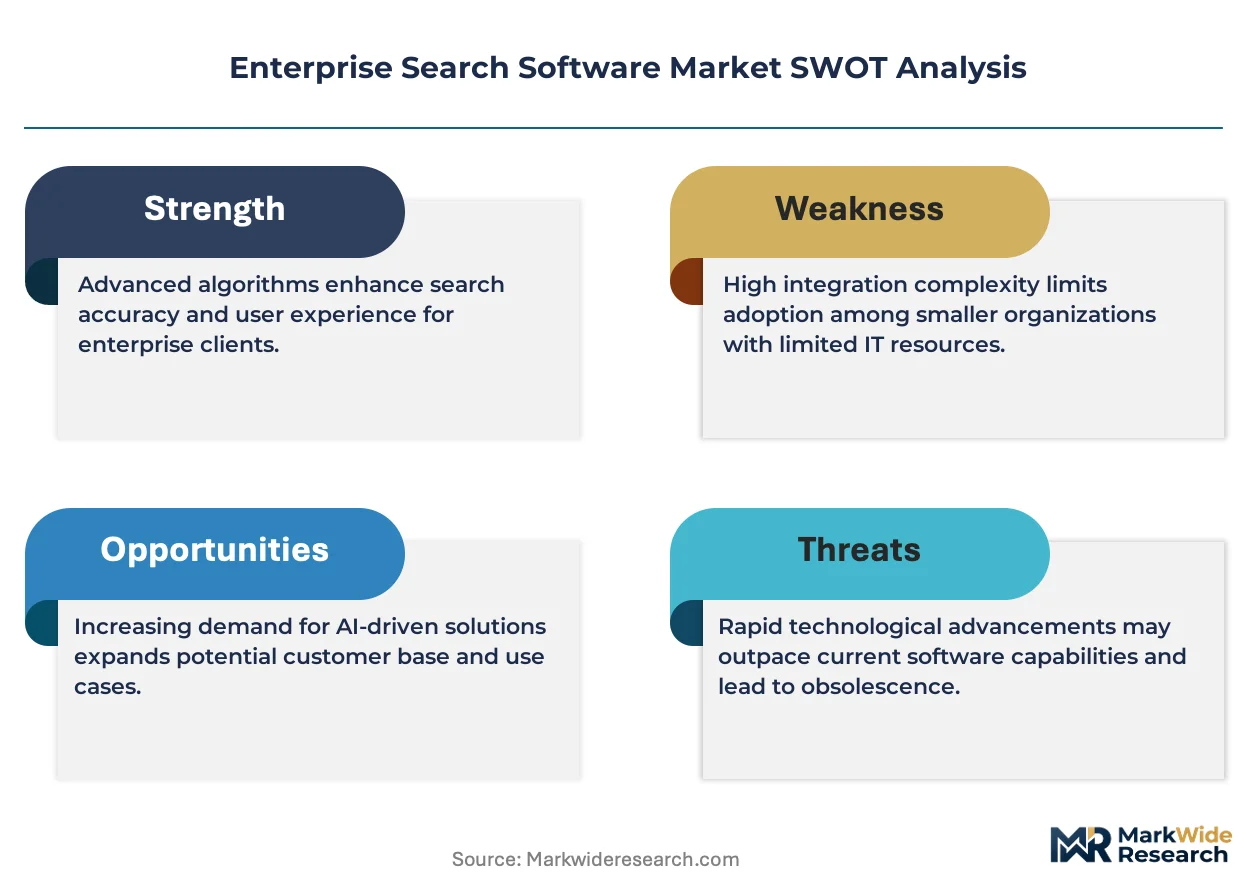
Retrieval-augmented generation architectures are compressing traditional keyword-based indexing into hybrid vector-semantic pipelines, forcing vendors to rebuild core engines around embedding models and real-time inference infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy explainable search systems with auditable retrieval paths, accelerating procurement of platforms with built-in consent management and lineage tracking.
- Financial services knowledge retrieval:Banks and insurance carriers are embedding AI-powered internal search to compress analyst research cycles and surface trapped institutional knowledge from unstructured document repositories.
- Vector database maturation:Open-source embedding frameworks and GPU-accelerated similarity search are reducing latency thresholds below 100 milliseconds, enabling real-time conversational interfaces.
Market Restraints
- Cloud compute cost volatility:Inference-heavy RAG workloads consume substantial GPU hours, creating margin pressure for vendors offering flat-rate SaaS pricing against unpredictable infrastructure bills.
- Data residency fragmentation:Cross-border data localization rules in Germany, France, and Switzerland force multi-region deployment architectures that inflate operational complexity.
- Legacy ECM integration friction:Decades-old SharePoint and Documentum installations lack modern APIs, requiring expensive connector development to unify siloed content sources.
Strategic Opportunities
- Healthcare clinical decision support:HIPAA-compliant search platforms can surface patient history and medical literature at the point of care, with US hospital systems representing substantial untapped deployment potential.
- Manufacturing technical documentation:Converging computer vision and NLP enables maintenance technicians to search equipment manuals using photographed part images rather than typed queries.
- SEC cybersecurity disclosure rules:Public companies must index and retrieve internal communications for incident response audits, creating compliance-driven demand for communication archiving with sub-second retrieval.
Industry Challenges
- ML engineering talent scarcity:Production-grade embedding optimization and ranking model fine-tuning require specialized skills that outstrip available supply in most enterprise IT organizations.
- ISO 27001 certification timelines:Enterprise procurement cycles stall for 6-12 months while vendors complete third-party security audits, delaying revenue recognition and stretching sales pipelines.
- Multilingual semantic drift:Cross-lingual embedding models exhibit accuracy degradation for low-resource languages, forcing costly regional model training for Japanese, Korean, and Arabic deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Search Software Market |
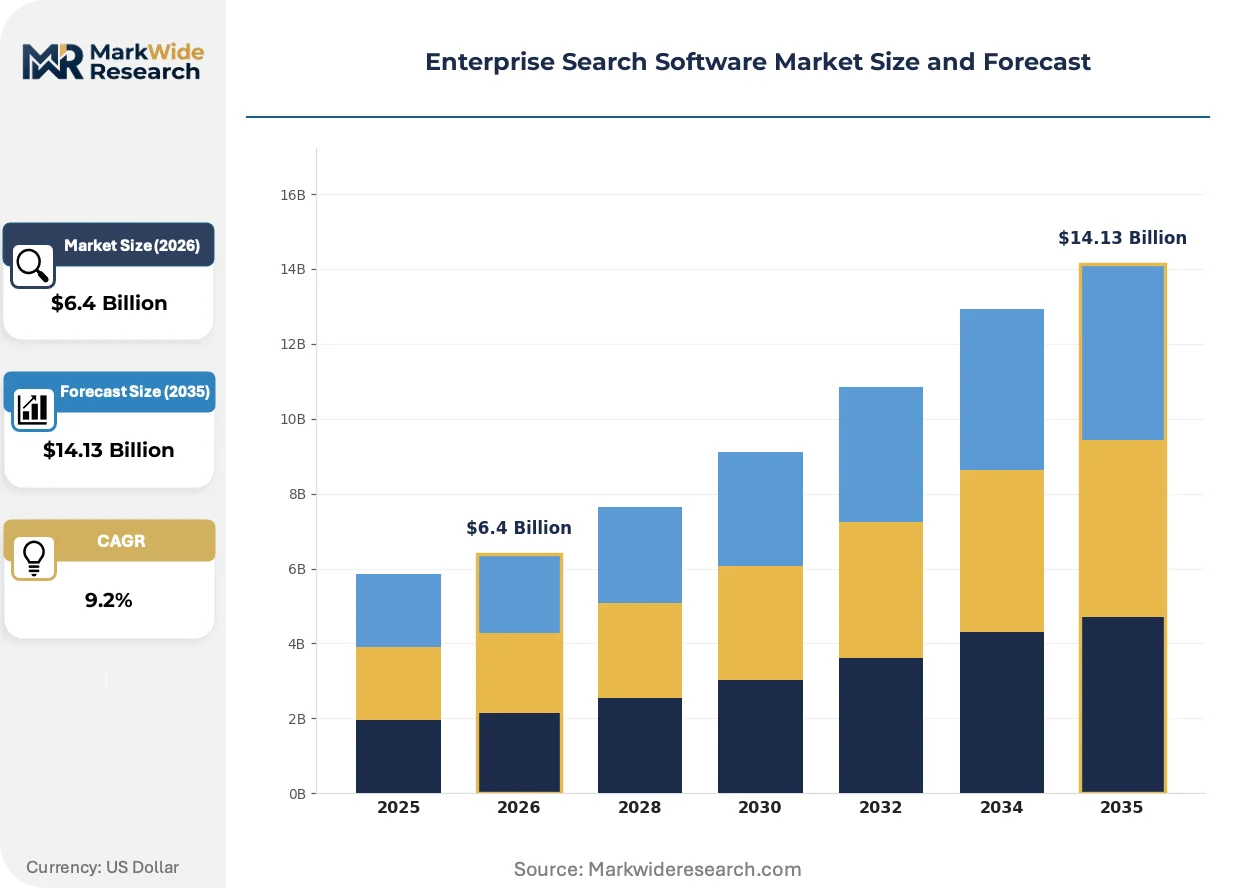
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Service Solution: File Search, Web Search, Database Search, Desktop Search End User: Corporations, Government Agencies, Educational Institutions, Non-Profits Integration Level: API Integration, Standalone, Plug-in, Custom Integration |
| Companies Covered | Guru, GoSearch, Glean, Google Cloud Search, Microsoft 365 Copilot Search, Coveo, Lucidworks, Algolia, Elastic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Search Software Market Strategic Shifts & Innovations
Enterprise search is absorbing generative AI capabilities that transform passive retrieval into active synthesis, compressing the boundary between information access and decision support.
Neural re-ranking models are absorbing attention-based architectures that dynamically score document relevance using query context rather than static term frequency. Financial services and legal research departments are deploying these systems to prioritize contract clauses and regulatory filings. The technology is absorbing relevance calibration tasks previously requiring dedicated data science teams, compressing total cost of ownership for mid-market buyers.
GDPR Article 22 automated decision-making restrictions are forcing vendors to expose retrieval provenance and confidence scores alongside generated summaries. European data protection authorities are interpreting these rules to cover AI-augmented workplace search. German and French enterprise buyers now require explainability dashboards as standard procurement criteria, displacing opaque black-box systems.
Consumption-metered pricing is displacing seat-based licensing as buyers demand elasticity for episodic research spikes. Procurement teams in US federal agencies and large consultancies are negotiating query-volume tiers with burst allowances. This pattern concentrates most visibly in professional services verticals where project-based research creates unpredictable usage patterns.
Enterprise Search Software Market Segmentation
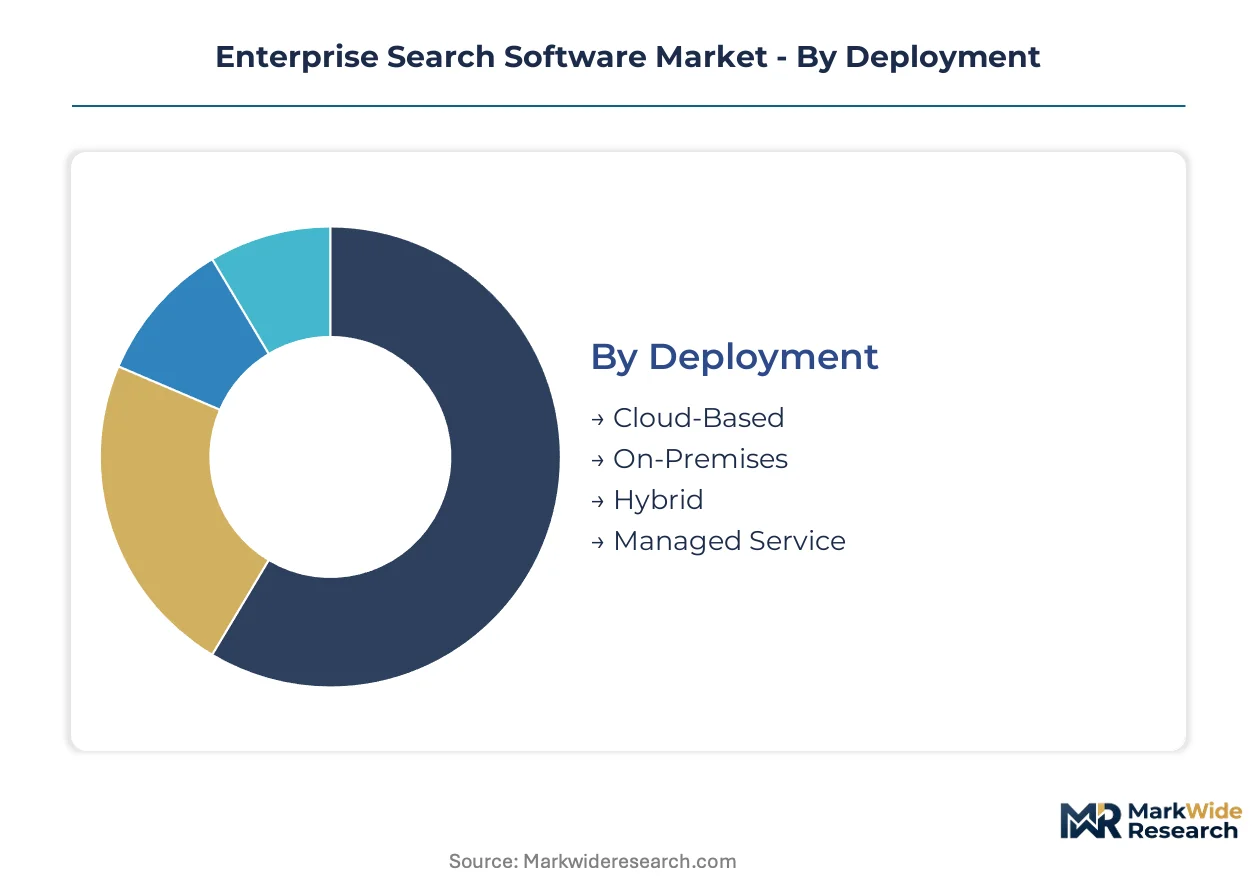
Enterprise search architectures fragment across deployment models, solution types, and integration depths. Procurement teams weigh cloud elasticity against data sovereignty requirements. Vendor selection hinges on whether search functions as a standalone platform or embedded service within existing workflows.
Deployment:
Cloud deployments capture volume leadership while hybrid configurations command premium pricing for regulated sectors.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling index clusters and consumption-metered billing. Financial services firms in the United States favor this model for rapid provisioning of AI-augmented retrieval without datacenter capital expenditure.
- On-Premises:Dedicated hardware installations with full data residency control and air-gapped security boundaries. German manufacturing conglomerates and Swiss pharmaceutical laboratories specify this deployment to satisfy national data localization statutes.
- Hybrid:Federated architectures splitting hot indexes across cloud edge nodes while retaining sensitive archives on-premises. French government agencies deploy hybrid configurations to balance accessibility with classified document protection.
- Managed Service:Vendor-operated private cloud instances with dedicated infrastructure and SLA-backed support. Japanese automotive suppliers prefer this model for outsourced operational burden with guaranteed latency thresholds.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution:
Application scope determines whether search functions as horizontal infrastructure or vertical point solution.
- File Search:Unified indexing of document repositories, SharePoint farms, and network-attached storage with version-aware retrieval. Healthcare systems in the United States deploy file search to surface patient records across Epic and Cerner environments under HIPAA audit requirements.
- Web Search:Crawler-based ingestion of public-facing websites, intranets, and knowledge bases with relevance-tuned ranking. Professional services firms embed web search into client-facing portals to accelerate proposal research and precedent discovery.
- Database Search:Structured query acceleration across SQL, NoSQL, and data warehouse schemas with faceted navigation. Expanding most quickly as analytics teams demand sub-second exploration of petabyte-scale lakehouses.
- Desktop Search:Local agent-based indexing of individual workstations and roaming profiles with offline availability. Knowledge workers in legal and research roles rely on desktop search for immediate access to downloaded case files and draft documents.
File search dominates current procurement cycles. Database search shows steepest expansion trajectory among data-intensive verticals.
End User:
Organizational scale and compliance posture shape feature requirements and pricing tolerance.
- Corporations:Enterprise-grade deployments with SSO integration, granular RBAC, and multi-language support across tens of thousands of seats. Procurement concentrates in technology, financial services, and professional services sectors with substantial knowledge-worker populations.
- Government Agencies:Classified and unclassified search environments with FedRAMP or equivalent certification, audit logging, and FOIA-compliant retrieval. United States federal modernization mandates sustain premium deployment rates for compliant platforms.
- Educational Institutions:Campus-wide discovery layers connecting library catalogs, learning management systems, and research repositories. University consortia negotiate volume pricing for shared infrastructure serving multiple institutions.
- Non-Profits:Constrained-budget deployments prioritizing open-source cores and grant-funded customization. Humanitarian organizations deploy search to unify dispersed field reports and donor documentation across low-bandwidth environments.
Corporations anchor current revenue. Government agencies represent the most price-insensitive expansion segment.
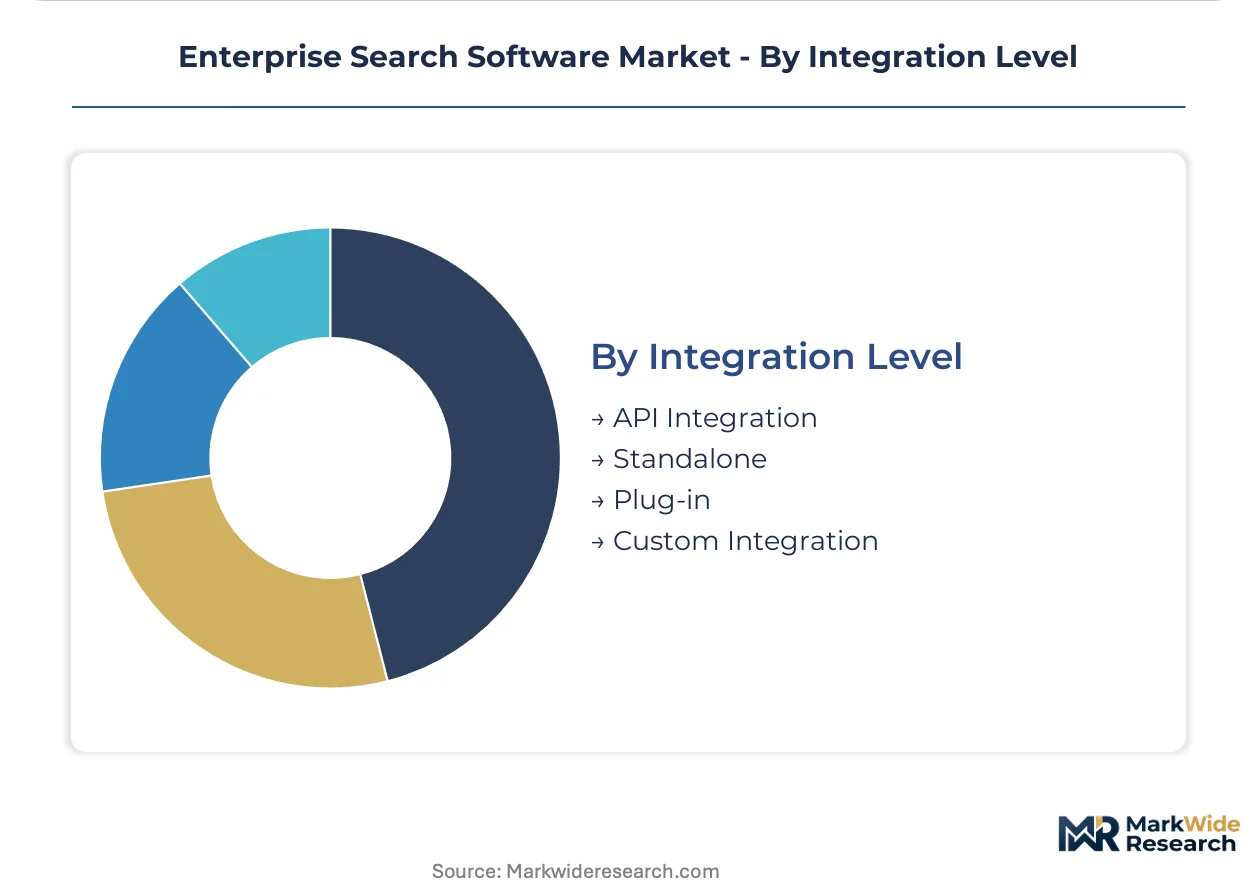
Integration Level:
Architectural embedding depth determines whether search operates as visible application or invisible infrastructure layer.
- API Integration:REST and GraphQL endpoints enabling developers to embed search into proprietary applications, customer portals, and mobile experiences. This segment gains share fastest as product teams prioritize embedded intelligence over standalone interfaces.
- Standalone:Full-featured web applications with dedicated UI, administration consoles, and end-user training requirements. Mid-market buyers without development resources default to standalone deployments for rapid time-to-value.
- Plug-in:Pre-built connectors for Salesforce, ServiceNow, Microsoft 365, and Slack that surface search within familiar productivity environments. Procurement teams favor plug-ins to minimize change management and retraining costs.
- Custom Integration:Bespoke engineering engagements for legacy ECM systems, proprietary data formats, and specialized security requirements. Investment banks and defense contractors commission custom integration for decades-old documentum installations lacking modern APIs.
API integration leads developer-led procurement. Plug-in models capture fastest adoption among business-unit buyers seeking minimal IT involvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains premium deployment rates through federal modernization mandates, while Germany enforces stricter data residency protocols that favor on-premises architectures. Japan and the United Kingdom follow divergent procurement patterns shaped by distinct regulatory timelines and cloud adoption maturity.
United States
Financial services firms in New York and San Francisco drive AI-powered internal knowledge retrieval adoption. SEC cybersecurity disclosure rules mandate sub-second retrieval for incident response audits. Federal agencies in Washington D.C. execute modernization contracts under cloud-first directives.
Germany
Manufacturing conglomerates in Munich and Stuttgart specify on-premises deployments to satisfy national data localization statutes. GDPR Article 22 enforcement requires explainable search systems with auditable retrieval paths. Industrial clusters along the Rhine-Ruhr corridor integrate legacy ECM systems with hybrid architectures.
United Kingdom
Professional services firms in London embed search into client-facing portals for precedent discovery. The Information Commissioner's Office interprets automated decision-making rules to cover AI-augmented workplace systems. Tech procurement in the Cambridge-Oxford corridor concentrates on API-first platforms.
Japan
Automotive suppliers in Toyota City and Nagoya prefer managed service models with guaranteed latency thresholds. METI guidelines on data governance shape enterprise software procurement criteria. Financial institutions in Tokyo deploy neural re-ranking for contract clause prioritization.
France
Government agencies in Paris deploy hybrid configurations to balance accessibility with classified document protection. CNIL enforcement of GDPR Article 22 drives demand for explainability dashboards. Pharmaceutical laboratories in Lyon specify air-gapped security boundaries for sensitive research archives.
Enterprise Search Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms capturing developer-led procurement while legacy vendors defend installed-base relationships. The vendor base concentrates around three strategic archetypes: open-core distributors sustaining developer mindshare, commerce-integrated specialists anchoring service-cloud ecosystems, and generative AI augmenters targeting workplace knowledge retrieval. Dominant competitive moves include API-first embedding into proprietary applications and consumption-metered pricing negotiations for episodic research spikes.
Within the generative AI augmentation tier, Glean exemplifies workplace knowledge retrieval specialization. Coveo occupies a position among commerce-integrated specialists with service-cloud embedding capabilities. Elastic represents the open-core distribution archetype across DevOps environments.
| Leading Market Players |
|---|
| Guru |
| GoSearch |
| Glean |
| Google Cloud Search |
| Microsoft 365 Copilot Search |
| Coveo |
| Lucidworks |
| Algolia |
| Elastic |
| Others |
Cost & Logistics Intelligence
Horizontal integration across cloud infrastructure layers anchors supply positioning and pricing power for enterprise search vendors. Consolidated control over GPU clusters, embedding pipelines, and vector storage compresses cost structures while enabling consumption-metered SaaS tiers that undercut perpetual-license competitors. German and Swiss data localization mandates force costly multi-region architectures that inflate operational overhead and compress margins for vendors serving European regulated industries.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for cloud-native search platforms as hyperscaler competition intensifies. Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with differentiation anchored in ISO 27001 certification status and query-volume burst allowances. Pricing pressure stems from GPU compute cost volatility eroding flat-rate SaaS margins. Mid-market buyers exhibit highest price sensitivity, while federal agencies and financial services firms tolerate premium tiers for FedRAMP and SEC compliance features.
Supply Chain Analysis
Freight costs for specialized AI accelerators and high-bandwidth memory modules factor marginally into total cost structures compared with cloud egress fees and cross-border data transfer tariffs. Supply concentrates in Taiwan for advanced GPUs, South Korea for HBM memory, and the United States for cloud orchestration software. Raw material dependencies span silicon wafers, rare earth elements for magnetic storage, and cobalt for power infrastructure. Single-source vulnerability around NVIDIA's datacenter GPU allocation creates procurement bottlenecks. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with embedded solution architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise search vendors can exploit geographic arbitrage between United States federal modernization budgets and European compliance premiums. HIPAA audit requirements in American healthcare systems create pricing tolerance absent in cost-constrained non-profit deployments.
For Market Incumbents: Acquire specialized vector database engineering teams to compress latency thresholds below 100 milliseconds and defend against open-source embedding framework commoditization. Invest in FedRAMP and ISO 27001 certification pipelines to sustain premium positioning in government and financial services procurement cycles. Channel control through hyperscaler marketplace listings captures procurement workflows that bypass traditional RFP processes. For New Entrants and Emerging Players: Mid-market manufacturing conglomerates in Germany's Rhine-Ruhr corridor represent an underserved buyer archetype with legacy Documentum installations requiring hybrid cloud migration. White-space targets include HIPAA-compliant clinical decision support for regional hospital systems and AI-augmented maintenance documentation for Japanese automotive suppliers. Go-to-market leverage rests on pre-built connectors for Siemens Teamcenter and SAP PLM that eliminate custom integration timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional managed service providers because data residency fragmentation forces localized operational footprints that resist pure SaaS consolidation. Platform-rollup viability extends across a 5-10 year window as embedding model commoditization compresses standalone search vendor margins. Acquisition target archetype: hybrid-cloud specialists with existing German, French, and Swiss data center presence. Signal to watch: CNIL and German data protection authority enforcement patterns around GDPR Article 22 explainability mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding search into ServiceNow and Salesforce workflows captures procurement budgets without standalone RFP cycles. |
| Acquisition of Specialist Firm | Vector database engineering teams compress inference latency below real-time conversational thresholds. |
| Geographic Expansion | FedRAMP-authorized cloud regions unlock United States federal modernization contract flows. |
| Strategic Partnership | Hyperscaler marketplace listings route procurement through existing cloud commit structures. |
| Product Launch | Explainability dashboards satisfy CNIL and German DPA enforcement of GDPR Article 22. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged CTOs at financial services firms, IT procurement officers in federal agencies, platform engineers at SaaS vendors, and integration specialists at systems integrators. Secondary validation drew from SEC cybersecurity disclosure filings, hyperscaler capex disclosures, FedRAMP authorization databases, and GDPR enforcement tracker records. Bottom-up deployment estimates across cloud, hybrid, and on-premises configurations triangulated against top-down vendor revenue attribution.
Historical reference periods anchored the forecast window to pre-pandemic baseline adoption and post-2022 generative AI inflection points. The analytical framework modeled deployment model, organization size, vertical industry, and integration complexity dimensions across the projection horizon. CAGR derivation incorporated vector database maturation curves, GPU cost deflation assumptions, and regulatory compliance timeline accelerations specific to EU AI Act implementation phases.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than custom integration engagements due to standardized billing data availability. Forecasts reflect documented assumptions around GPU supply constraints, data localization statute enforcement intensity, and open-source embedding model capability advancement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Intellectual Property Software Market
Software & Services
Relational Database Management System Market
Software & Services
Quality Management Software Market
Software & Services
Email Checker Tools Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Cursor Reviewer Market
Software & Services
Global Customer Experience Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Software Containers Market
Software & Services
Global Florist Software Market
Software & Services
Discount Management Software Market
Software & Services
Photo Editing Software Market