
 Global Conversational Computing Platform Market | 2026-2036
Global Conversational Computing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conversational Computing Platform Market Foresight
Multi-source AI model procurement is realigning how enterprises build conversational capabilities. Microsoft Corporation leverages its Azure cloud footprint to anchor enterprise deployments across hybrid environments. Alphabet Inc. competes through deep learning specialization in natural language understanding pipelines. IBM Corporation differentiates via industry-specific dialog management tools tailored to regulated sectors.
A conversational computing platform integrates natural language processing, machine learning, and speech recognition modules to enable human-like text and voice interactions between users and software systems. These platforms process intent classification, entity extraction, and contextual memory to automate customer support, enterprise workflows, and smart device control. Cloud-based deployment leads the infrastructure segment as organizations prioritize elastic scaling over capital-intensive on-premises installations. Natural language processing occupies the core technology layer where margin pools concentrate due to proprietary model training costs. Customer support applications sustain the largest revenue share among use cases, though banking solutions represent the fastest-expanding vertical as financial institutions automate compliance-heavy interactions.
The EU AI Act, GDPR, and the US FDA's emerging software-as-medical-device guidance shape product standards and market access for conversational platforms handling sensitive data. HIPAA constraints in US healthcare deployments and China's GB standards for algorithmic recommendation systems further fragment regulatory compliance requirements. Stakeholders must monitor divergent national AI governance frameworks to anticipate certification timelines that determine competitive entry windows.
Market Dynamics
EU AI Act compliance deadlines are compressing enterprise deployment timelines for conversational platforms handling biometric data and high-risk automated decisions, forcing vendors to rearchitect intent-classification pipelines around auditable decision trails.
Growth Catalysts
- EU AI Act risk-tier mandates:Financial institutions across Germany, France, and Italy must deploy auditable conversational systems for credit-scoring decisions, creating immediate procurement urgency for compliant platforms.
- Healthcare triage automation:US hospital systems facing nursing shortages are accelerating voice-first patient intake deployments that integrate with Epic and Cerner electronic health record ecosystems.
- 5G edge infrastructure:Low-latency inference at network edge nodes in South Korea and Japan enables real-time conversational processing for industrial field service applications previously constrained by cloud round-trip delays.
Market Restraints
- GPU cluster cost volatility:Training runs for large language models require sustained access to NVIDIA H100 or equivalent accelerators, with spot pricing fluctuations compressing vendor gross margins by double-digit percentages.
- Taiwan semiconductor concentration:Custom AI inference chip fabrication for edge-deployed conversational modules depends on TSMC capacity allocation, creating 18-24 month supply security exposure for platform hardware roadmaps.
- GDPR Article 22 friction:Automated decision-making restrictions limit fully autonomous conversational workflows in EU customer service deployments, requiring human-in-the-loop architectures that degrade cost efficiency targets.
Strategic Opportunities
- Brazilian Portuguese NLP gap:Underdeveloped open-source language models for Brazilian Portuguese create first-mover advantage for platforms investing in São Paulo-based annotation pipelines and local dialect coverage.
- CSRD disclosure automation:EU corporate sustainability reporting mandates require conversational interfaces for stakeholder ESG queries, opening vertical specialization for platforms integrating emissions calculation engines.
- Voice-to-CRM convergence:Salesforce and HubSpot API ecosystems now support bi-directional conversational data flows, enabling platform vendors to capture recurring revenue through native integration marketplaces rather than standalone licenses.
Industry Challenges
- Prompt engineering talent scarcity:Production-grade conversational systems require specialists capable of fine-tuning retrieval-augmented generation pipelines, with median time-to-hire exceeding four months in competitive labor markets.
- ISO 42001 certification timelines:AI management system audits for enterprise procurement eligibility extend vendor sales cycles by 6-9 months, straining cash conversion for mid-stage platform providers.
- Legacy IVR integration complexity:Fortune 500 contact centers maintain decades-old telephony infrastructure that resists API-native conversational handoffs, requiring costly middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conversational Computing Platform Market |
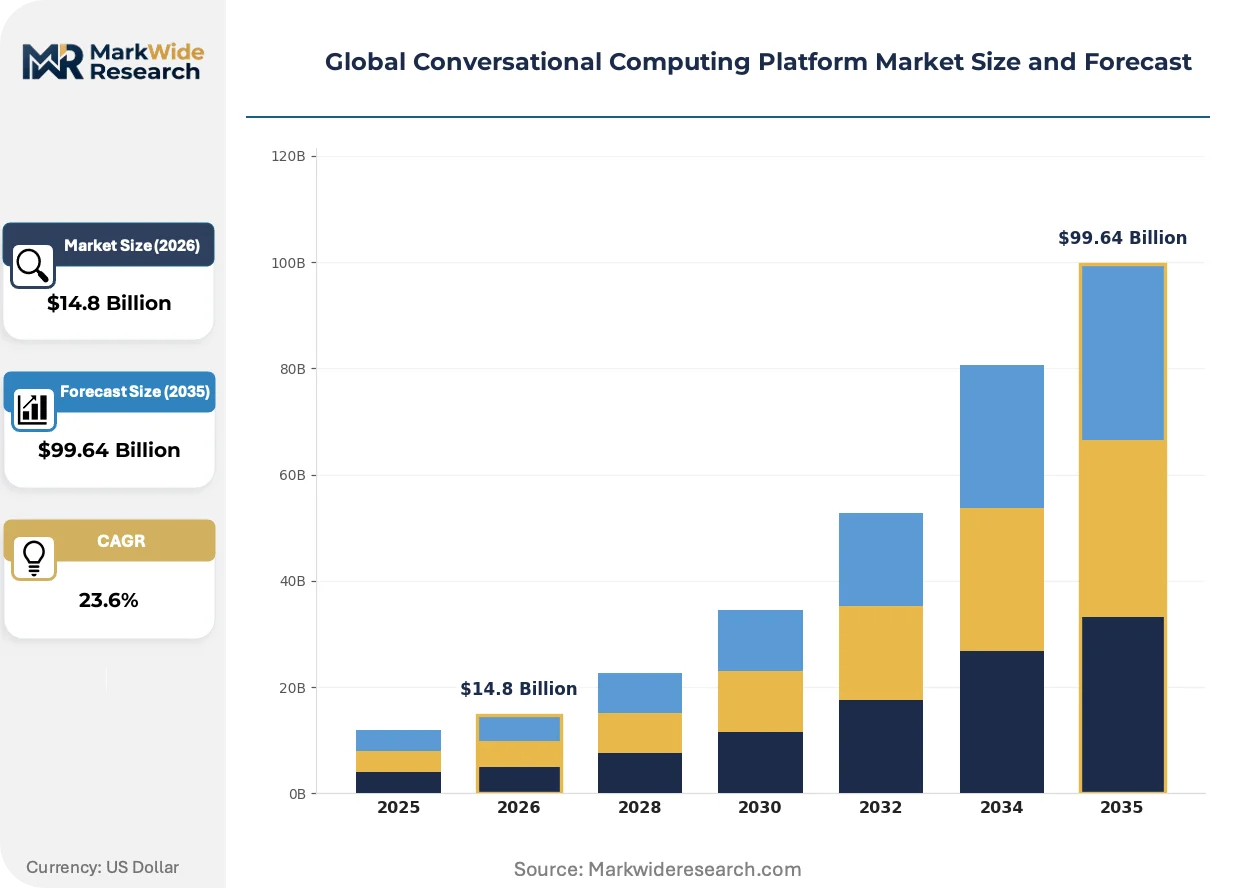
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $99.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Speech Recognition, Text-to-Speech, Sentiment Analysis, Dialog Management Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Customer Support, Virtual Assistants, Enterprise Automation, Smart Devices, Education Platforms, Banking Solutions End User: Financial Institutions, Retail Chains, Telecommunications Providers, Educational Institutions, Government Agencies |
| Companies Covered | Microsoft Corporation, Alphabet Inc., IBM Corporation, Amazon Web Services, Inc., Oracle Corporation, Nuance Communications, Inc., SAP SE, Salesforce Inc., Artificial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conversational Computing Platform Market Shifts & Advancements
Foundation model commoditization is fragmenting competitive advantage away from raw linguistic capability toward orchestration layers that route queries across specialized inference endpoints. Vendors now differentiate through vertical data moats rather than generalist conversation quality.
Retrieval-augmented generation architecture is modularizing how enterprises deploy conversational knowledge systems. Manufacturing quality-control teams in Germany adopt componentized RAG pipelines that separate document embedding, vector storage, and response generation into independently upgradeable subsystems. This decomposition slashes vendor lock-in and enables point substitution of embedding models as Hugging Face releases improved encoders.
EU AI Act high-risk system registration requirements are restructuring product liability frameworks for conversational platforms processing insurance claims or medical triage. Vendors serving Dutch and Spanish financial services markets now embed model cards, training data provenance logs, and human oversight audit trails as standard deliverables. Compliance engineering headcount ratios have doubled relative to core ML research staffing across mid-tier European platform providers.
Enterprise buying committees are consolidating conversational computing procurement under centralized AI governance offices rather than distributed departmental IT budgets. US Fortune 1000 organizations increasingly mandate enterprise architecture review for any departmental chatbot deployment exceeding 500 monthly active users. This centralization favors vendors with FedRAMP authorization or SOC 2 Type II attestation, disqualifying point solutions lacking enterprise-grade security documentation.
Global Conversational Computing Platform Market Segmentation
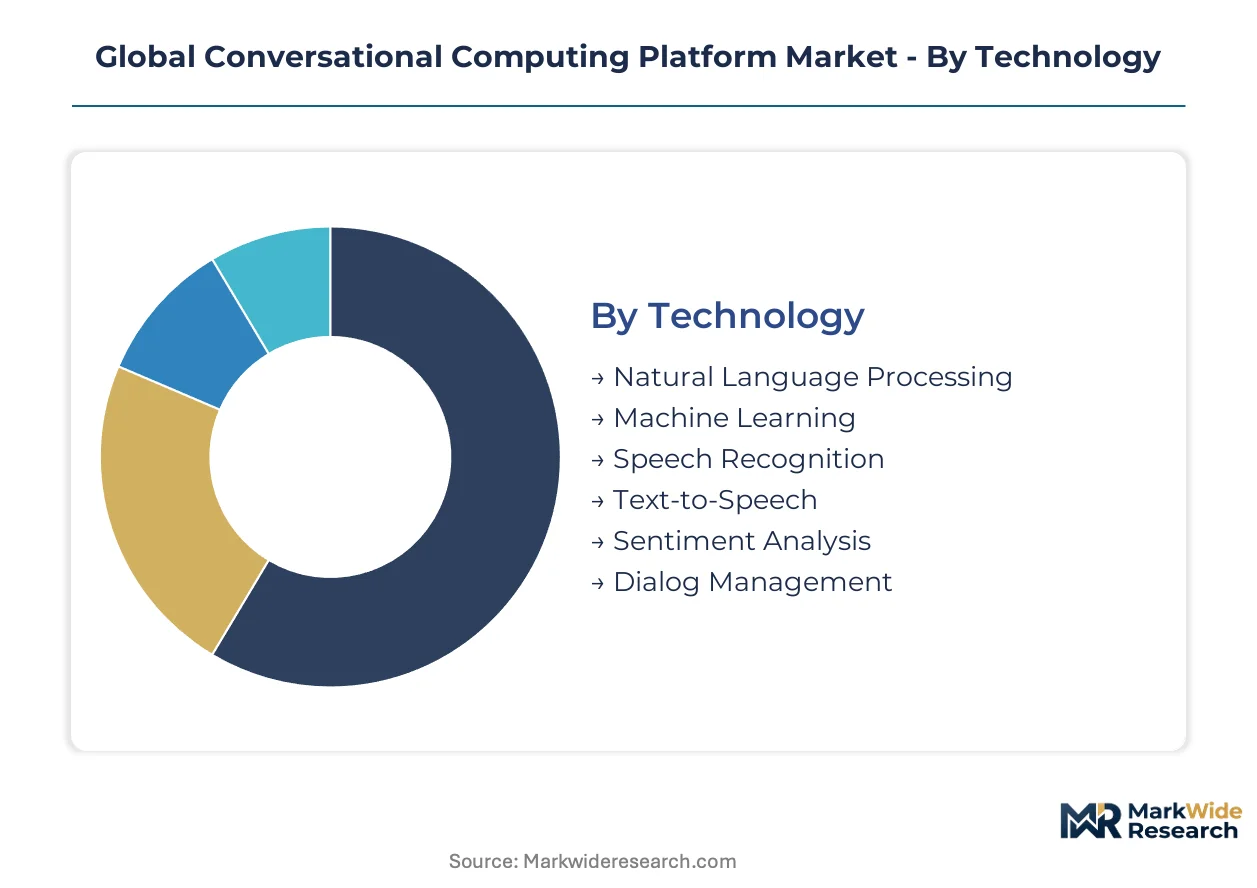
Conversational computing platforms fragment across four critical dimensions that determine vendor specialization and procurement patterns. Technology choices dictate model training costs and inference latency. Deployment modes reflect enterprise risk tolerance for data sovereignty. Application verticals concentrate regulatory exposure differently. End-user sectors impose distinct compliance architectures that reshape product roadmaps.
Technology:
Supply concentration in GPU clusters and proprietary foundation models is compressing margins for generalist NLP providers while rewarding specialized orchestration layers.
- Natural Language Processing:Core linguistic engines handle tokenization, syntactic parsing, and semantic embedding. Financial institutions in Frankfurt and Singapore deploy transformer-based intent classifiers for credit-scoring conversations under EU AI Act high-risk system mandates.
- Machine Learning:Training pipelines for conversational model fine-tuning require sustained accelerator access. US hospital systems in Texas and California prioritize ML-based triage bots that integrate with Epic electronic health records amid nursing workforce constraints.
- Speech Recognition:Acoustic modeling converts audio streams to structured text for voice-first interfaces.
- Text-to-Speech:Neural vocoders generate human-like prosody for outbound conversational responses.
- Sentiment Analysis:Emotional state detection layers enable escalation triggers in customer service workflows.
- Dialog Management:State machines and context windows govern multi-turn conversation flow.
Today's leader: Natural Language Processing. Tomorrow's challenger: Dialog Management.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure models dominating mid-market procurement.
- Cloud-Based:Elastic scaling through hyperscaler infrastructure eliminates upfront hardware commitments. German automotive suppliers in Stuttgart and Munich favor cloud deployments for supplier collaboration portals requiring burst capacity during quarterly procurement cycles.
- Hybrid:Sensitive data processing remains on-premises while model training leverages cloud resources. Japanese manufacturers in Osaka and Nagoya deploy hybrid architectures for quality-control conversational agents handling proprietary design specifications.
- On-Premises:Fully captive infrastructure satisfies strict data residency requirements in defense and intelligence sectors.
- Edge Computing:Low-latency inference at network periphery enables real-time field service applications.
Cloud-Based deployments command current procurement volume. Edge Computing is climbing the fastest as 5G infrastructure matures.
Application:
Volume concentration in customer service automation is diverting R&D investment away from emerging verticals with longer sales cycles.
- Customer Support:Ticket deflection and first-contact resolution dominate enterprise chatbot procurement. Telecommunications providers in São Paulo and Mexico City deploy multilingual support bots to manage prepaid subscriber churn in price-sensitive markets.
- Banking Solutions:Compliance-heavy financial interactions represent steepest expansion trajectory. Dutch and Spanish retail banks automate mortgage pre-qualification conversations with embedded audit trails for EU AI Act high-risk system registration.
- Virtual Assistants:Personal productivity and scheduling agents target knowledge worker segments.
- Enterprise Automation:Internal workflow orchestration through conversational interfaces streamlines HR and IT service desks.
- Smart Devices:Voice control for consumer electronics and industrial equipment.
- Education Platforms:Tutoring and administrative query handling for universities and K-12 systems.
Customer Support sustains revenue leadership. Banking Solutions is gaining share fastest through regulatory-driven procurement urgency.
End User:
Customer type fragmentation creates distinct certification requirements that favor vendors with vertical-specific compliance documentation.
- Financial Institutions:Banks, insurers, and asset managers face stringent model governance mandates. French and Italian institutions under ECB supervision deploy auditable conversational systems for investment advice conversations subject to MiFID II suitability requirements.
- Government Agencies:Public sector procurement prioritizes FedRAMP authorization and SOC 2 attestation. US federal civilian agencies in Washington DC and Denver consolidate chatbot deployments under centralized AI governance offices.
- Retail Chains:Omnichannel customer engagement drives conversational commerce investments.
- Telecommunications Providers:Subscriber service automation at massive scale.
- Educational Institutions:Student services and administrative query handling.
Financial Institutions anchor current enterprise spending. Government Agencies represent the fastest-climbing procurement segment through federal AI procurement guideline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler cloud infrastructure in the United States concentrates enterprise conversational computing deployments, while regulatory divergence across jurisdictions fragments vendor compliance roadmaps and procurement timelines.
United States
Federal AI procurement guidelines and FedRAMP authorization requirements drive enterprise adoption in Washington DC and Denver. HIPAA constraints shape healthcare conversational deployments in Texas and California hospital systems. The FDA's emerging software-as-medical-device guidance creates certification bottlenecks for triage automation vendors targeting Epic and Cerner integrations.
Germany
Automotive suppliers in Stuttgart and Munich favor cloud-based conversational portals for supplier collaboration during quarterly procurement cycles. EU AI Act high-risk system mandates force rearchitecture of credit-scoring conversation pipelines around auditable decision trails. Frankfurt financial institutions deploy transformer-based intent classifiers under ECB supervision.
Japan
Manufacturers in Osaka and Nagoya deploy hybrid architectures for quality-control conversational agents handling proprietary design specifications. METI industrial digitalization programs accelerate voice-first field service applications. 5G edge infrastructure in South Korea and Japan enables real-time conversational processing previously constrained by cloud latency.
Brazil
Telecommunications providers in São Paulo deploy multilingual support bots to manage prepaid subscriber churn in price-sensitive markets. Underdeveloped open-source language models for Brazilian Portuguese create first-mover advantage for platforms investing in local annotation pipelines. ANVISA regulatory frameworks shape healthcare conversational deployments.
Netherlands
Dutch retail banks automate mortgage pre-qualification conversations with embedded audit trails for EU AI Act high-risk system registration. CSRD disclosure mandates require conversational interfaces for stakeholder ESG queries. Amsterdam and Rotterdam financial services clusters drive procurement of compliant platforms with model cards and training data provenance logs.
Global Conversational Computing Platform Market Competitive Landscape
Global majors compete with regional champions across compliance documentation and vertical specialization, producing a tiered structure where hyperscaler cloud providers anchor enterprise deployments while mid-stage specialists capture regulated sector niches. The vendor base stratifies into three archetypes: infrastructure-anchored platforms, industry-specific dialog management specialists, and open-source orchestration layer providers. Competitive moves concentrate on FedRAMP and SOC 2 certification attainment, alongside native CRM integration marketplace positioning.
Within the infrastructure-anchored tier, Microsoft Corporation exemplifies hybrid cloud deployment strategies, while Alphabet Inc. occupies a position emphasizing deep learning specialization. IBM Corporation represents the regulated-sector specialist archetype, with industry-specific tooling tailored to financial services compliance requirements. These three entities anchor competitive positioning across divergent procurement evaluation criteria spanning security attestation, vertical data moats, and orchestration capabilities.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Alphabet Inc. |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Oracle Corporation |
| Nuance Communications, Inc. |
| SAP SE |
| Salesforce Inc. |
| Artificial Solutions |
| Others |
Supply & Pricing Matrix
Hyperscaler cloud providers anchor enterprise procurement through sovereign-backed infrastructure commitments, concentrating pricing power among AWS, Azure, and Google Cloud while compressing margins for mid-tier platform vendors dependent on spot GPU capacity. This ownership pattern feeds into supply chain fragility, as vendor pricing discipline weakens when NVIDIA H100 cluster costs spike and TSMC fabrication queues extend.
Pricing Analysis
GPU cluster cost pass-through dominates conversational platform economics, with training-run expenses for large language models compressing vendor gross margins when spot pricing surges. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized enterprise deployments from mid-market SaaS tiers and developer API access. Cost compression in the economy tier is intensifying because open-source model commoditization erodes differentiation. Financial institutions under ECB supervision exhibit lowest price sensitivity due to compliance mandates, while retail chains in São Paulo show highest elasticity.
Supply Chain Analysis
NVIDIA H100 and equivalent AI accelerator supply rests on TSMC fabrication capacity in Taiwan, with CoWoS packaging bottlenecks extending lead times for training infrastructure. Custom inference chip production draws from South Korean memory suppliers and Japanese specialty substrate providers. Single-source vulnerability concentrates in TSMC's advanced-node allocation decisions for AI workloads. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales teams, with native CRM integration marketplaces capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conversational computing platform market compounds steadily through regulatory-mandated procurement urgency, as EU AI Act deadlines and HIPAA constraints force enterprise refresh cycles regardless of macroeconomic conditions.
For Market Incumbents: Deploy compliance engineering capacity expansion to capture EU AI Act high-risk system registration demand from Frankfurt and Amsterdam financial clusters. Fortify FedRAMP authorization pipelines against emerging SOC 2 Type II requirements that disqualify point solutions. Consolidate native Salesforce and HubSpot API integrations to lock in recurring revenue through bi-directional conversational data flows rather than standalone licenses.
For New Entrants and Emerging Players: Launch via São Paulo-based annotation pipelines targeting the Brazilian Portuguese NLP gap, where underdeveloped open-source models create first-mover advantage. Penetrate EU corporate sustainability reporting verticals with conversational interfaces embedding emissions calculation engines for CSRD disclosure automation. Pursue voice-to-CRM convergence through partnership-first go-to-market rather than direct enterprise sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-stage platform providers with ISO 42001 certification gaps that extend sales cycles. Long-term viability favors vendors with vertical data moats in regulated sectors rather than generalist conversation quality. Watch NVIDIA H100 spot pricing volatility as the inflection signal determining vendor margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Engineering | Captures high-risk system procurement urgency from Dutch and Spanish retail banks. |
| Native CRM Marketplace Integration | Locks recurring revenue through Salesforce and HubSpot API ecosystem positioning. |
| FedRAMP Authorization Attainment | Qualifies vendors for US federal civilian agency consolidation under AI governance offices. |
| Retrieval-Augmented Generation Modularization | Reduces vendor lock-in for German manufacturing quality-control teams adopting componentized pipelines. |
| Brazilian Portuguese NLP Investment | Secures first-mover advantage in São Paulo telecommunications subscriber service automation. |
Research Methodology
Coverage spans the United States, Germany, Japan, Brazil, and the Netherlands, with primary inputs from each market cluster. The analysis combines structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation through SEC filings, hyperscaler capex disclosures, EU regulatory filings, and hospital procurement databases. Bottom-up deployment tracking and top-down infrastructure spend analysis triangulate market sizing across the analysis window.
Rate-of-change decomposition separates baseline enterprise SaaS growth from regulatory-driven procurement acceleration and edge computing infrastructure buildout. Segmentation dimensions modeled include deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs derive from elasticity-adjusted spend projections and compliance deadline clustering. Industry-specific inputs incorporate EU AI Act implementation timelines and Epic EHR integration certification queues.
Several conditions sit outside the modeled scope, including sovereign AI chip fabrication breakthroughs, TSMC capacity reallocation shocks, and foundation model open-source releases that abruptly commoditize linguistic capability. Forecasts reflect documented assumptions about regulatory enforcement consistency and hyperscaler pricing discipline. A small set of named triggers warrants ongoing watch: NVIDIA supply allocation decisions, ISO 42001 audit backlog resolution, and 5G edge node deployment velocity in South Korea and Japan.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Deep Learning Market