
 Global Electronic Design Automation Tools (EDA) Market | 2026-2036
Global Electronic Design Automation Tools (EDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Design Automation Tools (EDA) Market Foresight
Platform bundling is consolidating buyer preference toward integrated design suites spanning logic synthesis through physical verification. Synopsys Inc. leverages its breadth across simulation and verification to anchor enterprise relationships with leading foundries. Cadence Design Systems Inc. sustains R&D intensity in custom analog and mixed-signal flows. Siemens EDA differentiates through tight integration with manufacturing execution systems and multi-domain system design.
Electronic Design Automation Tools comprise software environments that enable integrated circuit and system-level design through algorithmic transformation of hardware description languages into manufacturable mask layouts, operating at process nodes measured in nanometers with verification coverage demands exceeding billions of simulation cycles. The primary commercial purpose is reduction of design cycle time and silicon respin risk for semiconductor devices. Physical design and verification tools capture the deepest margin pools as process complexity escalates at advanced nodes, while simulation demand expands fastest among mid-tier fabless entrants targeting automotive and edge AI silicon. Application-specific integrated circuit flows retain structural importance for high-volume mobile and datacenter processors.
The EU Chips Act and U.S. CHIPS and Science Act are reshaping foundry location decisions and design-tool procurement patterns across subsidized greenfield projects. China's MIIT dual carbon goals and indigenous semiconductor directives are redirecting domestic EDA procurement toward locally developed alternatives for mature-node chips. ISO 26262 functional safety mandates in automotive electronics are forcing verification tool upgrades that trace failure modes from register-transfer level through gate-level implementation. Stakeholders must monitor how export control expansions affect cross-border collaboration features within cloud-hosted design environments.
Market Dynamics
Platform consolidation around cloud-native EDA architectures is compressing procurement cycles and displacing perpetual license models across fabless design houses.
Growth Catalysts
- EU Chips Act subsidies:Greenfield fab investments in Germany and France are mandating advanced verification tool suites for domestic design centers.
- Automotive functional safety mandates:ISO 26262 traceability requirements from register-transfer level through physical implementation are forcing tool upgrades at tier-1 suppliers.
- 3nm process node migration:Taiwan and South Korea foundry expansions are pulling computational lithography and multi-patterning software demand.
Market Restraints
- PhD-level talent scarcity:Physical design and formal verification expertise concentrates at a handful of US and Israeli engineering clusters.
- Foundry-process lock-in:Proprietary design kits from Taiwan Semiconductor Manufacturing Company and Samsung Foundry create switching costs that fragment tool standardization.
- Export control friction:US Bureau of Industry and Security restrictions on China-bound EDA exports are bifurcating cloud collaboration architectures.
Strategic Opportunities
- India PLI scheme for semiconductors:Design-linked incentives are attracting captive EDA tool development for mature-node analog chips.
- Photonics-electronics co-design:Silicon photonics foundry services are opening unmet demand for multi-physics simulation environments.
- Subscription monetization:Pay-per-simulation-hour models are penetrating mid-tier fabless entrants previously priced out of enterprise suites.
Industry Challenges
- Multi-die packaging complexity:Chiplet assembly verification requires new thermal-electrical-mechanical co-simulation competencies that strain legacy team structures.
- AI-generated code validation:Large language model-assisted hardware description language authoring is outpacing formal equivalence checking methodologies.
- Cross-border data residency:Cloud-hosted design environments face sovereignty requirements from EU GDPR and China's data localization rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Design Automation Tools (EDA) Market |
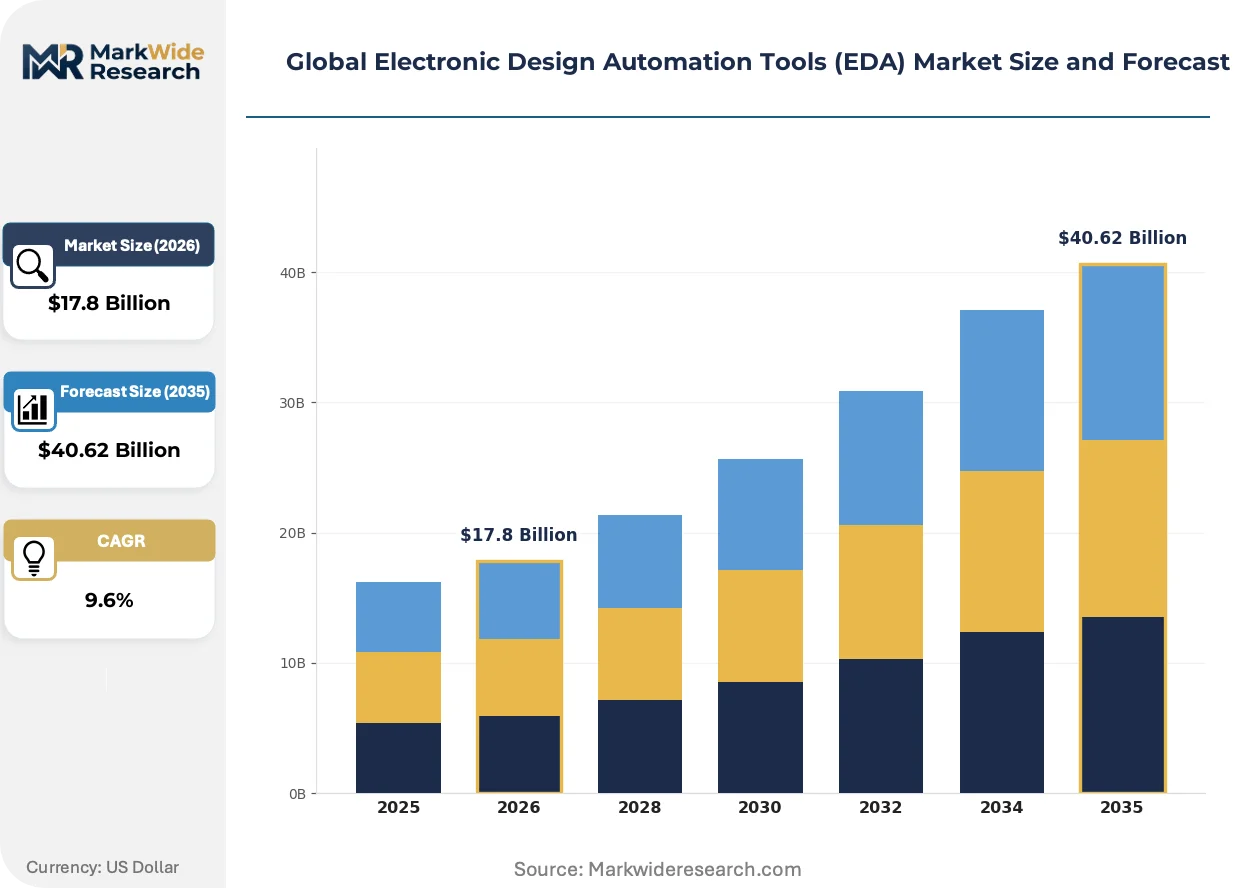
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $40.62 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Logic Synthesis, Simulation, Verification, Physical Design, Layout, Circuit Design Technology: Field-Programmable Gate Array, Application-Specific Integrated Circuit, System-on-Chip, Full Custom Design, Semi-Custom Design Application: Consumer Electronics, Telecommunications, Aerospace & Defense, Semiconductor Fabrication, Embedded Systems End User: Chip Designers, Electronic Manufacturing Services, Integrated Circuit Fabricators, Research & Development Labs |
| Companies Covered | ANSYS Inc., Zuken Ltd., Synopsys Inc., Altium Limited, Silvaco Inc., Cadence Design Systems Inc., Keysight Technologies Inc., Arteris Inc., Siemens EDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Design Automation Tools (EDA) Market Shifts & Advancements
Computational intensity at advanced nodes is forcing algorithmic breakthroughs in parallel simulation and machine learning-accelerated optimization.
Machine learning-driven place-and-route is converging with reinforcement learning frameworks to compress physical design closure timelines. Fabless AI accelerator startups in the United States are adopting these flows fastest, cutting iteration counts from hundreds to dozens. The structural consequence is a margin squeeze on traditional manual floorplanning services.
REACH substance restrictions and EU AI Act transparency mandates are forcing disclosure of training data provenance in AI-assisted design tools. European automotive OEMs now require supply-chain documentation spanning EDA tool training sets through mask fabrication chemicals. German and French regulators are inspecting cloud provider certifications for design environment hosting.
Buying committees at fabless semiconductor firms are unbundling verification tool procurement from bundled enterprise agreements. Mid-size design houses in Israel and the United Kingdom are selecting best-of-breed point tools over integrated suites. This fragmentation is most visible in formal property checking and emulation hardware segments where specialized vendors capture share.
Global Electronic Design Automation Tools (EDA) Market Segmentation
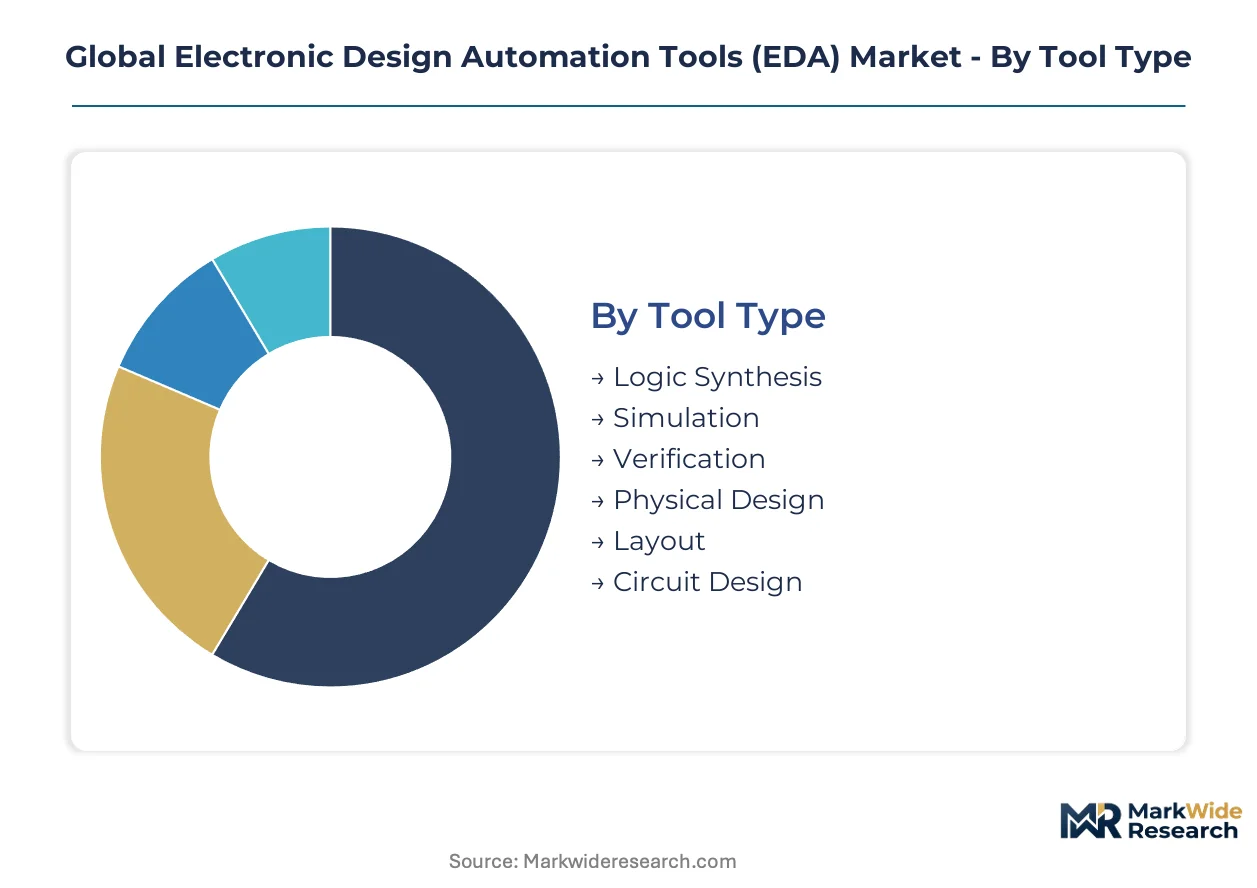
EDA tool segmentation reveals distinct capital requirements and margin profiles across design workflows. Tool type and technology choices determine upfront licensing costs and talent intensity, while application and end-user segments dictate procurement cycles and customization depth.
Tool Type:
Capital intensity peaks in verification and physical design suites requiring specialized compute infrastructure and PhD-level expertise.
- Logic Synthesis:Algorithms transform hardware description languages into gate-level netlists through technology mapping and timing optimization. Demand clusters at fabless AI accelerator startups in the United States seeking rapid design iteration for inference chips.
- Simulation:Event-driven and cycle-accurate modeling environments validate functional correctness before silicon commitment. Taiwan and South Korea foundry customers are expanding simulation farm capacity to handle billion-cycle regression suites for 3nm processors.
- Verification:Formal property checking and emulation hardware catch corner-case failures. ISO 26262 mandates from German automotive OEMs are forcing upgrades at tier-1 suppliers.
- Physical Design:Place-and-route engines optimize power, performance, and area tradeoffs at advanced nodes. Proprietary design kits from Taiwan Semiconductor Manufacturing Company and Samsung Foundry create foundry-specific workflow lock-in.
- Layout:Mask preparation and design rule checking tools bridge design-to-manufacturing handoffs. EU Chips Act subsidies for German greenfield fabs are pulling layout tool procurement.
- Circuit Design:Schematic capture and analog simulation environments serve mixed-signal and RF design. Custom analog flows at Israeli and United Kingdom design houses favor best-of-breed point tools over integrated suites.
Most installed capacity flows through Physical Design. Expansion is steepest in Verification.
Technology:
Application complexity and non-recurring engineering costs separate programmable logic from full-custom silicon development paths.
- Field-Programmable Gate Array:Reconfigurable logic devices enable rapid prototyping and low-volume production without mask costs. Mid-tier fabless entrants in the United States targeting edge AI inference favor FPGA-to-ASIC migration flows.
- Application-Specific Integrated Circuit:Hardwired logic delivers optimal power efficiency for high-volume mobile and datacenter processors. Taiwan and South Korea foundry expansions are pulling ASIC design tool demand at 3nm nodes.
- System-on-Chip:Integration of processors, memory, and accelerators on single die demands multi-domain co-design. Multi-die packaging complexity is straining legacy verification methodologies at chiplet-focused design houses.
- Full Custom Design:Transistor-level optimization for analog, RF, and memory circuits requires specialized device simulation. Cadence Design Systems sustains R&D intensity in this segment for high-speed SerDes and PLL design.
- Semi-Custom Design:Standard cell-based implementation balances optimization leverage with design velocity. India PLI scheme design-linked incentives are attracting captive tool development for mature-node analog chips using semi-custom flows.
Volume concentration sits with Application-Specific Integrated Circuit. System-on-Chip is climbing the fastest.
Application:
Safety-critical and high-reliability end-uses impose the steepest verification tool requirements and longest qualification cycles.
- Consumer Electronics:Mobile and wearable silicon drives aggressive power-performance-area optimization at leading nodes. Fabless design houses in the United States prioritize cloud-based EDA platforms for rapid consumer product cycles.
- Telecommunications:Baseband and infrastructure processors require mixed-signal RF integration and signal integrity analysis. 5G base station deployments are pulling electromagnetic simulation demand.
- Aerospace & Defense:Radiation-hardened and high-reliability designs mandate formal verification and fault simulation. US Bureau of Industry and Security export controls are bifurcating cloud collaboration architectures for defense-linked programs.
- Semiconductor Fabrication:Process development and yield ramping depend on computational lithography and multi-patterning software. Taiwan and South Korea foundry expansions anchor this segment's tool demand.
- Embedded Systems:Microcontroller and IoT edge designs concentrate at mature nodes with cost-sensitive tool budgets. Subscription monetization through pay-per-simulation-hour models is penetrating this segment.
Revenue weight centers on Semiconductor Fabrication. Aerospace & Defense carries the steepest qualification burden.
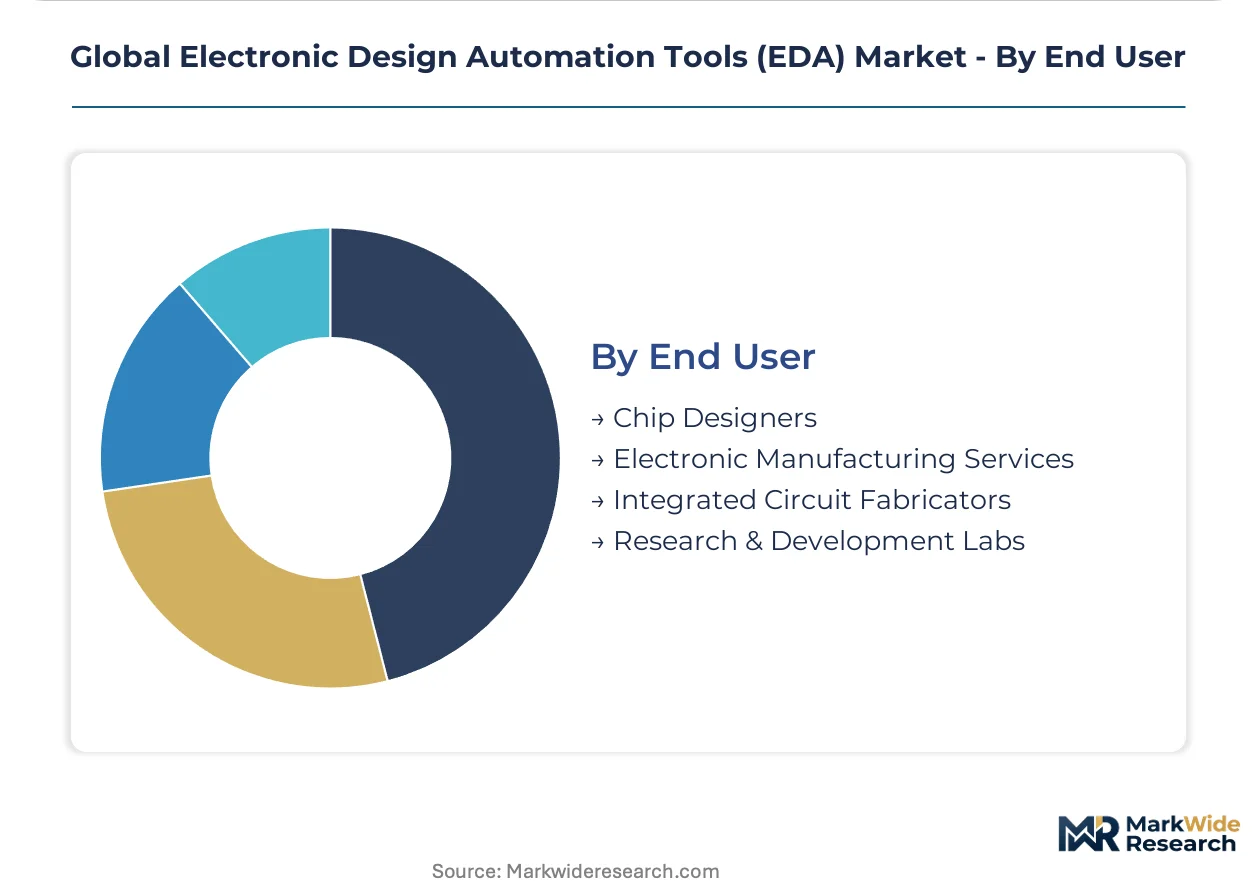
End User:
Procurement scale and technical sophistication separate enterprise fabless designers from contract manufacturing services.
- Chip Designers:Fabless semiconductor firms own full design flow responsibility from architecture through tapeout. Platform bundling is consolidating buyer preference toward integrated suites spanning logic synthesis through physical verification.
- Electronic Manufacturing Services:Contract manufacturers provide design-for-manufacturing and test services post-tapeout. EMS providers in Taiwan and Mexico are expanding DFM tool adoption for advanced packaging assembly.
- Integrated Circuit Fabricators:Foundries and IDMs develop process design kits and reference flows for customer enablement. Proprietary design kits from Taiwan Semiconductor Manufacturing Company and Samsung Foundry fragment tool standardization.
- Research & Development Labs:University and government laboratories explore novel devices and architectures. Cloud-native EDA architectures are compressing procurement cycles at academic institutions previously locked out of enterprise licensing.
Spending dominance rests with Chip Designers. Integrated Circuit Fabricators are gaining share fastest through foundry-developed reference flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic Design Automation Tools originated in United States research laboratories during the 1970s, with commercialization scaling through Silicon Valley software houses. The industry now distributes across three dominant technology clusters.
United States
Fabless AI accelerator startups in California and Texas drive cloud-based EDA platform adoption. The CHIPS and Science Act directs subsidies toward domestic design capacity in Arizona and New York. Boston-area research institutions compress procurement cycles for academic licensing.
Taiwan
Foundry expansions by Taiwan Semiconductor Manufacturing Company pull computational lithography and multi-patterning software demand. The National Development Council coordinates domestic design-tool procurement for mature-node chips. Hsinchu Science Park anchors physical design verification tool deployment.
South Korea
Samsung Foundry and SK Hynix expand simulation farm capacity for billion-cycle regression suites. The Ministry of Trade, Industry and Energy funds indigenous EDA alternatives under K-Semiconductor Belt initiatives. Pangyo Techno Valley concentrates emulation hardware procurement.
Germany
Automotive OEMs in Stuttgart and Munich mandate ISO 26262 traceability upgrades at tier-1 suppliers. The EU Chips Act subsidizes greenfield fab investments in Dresden and Magdeburg. Bavarian regulators inspect cloud provider certifications for design environment hosting.
China
MIIT dual carbon goals redirect domestic EDA procurement toward locally developed alternatives. Shanghai and Beijing design houses accelerate mature-node analog chip flows. Shenzhen clusters face export control friction from US Bureau of Industry and Security restrictions.
Global Electronic Design Automation Tools (EDA) Market Competitive Landscape
The competitive structure tilts toward integrated suite providers with foundry-certified reference flows. Three firms capture dominant share across simulation, physical design, and verification segments. Strategic archetypes include: full-stack platform bundlers, analog-mixed-signal specialists, and manufacturing-execution integrators. Competitive moves concentrate on cloud-native architecture migration and AI-assisted optimization licensing.
Among United States-based platform providers, Synopsys Inc., Cadence Design Systems Inc., and ANSYS Inc. exemplify the dominant archetypes. Synopsys occupies a position spanning logic synthesis through emulation hardware. Cadence anchors custom analog and mixed-signal workflow depth. ANSYS represents multi-physics simulation expansion beyond traditional electronic domains. Siemens EDA, operating from German industrial roots, sits within the manufacturing-execution integration tier. These five names structure procurement committee evaluations across fabless design houses and foundry reference flow certifications.
| Leading Market Players |
|---|
| ANSYS Inc. |
| Zuken Ltd. |
| Synopsys Inc. |
| Altium Limited |
| Silvaco Inc. |
| Cadence Design Systems Inc. |
| Keysight Technologies Inc. |
| Arteris Inc. |
| Siemens EDA |
| Others |
Supply & Pricing Matrix
Captive integration into foundry-certified reference flows anchors both supply security and pricing power for EDA suite providers. Synopsys, Cadence, and Siemens EDA maintain backward integration into proprietary design kits from Taiwan Semiconductor Manufacturing Company and Samsung Foundry, creating switching costs that sustain premium positioning against point-tool competitors. This integration choice locks in multi-year enterprise agreements while fragmenting procurement for mid-tier fabless houses seeking best-of-breed alternatives.
Pricing Analysis
Subscription monetization through cloud-native platforms now dominates enterprise procurement, displacing perpetual license models across fabless design houses. Price differentiation rests on certification tier—ISO 26262 functional safety compliance commands substantial premiums from German automotive OEMs—and volume scale, with pay-per-simulation-hour models penetrating cost-sensitive embedded systems segments. Pricing pressure stems from mid-tier entrants in Israel and the United Kingdom unbundling verification tools from bundled suites. Consumer electronics chip designers show highest price sensitivity, while aerospace and defense contractors absorb premium tiers for traceability mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced process node design kits and emulation hardware fabrication. The supply chain draws from United States for algorithmic IP and cloud infrastructure, Germany for manufacturing execution system integration, and India for mature-node analog design services. Raw material dependencies center on specialized compute accelerators, high-bandwidth memory modules, and photonics-electronics co-simulation substrates. Tariff exposure from US Bureau of Industry and Security export controls on China-bound EDA exports fragments cloud collaboration architectures. Distribution runs through direct enterprise sales teams for tier-one foundries, with channel partners serving academic and mid-tier fabless segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in electronic design automation tools rests on cloud infrastructure cost compression and the shift toward premium-tier functional safety certification bundles. Foundry-process lock-in and ISO 26262 mandates create durable pricing power for integrated suite providers.
For Market Incumbents: Extend foundry-certified reference flow coverage into silicon photonics and multi-die packaging verification to defend against point-tool fragmentation. Deepen backward integration into computational lithography algorithms as Samsung Foundry and Taiwan Semiconductor Manufacturing Company advance 3nm nodes. Prioritize R&D investment in machine learning-accelerated place-and-route to compress physical design closure timelines for AI accelerator startups. For New Entrants and Emerging Players: Photonics-electronics co-design environments represent the most penetrable white-space, with unmet demand from silicon photonics foundry services in Germany and the United States. Target mid-tier fabless entrants in India and Israel with subscription-based formal property checking tools priced below enterprise emulation suites. Pursue design-linked incentive partnerships under India's PLI scheme for mature-node analog chips. For Investors and Strategic Acquirers: Roll-up economics work for specialized verification point-tool vendors because buying committee fragmentation at mid-size design houses is accelerating best-of-breed procurement. Long-term viability favors firms with cloud-native architectures and AI-assisted optimization licensing models. Watch for inflection in emulation hardware procurement cycles at South Korean memory fabricators as 3nm process ramps mature.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses procurement cycles at fabless AI accelerator startups in California and Texas. |
| AI-Assisted Optimization Licensing | Reinforcement learning frameworks cut physical design iteration counts from hundreds to dozens. |
| Acquisition of Formal Verification Specialist | Addresses unbundling trend among Israeli and United Kingdom mid-size design houses. |
| Silicon Photonics Co-Design Partnership | Captures demand from German automotive OEMs integrating optical interconnects. |
| ISO 26262 Certification Investment | Unlocks premium-tier pricing from Stuttgart and Munich tier-1 supplier mandates. |
Research Methodology
Direct dialogue with EDA tool procurement officers, fabless semiconductor CTOs, foundry process integration engineers, and academic research lab directors grounded qualitative assessment. Secondary validation drew from SEC 10-K filings of publicly traded design automation firms, foundry capex disclosure reports, EU Chips Act subsidy documentation, and US Bureau of Industry and Security export control registers. Bottom-up segment sizing triangulated against top-down market aggregation across tool type, technology node, and end-user procurement tiers.
Installed base and revenue outputs reflect algorithmic allocation across the analysis window, with segmentation by tool category, process node complexity, deployment model, and regional regulatory cluster. CAGRs derived from regression against semiconductor capital expenditure cycles, foundry capacity expansion timelines, and functional safety mandate adoption curves. Forecast inputs incorporated cloud infrastructure cost trajectories, PhD-level talent availability indices, and export control policy scenario modeling.
The model holds under sustained foundry investment in Taiwan and South Korea and stable US-EU technology trade frameworks; deviation in China-access restrictions or EU AI Act enforcement intensity would shift cloud collaboration architecture demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction and Design Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Order Management Software Market
Software & Services
Machine Translation Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Global Testing Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Lifecycle Management Software Market
Software & Services
Towing Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Braking Systems Software Market
Software & Services
Packaged Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market