
 Denmark Software As a Service (Saas) Market | 2026-2036
Denmark Software As a Service (Saas) Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Software As a Service (Saas) Market Insights
Market Context
Danish cloud infrastructure providers is realigning capacity to serve Nordic enterprise demand. Visma e-conomic A/S leverages deep integration with Danish tax systems to anchor the accounting SaaS segment. team.blue Denmark A/S sustains a broad hosting and business software portfolio across the mid-market. Dixa competes aggressively in customer service platforms, differentiating through real-time conversational AI.
Technical Definition and Segments
Denmark Software As a Service refers to cloud-hosted software applications delivered via internet subscription, typically running on multi-tenant architectures with automated updates and API-first integration protocols, serving commercial and industrial users without local installation. The primary purpose is to replace capital-intensive on-premise software with operational expenditure models that scale elastically with user counts and transaction volumes. Public Cloud deployment leads in raw subscriber numbers while Hybrid Cloud captures the highest-margin enterprise contracts requiring data sovereignty controls. Customer Relationship Management solutions represent the most mature competitive arena, whereas Collaboration Tools generate the fastest growth from distributed workforce adoption. Subscription-Based pricing dominates revenue recognition, though Tiered Pricing structures concentrate margin pools at enterprise tiers.
Regulatory Outlook
The EU GDPR and the EU AI Act impose strict data residency and algorithmic transparency obligations on SaaS vendors operating from Denmark, directly shaping product architecture and liability frameworks. The Danish Business Authority enforces national e-invoicing mandates that force compliance module development across accounting platforms. Stakeholders must monitor how forthcoming EU cybersecurity certification schemes alter procurement criteria for public-sector SaaS contracts.
Market Dynamics
Denmark's SaaS market is restructuring around the EU AI Act's algorithmic transparency mandates, forcing vendors to rearchitect their machine-learning pipelines and data governance frameworks before enforcement deadlines crystallize competitive winners from compliance laggards.
Growth Catalysts
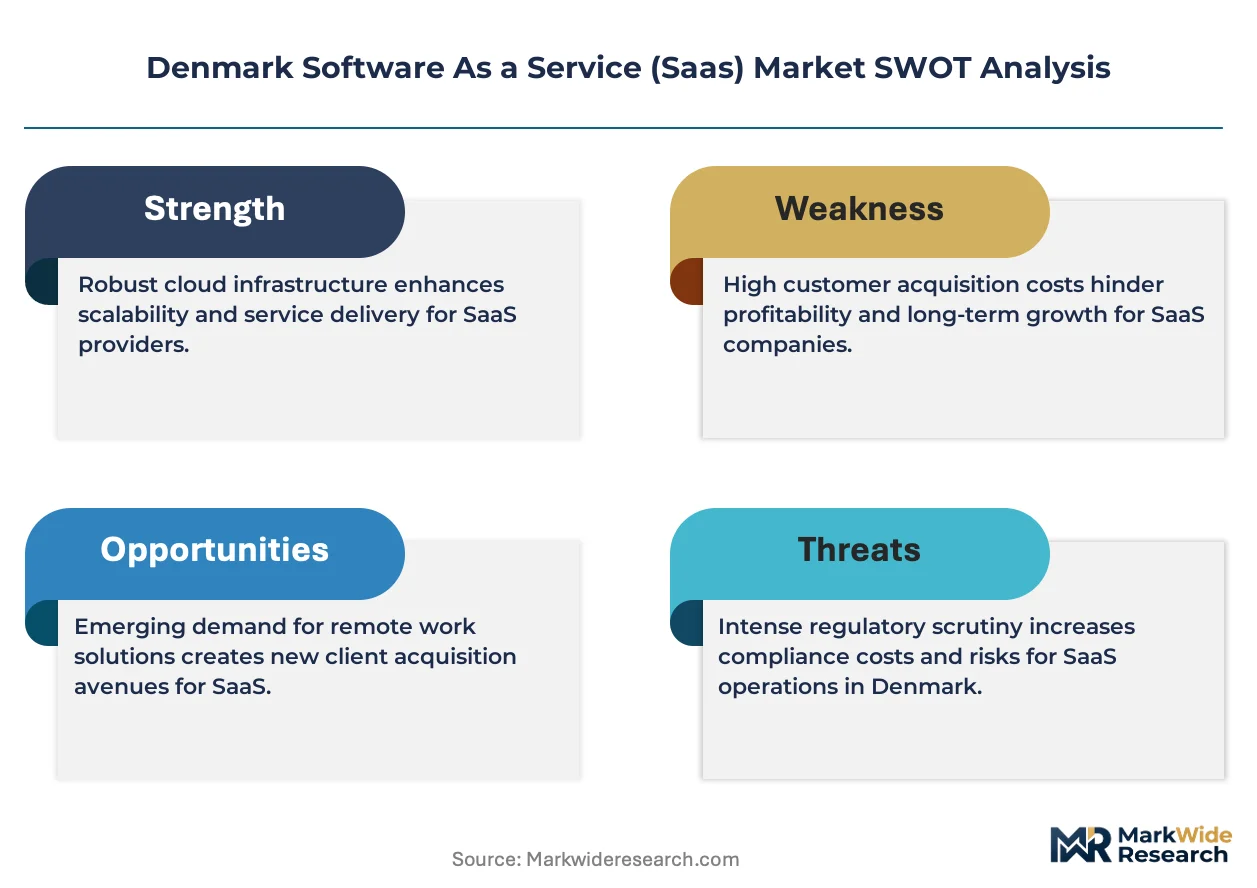
- GDPR-Driven Data Sovereignty:The EU GDPR compels Danish enterprises to favor domestic cloud providers for sensitive workloads, accelerating local infrastructure investment and vendor ecosystem maturation.
- Healthcare Digitization:Danish hospitals and regional health authorities are migrating patient records to cloud-native platforms, creating sustained demand for HIPAA-equivalent compliant SaaS solutions.
- Copenhagen Fintech Cluster:The capital's concentration of payment processors and neobanks generates specialized demand for subscription-based financial infrastructure software.
Market Restraints
- EU AI Act Compliance Costs:The regulation's risk-classification system imposes documentation and audit burdens that disproportionately burden mid-tier SaaS vendors with limited legal resources.
- Power Infrastructure Constraints:Data center electricity demand in Denmark's grid is colliding with renewable transition timelines, creating capacity allocation uncertainty for hyperscale cloud entrants.
- Legacy ERP Entrenchment:SAP and Oracle on-premise installations in Danish manufacturing retain deep workflow integration, extending replacement cycles beyond typical SaaS conversion timelines.
Strategic Opportunities
- Jutland Industrial Corridor:Manufacturing SMEs in Aarhus and Odense remain underpenetrated by vertical SaaS solutions for supply chain and production planning.
- E-Invoicing Mandate Expansion:The Danish Business Authority's phased requirements for real-time VAT reporting create embedded software opportunities within accounting platforms.
- API-First Convergence:The intersection of open banking standards and accounting software interfaces is expanding into automated reconciliation and cash-flow forecasting tools.
Industry Challenges
- Specialized Cloud Engineering Talent:Denmark's technical universities produce insufficient Kubernetes and platform engineering graduates relative to vendor hiring velocity.
- Cross-Border Data Fragmentation:Divergent Nordic interpretations of GDPR adequacy create operational friction for SaaS providers serving Swedish and Norwegian customers from Danish data centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Software As a Service (Saas) Market |
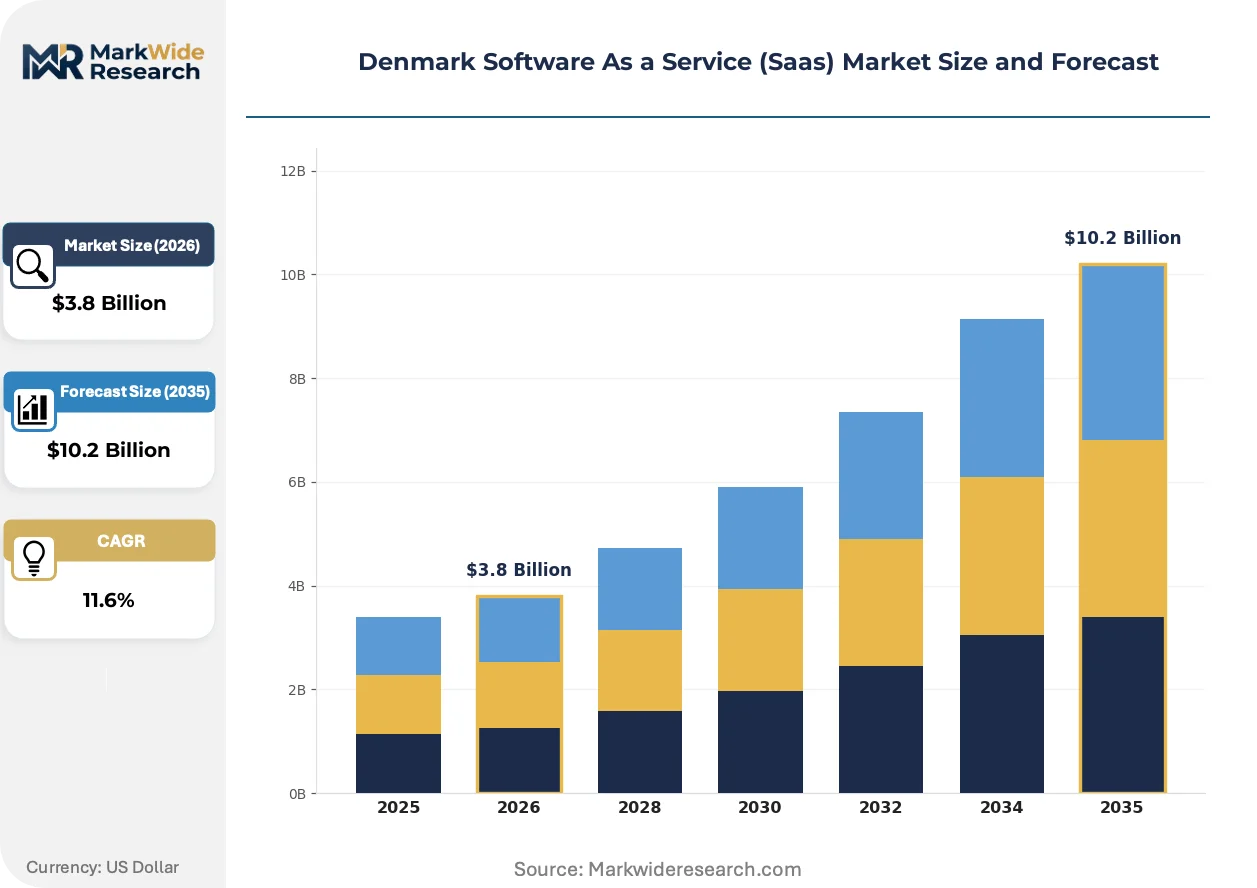
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Collaboration Tools, Customer Relationship Management, Enterprise Resource Planning, Human Resource Management End User: Small Businesses, Medium Enterprises, Large Enterprises, Startups Pricing Model: Subscription-Based, Pay-As-You-Go, Freemium, Tiered Pricing |
| Companies Covered | Visma e-conomic A/S, Veo Technologies ApS, team.blue Denmark A/S, Visma DataLøn A/S, Keylane A/S, SiteHub ApS, SECOMEA A/S, Dixa, Keepit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Software As a Service (Saas) Market Trends and Innovations
Real-time conversational AI is penetrating Danish customer service workflows, while regulatory automation tools and embedded finance modules are reshaping how SaaS vendors capture enterprise spend.
Generative AI copilots are expanding into code completion, contract drafting, and customer support automation within Danish SaaS platforms. Mid-market professional services firms are adopting these tools fastest, compressing the traditional 12-18 month enterprise software evaluation cycle into quarterly procurement decisions. The technology is expanding into adjacent workflow categories previously resistant to automation, including regulatory compliance documentation and multi-jurisdictional tax calculations.
The EU AI Act's risk-tier classification system is mandating algorithmic impact assessments for high-stakes SaaS applications in credit scoring and hiring. Danish vendors must now maintain technical documentation and human oversight protocols that mirror pharmaceutical traceability requirements. Healthcare and financial services SaaS providers face the steepest compliance gradients, with several Copenhagen-based startups restructuring their ML pipelines to segregate prohibited practices from acceptable use cases.
Danish enterprises are unbundling traditional software suites in favor of best-of-breed point solutions connected through native integrations. Procurement departments now evaluate API reliability and webhook latency alongside core feature parity, displacing the monolithic ERP renewal as the default budget anchor. This pattern is most visible in Copenhagen's fintech and professional services clusters, where finance teams assemble custom stacks from 15-20 specialized vendors rather than accepting vendor consolidation pressure.
Denmark Software As a Service (Saas) Market Segmentation
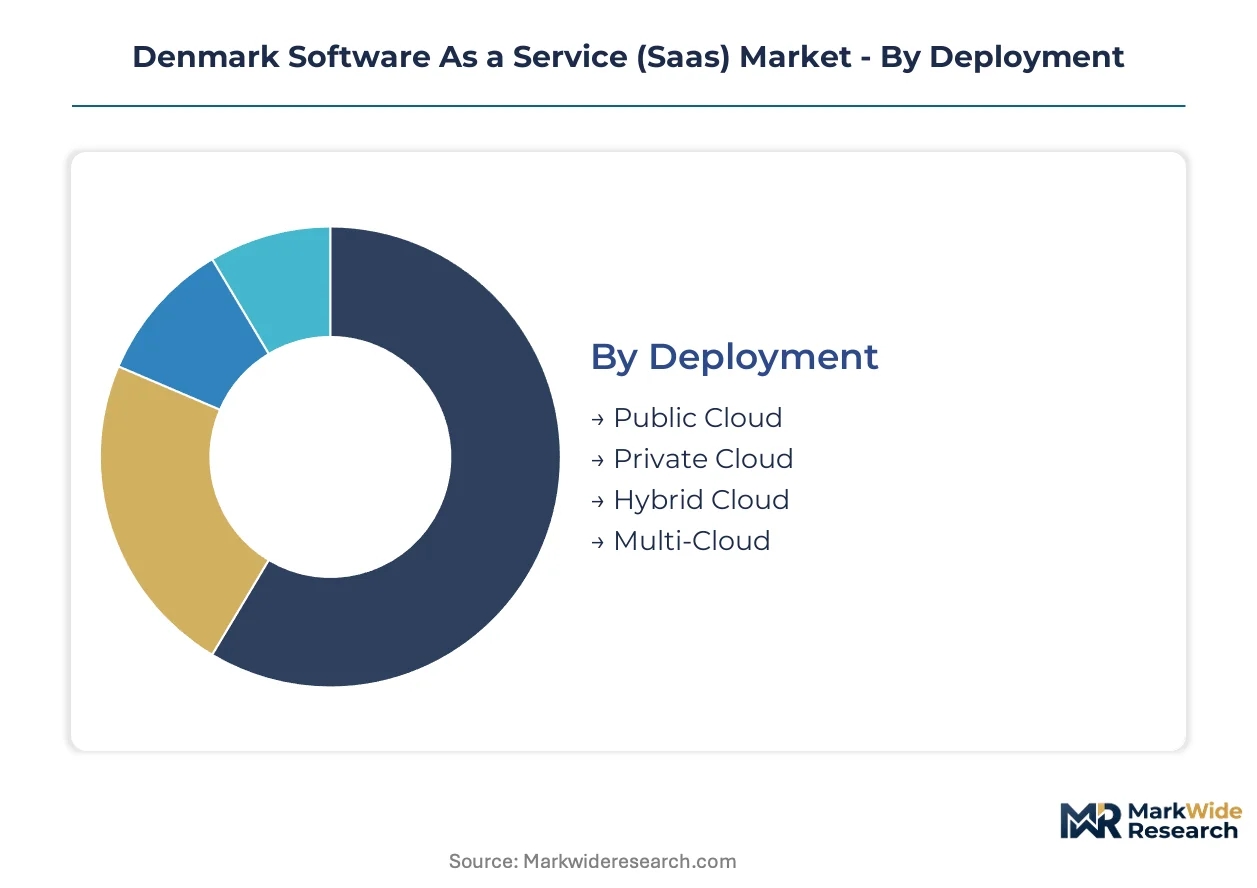
Denmark's SaaS market segments reflect divergent compliance obligations under the EU AI Act and GDPR. Deployment choices determine data residency architectures, while pricing models shape how vendors absorb regulatory documentation costs across customer tiers.
Deployment:
GDPR certification requirements vary sharply across deployment modes, with Public Cloud facing streamlined adequacy assessments while Hybrid Cloud demands bespoke data sovereignty audits.
- Public Cloud:Multi-tenant infrastructure pools compute resources across Danish and EU data centers. Copenhagen fintech clusters favor this mode for rapid scaling, though GDPR Article 44 transfer mechanisms add contractual overhead for US-hosted instances.
- Hybrid Cloud:Workload orchestration splits sensitive patient data across on-premise Danish health authority servers and burst-capacity public nodes. The Danish Patient Safety Authority mandates this architecture for electronic health record systems, creating premium pricing power for compliant vendors.
- Private Cloud:Dedicated single-tenant environments serve defense contractors and critical infrastructure operators under Denmark's Center for Cyber Security guidelines.
- Multi-Cloud:Redundancy across AWS, Azure, and Nordic regional providers mitigates vendor lock-in for Aarhus manufacturing exporters.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
Solution Type:
Application categories align with Denmark's sector-specific digitization priorities, from healthcare workflows to manufacturing supply chains.
- Customer Relationship Management:Mature competitive arena with deep API integration into Danish CVR business registry systems. Visma e-conomic A/S anchors this segment through native tax reporting automation that compresses quarterly compliance cycles.
- Collaboration Tools:Real-time document editing and video conferencing platforms exploded following Denmark's national remote work guidelines. Distributed professional services firms in Copenhagen drive replacement of legacy on-premise productivity suites.
- Enterprise Resource Planning:Cloud-native financial and operational modules displace SAP installations in Odense manufacturing SMEs, though deep workflow integration extends replacement timelines.
- Human Resource Management:Payroll and workforce planning tools face EU AI Act scrutiny when embedding algorithmic hiring assessments, forcing documentation retrofits.
Most mature margin pool: Customer Relationship Management. Steepest adoption curve: Collaboration Tools.
End User:
Organizational scale dictates procurement sophistication and regulatory exposure thresholds.
- Large Enterprises:Centralized IT governance mandates ISO 27001-certified vendors with Danish data center presence. Procurement teams evaluate API reliability and webhook latency alongside core functionality.
- Medium Enterprises:Aarhus and Odense manufacturing clusters seek vertical supply chain modules with native e-invoicing compliance to Danish Business Authority mandates.
- Small Businesses:Copenhagen creative agencies and professional services firms adopt generative AI copilots fastest, compressing traditional software evaluation cycles.
- Startups:Pre-revenue ventures favor freemium tiers with path to scale, though EU AI Act risk classifications complicate ML-powered feature roadmaps.
Highest contract values: Large Enterprises. Fastest decision velocity: Small Businesses.
Pricing Model:
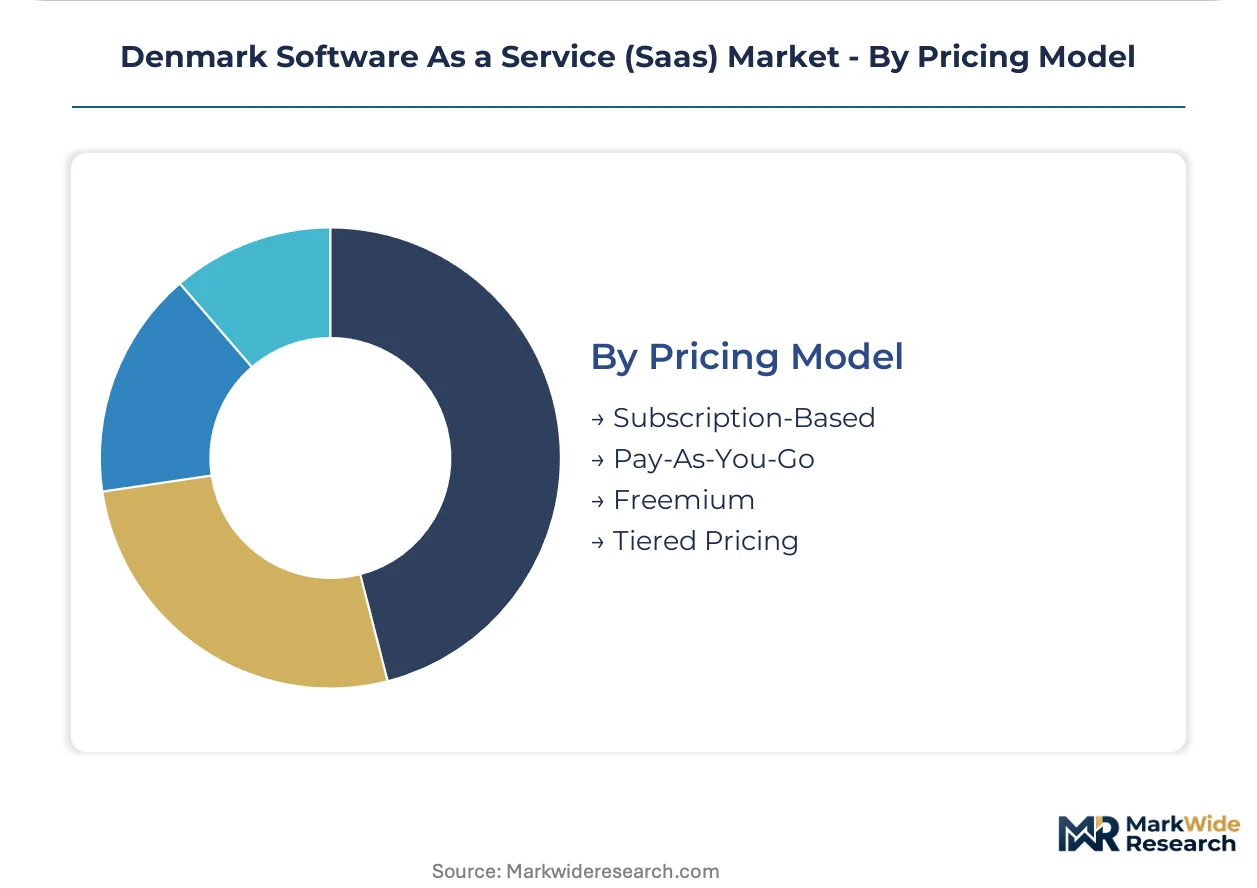
Revenue recognition structures determine how vendors amortize compliance investments across customer lifecycles.
- Subscription-Based:Predictable annual recurring revenue dominates Danish SaaS vendor financial models. Healthcare and fintech procurement departments favor this stability for multi-year budget planning.
- Tiered Pricing:Enterprise tiers capture margin pools through advanced analytics and custom integration support. The Danish Business Authority's phased e-invoicing mandates create upgrade triggers from standard to premium tiers.
- Pay-As-You-Go:Consumption metering suits variable workloads like tax season spikes in accounting platforms, though GDPR audit trails complicate per-transaction billing transparency.
- Freemium:User acquisition engines for collaboration and productivity tools face EU AI Act constraints on data harvesting from free-tier users for model training.
Dominant revenue share: Subscription-Based. Fastest margin expansion: Tiered Pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center capacity in Denmark's Øresund corridor anchors Nordic cloud infrastructure expansion. The country's renewable energy surplus attracts hyperscale facility investments while GDPR compliance requirements shape cross-border service architectures.
United States
Silicon Valley SaaS vendors dominate enterprise workflow automation and generative AI platforms. The SEC's cybersecurity disclosure rules and state-level privacy laws in California and Virginia create compliance complexity for Danish subsidiaries of US parents. Seattle and Austin clusters concentrate DevOps tooling and fintech infrastructure development.
Germany
Industrial software demand from Mittelstand manufacturers drives specialized ERP and supply chain modules. The BSI's IT-Grundschutz certification requirements intersect with GDPR to create dual compliance burdens for vendors serving German-Danish operations. Munich and Stuttgart host automotive-focused SaaS development centers.
United Kingdom
Post-Brexit data adequacy arrangements complicate UK-Denmark cloud service flows despite retained GDPR alignment. London's financial services concentration generates demand for regulatory reporting and risk management platforms. The FCA's operational resilience requirements shape procurement criteria for Danish fintech exporters.
Sweden
Cross-border Nordic integration sustains unified SaaS procurement across Copenhagen-Stockholm-Malmö corridors. The Swedish Authority for Privacy Protection enforces GDPR interpretations that occasionally diverge from Danish Data Protection Agency rulings, creating operational friction. Gothenburg's automotive engineering cluster demands specialized product lifecycle management tools.
Denmark Software As a Service (Saas) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vertical specialization and AI-native architectures. The Danish SaaS market exhibits moderate consolidation around accounting and customer service platforms, with fragmentation persisting in industrial IoT and healthcare verticals. Three archetypes dominate: legacy software vendors migrating cloud-native delivery, born-digital specialists in regulatory-heavy sectors, and Nordic regional challengers leveraging data sovereignty positioning. Competitive moves concentrate on API ecosystem expansion and compliance module pre-certification to accelerate public-sector procurement cycles.
Among Denmark-based operators, Visma e-conomic A/S anchors the accounting automation segment through deep public-sector integration, while team.blue Denmark A/S occupies a position spanning hosting infrastructure and business applications. Dixa exemplifies the conversational AI specialization archetype within customer experience platforms. These three entities represent distinct strategic postures: incumbent platform leverage, infrastructure-application convergence, and vertical AI differentiation.
| Leading Market Players |
|---|
| Visma e-conomic A/S |
| Veo Technologies ApS |
| team.blue Denmark A/S |
| Visma DataLøn A/S |
| Keylane A/S |
| SiteHub ApS |
| SECOMEA A/S |
| Dixa |
| Keepit |
| Others |
Pricing and Supply Chain Analysis
Multi-tenant cloud architecture migration simultaneously compresses marginal delivery costs and concentrates infrastructure ownership among hyperscale providers, reshaping how Danish SaaS vendors structure subscription economics and negotiate data center capacity.
Pricing Analysis
Warranty and service bundling separates premium tiers from standard offerings across Danish SaaS procurement. Subscription-based annual recurring revenue dominates financial models, with price differentiation hinging on GDPR certification grade and API integration depth. Cost compression in mid-market tiers intensifies as generative AI copilots commoditize baseline automation features. Small businesses exhibit highest price sensitivity, while large enterprises prioritize compliance documentation over per-seat economics.
Supply Chain Analysis
Reverse-logistics flows for data center hardware refurbishment and component recovery remain underdeveloped across Nordic cloud infrastructure. Denmark's supply chain draws from Germany, Netherlands, and Ireland for server hardware, with software dependencies resting on open-source frameworks and proprietary ML training pipelines. Single-source vulnerability concentrates in GPU accelerators for AI workloads. Distribution runs through direct vendor sales for enterprise contracts and self-service portals for mid-market acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's SaaS sector sits in a generative AI transition phase, with conversational AI and regulatory automation tools displacing legacy workflow software across healthcare and fintech verticals.
For Market Incumbents: Deepen API ecosystem control through native integration with Danish Business Authority e-invoicing systems and CVR registry automation. Incumbent platforms face substitution threat from AI-native entrants rearchitecting customer service and accounting workflows around real-time inference. Certification investment in EU AI Act documentation protocols accelerates public-sector procurement cycles. For New Entrants and Emerging Players: Launch via vertical specialization in Jutland manufacturing corridors, where supply chain and production planning SaaS remains underpenetrated. White-space targets cluster in Odense industrial IoT and Aarhus SME ERP displacement. Go-to-market leverage rests on e-invoicing mandate compliance as embedded wedge into accounting platform budgets. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays, where compliance-heavy verticals command premium multiples. Long-term viability favors vendors with Danish data center presence and pre-certified AI governance frameworks. Acquisition target archetype: born-digital specialists in healthcare or fintech with existing Danish Patient Safety Authority or Financial Supervisory Authority relationships. Signal to watch: EU cybersecurity certification scheme adoption timelines altering public-sector RFP criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Danish CVR and tax system connectivity compresses quarterly compliance cycles for accounting vendors. |
| Regulatory Pre-Certification | EU AI Act documentation investment accelerates hospital and bank procurement decisions ahead of enforcement deadlines. |
| Vertical AI Differentiation | Conversational AI specialization in customer experience platforms displaces legacy ticketing systems in Copenhagen fintech clusters. |
| Data Center Sovereignty | Danish facility presence satisfies GDPR Article 44 requirements for public-sector and healthcare contracts. |
| API Ecosystem Expansion | Open banking standard integration enables automated reconciliation modules capturing cash-flow forecasting spend. |
Research Methodology
Document review covered SEC filings from hyperscale cloud providers, EU regulatory databases, and Danish Business Authority mandate documentation, complemented by interviews with SaaS vendor executives, IT procurement officers at Copenhagen fintech firms, platform engineers, and healthcare IT directors. Secondary sources included hyperscaler capex disclosures, GDPR enforcement tracker data, and Nordic venture capital investment databases. Bottom-up subscriber and revenue estimates triangulated against top-down market sizing from infrastructure capacity expansion announcements.
Segment-level projections across deployment modes, solution types, and end-user tiers fed into consolidated market value estimates over the projection horizon. The analytical framework modeled public cloud, hybrid cloud, private cloud, and multi-cloud adoption patterns alongside organization size and vertical industry dimensions. CAGRs derived from elasticity-adjusted subscription growth curves, incorporating EU AI Act compliance cost absorption rates and generative AI feature adoption velocity as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook if enterprise evaluation cycles fail to compress as projected. Forecasts reflect documented assumptions about regulatory enforcement timelines and data center capacity allocation. Practitioners should monitor Danish grid renewable transition schedules and EU cybersecurity certification scheme finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Global Journal App Market
Software & Services
Marketing Automation Software Market
Software & Services
Live Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Global Automation Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Remote Browser Market
Software & Services
CAD Modeling Software Market
Software & Services
Test Management Software Market
Software & Services
Test Automation Market
Software & Services
Parametric Design Software Market
Software & Services
Drone Mapping Software Market