
 Contract Abstraction Software Market | 2026-2036
Contract Abstraction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Abstraction Software Market Insights
Legal operations talent scarcity is collapsing implementation timelines for enterprise contract management platforms. Icertis, Inc. leverages its integrated platform architecture to sustain deployment momentum across Fortune 500 legal departments. Ironclad, Inc. specializes in workflow automation for high-velocity commercial contracting, while Evisort, Inc. anchors its position in AI-powered data extraction for legacy contract migration.
Contract abstraction software extracts, classifies, and structures provisions from legal agreements using natural language processing engines that parse unstructured text into machine-readable data fields with extraction accuracy thresholds typically exceeding ninety percent. The technology serves primarily to accelerate due diligence, ensure regulatory compliance, and surface revenue leakage from unfavorable terms. Cloud-based services dominate new bookings as law firms and corporations abandon on-premises maintenance burdens, while AI-powered analysis commands premium pricing due to scarce technical talent and proprietary training data requirements. Integrated platforms capture expanding share as buyers consolidate point solutions into unified legal tech stacks.
FDA oversight of software-as-a-medical-device intersects with contract abstraction tools used in pharmaceutical licensing agreements, while HIPAA compliance requirements shape security specifications for healthcare sector deployments. The EU AI Act's risk-tiered obligations for automated contract review systems will force vendors to reengineer algorithmic transparency features. Stakeholders must evaluate whether their current abstraction engines can satisfy emerging explainability mandates before procurement cycles harden around certified platforms.
Market Dynamics
EU AI Act risk-tiered obligations are forcing algorithmic transparency reengineering across contract abstraction vendors, compressing procurement cycles around certified platforms while legal operations talent scarcity collapses enterprise implementation timelines.
Growth Catalysts
- Fortune 500 legal operations budget expansion:Multinational corporations are consolidating point solutions into unified legal tech stacks, accelerating integrated platform adoption.
- HIPAA security specifications:Healthcare sector deployments require hardened data protection, driving premium pricing for compliant cloud-based contract abstraction services.
- Legacy contract migration demand:AI-powered data extraction engines parse decades of unstructured agreements into machine-readable fields, unlocking revenue leakage detection.
Market Restraints
- Proprietary training data scarcity:High-quality annotated legal corpora concentrate among established vendors, creating barriers for new entrants.
- EU AI Act compliance costs:Explainability mandate reengineering diverts R&D resources from core extraction accuracy improvements.
- On-premises maintenance abandonment:Law firms and corporations face stranded asset risks during cloud migration transitions.
Strategic Opportunities
- Pharmaceutical licensing agreement vertical:FDA software-as-a-medical-device oversight intersects with contract abstraction, creating specialized compliance tooling demand.
- Natural language processing convergence with knowledge graphs:Combined technologies enable contextual clause interpretation beyond surface-level extraction.
- India's digitizing legal services sector:Underpenetrated mid-market law firms present channel expansion potential for workflow automation platforms.
Industry Challenges
- Legal engineering talent scarcity:Hybrid professionals combining domain expertise with machine learning operations remain critically undersupplied.
- Legacy system integration complexity:Enterprise resource planning and matter management system interoperability consumes disproportionate implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Abstraction Software Market |
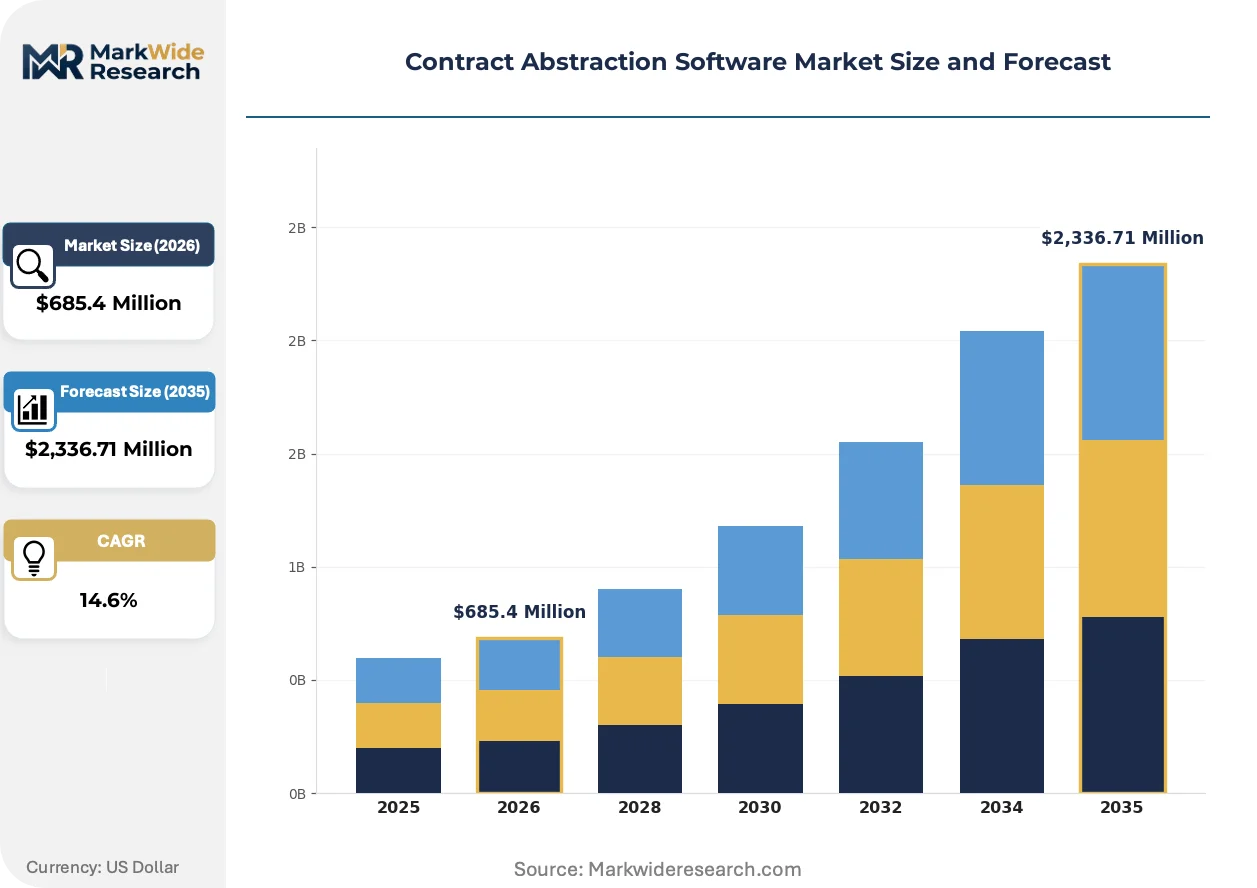
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,336.71 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
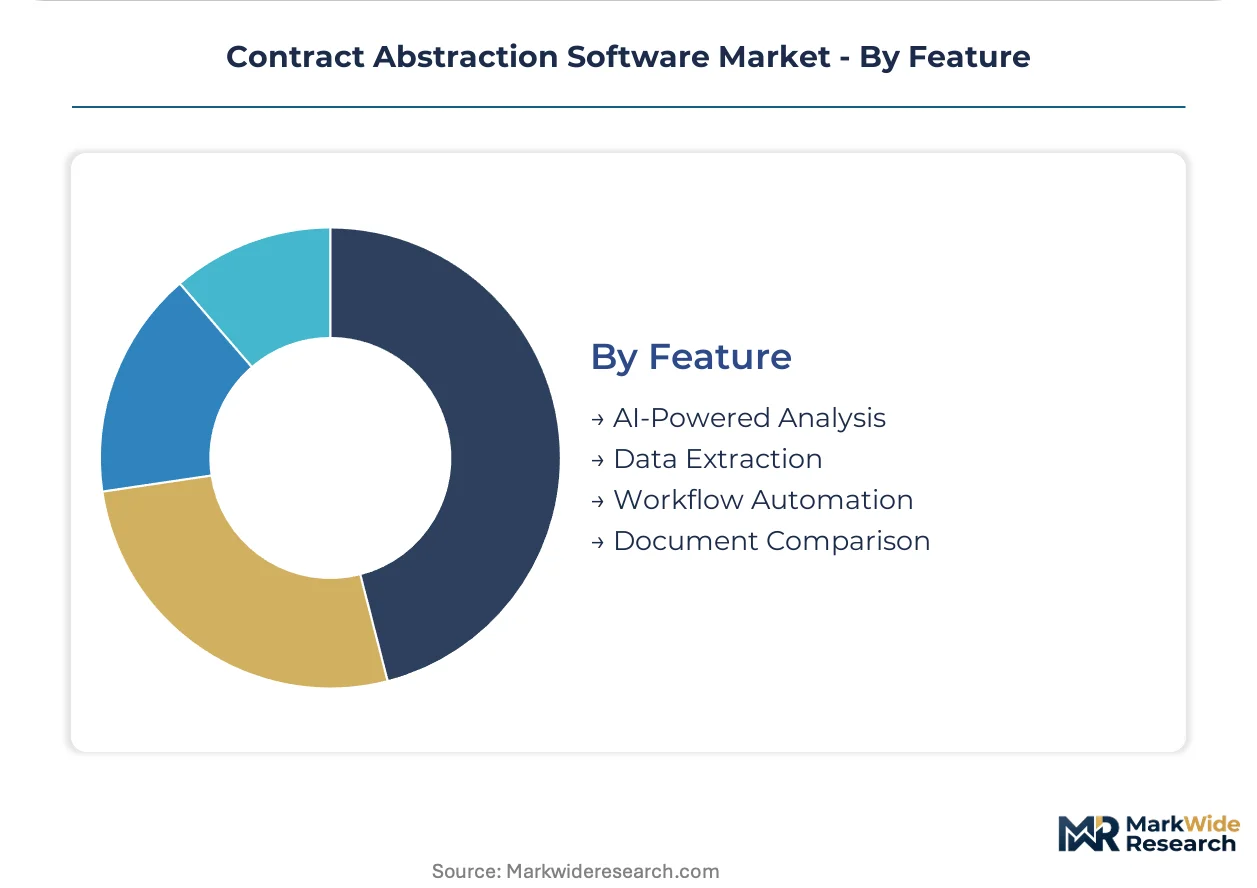
| Segmentation | Product Type: Standalone Solutions, Integrated Platforms, Cloud-Based Services, On-Premises Software Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Law Firms, Corporations, Government Agencies, Nonprofits Feature: AI-Powered Analysis, Data Extraction, Workflow Automation, Document Comparison |
| Companies Covered | Ironclad, Inc., Icertis, Inc., Conga, Inc., DocuSign, Inc., Agiloft, Inc., SirionLabs, Evisort, Inc., ThoughtTrace, Inc., LinkSquares, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Abstraction Software Market Trends and Innovations
Natural language processing architectures are compressing extraction latency while regulatory mandates harden around algorithmic accountability, reshaping vendor competitive moats.
Transformer-based contract analysis engines are miniaturizing into edge-deployable modules. Mid-sized law firms lacking dedicated IT infrastructure now adopt lightweight abstraction tools without cloud dependency. This architecture is miniaturizing the addressable market downward, fragmenting historically enterprise-centric vendor portfolios.
EU AI Act automated decision system classifications impose conformity assessment burdens on high-risk contract review deployments. Pharmaceutical and financial services verticals face mandatory algorithmic transparency documentation. European legal departments are front-loading procurement diligence to pre-certify vendor platforms before hardening compliance deadlines.
Subscription pricing unbundling accelerates as buyers resist bundled platform premiums for underutilized feature sets. Point solution procurement is displacing integrated suite commitments among budget-constrained regional law firms. United Kingdom and German mid-market segments exhibit strongest preference for modular, usage-metered contract abstraction services.
Contract Abstraction Software Market Segmentation
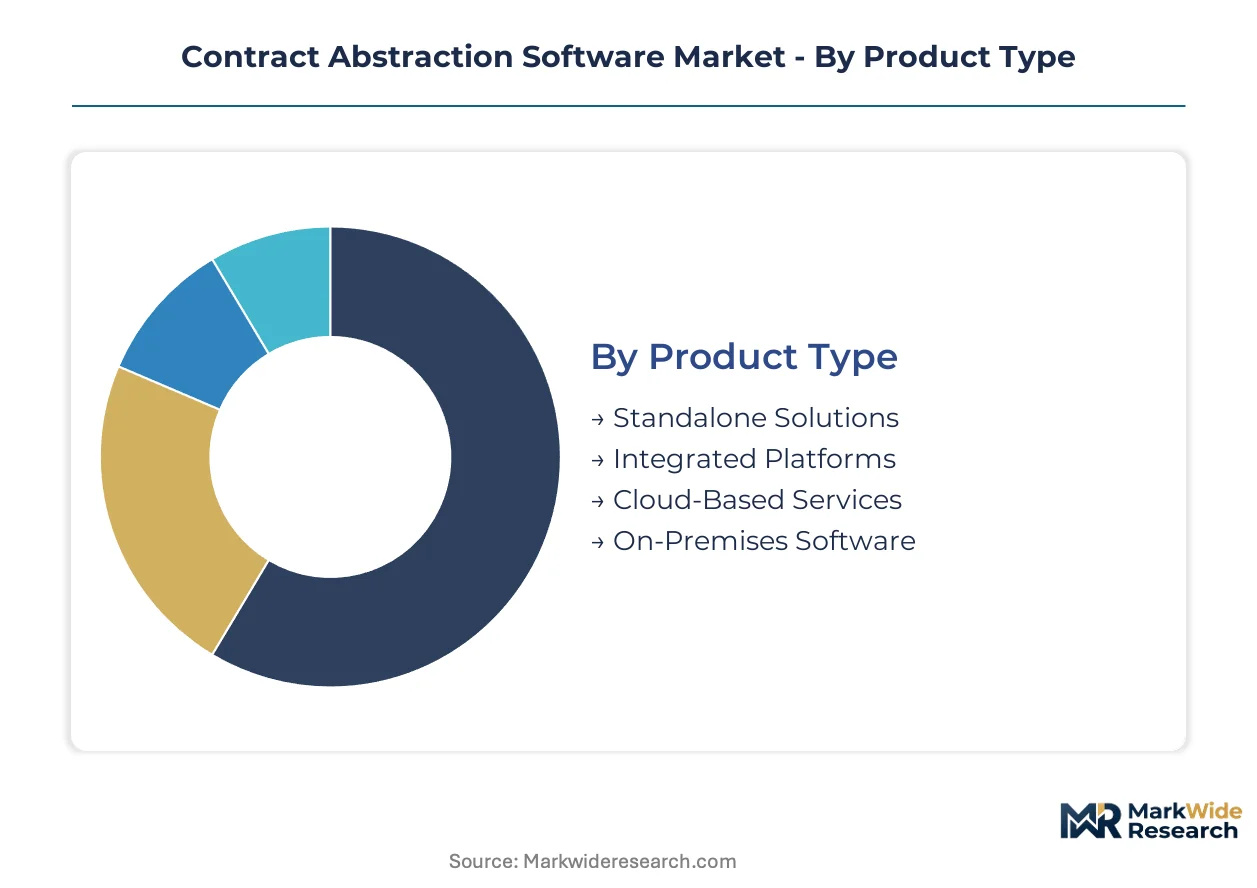
Segmentation in contract abstraction software reveals how regulatory pressure and procurement consolidation reshape vendor priorities. Buyers now segment solutions by compliance readiness rather than feature breadth alone.
Product Type:
EU AI Act risk classifications and FDA software-as-a-medical-device oversight differentiate product architectures by audit trail depth and algorithmic transparency.
- Integrated Platforms:Unified legal tech stacks consolidate contract lifecycle management, e-signature, and analytics into single vendor relationships. Fortune 500 legal operations teams in the United States demand these configurations to collapse implementation timelines and reduce vendor management overhead.
- Cloud-Based Services:Multi-tenant SaaS architectures eliminate on-premises maintenance burdens while enabling continuous model updates. Healthcare sector deployments in the United States require HIPAA-compliant cloud instances with hardened encryption and access logging.
- Standalone Solutions:Point tools address specific extraction or comparison workflows without platform overhead.
- On-Premises Software:Air-gapped installations serve national security and classified contracting environments with zero external data transmission.
Integrated platforms handle the majority of throughput; cloud-based services are expanding most quickly on share.
Deployment Model:
Cost tier separation between capital-intensive private infrastructure and operationalized public consumption shapes enterprise roadmaps.
- Public Cloud:Shared infrastructure delivers metered pricing and elastic scaling for variable contract review volumes. Mid-market law firms in the United Kingdom and Germany prefer this model for workflow automation without dedicated IT staffing.
- Hybrid Cloud:Sensitive extraction workloads run on-premises while model training leverages pooled cloud compute. Pharmaceutical licensing agreement verticals in the United States deploy this architecture to satisfy FDA audit requirements while accessing AI acceleration.
- Private Cloud:Single-tenant environments isolate client data with dedicated hardware stacks.
- On-Premises:Fully captive infrastructure persists in government and defense contracting contexts.
Public cloud absorbs the volume base; hybrid cloud is climbing the fastest as regulated industries seek partitioned compliance.
End User:
Application maturity varies sharply between revenue-protecting corporate functions and cost-optimized nonprofit operations.
- Corporations:Enterprise legal departments deploy abstraction engines across procurement, sales, and M&A workflows to surface revenue leakage and accelerate due diligence. Multinational headquarters in the United States anchor category demand with expanding legal operations budgets.
- Law Firms:Partnership structures prioritize billable efficiency and client-facing technology differentiation. AmLaw 200 firms in the United States and Magic Circle firms in the United Kingdom compete on AI-powered contract review speed.
- Government Agencies:Public procurement and regulatory enforcement drive standardized extraction requirements.
- Nonprofits:Grant compliance and donor agreement management create specialized workflow needs at constrained price points.
Corporations dominate current procurement value; law firms are gaining share fastest as partnership technology investment accelerates.
Feature:
Margin concentration follows technical differentiation, with AI-powered capabilities commanding premium pricing against commoditized document comparison.
- AI-Powered Analysis:Transformer-based natural language processing engines parse contextual meaning across clause variations, enabling risk scoring and obligation surfacing beyond keyword matching. Proprietary training data scarcity limits vendor supply, supporting pricing power for established platforms.
- Workflow Automation:Rules-based routing and approval orchestration accelerates high-velocity commercial contracting. High-growth technology companies in the United States deploy these capabilities to scale legal operations without linear headcount expansion.
- Data Extraction:Structured field population from unstructured agreement text supports legacy contract migration and repository building.
- Document Comparison:Redline generation and version reconciliation remain table-stakes functionality with compressed pricing.
AI-powered analysis captures the steepest expansion trajectory; workflow automation handles the broadest deployment base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance requirements and Fortune 500 legal operations budget expansion anchor United States market dominance, while the EU AI Act's risk-tiered obligations reshape European procurement patterns.
United States
Enterprise legal departments at multinational corporations consolidate point solutions into unified tech stacks, accelerating integrated platform adoption. FDA oversight of software-as-a-medical-device intersects with pharmaceutical licensing agreement tools, creating specialized compliance demands. Silicon Valley and New York City clusters host the densest concentration of AI-powered contract analysis vendors serving high-growth technology companies.
Germany
Mid-market law firms in the United Kingdom and German segments exhibit strongest preference for modular, usage-metered contract abstraction services. The EU AI Act's conformity assessment burdens force algorithmic transparency reengineering across deployments. Frankfurt's financial services hub drives demand for automated contract review systems satisfying high-risk classification mandates.
United Kingdom
Magic Circle firms compete on AI-powered contract review speed, prioritizing billable efficiency and client-facing technology differentiation. GDPR data protection specifications shape security requirements for cloud-based service deployments. London's legal technology corridor concentrates vendor development resources and partnership networks.
India
Underpenetrated mid-market law firms present channel expansion potential for workflow automation platforms as the country's legal services sector digitizes. The central bank's regulatory sandbox initiatives support fintech contract automation pilots. Bangalore and Mumbai technology clusters incubate natural language processing talent for extraction engine development.
Japan
Corporate legal departments deploy abstraction engines across procurement and sales workflows to surface revenue leakage amid expanding compliance requirements. METI industrial digitization programs subsidize legal technology adoption for mid-sized enterprises. Tokyo's concentrated headquarters economy drives enterprise software procurement at scale.
Contract Abstraction Software Market Competitive Landscape
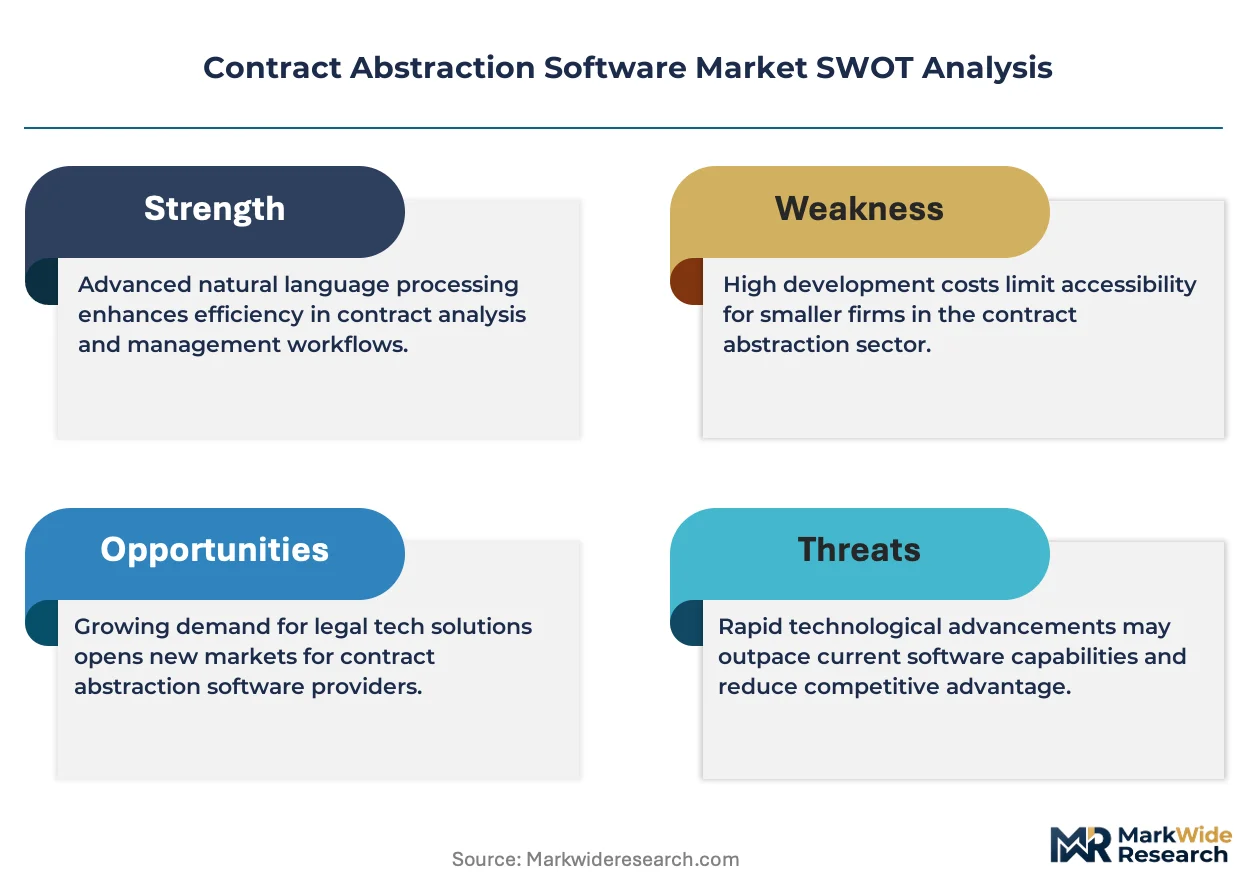
Technology leadership and cost leadership are held by different player archetypes across the contract abstraction software market. Integrated platform vendors capture expanding share as buyers consolidate point solutions, while specialized workflow automation providers defend positions in high-velocity commercial contracting segments. Two strategic archetypes dominate: full-stack legal tech suites and AI-native extraction specialists. Competitive moves center on strategic partnerships for training data access and geographic expansion into underpenetrated mid-market segments.
Within the integrated platform tier, Icertis, Inc. and Ironclad, Inc. exemplify contrasting positioning strategies. Icertis occupies a position serving Fortune 500 legal departments through unified architecture, while Ironclad anchors the high-velocity commercial contracting specialization. Evisort, Inc. represents the AI-native extraction archetype, with its focus on legacy contract migration workflows. These three companies collectively illustrate how vendor competitive moats form around proprietary training data reservoirs and deployment velocity capabilities rather than feature breadth alone.
| Leading Market Players |
|---|
| Ironclad, Inc. |
| Icertis, Inc. |
| Conga, Inc. |
| DocuSign, Inc. |
| Agiloft, Inc. |
| SirionLabs |
| Evisort, Inc. |
| ThoughtTrace, Inc. |
| LinkSquares, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native architecture substitution for on-premises infrastructure simultaneously redistributes supply geography toward hyperscaler regions and compresses pricing economics through metered consumption models. This shift concentrates vendor margins in recurring service layers while commoditizing perpetual license revenue streams.
Pricing Analysis
Price spreads between United States and European deployments reflect HIPAA compliance premiums and EU AI Act certification costs. Three-tier pricing structure across premium, standard, and economy levels segments by extraction accuracy thresholds and audit trail depth. Cost compression in the standard tier intensifies because mid-market law firms resist bundled platform premiums. Regional law firms in the United Kingdom and Germany exhibit highest price sensitivity; Fortune 500 legal departments in the United States show lowest sensitivity due to budget expansion.
Supply Chain Analysis
Just-in-time model updates via continuous delivery pipelines dominate cloud-native deployments, while strategic stockpiling of proprietary training data reserves differentiates established vendors. Supply concentrates in the United States, the United Kingdom, and India for NLP engine development and legal engineering talent. Raw material dependencies include annotated legal corpora, transformer compute infrastructure, and compliance certification frameworks. Single-source vulnerability in proprietary training data reservoirs threatens new entrant viability. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract abstraction software functions as a service-attach opportunity where continuous model retraining and compliance certification subscriptions expand faster than initial platform licensing. Recurring revenue layers now exceed half of vendor bookings as buyers prioritize operationalized consumption over capital deployment.
For Market Incumbents: Compound platform stickiness through deeper ERP and matter management system interoperability, addressing the integration complexity that consumes disproportionate implementation resources. Prioritize proprietary training data reservoir expansion to defend against AI-native extraction specialists. Vertical integration into legal engineering talent pipelines mitigates the hybrid professional scarcity collapsing enterprise deployment timelines. For New Entrants and Emerging Players: EU AI Act conformity assessment fast-tracks present procurement entry points as European legal departments front-load vendor diligence before hardening compliance deadlines. White-space targets include India's underpenetrated mid-market law firms and workflow automation for high-velocity commercial contracting. Channel partnerships with regional system integrators accelerate footprint without dedicated direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform vendors with certified compliance architectures and proven deployment velocity. Long-term viability hinges on recurring revenue mix and proprietary data moats rather than feature breadth. Acquisition target archetype: AI-native extraction specialists with healthcare or pharmaceutical vertical penetration. Watch EU AI Act enforcement timelines as inflection indicator for certified platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies contract lifecycle management with e-signature and analytics for Fortune 500 legal departments. |
| Strategic Partnership | Secures proprietary training data access through law firm or corporate repository alliances. |
| Acquisition of Specialist Firm | Adds AI-native extraction capabilities or vertical-specific compliance expertise. |
| Geographic Expansion | Targets India's digitizing legal services sector through channel partner networks. |
| Product Launch | Introduces edge-deployable transformer modules for mid-sized law firms lacking cloud dependency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across legal operations executives at Fortune 500 corporations, AmLaw 200 and Magic Circle firm partners, healthcare compliance officers, pharmaceutical licensing specialists, and contract management platform engineers. Secondary validation drew from SEC filings, EU regulatory submissions, HIPAA compliance documentation, and legal technology procurement databases. Bottom-up deployment estimates triangulated against top-down legal operations budget analysis.
Across the analysis window, value projections incorporate deployment model segmentation by public cloud, hybrid cloud, and on-premises architectures, alongside organization size tiers and vertical regulatory clusters. CAGRs derive from adoption curve modeling and budget elasticity estimates. Forecast inputs include EU AI Act implementation timelines and FDA software-as-a-medical-device oversight expansion.
Underlying assumptions cover sustained legal operations budget expansion and cloud migration momentum, with deviation risk concentrated in regulatory compliance cost acceleration and legal engineering talent supply constraints. Revision becomes warranted when EU AI Act enforcement thresholds or HIPAA audit intensity crosses predetermined escalation bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Recruitment Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Compensation Software Market
Software & Services
Patent Management Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Data Migration Software Services Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global Microscopy Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Referral Marketing Software Market
Software & Services
Global Project Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Global Political Campaign Software Market