
 Global Product Management Software Market | 2026-2036
Global Product Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Management Software Market Outlook
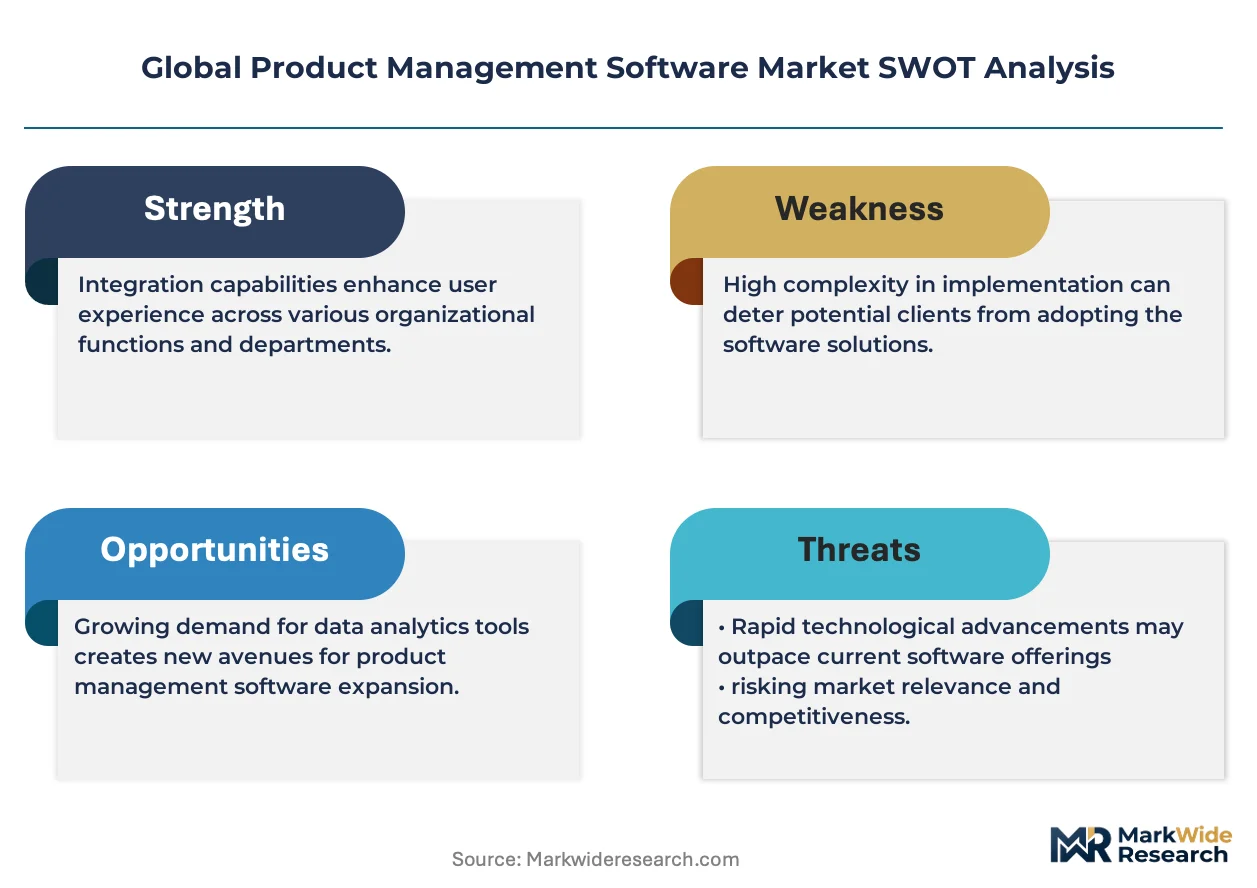
Subscription-based feature tiers is restructuring how product management software gets monetized, shifting perpetual licenses toward recurring revenue models with embedded analytics. Atlassian leverages its Jira ecosystem to dominate developer-adjacent product workflows. Pendo sustains competitive positioning through in-app guidance and behavioral analytics specialization. Monday.com anchors mid-market expansion with configurable workflow automation across non-technical teams.
Product management software comprises cloud-native and on-premise applications that orchestrate roadmapping, backlog prioritization, cross-functional collaboration, and outcome measurement through API-connected data layers. Its primary commercial purpose centers on reducing time-to-market for digital and physical products by aligning engineering, design, and business stakeholders around shared objectives. Cloud-based deployment leads segment momentum as enterprises retire legacy on-premise installations, while roadmapping software captures disproportionate R&D investment due to its direct linkage with C-suite strategic planning. Analytics platforms represent the fastest-growing product type as product operations teams demand predictive churn and adoption metrics.
The EU AI Act, GDPR, and ISO 27001 collectively shape vendor development priorities by mandating algorithmic transparency, data residency controls, and security certification for enterprise procurement eligibility. The US SEC and HIPAA impose additional constraints on financial services and healthcare adopters respectively, fragmenting compliance roadmaps across geographies. Stakeholders must monitor how emerging AI governance frameworks in the European Union and United States will redefine acceptable automation boundaries within product analytics workflows.
Market Dynamics
Cloud migration is compressing deployment cycles across the product management software market, forcing vendors to rearchitect on-premise systems for multi-tenant SaaS delivery while absorbing compliance burdens from the EU AI Act and GDPR.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must embed algorithmic transparency and audit trails into product analytics workflows, creating procurement pull for governance-ready platforms.
- API-first architecture adoption:Engineering teams demand modular integration with CI/CD pipelines, favoring vendors offering native Jira, GitHub, and Slack connectors.
- India's digital product operations expansion:Bengaluru and Hyderabad-based technology firms are scaling dedicated product operations functions, driving seat-license growth for roadmapping and analytics tools.
Market Restraints
- Data residency enforcement:GDPR Article 44 restrictions on cross-border data transfers force vendors to maintain sovereign cloud instances, inflating infrastructure costs.
- Enterprise sales cycle elongation:Security reviews for ISO 27001 and SOC 2 Type II certification now average six to nine months, delaying revenue recognition.
- Freemium substitution pressure:Open-source alternatives including OpenProject and Focalboard capture price-sensitive teams in early-stage startups.
Strategic Opportunities
- Germany's Mittelstand digitization:Mid-sized manufacturers in Baden-Württemberg and Bavaria are adopting product management software to coordinate hardware-software convergence in industrial IoT.
- Behavioral analytics convergence:Integration of product usage data with revenue operations platforms enables predictive churn scoring for subscription businesses.
- US SEC climate disclosure rules:Public software companies must trace product carbon footprints through supply chains, creating demand for sustainability-linked roadmapping modules.
Industry Challenges
- Product operations talent scarcity:Organizations struggle to hire professionals fluent in both SQL-based analytics and qualitative user research methodologies.
- Legacy ERP integration friction:SAP and Oracle systems in established enterprises resist API connectivity, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Management Software Market |
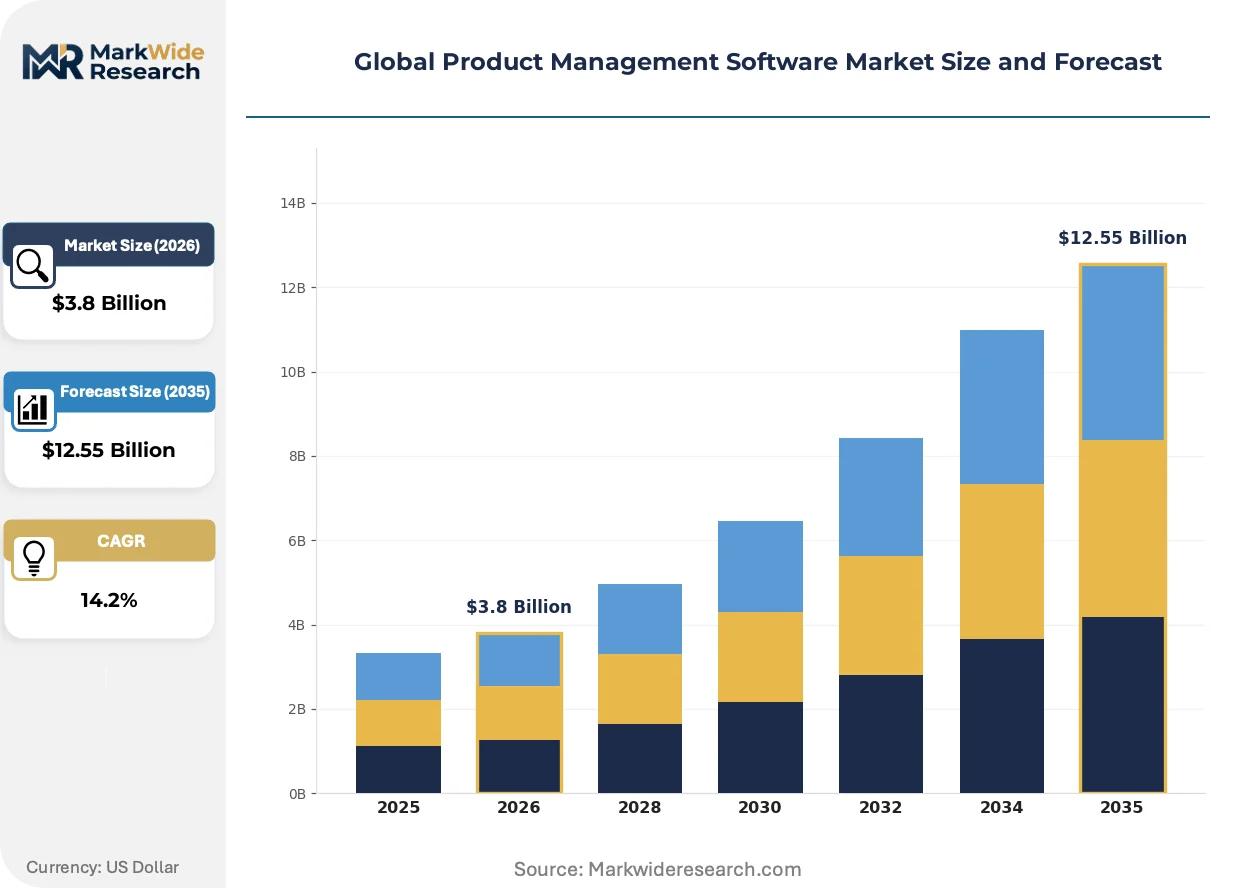
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
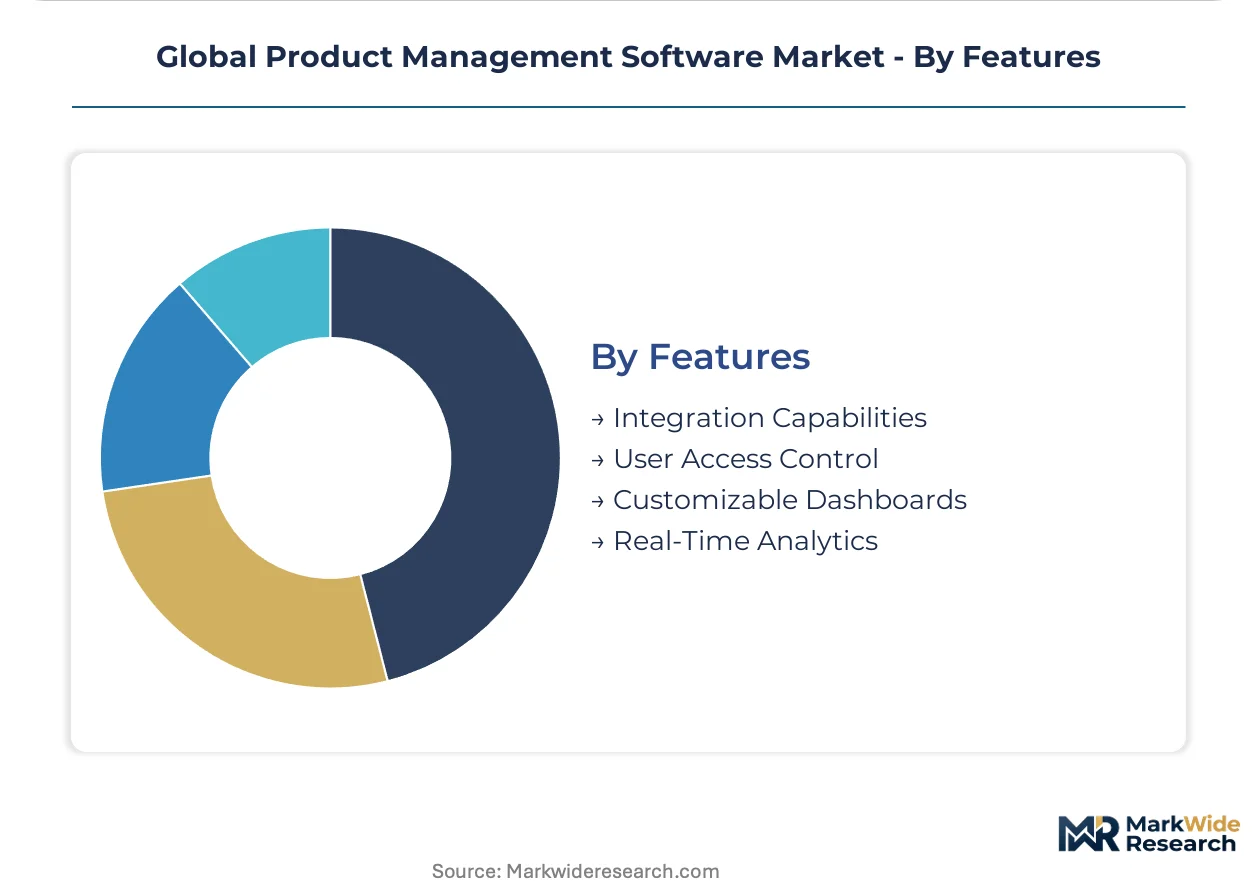
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturers, Retailers, Technology Firms, Startups Product Type: Collaboration Tools, Roadmapping Software, Analytics Platforms, Project Management Tools Features: Integration Capabilities, User Access Control, Customizable Dashboards, Real-Time Analytics |
| Companies Covered | Aha!, Asana, Atlassian, Pendo, Productboard, Monday.com, ProductPlan, TeamGantt, Wrike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Management Software Market Strategic Shifts
Artificial intelligence capabilities are embedding into core product workflows, shifting competitive advantage from feature breadth toward predictive intelligence and automated insight generation.
Generative AI copilots are expanding into backlog refinement and user story drafting, reducing manual documentation overhead for product managers. Mid-market SaaS companies are deploying these tools at scale within three-month implementation windows. The technology is expanding into competitive differentiation as vendors race to surface actionable recommendations from unstructured customer feedback.
The EU AI Act's risk-based classification system is mandating human-in-the-loop controls for high-stakes product decisions in financial services and healthcare. Vendors must now document training data provenance and model performance metrics to maintain enterprise eligibility. German automotive and French fintech adopters are demanding pre-certified compliance modules to accelerate procurement timelines.
Buyers are consolidating vendor relationships around integrated suites rather than best-of-breed point solutions, compressing evaluation cycles and raising switching costs. Procurement teams in US technology firms now prioritize platforms combining roadmapping, analytics, and in-app guidance under single contracts. This concentration is most visible among Series C and later-stage startups seeking to reduce tool sprawl and administrative overhead.
Global Product Management Software Market Segmentation
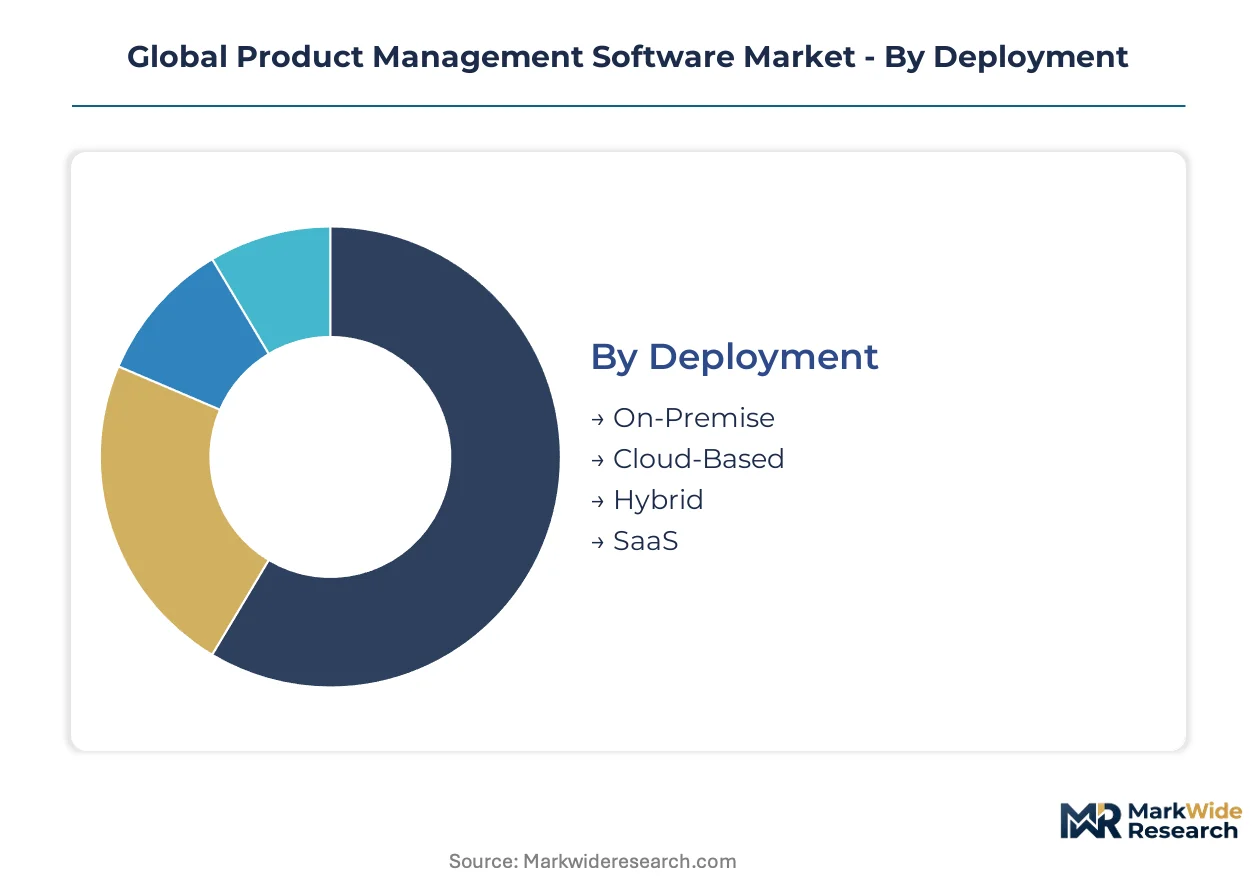
Product management software vendors architect go-to-market strategies around deployment flexibility and feature depth, with procurement patterns diverging sharply between regulated enterprises and agile startups. Segmentation reveals where R&D investment concentrates and which customer profiles justify premium pricing tiers.
Deployment:
Cloud infrastructure providers concentrate capacity in multi-tenant architectures, while sovereign data requirements sustain niche on-premise installations.
- Cloud-Based:Multi-tenant SaaS architectures with automatic scaling and API-native connectivity dominate new procurement. German automotive manufacturers and US healthcare systems drive demand for GDPR and HIPAA-aligned cloud instances with regional data residency.
- SaaS:Subscription delivery models with tiered feature access and embedded analytics capture recurring revenue from mid-market technology firms. Bengaluru-based product operations teams favor these tools for rapid deployment without IT procurement cycles.
- On-Premise:Air-gapped installations in defense contractors and classified government facilities require hardened security certifications.
- Hybrid:Split architectures synchronize sensitive data on-premise with collaborative workflows in cloud tiers.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Customer sophistication determines feature requirements and sales cycle complexity, with procurement authority residing in distinct organizational functions.
- Technology Firms:Engineering-led organizations demand deep CI/CD pipeline integration and developer-centric APIs. San Francisco and Hyderabad product operations teams prioritize tools with native Jira and GitHub connectors for backlog synchronization.
- Manufacturers:Industrial IoT adopters coordinate hardware-software convergence through roadmapping modules with supply chain traceability. Baden-Württemberg automotive suppliers and Bavarian machinery producers drive this segment.
- Startups:Seed-stage companies favor freemium tiers with rapid scaling paths.
- Retailers:Omnichannel merchants prioritize customer journey analytics and seasonal release planning.
Technology Firms command the highest seat-license volumes; Manufacturers are climbing the fastest as industrial digitization accelerates.
Product Type:
Functional specialization determines competitive moats, with consolidation pressure favoring integrated suites over point solutions.
- Roadmapping Software:Strategic planning tools with C-suite visualization and scenario modeling anchor enterprise contracts. Financial services firms in Frankfurt and New York require EU AI Act-compliant audit trails for algorithmic decision documentation.
- Analytics Platforms:Behavioral data ingestion with predictive churn scoring and revenue operations integration drives fastest growth. Subscription SaaS companies in London and Singapore deploy these for retention optimization.
- Collaboration Tools:Cross-functional workspace platforms with async communication and document co-editing.
- Project Management Tools:Task-tracking systems with resource allocation and timeline visualization.
Roadmapping Software captures the largest deal sizes; Analytics Platforms are gaining share fastest through AI-augmented insight generation.
Features:
Capability depth separates enterprise-grade platforms from mid-market alternatives, with integration breadth serving as primary switching cost.
- Integration Capabilities:Pre-built connectors to CRM, ERP, and DevOps stacks determine procurement eligibility. ISO 27001-certified API gateways are mandatory for French fintech and German automotive adopters under EU AI Act requirements.
- Real-Time Analytics:Streaming data processing with sub-second latency for operational decision dashboards.
- User Access Control:Role-based permissions with SAML and OAuth federation for enterprise identity management.
- Customizable Dashboards:Drag-and-drop visualization builders with templated reporting for executive consumption.
Integration Capabilities absorb the bulk of engineering investment; Real-Time Analytics is expanding most quickly as product operations teams demand immediate insight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Product management software vendors concentrate engineering talent in the United States while expanding delivery infrastructure across Germany and India to serve localized data residency requirements. Consumption clusters in financial services hubs and manufacturing belts drive divergent feature priorities across geographies.
United States
San Francisco and New York technology firms drive seat-license volume through API-first procurement mandates. SEC disclosure rules and HIPAA constraints fragment compliance roadmaps for financial services and healthcare adopters respectively. The Pacific Northwest hosts concentrated product operations talent pools that accelerate enterprise deployment cycles.
Germany
Baden-Württemberg automotive suppliers and Bavarian machinery producers adopt roadmapping modules for hardware-software convergence in industrial IoT. The EU AI Act and GDPR Article 44 force vendors to maintain sovereign cloud instances with algorithmic transparency documentation. Frankfurt fintech clusters demand pre-certified compliance modules to compress procurement timelines.
India
Bengaluru and Hyderabad technology firms scale dedicated product operations functions, driving rapid seat-license expansion for cloud-native tools. RBI guidelines on data localization influence vendor infrastructure decisions for financial services adopters. The National Payments Corporation of India's API standards shape integration requirements for domestic fintech procurement.
United Kingdom
London-based subscription SaaS companies deploy behavioral analytics platforms for retention optimization and revenue operations integration. The Financial Conduct Authority's operational resilience requirements impose system availability standards on vendor selection. Manchester and Edinburgh technology clusters favor configurable workflow automation for cross-functional team coordination.
Japan
Tokyo and Osaka enterprises prioritize integration with legacy ERP systems, creating demand for middleware-capable vendors. METI's data free flow with trust initiatives shape cross-border data governance expectations. Automotive and electronics manufacturers in Nagoya and Hiroshima drive requirements for supply chain traceability within roadmapping modules.
Global Product Management Software Market Competitive Environment
Capital-heavy platform developers compete with asset-light specialists across the product management software market, with infrastructure investment separating enterprise-grade suites from point solutions. The vendor base concentrates around three tiers: integrated ecosystem players, vertical specialists, and workflow automation generalists. Consolidation pressure favors bundled offerings over best-of-breed procurement, raising switching costs through API depth and data gravity. Dominant competitive moves include geographic expansion into regulated European markets and portfolio diversification through adjacent collaboration tools.
Among ecosystem-anchored platforms, Atlassian exemplifies the developer-adjacent archetype through Jira-native positioning, while Pendo occupies the behavioral analytics specialization tier with in-app guidance capabilities. Monday.com represents the mid-market workflow automation archetype, serving non-technical teams through configurable interfaces. These three companies illustrate how competitive positioning fragments across technical depth, analytical sophistication, and accessibility vectors.
| Leading Market Players |
|---|
| Aha! |
| Asana |
| Atlassian |
| Pendo |
| Productboard |
| Monday.com |
| ProductPlan |
| TeamGantt |
| Wrike |
| Others |
Value Chain & Pricing Dynamics
API-first integration patterns anchor supply positioning and pricing power for product management software vendors, embedding connectivity costs into subscription tiers while cloud infrastructure concentration in the United States, Germany, and India shapes regional delivery economics. This vertical integration into hyperscaler ecosystems locks in data residency capabilities that command premium positioning under EU AI Act and GDPR mandates.
Pricing Analysis
Margin tightening in mid-market tiers reflects freemium substitution pressure from open-source alternatives including OpenProject and Focalboard. Three-tier pricing structure across premium, standard, and economy levels dominates, with seat-license differentiation driven by integration breadth and algorithmic transparency certification. Cost compression accelerates as Bengaluru-based startups demand rapid scaling without enterprise procurement overhead. Early-stage companies exhibit highest price sensitivity; regulated financial services in Frankfurt and New York show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate multi-tenant qualification across AWS, Azure, and Google Cloud platforms. Supply concentration rests on data center capacity in the United States, Germany, and India, with sovereign cloud instances required for EU AI Act compliance. Component dependencies span API gateway services, identity federation systems, and behavioral analytics engines. Single-source vulnerability emerges from hyperscaler concentration in core compute layers. Distribution runs through direct sales teams for enterprise contracts and self-service portals for mid-market acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The product management software market functions as a vertical-integration race, with vendors pursuing backward integration into AI model training data and downstream control over customer success services to deepen switching costs.
For Market Incumbents: Lock in enterprise relationships by embedding EU AI Act-compliant audit trails and ISO 27001-certified API gateways that resist displacement from modular alternatives. Expand sovereign cloud infrastructure in Germany and India to preempt data residency enforcement. Prioritize integration depth with Jira and GitHub ecosystems to defend against point-solution unbundling. For New Entrants and Emerging Players: The price-point gap between Atlassian's premium ecosystem tiers and freemium open-source tools creates entry space for mid-market workflow automation with native AI copilots. Target Series C technology startups in London and Singapore seeking to consolidate tool sprawl. Pursue vertical specialization in industrial IoT roadmapping for Baden-Württemberg automotive suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as private equity seeks bundled roadmapping-analytics-guidance suites. Long-term viability hinges on AI-augmented insight generation capabilities that differentiate from commodity task-tracking. Monitor EU AI Act enforcement intensity as inflection indicator for compliance-ready platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating roadmapping, analytics, and in-app guidance reduces customer churn and raises switching costs. |
| Geographic Expansion | Sovereign cloud deployment in Germany satisfies GDPR Article 44 and accelerates Mittelstand procurement cycles. |
| Acquisition of Specialist Firm | Behavioral analytics capabilities from Pendo-class vendors deepen predictive churn scoring for subscription SaaS. |
| Product Launch | Generative AI copilots for backlog refinement differentiate mid-market offerings against legacy documentation tools. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure embed data residency controls required by EU AI Act risk classification. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with product operations directors, CTOs at Series B-C technology firms, IT procurement officers, and platform engineering leads. SEC 10-K disclosures, EU AI Act implementation guidance, and hyperscaler capex reports provided demand-side validation. Bottom-up seat-license modeling and top-down market sizing triangulated volume estimates across deployment models and organization size tiers.
Data-stream reconciliation across quarterly earnings disclosures, vendor pricing documentation, and enterprise procurement databases informed the analytical framework. Segmentation dimensions modeled include deployment architecture, end-user industry vertical, product type specialization, and regional adoption pattern. CAGRs were derived from trend-line extrapolation of disclosed seat growth and pricing evolution. AI governance timeline uncertainty and cloud infrastructure cost trajectories introduced scenario bands.
Inputs from hyperscaler infrastructure reports and vendor sales disclosures were available through the study window; gaps in private company financials introduce uncertainty bands around mid-market share estimates. Forecasts reflect assumptions on EU AI Act enforcement pacing and enterprise cloud migration velocity. Deviation in regulatory implementation timelines or freemium substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Tenant Billing System Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Deck Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Home Design Software Market
Software & Services
Media Editing App Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Estate Management Software Market
Software & Services
Global Church Management Software Market
Software & Services
Global DevOps Software Market
Software & Services
Network Documentation Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Reporter Systems Market