
 Global Fixed Asset Management Software Market | 2026-2036
Global Fixed Asset Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fixed Asset Management Software Market Foresight
Enterprise IT talent scarcity is unwinding deployment timelines for complex fixed asset platforms. SAP SE leverages its ERP integration depth to anchor large manufacturing accounts. Oracle Corp. competes through database-native asset lifecycle modules that sustain renewal rates. Asset Panda LLC specializes in mobile-first interfaces for mid-market field operations.
Fixed asset management software comprises applications that track physical capital equipment from acquisition through disposal, incorporating depreciation algorithms, maintenance scheduling, and compliance audit trails. Cloud-based deployment leads solution architecture as organizations abandon server maintenance overhead, while asset tracking and compliance management command premium positioning due to regulatory audit density. Manufacturing and government applications dominate volume, though energy production segments show accelerated replacement cycles driven by grid modernization investments.
US SEC disclosure requirements, EU CSRD sustainability reporting mandates, and ISO 55000 asset management standards collectively reshape product roadmaps toward audit-ready transparency. FDA equipment qualification rules for healthcare providers and FAA maintenance logging for aviation assets create vertical-specific compliance layers. Stakeholders must evaluate whether their current platforms can absorb emerging carbon-footprint tagging alongside traditional financial depreciation without parallel system proliferation.
Market Dynamics
Cloud migration mandates from EU CSRD and US SEC disclosure rules are pressuring legacy on-premise fixed asset systems into accelerated replacement cycles, while enterprise IT talent scarcity unwinds deployment timelines for complex depreciation platforms.
Growth Catalysts
- CSRD Sustainability Mandates:EU corporate sustainability reporting directives force granular asset-level carbon footprint tracking, expanding software scope beyond traditional financial depreciation into environmental audit trails.
- Manufacturing Automation:Industrial firms in Germany and the United States deploy predictive maintenance modules to compress equipment downtime and automate compliance documentation for ISO 55000 certification.
- Aviation Maintenance Logging:FAA requirements for digital equipment qualification records drive adoption of mobile-first asset tracking among US-based MRO providers and regional carriers.
Market Restraints
- Implementation Cost Structure:Mid-market manufacturers face prohibitive professional services expenses for ERP integration, particularly when migrating historical depreciation data from legacy spreadsheets.
- Technical Debt Accumulation:Hybrid cloud architectures create synchronization failures between on-premise legacy databases and cloud-native reporting layers, forcing parallel system maintenance.
- Substitution by ERP Modules:Native fixed asset capabilities within SAP S/4HANA and Oracle Fusion threaten standalone software vendors by bundling lifecycle management at marginal cost.
Strategic Opportunities
- India Industrial Modernization:PLI scheme incentives for domestic manufacturing capacity create first-mover advantage for cloud-native platforms targeting automotive and electronics assembly lines.
- Healthcare Equipment Qualification:FDA 21 CFR Part 11 validation requirements for electronic records open vertical-specific modules for hospital asset compliance and calibration tracking.
- AI-IoT Convergence:Machine learning algorithms layered atop sensor networks enable predictive depreciation modeling, differentiating next-generation platforms from static schedule-based systems.
Industry Challenges
- Integration Architecture Complexity:Enterprise IT teams struggle to reconcile fixed asset data models with existing ERP chart-of-accounts structures, extending deployment timelines by 8-14 months.
- Compliance Certification Velocity:Multi-jurisdiction audit requirements from SEC, EMA, and national regulators force continuous software updates that strain vendor R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fixed Asset Management Software Market |
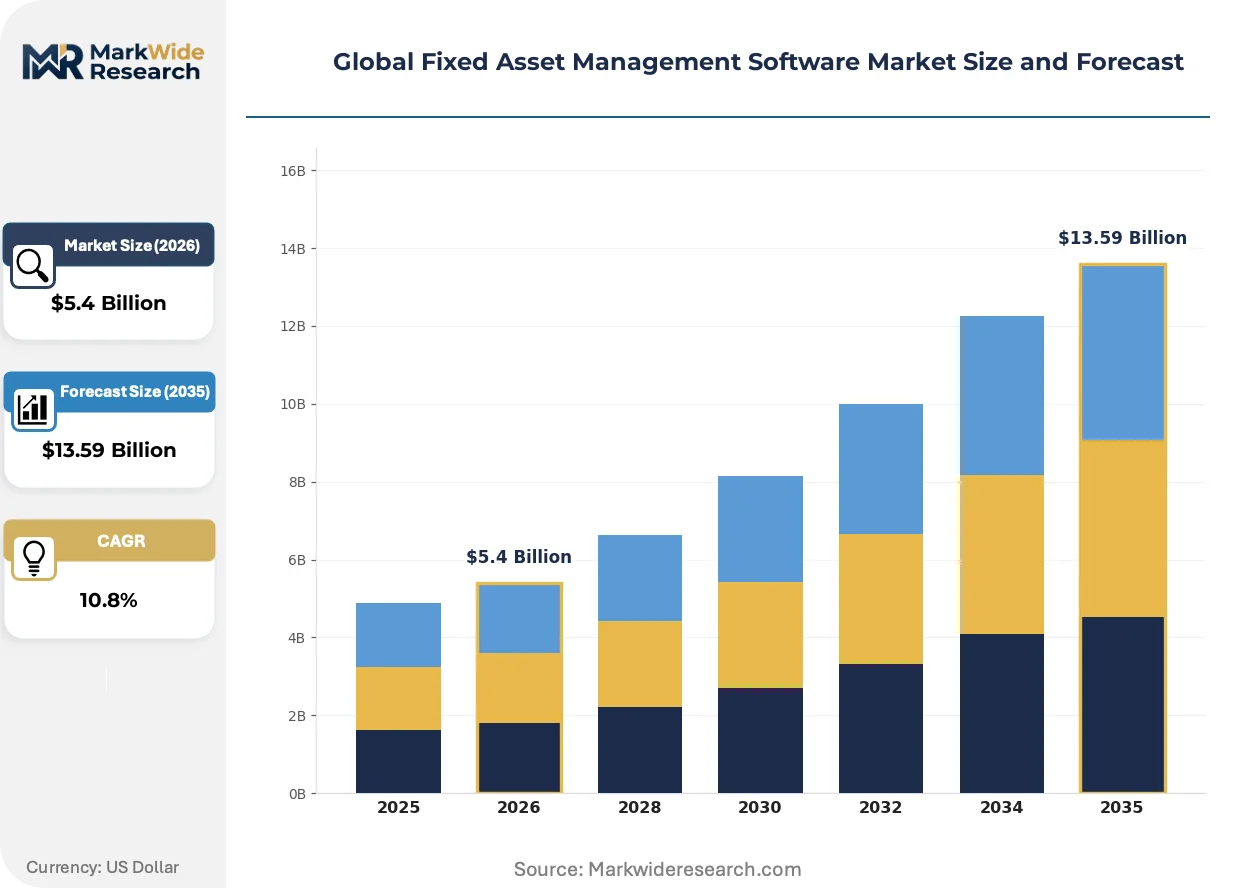
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $13.59 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS, Hosted Solution Type: Asset Tracking, Asset Maintenance, Inventory Management, Depreciation Management, Compliance Management Application: Manufacturing, Telecommunications, Energy Production, Transportation, Government, Education End User Industry: Construction Firms, Financial Services, Retail Chains, Healthcare Providers, Media Companies |
| Companies Covered | Oracle Corp., SAP SE, Infor Inc., Sage Group Plc, International Business Machines Corp., Acumatica Inc., Asset Panda LLC, NetSuite, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fixed Asset Management Software Market Shifts & Advancements
Fixed asset management software is undergoing architectural transformation as sensor networks, regulatory mandates, and procurement expectations restructure how physical capital is tracked, valued, and reported across enterprise boundaries.
Edge computing infrastructure is decomposing centralized asset tracking into distributed sensor nodes that capture real-time equipment condition data at manufacturing lines, energy substations, and transportation depots. German automotive suppliers and US utility operators deploy these architectures to eliminate latency in maintenance alerting. The shift compresses traditional monthly depreciation reviews into continuous valuation adjustments based on actual utilization patterns.
EU CSRD sustainability disclosure rules mandate granular carbon-footprint attribution to individual capital assets, forcing software vendors to embed emissions calculation engines alongside financial depreciation modules. Industrial firms in France and the Netherlands reconfigure procurement criteria to prioritize platforms with built-in lifecycle assessment capabilities. Healthcare and aviation verticals face parallel pressure from FDA equipment qualification rules and FAA maintenance logging standards.
Subscription pricing models displace perpetual licenses as mid-market buyers demand operational expenditure treatment for software procurement. Field service organizations in India and Brazil favor consumption-based contracts that scale with asset register growth rather than upfront enterprise commitments. This shift pressures vendor cash flow structures while accelerating customer acquisition in underpenetrated geographies.
Global Fixed Asset Management Software Market Segmentation
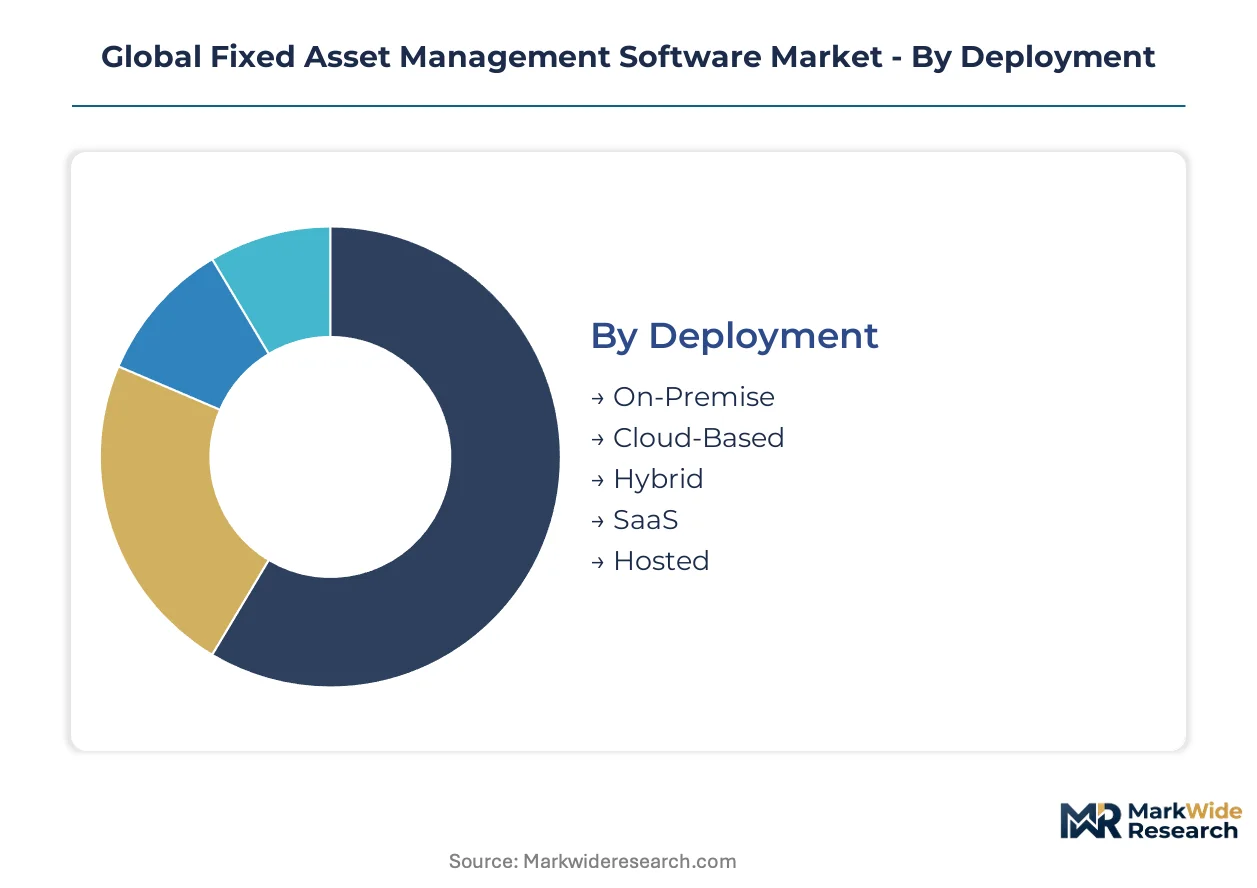
Fixed asset management software segments reflect divergent procurement patterns across enterprise maturity levels. Cloud-native architectures dominate new customer acquisition while hybrid deployments persist among established manufacturing bases with legacy ERP investments.
Deployment:
Channel mix varies sharply by deployment model: direct enterprise sales anchor on-premise and hybrid implementations, while cloud-based and SaaS variants flow through partner marketplaces and self-service portals.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance overhead for mid-market manufacturers. German automotive suppliers and US utility operators prioritize these platforms to satisfy EU CSRD carbon-footprint tagging mandates without infrastructure capital expenditure.
- SaaS:Subscription pricing with consumption-based scaling appeals to Indian electronics manufacturers qualifying for PLI scheme incentives. Field service organizations in Brazil favor per-asset pricing that aligns software costs with register growth rather than upfront licensing.
- On-Premise:Air-gapped installations persist among defense contractors and critical infrastructure operators subject to national security data sovereignty requirements.
- Hybrid:Synchronization layers bridge legacy depreciation databases with cloud reporting modules, creating parallel maintenance burdens that extend deployment timelines.
- Hosted:Single-tenant managed deployments serve healthcare providers navigating FDA 21 CFR Part 11 validation requirements for electronic equipment records.
By volume, Cloud-Based deployments lead. By growth pace, SaaS is expanding most quickly.
Solution Type:
Cost tier stratification separates compliance modules commanding premium pricing from standardized asset tracking functions.
- Compliance Management:Audit-ready transparency engines embed SEC disclosure rules, EU CSRD sustainability directives, and ISO 55000 certification workflows. Financial services firms in the United States and Netherlands prioritize these capabilities to streamline multi-jurisdiction regulatory filings.
- Asset Tracking:Mobile-first barcode and RFID interfaces dominate mid-market field operations. Indian construction firms and Brazilian logistics providers deploy these systems to compress equipment location verification cycles.
- Depreciation Management:Automated schedule calculations with ERP chart-of-accounts integration serve manufacturing controllers migrating from spreadsheet-based historical records.
- Asset Maintenance:Predictive algorithms layered atop sensor networks enable condition-based servicing for German automotive assembly lines and US energy substations.
- Inventory Management:Spare parts synchronization modules link procurement systems with maintenance scheduling for aviation MRO providers under FAA digital logging mandates.
By margin contribution, Compliance Management commands the highest premium. By customer expansion velocity, Asset Tracking is gaining share fastest.
Application:
Application concentration maps directly to industrial asset base modernization cycles across specific national programs.
- Manufacturing:Predictive maintenance modules compress equipment downtime for German automotive suppliers and US industrial firms automating ISO 55000 certification documentation.
- Energy Production:Grid modernization investments drive accelerated replacement cycles for utility operators deploying edge computing nodes at substations.
- Government:Asset disposal audit trails satisfy public sector transparency requirements in India and the United States.
- Transportation:FAA maintenance logging standards push US-based MRO providers toward mobile-first equipment qualification records.
- Telecommunications:Tower and infrastructure lifecycle tracking supports 5G rollout depreciation schedules.
- Education:Campus equipment registers with grant-funded acquisition tracking serve university research facilities.
By installed base, Manufacturing dominates. By investment intensity, Energy Production shows the steepest expansion trajectory.
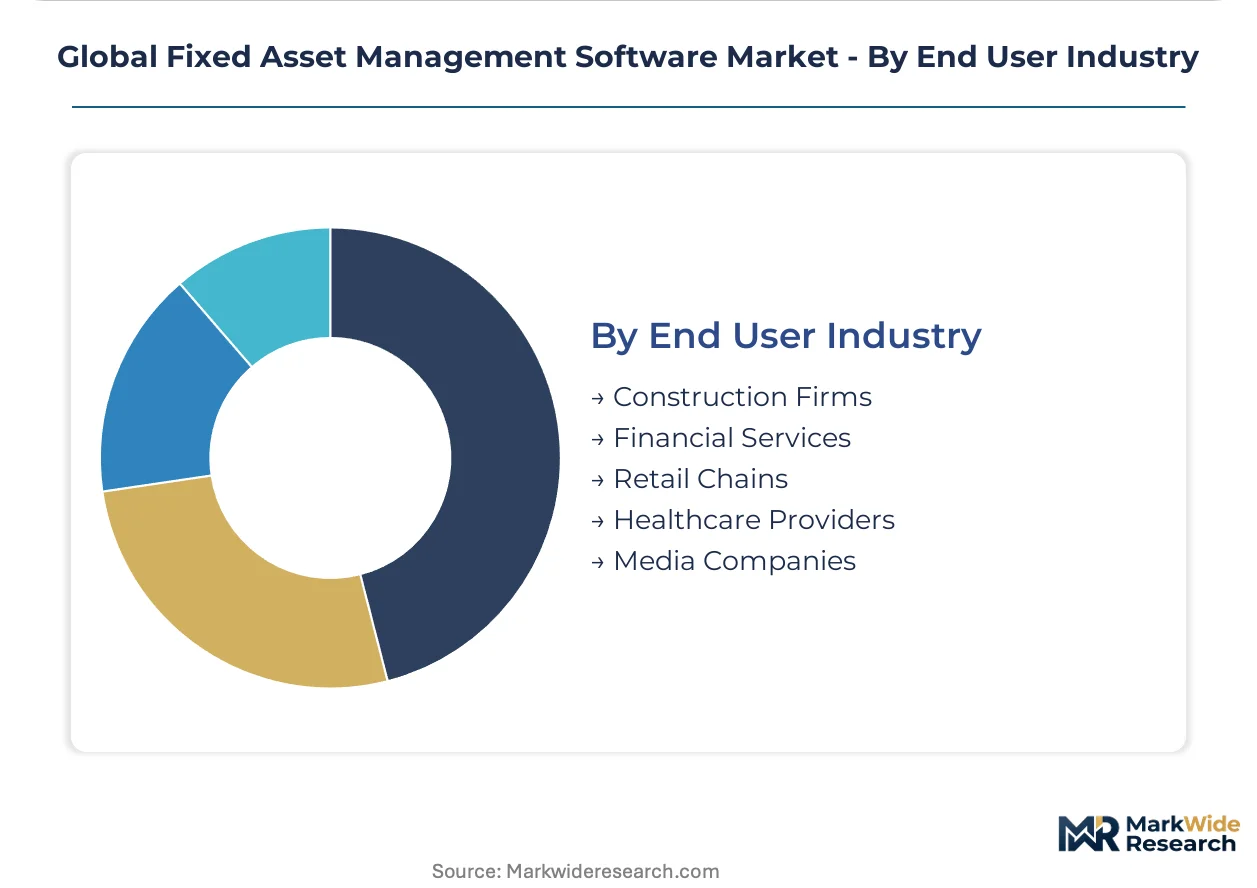
End User Industry:
Customer type determines implementation complexity, with healthcare and financial services demanding vertical-specific compliance layers.
- Healthcare Providers:FDA equipment qualification rules for medical device calibration and validation drive specialized module adoption. Hospital networks prioritize platforms with built-in 21 CFR Part 11 electronic record capabilities.
- Financial Services:SEC disclosure requirements and audit-ready depreciation schedules anchor procurement criteria for US-based asset managers and insurance underwriters.
- Construction Firms:Mobile field access for distributed equipment registers serves Indian infrastructure contractors and Brazilian project developers.
- Retail Chains:Point-of-sale hardware lifecycle tracking with lease management integration supports multi-location rollout planning.
- Media Companies:Broadcast equipment depreciation with content production tax credit documentation serves studio operators.
By contract value, Healthcare Providers lead. By platform switching frequency, Financial Services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure requirements anchor software procurement patterns in the United States, while EU CSRD mandates and India's PLI scheme reshape adoption trajectories across their respective industrial bases.
United States
Manufacturing firms automate depreciation schedules to satisfy SEC audit trails. FAA maintenance logging standards push aviation MRO providers toward mobile-first equipment qualification systems. Dallas-Fort Worth aerospace clusters and Houston energy corridors deploy predictive maintenance modules for grid modernization assets.
Germany
Automotive suppliers compress equipment downtime through sensor-network integration. EU CSRD carbon-footprint tagging mandates force granular asset-level emissions tracking. Stuttgart industrial corridors and Bavarian manufacturing belts prioritize cloud-native platforms for ISO 55000 certification workflows.
India
Electronics manufacturers qualifying for PLI scheme incentives demand consumption-based SaaS pricing. CEA grid modernization directives accelerate utility software replacement cycles. Tamil Nadu automotive belts and Karnataka electronics corridors adopt cloud-first asset registers for assembly line modernization.
United Kingdom
Financial services firms prioritize audit-ready transparency engines for multi-jurisdiction regulatory filings. FCA disclosure expectations align with SEC-equivalent reporting density. London financial districts and Manchester industrial zones deploy compliance management modules for asset depreciation documentation.
Japan
Precision manufacturers integrate predictive algorithms for condition-based equipment servicing. METI industrial digitization guidelines encourage sensor-network adoption. Nagoya automotive clusters and Osaka machinery belts implement edge computing nodes for real-time utilization tracking.
Global Fixed Asset Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ERP-native providers anchoring large manufacturing accounts through database integration depth while mobile-first specialists capture mid-market field operations. The market structure reflects consolidation pressure from bundled lifecycle management modules. Three archetypes dominate: ERP-integrated platforms, cloud-native specialists, and vertical compliance modules. Competitive moves center on strategic partnerships for IoT sensor integration and portfolio diversification into sustainability reporting engines.
Within the integrated tier, Oracle Corp. and SAP SE exemplify ERP-native anchoring strategies, while Asset Panda LLC occupies a position among mobile-first specialists targeting distributed field operations. Oracle Corp. represents database-native lifecycle module approaches that sustain renewal rates through chart-of-accounts integration. SAP SE exemplifies manufacturing account penetration through ERP ecosystem depth. Asset Panda LLC anchors the mid-market vector with interface-first deployment models for construction and logistics field teams.
| Leading Market Players |
|---|
| Oracle Corp. |
| SAP SE |
| Infor Inc. |
| Sage Group Plc |
| International Business Machines Corp. |
| Acumatica Inc. |
| Asset Panda LLC |
| NetSuite |
| Microsoft |
| Others |
Supply & Pricing Matrix
EU CSRD sustainability disclosure mandates gate vendor qualification for enterprise procurement while simultaneously stratifying price tiers through compliance certification requirements. Buyers demand audit-ready carbon-footprint engines alongside traditional depreciation modules, forcing vendors to absorb R&D costs or pass through premium pricing.
Pricing Analysis
Contract structures stratify across annual SaaS subscriptions, multi-year enterprise licenses, and consumption-based per-asset pricing. Three-tier pricing structure across premium, standard, and economy levels separates compliance-certified platforms with ISO 55000 validation from basic asset tracking tools. Price differentiation hinges on vertical integration depth and geographic data residency guarantees. Pricing pressure stems from ERP-native bundling by Oracle and SAP, compressing margins for standalone vendors. Mid-market field service organizations exhibit highest price sensitivity, while healthcare providers under FDA 21 CFR Part 11 mandates show lowest.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore elevates inbound logistics costs for edge computing hardware components sourced from Taiwan and South Korea. Software supply chains draw from cloud infrastructure providers concentrated in the United States, Germany, and India, with raw dependencies on semiconductor chips, sensor networks, and data center capacity. Single-source vulnerability concentrates in hyperscaler compute availability. Distribution runs through direct enterprise sales for on-premise implementations and partner marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
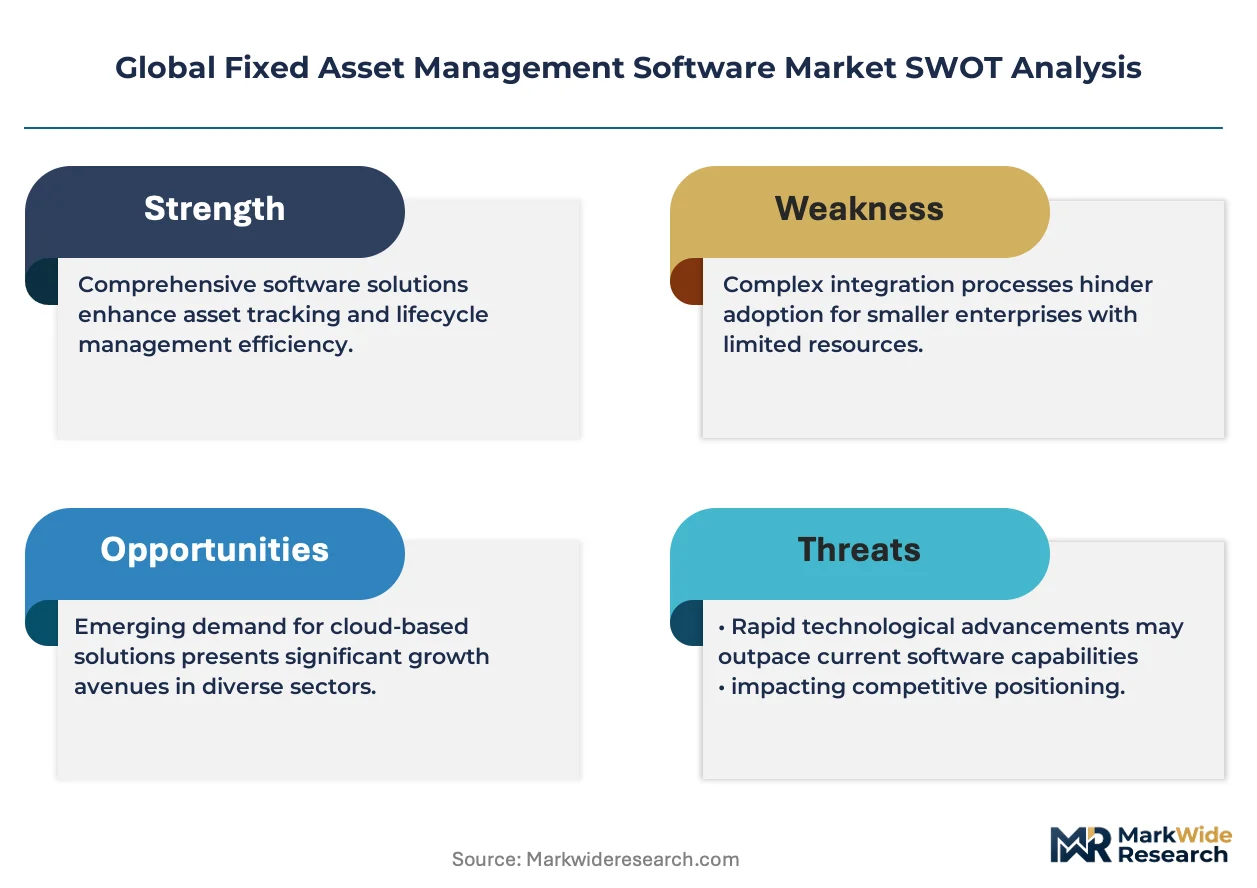
Fixed asset management software constitutes a defensive-moat market where regulatory entrenchment creates prohibitive switching costs. Enterprise customers face 8-14 month deployment timelines and historical data migration complexity that locks in incumbent platforms.
For Market Incumbents: Secure certification velocity advantage by accelerating ISO 55000 and EU CSRD compliance module updates ahead of regulatory deadlines. Deepen ERP integration moats through chart-of-accounts native architecture that elevates substitution costs. Threat from ERP-native bundling by Oracle and SAP demands continuous R&D investment in predictive maintenance algorithms. For New Entrants and Emerging Players: FDA 21 CFR Part 11 validation fast-tracks open vertical-specific healthcare modules with lower competitive density than manufacturing. White-space concentrates in Indian electronics manufacturers qualifying for PLI scheme incentives, where consumption-based SaaS pricing aligns with capital-constrained procurement patterns. Go-to-market through mobile-first field operations in Brazilian logistics and Indian construction bypasses entrenched ERP relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as multi-tenant architectures reduce per-customer infrastructure provisioning. Long-term viability favors platforms with sustainability reporting engine differentiation and IoT sensor integration partnerships. Acquisition target archetype: mid-market specialists with vertical compliance modules and established channel partner networks. Signal to watch: PLI scheme disbursement velocity in India as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectivity with SAP S/4HANA and Oracle Fusion sustains renewal rates through data model unification. |
| Strategic Partnership | IoT sensor network alliances with German automotive suppliers enable predictive maintenance differentiation. |
| Acquisition of Specialist Firm | Vertical compliance modules for FDA 21 CFR Part 11 and FAA maintenance logging expand addressable market. |
| Product Launch | CSRD-mandated carbon-footprint engines embed emissions calculation alongside financial depreciation. |
| Geographic Expansion | Cloud-first deployment in Tamil Nadu and Karnataka automotive corridors captures PLI scheme-driven modernization. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and integration specialists across manufacturing, healthcare, and energy verticals and refined through secondary validation against SEC filings, EU regulatory directives, hyperscaler capex disclosures, and ISO certification databases. Bottom-up deployment model sizing triangulated against top-down enterprise software spend estimates.
Variance-decomposition framing isolated growth contributions across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern. CAGRs were derived from regression analysis against capital expenditure cycles and regulatory mandate timelines. Forecast inputs incorporated cloud migration velocity under EU CSRD and US SEC disclosure rules, plus sensor network adoption curves in German automotive and US utility sectors.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and cloud infrastructure availability; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Spa and Salon Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Global Kiosk Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
France Digital Marketing Software Market
Software & Services
Movie Editing Software Market
Software & Services
Business Analytics Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Spend Analysis Software Market
Software & Services
North America Automotive Software Market
Software & Services
Global Vendor Management Software Market
Software & Services
Global App Builder Software Market
Software & Services
Design Engineering Software Market
Software & Services
Global Policy Management Software Market