
 Middle East and Africa Digital Signage Software Market | 2026-2036
Middle East and Africa Digital Signage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Digital Signage Software Market Foresight
Multi-source vendor strategies is repositioning procurement patterns across the Middle East and Africa Digital Signage Software Market as buyers seek resilience against supply constraints. Samsung Electronics Co., Ltd. dominates hardware-software bundling across Gulf retail deployments. NEC Corporation anchors enterprise-grade installations through deep channel partnerships in South Africa and Nigeria. Scala differentiates via specialized content management tools for luxury hospitality verticals.
Digital signage software comprises platforms that schedule, distribute, and render multimedia content across networked display endpoints, typically operating through IP-connected players with centralized remote management capabilities. The primary commercial purpose centers on dynamic visual communication that replaces static messaging with updatable, targeted, and sometimes interactive screen experiences. Content Management systems capture the largest installed base as legacy on-premises deployments persist across budget-constrained African education and healthcare sectors. Cloud-Based Solutions represent the fastest-expanding deployment architecture, particularly where Gulf retailers prioritize rapid rollout across franchise locations without dedicated IT infrastructure. Interactive Displays command premium pricing in wayfinding and experiential retail applications, though unit volumes remain constrained by higher per-screen software licensing costs.
Saudi Arabia's Communications and Information Technology Commission and South Africa's Information Regulator impose data localization and consent frameworks that shape cloud deployment architectures and audience measurement capabilities. The UAE's cybersecurity standards for critical infrastructure additionally constrain edge computing configurations in transportation and government applications. Stakeholders must evaluate whether hybrid deployment models can satisfy divergent data sovereignty requirements without fragmenting operational scalability.
Market Dynamics
Cloud migration is compressing deployment cycles across Gulf retail networks while data localization mandates in Saudi Arabia and South Africa force hybrid architectural compromises that fragment vendor standardization.
Growth Catalysts
- Smart city infrastructure mandates:UAE government investments in transportation hubs and public venues are generating large-format display procurement contracts with multi-year software licensing terms.
- POPIA compliance frameworks:South Africa's Protection of Personal Information Act is accelerating demand for privacy-certified audience analytics modules within digital signage platforms.
- Franchise network expansion:Retail chains across Saudi Arabia and the Emirates are deploying centralized content management systems to synchronize brand messaging across dozens of new locations quarterly.
Market Restraints
- Data sovereignty fragmentation:Saudi Arabia's Communications and Information Technology Commission localization requirements prevent pure-cloud architectures from serving cross-border franchise operations without redundant infrastructure.
- Edge hardware cost concentration:Industrial-grade media players with IP65 ratings for Gulf outdoor deployments carry 3-4x cost premiums versus indoor equivalents, constraining network scale.
- Skills pipeline gaps:Networked AV integration expertise concentrates in Johannesburg, Dubai, and Riyadh, leaving secondary cities dependent on fly-in technicians with 48-72 hour response windows.
Strategic Opportunities
- Nigeria's retail formalization:Lagos and Abuja shopping mall construction is creating first-mover positioning for cloud-native signage platforms targeting mid-market apparel and quick-service restaurant chains.
- Interactive wayfinding convergence:Touch-enabled directory systems in UAE healthcare facilities and Qatar transit hubs are converging with mobile app integration to capture premium per-screen licensing.
- Egyptian tourism recovery infrastructure:Government-backed resort and museum digitization programs are soliciting turnkey content management proposals with Arabic-localized workflow tools.
Industry Challenges
- Cybersecurity certification timelines:UAE's critical infrastructure standards for transportation and government signage networks require 6-12 month approval cycles that delay project commissioning.
- Legacy on-premises integration:South African universities and public hospitals maintain decade-old content scheduling systems that resist API-based connectivity with modern cloud dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Digital Signage Software Market |
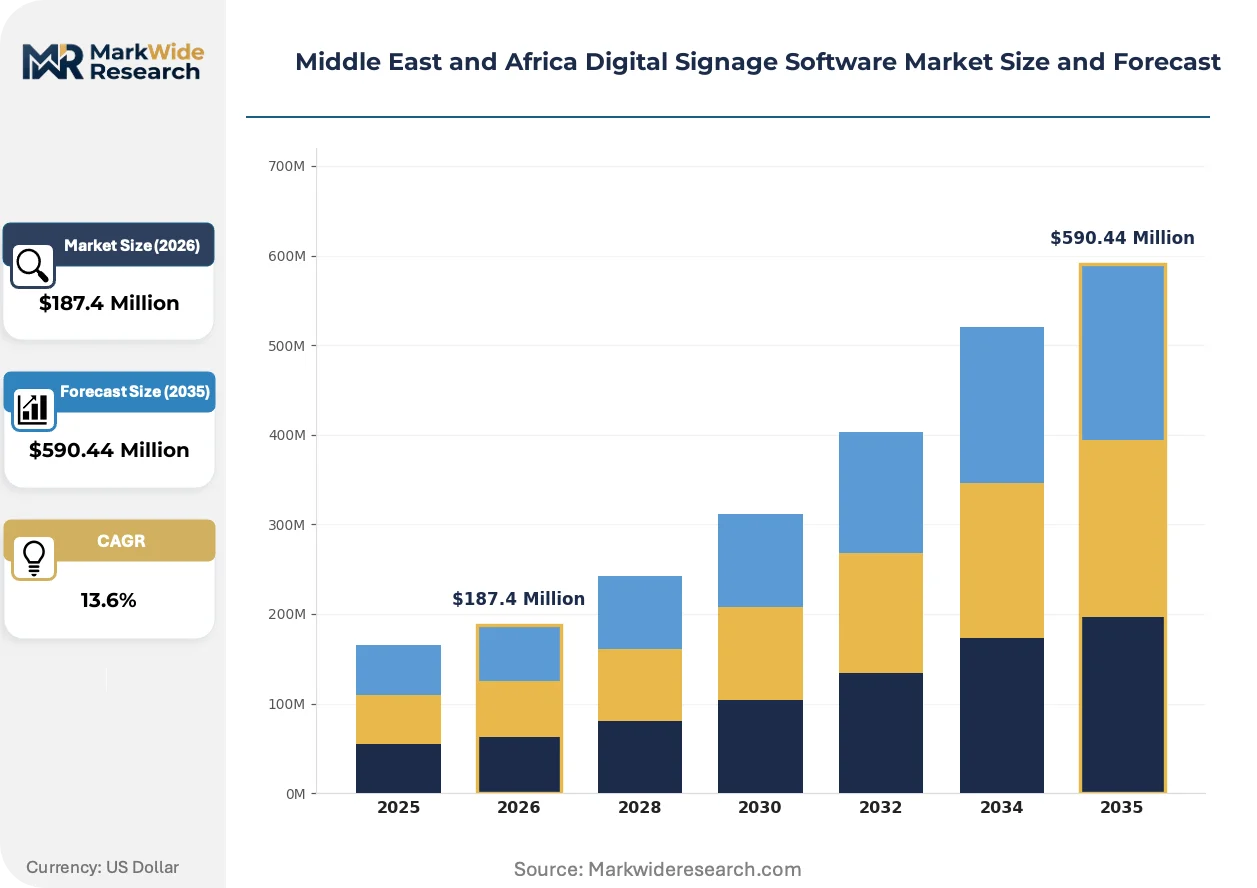
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $590.44 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Management, Video Wall Solutions, Cloud-Based Solutions, Interactive Displays Deployment: On-Premises, SaaS, Hybrid, Edge Computing End User: Retail, Corporate, Transportation, Education Application: Advertising, Wayfinding, Internal Communications, Event Management |
| Companies Covered | Scala, Samsung Electronics Co., Ltd., BrightSign, Navori, Uniguest, NoviSign Digital Signage Inc., YCD Multimedia, NEC Corporation, Panasonic Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Digital Signage Software Market Shifts & Advancements
Artificial intelligence is embedding into audience measurement and content optimization workflows, altering how Gulf retailers and African transit operators justify screen network investments.
Computer vision analytics is converging with digital signage platforms to enable real-time demographic profiling and content adaptation. Luxury retail chains in Dubai Mall and Riyadh's Diriyah Gate are piloting gaze-tracking and dwell-time measurement to optimize promotional rotation. This convergence is compressing the feedback loop between content deployment and performance attribution, forcing legacy CMS vendors to acquire or partner with AI specialists.
Saudi Arabia's Communications and Information Technology Commission data localization directives are mandating in-country server presence for any audience analytics processing. Cloud providers are establishing Riyadh and Jeddah points of presence to maintain contract eligibility with government and critical infrastructure buyers. Enterprise retail deployments are responding by adopting hybrid architectures that keep scheduling and playback local while pushing non-sensitive telemetry to regional clouds.
Subscription-based software procurement is displacing perpetual license purchases among mid-market franchise operators. South African quick-service restaurant chains and Nigerian retail groups are prioritizing vendors offering month-to-month content management access without upfront capital commitment. This preference shift is most visible in markets where IT infrastructure ownership remains concentrated at holding-company level rather than franchisee level.
Middle East and Africa Digital Signage Software Market Segmentation
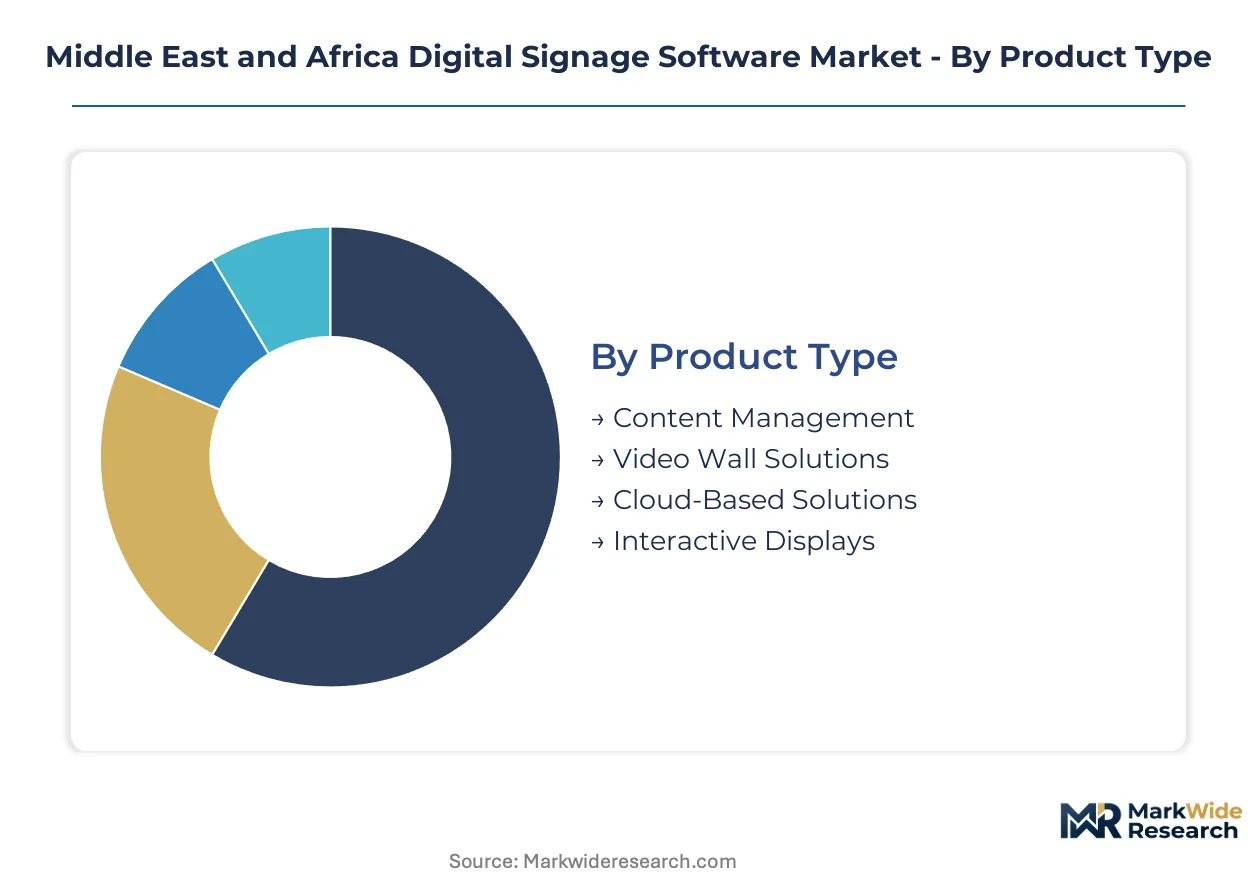
Digital signage software segmentation reveals divergent capital requirements and deployment complexity across the Middle East and Africa. Buyers in Saudi Arabia and the UAE prioritize scalable architectures that balance upfront investment against operational flexibility.
Product Type:
Capital intensity varies sharply by product category, with infrastructure-heavy segments demanding substantial hardware integration budgets.
- Content Management:Core scheduling and distribution platforms that coordinate multimedia playback across networked endpoints. South African universities and healthcare facilities in Johannesburg and Cape Town sustain legacy on-premises installations due to constrained IT modernization budgets.
- Cloud-Based Solutions:Browser-accessible platforms eliminating local server infrastructure. Gulf retailers across Dubai, Riyadh, and Jeddah favor this architecture for rapid franchise rollout without dedicated technical staff.
- Video Wall Solutions:Multi-panel synchronization software for large-format immersive displays. Command premium licensing in UAE transportation hubs and Qatar stadium infrastructure.
- Interactive Displays:Touch-enabled and sensor-integrated platforms supporting user input. Wayfinding deployments in UAE hospitals and Saudi smart city projects absorb elevated per-screen costs.
Content Management absorbs the bulk of installed capacity; Cloud-Based Solutions are expanding most quickly.
Deployment:
Deployment architecture determines ongoing operational expenditure and regulatory compliance exposure across the region.
- On-Premises:Local server installations with full data custody. South African public institutions under POPIA scrutiny prefer this model for sensitive audience analytics.
- SaaS:Fully managed cloud subscriptions with remote accessibility. Nigerian mid-market retail chains in Lagos adopt this for zero-capital scaling.
- Hybrid:Split architectures keeping scheduling local while pushing telemetry to regional clouds. Saudi Arabia's CITC localization mandates force this configuration for cross-border franchise operators.
- Edge Computing:Distributed processing at display endpoints for low-latency responsiveness. UAE critical infrastructure projects require this for cybersecurity certification.
Hybrid deployments are gaining share fastest as regulatory fragmentation intensifies; On-Premises retains the largest legacy footprint.
End User:
End-user verticals exhibit distinct procurement cycles and integration sophistication requirements.
- Retail:Franchise networks and flagship stores across GCC states. Mall operators in Dubai and Riyadh deploy synchronized brand messaging across dozens of locations.
- Transportation:Airports, metro systems, and logistics hubs. UAE aviation infrastructure drives large-format wayfinding contracts with multi-year software terms.
- Corporate:Internal communication networks and lobby displays. Johannesburg and Nairobi headquarters concentrate demand for enterprise-grade platforms.
- Education:Campus-wide information systems and classroom technology. Budget constraints across African institutions favor basic scheduling tools over advanced analytics.
Retail commands the dominant revenue share; Transportation shows the steepest expansion trajectory.
Application:
Application focus shapes content workflow complexity and integration requirements with adjacent systems.
- Advertising:Programmatic content rotation and audience measurement. Dubai Mall luxury tenants pilot gaze-tracking for promotional optimization.
- Wayfinding:Interactive directory and navigation assistance. Qatar transit hubs and UAE healthcare facilities converge this with mobile app integration.
- Internal Communications:Employee-facing messaging and corporate broadcasting. Corporate headquarters in Riyadh and Johannesburg standardize on unified platforms.
- Event Management:Temporary deployment and real-time content adaptation. Egyptian tourism recovery programs solicit turnkey solutions for museum and resort digitization.
Advertising captures the largest licensing value; Wayfinding climbs fastest as smart city infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon supply chains from East Asian fabrication centers feed hardware assembly operations across Gulf Cooperation Council states, anchoring digital signage deployment capacity in the Middle East and Africa region.
United Arab Emirates
Dubai Mall and Abu Dhabi International Airport drive premium large-format display procurement with multi-year software licensing contracts. The UAE's cybersecurity standards for critical infrastructure mandate edge computing configurations in transportation applications. Riyadh-based systems integrators maintain satellite offices in Dubai to serve Emirates government smart city tenders.
Saudi Arabia
NEOM and Diriyah Gate developments generate concentrated demand for immersive video wall installations across hospitality and retail verticals. The Communications and Information Technology Commission enforces data localization requirements that force hybrid cloud architectures for audience analytics. Jeddah's Red Sea tourism corridor attracts turnkey content management proposals from regional vendors establishing local server presence.
South Africa
Johannesburg corporate headquarters and Cape Town retail chains sustain enterprise-grade platform demand despite constrained IT modernization budgets. The Protection of Personal Information Act shapes procurement specifications for privacy-certified audience measurement modules. Durban's logistics hubs concentrate networked AV integration expertise serving secondary African markets.
Nigeria
Lagos shopping mall construction and Abuja quick-service restaurant expansion create first-mover positioning opportunities for cloud-native signage platforms. The country's national data protection regulator imposes emerging consent frameworks that influence analytics module selection. Port Harcourt's oil sector corporate campuses drive internal communication display network upgrades.
Egypt
Government-backed resort digitization and museum modernization programs solicit Arabic-localized workflow tools from turnkey solution providers. The Egyptian financial services regulator's emerging cybersecurity guidelines shape procurement standards for banking sector lobby displays. Cairo's hospitality clusters concentrate demand for event management and temporary deployment capabilities.
Middle East and Africa Digital Signage Software Market Competitive Landscape
Hardware-software bundling dominates the current landscape across Gulf retail deployments, compressing standalone software vendor margins. The vendor base organizes into three tiers: integrated electronics conglomerates with captive software stacks, specialized content management pure-plays, and hospitality-focused vertical specialists. Strategic archetypes include scale-driven hardware bundlers, cloud-native mid-market platforms, and luxury vertical specialists. Portfolio diversification and geographic channel expansion represent the dominant competitive moves as vendors respond to data sovereignty fragmentation.
Among integrated electronics conglomerates, Samsung Electronics Co., Ltd. and NEC Corporation anchor the hardware-software bundling tier, exemplifying scale-driven competitive positioning through direct Gulf retail penetration and South African enterprise channel depth respectively. Scala occupies a specialist position within luxury hospitality verticals, representing the narrow-focus archetype that commands premium licensing through sector-specific workflow tools. These three patterns—integrated bundling, enterprise channel anchoring, and vertical specialization—collectively structure procurement alternatives for buyers across the region's divergent deployment requirements.
| Leading Market Players |
|---|
| Scala |
| Samsung Electronics Co., Ltd. |
| BrightSign |
| Navori |
| Uniguest |
| NoviSign Digital Signage Inc. |
| YCD Multimedia |
| NEC Corporation |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Franchise procurement centralization across Saudi Arabia and the UAE is compressing vendor margins by demanding bundled hardware-software-service packages, forcing suppliers to absorb media player costs into multi-year licensing contracts while maintaining localized server presence for CITC compliance. This buyer consolidation dynamic shifts pricing power toward holding-company IT departments and away from standalone software vendors.
Pricing Analysis
Warranty and field service bundling now separates premium-tier Gulf deployments from stripped-down Nigerian mid-market contracts, with Dubai mall operators demanding 24-hour technician response SLAs while Lagos retail chains accept remote-only support. Three-tier pricing structure across premium, standard, and economy levels tracks integration complexity and data sovereignty certification rather than core feature differentiation. Cost compression in the mid-market SaaS tier is intensifying because Nigerian and South African franchise groups prioritize month-to-month subscriptions over perpetual licenses. South African public institutions under POPIA scrutiny exhibit the lowest price sensitivity, accepting 40-60% premiums for on-premises audience analytics modules with local data custody.
Supply Chain Analysis
Industrial-grade display panel supply rests on South Korean and Chinese fabrication facilities, with Taiwanese semiconductor foundries feeding media player processor demand and Japanese precision optics anchoring large-format LED module production. Software licensing draws from cloud infrastructure concentrated in UAE and Saudi Arabia to satisfy data localization mandates, while content creation talent clusters in Johannesburg and Dubai. Single-source vulnerability runs through East Asian display driver IC suppliers exposed to regional logistics chokepoints. Distribution runs through Riyadh and Dubai-based systems integrators who bundle hardware procurement with software configuration and ongoing managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Networked AV integration expertise scarcity across secondary African cities props pricing for fly-in technical services, creating durable margin pools for vendors with established Johannesburg and Dubai service footprints.
For Market Incumbents: Anchor channel control through exclusive partnerships with Saudi systems integrators possessing CITC-certified data center operations, insulating against cloud-native entrants lacking localized server infrastructure. Deepen vertical integration into Arabic-localized content creation workflows to defend against hospitality-focused specialists capturing Diriyah Gate and Red Sea tourism contracts. Prioritize API development for legacy on-premises South African university and hospital installations resisting full cloud migration. For New Entrants and Emerging Players: Systems integrators without captive software stacks represent the most penetrable channel entry point, particularly those serving Nigerian retail formalization in Lagos mall construction lacking established digital signage relationships. Target cloud-native SaaS positioning for mid-market quick-service restaurant chains in Abuja and Port Harcourt where IT infrastructure ownership sits at holding-company level rather than franchisee level. Pursue white-label licensing arrangements with Dubai-based hardware distributors seeking software differentiation against Samsung and NEC bundling. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing hospitality-specific workflow tools given NEOM and Diriyah Gate immersive video wall deployment timelines. Long-term viability favors vendors with hybrid architecture capabilities spanning on-premises scheduling and regional cloud telemetry. Acquisition target archetype: AI-enabled audience analytics platforms with Saudi data localization compliance already operational. Watch CITC enforcement intensity against pure-cloud deployments as the signal for hybrid architecture demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Development | Satisfies Saudi CITC mandates while preserving operational scalability for cross-border franchise operators. |
| AI Audience Analytics Acquisition | Compresses feedback loops between content deployment and performance attribution for Dubai luxury retail. |
| Arabic Localization Investment | Captures Egyptian government resort digitization and museum modernization program tenders. |
| Systems Integrator Channel Partnership | Secures access to UAE critical infrastructure projects requiring 6-12 month cybersecurity certification cycles. |
| Edge Computing Configuration Certification | Unlocks UAE transportation and government applications with mandated low-latency processing requirements. |
Research Methodology
Independent corroboration across platform engineering directors, AV integration specialists, and franchise IT procurement officers underwrites the qualitative findings, with secondary validation drawing from CITC regulatory filings, POPIA compliance documentation, and hyperscaler regional cloud expansion disclosures. Bottom-up triangulation against top-down market sizing ensures segmentation integrity across deployment architecture and end-user verticals.
Comparable-period anchoring to legacy on-premises installation bases and cloud migration trajectories structured the projection horizon, with modeled dimensions spanning deployment model, organization scale, vertical application, integration complexity, and regional regulatory cluster. CAGRs were derived from install-base growth rates and average revenue per screen expansion patterns, incorporating franchise network rollout schedules and smart city infrastructure procurement timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential relaxation of Saudi data localization requirements, abrupt POPIA enforcement shifts affecting South African analytics module demand, and East Asian semiconductor supply disruptions impacting media player availability. Forecasts reflect documented assumptions about franchise expansion velocity and government digitization program commitment levels. A small set of named triggers warrants ongoing watch: CITC regulatory interpretation changes, Nigerian data protection regulator enforcement emergence, and UAE cybersecurity standard revision cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Storyboarding Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global UIUX Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Email Marketing Software Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Audience Response Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Illustration Software Market
Software & Services
Performing Arts Software Market