
 Intelligent Conveyor System Market | 2026-2036
Intelligent Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Conveyor System Market Outlook
ISO 3691-4 safety certification for autonomous mobile robots is rotating supplier eligibility across Europe, forcing subsystem vendors to recertify every three years. Daifuku Co., Ltd. leverages its captive testing facilities in Osaka to fast-track compliance cycles. Schneider Electric anchors its position through in-house production of safety-rated PLC modules that command premium placement in retrofit installations. Vanderlande competes by specializing in airport baggage handling subsystems where certification depth creates defensive moats.
An intelligent conveyor system integrates motorized transport mechanisms with programmable logic controllers, sensor arrays, and network connectivity to autonomously route, sort, and track materials through industrial workflows; typical configurations achieve throughput rates exceeding 15,000 units per hour with positional accuracy within two millimeters. Belt and roller configurations dominate installed base volumes but carry thinner margins due to commoditized mechanical components. IoT-enabled and AI-driven technology layers capture disproportionate margin pools as buyers prioritize predictive maintenance and dynamic routing optimization over hardware replacement cycles.
FDA food safety modernization rules in the United States and EU Machinery Directive compliance frameworks in Europe are elevating traceability and hygienic design requirements for food processing installations. China's SAMR enforces GB standard conformity for networked industrial equipment, creating a three-regulator compliance landscape that shapes product development roadmaps. Stakeholders must monitor how divergent cybersecurity certification timelines across these jurisdictions affect cross-border deployment economics and service architecture decisions.
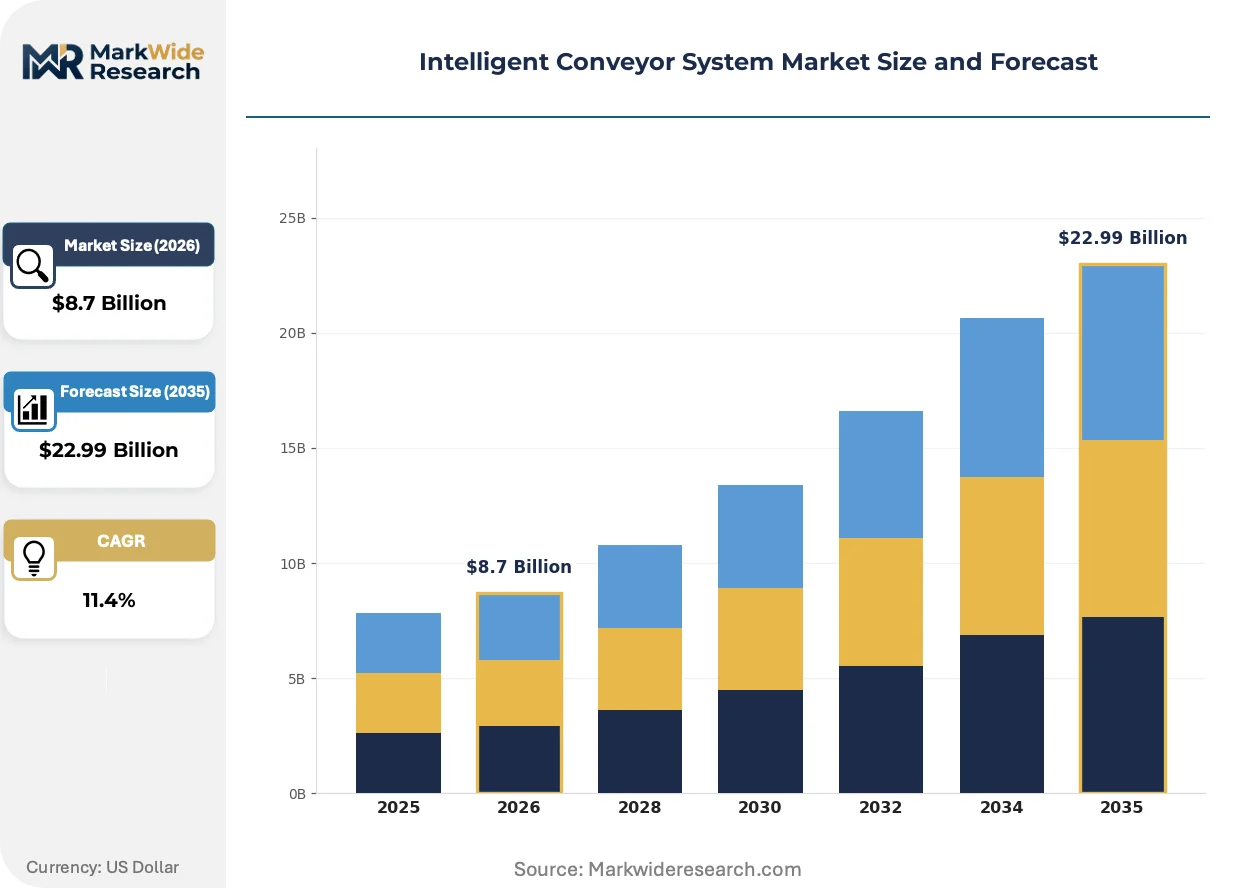
Market Dynamics
ISO 3691-4 safety certification is rotating supplier eligibility across Europe, forcing subsystem vendors to recertify every three years and compressing the competitive set to those with captive testing infrastructure.
Growth Catalysts
- EU Machinery Directive tightening:Autonomous material handling equipment faces elevated safety requirements, driving replacement demand for certified intelligent conveyor installations in German e-commerce fulfillment centers.
- AI-driven sortation systems:Machine learning algorithms now optimize routing decisions in real-time, cutting dwell times and enabling throughput rates that justify premium system pricing for parcel handlers.
- Yangtze River Delta concentration:Manufacturing corridor density in Jiangsu and Zhejiang provinces generates localized demand for networked conveyor systems with predictive maintenance capabilities.
Market Restraints
- Steel and rare-earth magnet cost volatility:Motorized roller components depend on NdFeB permanent magnets and cold-rolled steel, exposing system integrators to input price swings that compress quoted margins.
- Captive testing facility concentration:Fast-track ISO 3691-4 compliance requires access to specialized proving grounds concentrated in Japan and Germany, disadvantaging vendors without regional presence.
- Three-regulator compliance burden:Divergent FDA food safety, EU Machinery Directive, and China SAMR GB standard timelines force parallel development tracks that elongate product release cycles.
Strategic Opportunities
- Airport baggage handling retrofit:Certification depth in this vertical creates defensive moats where specialized subsystem vendors command premium placement against generalist competitors.
- India PLI scheme alignment:Production-linked incentives for advanced manufacturing equipment create tariff advantages for localized assembly of AI-enabled sortation modules.
- Predictive maintenance unbundling:IoT sensor data monetization is emerging as a discrete revenue stream separate from hardware sales, with aftermarket service contracts capturing recurring margin pools.
Industry Challenges
- Functional safety engineer scarcity:ISO 13849 and IEC 62061 certification expertise sits concentrated with aging specialists in Germany and Japan, constraining vendor expansion timelines.
- Legacy PLC integration friction:Brownfield installations require protocol translation layers between proprietary safety-rated PLCs and modern Ethernet/IP networks, extending commissioning durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Conveyor System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Modular, Belt, Roller End User: Manufacturing, Warehousing, Distribution, Food Processing Technology: IoT, Sensor-Based, AI-Driven, Robotics Installation: On-Premise, Integrated, Standalone, Retro-Fit |
| Companies Covered | Schneider Electric, Daifuku Co., Ltd., Dematic, Honeywell Intelligrated, SSI SCHAEFER Group, Vanderlande, Swisslog AG, BEUMER Group, Murata Machinery, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Conveyor System Market Strategic Shifts
Modular software architectures are decomposing monolithic control systems into interoperable subsystems, enabling buyers to upgrade intelligence layers without full mechanical replacement. This shift is compressing technology refresh cycles and redistributing value capture toward software vendors.
Edge computing nodes embedded directly in motorized drive rollers are decomposing centralized PLC architectures into distributed intelligence networks. Parcel handlers in the Netherlands and Belgium are deploying these configurations to achieve sub-50-millisecond routing decisions. The structural consequence is decomposing the traditional automation hierarchy into flat, peer-to-peer device networks that reduce wiring complexity and commissioning labor.
China's SAMR enforcement of GB/T 22239 cybersecurity baselines for networked industrial equipment is forcing foreign vendors to establish localized firmware development centers. The industrial consequence is segmented product roadmaps where export-configured systems diverge from domestic China builds. Food processing installations in Shandong and Guangdong provinces are most affected, with buyers now requiring separate compliance documentation for cross-border deployments.
Buyers are unbundling after-sales service contracts from initial system procurement, treating predictive maintenance subscriptions as discrete purchasing decisions evaluated on uptime guarantees rather than brand loyalty. This pattern is most visible among third-party logistics operators in Germany's Ruhr industrial cluster, where procurement teams now benchmark service offerings through competitive tender rather than incumbent renewal.
Intelligent Conveyor System Market Segmentation
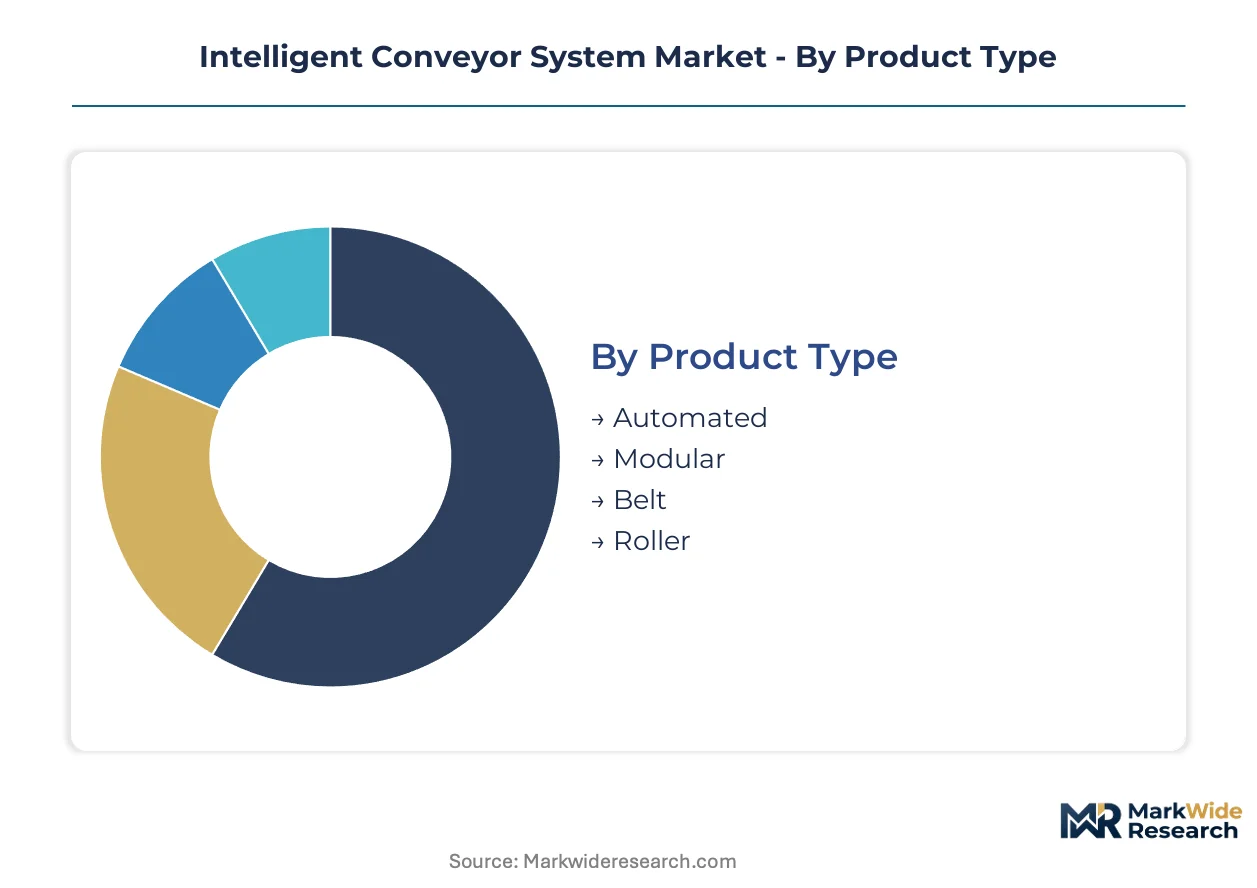
Intelligent conveyor system buyers select configurations based on throughput requirements, legacy infrastructure constraints, and regulatory exposure. Technology layering decisions determine margin capture, with hardware commoditization pushing value toward software-enabled intelligence.
Product Type:
Margin pools concentrate in configurations that integrate programmable control layers with mechanical transport infrastructure.
- Automated:Systems incorporate motorized drive units with programmable logic controllers and sensor feedback loops for autonomous routing decisions. German e-commerce fulfillment centers in Saxony and Lower Saxony are expanding automated deployments to meet EU Machinery Directive safety certification requirements.
- Modular:Decomposable subsystems enable buyers to upgrade intelligence layers without full mechanical replacement. Netherlands parcel handlers in Rotterdam and Eindhoven are adopting modular architectures to compress technology refresh cycles and reduce commissioning downtime.
- Belt:Continuous-loop transport configurations dominate legacy installed bases with standardized mechanical components.
- Roller:Motorized roller systems with embedded edge computing nodes are gaining traction in high-throughput sortation applications.
Belt configurations hold installed capacity. Modular systems are rotating up the share rankings.
End User:
Application-specific regulatory exposure shapes procurement priorities and certification depth requirements.
- Manufacturing:Production-line integration demands sub-millimeter positional accuracy and real-time work-in-process tracking. China's Yangtze River Delta manufacturing corridor in Jiangsu and Zhejiang provinces is driving demand for networked conveyor systems with predictive maintenance capabilities.
- Warehousing:E-commerce fulfillment operations prioritize throughput velocity over precision, favoring configurations with dynamic routing optimization. Germany's Ruhr industrial cluster is unbundling after-sales service contracts from initial procurement, treating predictive maintenance as discrete purchasing decisions.
- Distribution:Third-party logistics operators benchmark service offerings through competitive tender rather than incumbent renewal.
- Food Processing:FDA food safety modernization rules and EU Machinery Directive compliance frameworks elevate traceability and hygienic design requirements.
Manufacturing holds installed capacity. Warehousing is rotating up the share rankings.
Technology:
Intelligence layering determines pricing power, with data-enabled offerings capturing premium placement over commodity hardware.
- IoT:Networked sensor arrays transmit operational telemetry to cloud platforms for centralized monitoring and optimization. Belgium parcel handlers are deploying IoT-enabled configurations to achieve predictive maintenance capabilities and reduce unplanned downtime.
- AI-Driven:Machine learning algorithms optimize routing decisions in real-time, cutting dwell times and enabling throughput rates that justify premium system pricing. Netherlands distribution centers are adopting AI-driven sortation to handle peak seasonal volumes without proportional labor scaling.
- Sensor-Based:Photoelectric and proximity sensors provide positional feedback for basic automation control loops.
- Robotics:Collaborative robot integration with conveyor subsystems enables flexible handling of variable package geometries.
Sensor-based configurations hold installed capacity. AI-driven systems are rotating up the share rankings.
Installation:
Deployment architecture determines integration complexity and service contract structures.
- Retro-Fit:Brownfield installations require protocol translation layers between proprietary safety-rated PLCs and modern Ethernet/IP networks, extending commissioning durations. Germany's established industrial base is driving retro-fit demand as aging systems require ISO 3691-4 recertification.
- Integrated:Greenfield deployments with unified control architectures reduce wiring complexity and commissioning labor. China's Shandong and Guangdong provinces are requiring separate compliance documentation for cross-border deployments of integrated systems under SAMR GB/T 22239 cybersecurity baselines.
- On-Premise:Localized control systems maintain operational continuity without cloud dependency.
- Standalone:Self-contained units serve discrete process steps without upstream or downstream system coupling.
On-premise configurations hold installed capacity. Integrated systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement teams in German e-commerce fulfillment centers, Chinese Yangtze River Delta manufacturing plants, and US food processing facilities drive regional demand concentration. Buyers prioritize ISO 3691-4 certification depth, predictive maintenance capabilities, and divergent regulatory compliance across FDA, EU Machinery Directive, and China SAMR frameworks.
Germany
Ruhr industrial cluster procurement teams unbundle after-sales service contracts from initial system purchases. EU Machinery Directive tightening elevates safety requirements for autonomous material handling equipment. Saxony and Lower Saxony e-commerce fulfillment centers expand automated conveyor deployments to meet recertification deadlines.
China
Yangtze River Delta manufacturing corridor density in Jiangsu and Zhejiang provinces generates localized demand for networked systems. SAMR enforces GB/T 22239 cybersecurity baselines for networked industrial equipment. Shandong and Guangdong food processing buyers now require separate compliance documentation for cross-border deployments.
United States
FDA food safety modernization rules elevate traceability and hygienic design requirements for food processing installations. Brownfield retrofit demand concentrates in established industrial bases requiring ISO 3691-4 recertification. Midwest and Southeast distribution centers prioritize dynamic routing optimization over hardware replacement cycles.
Netherlands
Rotterdam and Eindhoven parcel handlers adopt modular architectures to compress technology refresh cycles. Belgium and Netherlands distribution centers deploy edge computing nodes to achieve sub-50-millisecond routing decisions. Benelux logistics operators benchmark predictive maintenance subscriptions through competitive tender rather than incumbent renewal.
Japan
Captive testing facilities in Osaka fast-track ISO 3691-4 compliance cycles for subsystem vendors. METI industrial automation policies support edge computing integration in motorized drive rollers. Kanto and Kansai manufacturing corridors concentrate functional safety engineering expertise for IEC 62061 certification.
Intelligent Conveyor System Market Competitive Environment
Player mix skews toward diversified industrial automation conglomerates with captive safety-rated component production. Tier concentration favors vendors with in-house testing infrastructure and three-year recertification capabilities. Two strategic archetypes dominate: integrated system providers with end-to-end control architectures, and specialized subsystem vendors with vertical certification depth. Competitive moves center on M&A for regional compliance capabilities and strategic partnerships for localized firmware development.
Among diversified automation conglomerates, Schneider Electric anchors premium placement through in-house safety-rated PLC production. Daifuku Co., Ltd. occupies a position exemplifying fast-track compliance leveraging captive Osaka testing facilities. Vanderlande represents the specialized subsystem archetype with defensive moats in airport baggage handling certification depth.
| Leading Market Players |
|---|
| Schneider Electric |
| Daifuku Co., Ltd. |
| Dematic |
| Honeywell Intelligrated |
| SSI SCHAEFER Group |
| Vanderlande |
| Swisslog AG |
| BEUMER Group |
| Murata Machinery, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Edge computing node substitution for centralized PLC architectures is redrawing supply geography toward Netherlands and Belgium assembly hubs while compressing pricing premiums for legacy control configurations. This displacement simultaneously concentrates component sourcing in East Asian semiconductor corridors and erodes margin buffers for vendors without captive firmware development capabilities.
Pricing Analysis
Cost-plus contracts with steel and NdFeB magnet indexation dominate system integrator agreements, exposing quoted margins to commodity volatility. Pricing stratifies across ISO 3691-4 certified premium tiers, sensor-based standard configurations, and commodity belt-roller economy offerings. Price erosion runs through economy tiers as Chinese vendors expand modular exports. Third-party logistics operators in Germany's Ruhr cluster exhibit highest price sensitivity through competitive service tendering, while airport baggage handlers accept certification premiums.
Supply Chain Analysis
Strategic stockpiling of NdFeB permanent magnets and cold-rolled steel has displaced just-in-time preferences among Japanese and German system integrators facing supply uncertainty. Manufacturing concentration centers on China for motor assemblies, Japan for precision drive components, and Germany for safety-rated PLC modules. Supply chain risk rests on single-source vulnerability for functional safety engineering expertise concentrated in Osaka and Stuttgart. Distribution runs through OEM-direct channels for integrated greenfield deployments and specialized integrators for brownfield retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent conveyor systems are approaching a platform-economics inflection where modular software architectures and interoperable subsystem standards will determine competitive survival, with the shift toward decomposed control hierarchies in Netherlands parcel handling operations demonstrating ecosystem momentum.
For Market Incumbents: Fortify defensive positions by deepening captive production of safety-rated PLC modules following Schneider Electric's vertical integration model, and accelerate ISO 3691-4 recertification investments to compress competitor compliance timelines. Functional safety engineer scarcity in Germany and Japan represents the critical vulnerability to address through specialist acquisition or apprenticeship pipeline development. For New Entrants and Emerging Players: Predictive maintenance subscription unbundling presents the most penetrable service-layer gap where incumbents under-serve third-party logistics operators seeking uptime-guaranteed contracts. Target India's PLI scheme corridors for localized AI-enabled sortation module assembly, leveraging tariff advantages against established import-dependent competitors. Lead with outcome-based pricing models that shift buyer evaluation from capital expenditure to operational expenditure frameworks. For Investors and Strategic Acquirers: The market sits at a consolidation-preparatory phase that favors specialized subsystem vendors with vertical certification depth over diversified conglomerates facing margin compression. Long-term viability over the next decade hinges on software-enabled recurring revenue attachment rates rather than hardware shipment volumes. Watch for edge computing node deployment velocity in Benelux parcel operations as the inflection indicator signaling platform standardization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Safety-Rated Component Production | Schneider Electric's in-house PLC manufacturing anchors premium retrofit placement against module-dependent competitors. |
| Localized Firmware Development Centers | China SAMR GB/T 22239 compliance forces segmented product roadmaps separating export from domestic China builds. |
| Predictive Maintenance Subscription Unbundling | Germany's Ruhr logistics operators now benchmark service offerings through competitive tender rather than incumbent renewal. |
| Airport Baggage Handling Certification Depth | Vanderlande's specialized subsystem expertise creates defensive moats against generalist competitors in retrofit procurement. |
| Edge Computing Node Integration | Netherlands and Belgium parcel handlers deploy distributed intelligence networks achieving sub-50-millisecond routing decisions. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from EU Machinery Directive compliance databases, FDA food safety modernization filings, China SAMR GB standard registries, and customs trade data for motorized conveyor components. Bottom-up installation tracking and top-down industrial automation expenditure analysis provided triangulation across the intelligence layering.
Sensitivity analysis tested forecast robustness against steel price volatility, rare-earth magnet supply disruption scenarios, and regulatory timeline compression across the projection horizon. Segmentation dimensions modeled include product configuration type, end-use application intensity, technology intelligence tier, and installation architecture complexity. CAGRs derived from geometric progression of base-year verified installations and elasticity-adjusted replacement demand curves, with specific inputs for ISO 3691-4 recertification cycle timing and AI-driven sortation adoption velocity in e-commerce fulfillment.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement, FDA food safety frameworks, and China SAMR cybersecurity baselines; material policy shifts would require re-modeling. Specific risks include divergent certification timeline elongation, functional safety engineer supply constraints, and legacy PLC protocol translation friction in brownfield deployments. Revision becomes warranted when edge computing node deployment penetration in European parcel handling crosses critical mass thresholds signaling architectural standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global SCADA Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Factory Automation Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Grippers Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Smart Elevator Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Middle East and Africa Industrial Automation Market