
 Global Omnichannel Retail Commerce Platform Market | 2026-2036
Global Omnichannel Retail Commerce Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Omnichannel Retail Commerce Platform Market Foresight
The EU Green Deal is restructuring procurement criteria for retail technology across European markets. Salesforce leverages its enterprise CRM heritage to anchor cloud-based omnichannel deployments for large-format retailers. Shopify competes through merchant-centric SaaS tooling that simplifies cross-channel inventory synchronization.
An omnichannel retail commerce platform integrates point-of-sale, e-commerce, inventory, and customer data systems into a unified operational layer, typically deployed through API-first cloud architectures that enable real-time stock visibility and order orchestration across physical and digital touchpoints. Cloud-based deployment leads solution type adoption due to lower capital requirements and faster implementation cycles, while order management functionality captures disproportionate margin pools as retailers prioritize buy-online-pickup-in-store and ship-from-store capabilities. Analytics and reporting segments are accelerating as merchants demand predictive demand forecasting and customer lifetime value modeling.
The EU AI Act, GDPR, and California Consumer Privacy Act shape platform development by mandating algorithmic transparency, consent management, and data localization controls that increase compliance costs but create barriers for non-compliant vendors. Japan's METI guidelines on digital platform transparency add another compliance layer for Asia-Pacific deployments. Stakeholders must monitor evolving data sovereignty requirements and assess whether their architecture supports modular compliance upgrades without core system replacement.
Market Dynamics
The convergence of real-time inventory visibility demands with algorithmic personalization requirements is compressing platform architecture cycles. Retailers now require unified data layers that synchronize point-of-sale, warehouse management, and customer identity systems without latency.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated pricing and recommendation engines are forcing retailers to upgrade from legacy siloed systems to auditable unified platforms.
- Ship-from-store capability expansion:Specialty retailers in Germany and Japan are repurposing physical locations as fulfillment nodes, driving demand for distributed order management orchestration.
- API-first cloud architectures:Microservices-based deployment models reduce implementation timelines and enable modular feature activation across heterogeneous retail technology stacks.
Market Restraints
- GDPR data localization costs:The requirement to maintain EU citizen data within territorial boundaries increases infrastructure expenditure and complicates cross-border inventory visibility.
- Cloud concentration risk:Hyper-scale infrastructure providers in the United States dominate hosting capacity, creating vendor lock-in exposure for European and Asian retailers.
- Legacy system technical debt:Mainframe-based inventory systems from the 1990s lack real-time API connectivity, forcing expensive middleware layers or complete replacement.
Strategic Opportunities
- India retail modernization:The country's fragmented kirana store sector presents white-space demand for lightweight mobile-first omnichannel solutions with vernacular language support.
- Predictive demand forecasting convergence:Integration of machine learning models with weather data and social sentiment analysis enables anticipatory inventory positioning.
- Buy-online-pickup-in-store channel innovation:Curbside fulfillment workflows and automated locker networks are expanding addressable transaction volume for grocery and big-box formats.
Industry Challenges
- Real-time data engineering talent scarcity:Platform vendors struggle to hire sufficient Kafka and event-streaming specialists to implement sub-second inventory synchronization.
- Multi-jurisdiction compliance complexity:Simultaneous adherence to GDPR, CCPA, and Japan's METI transparency guidelines requires parallel legal and technical workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Omnichannel Retail Commerce Platform Market |
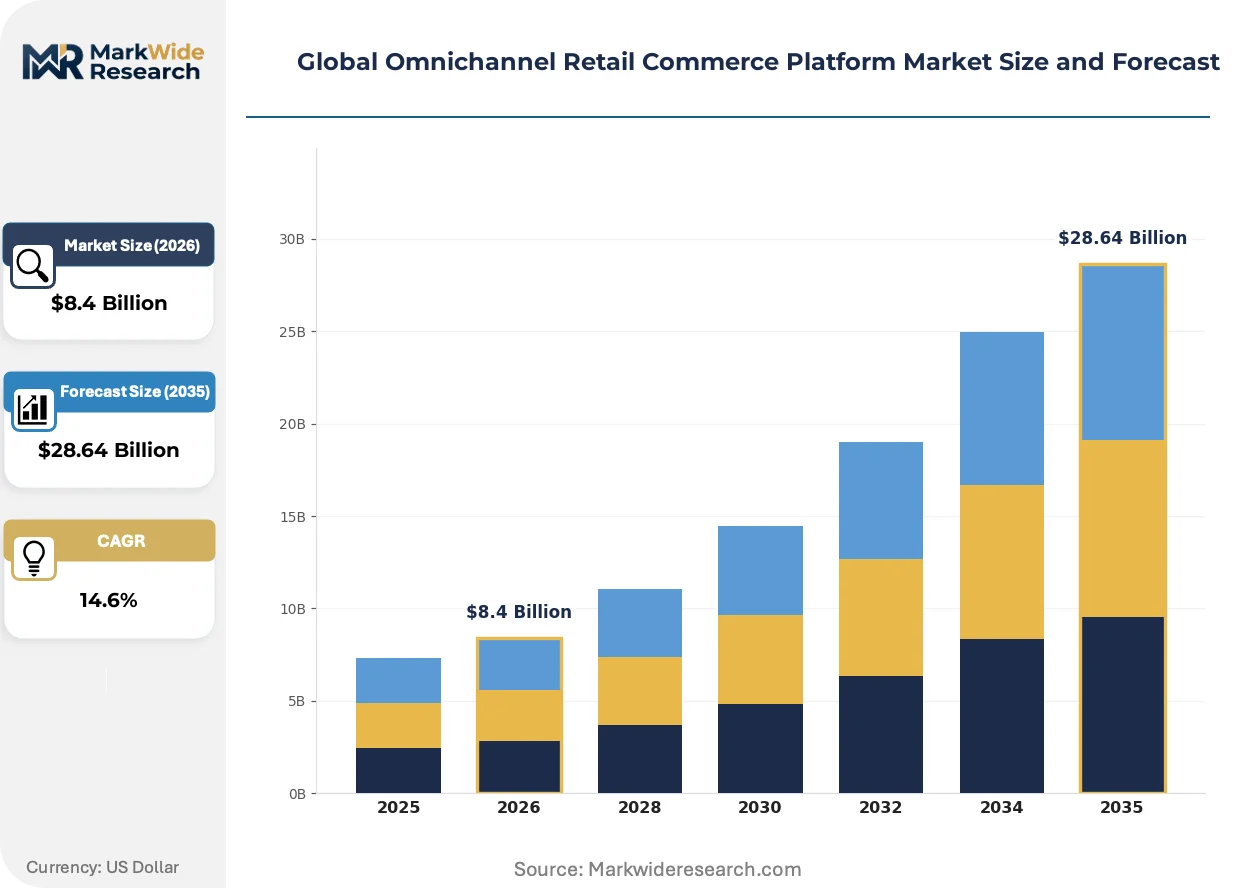
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: E-Commerce Integration, Customer Relationship Management, Inventory Management, Payment Processing, Order Management, Analytics & Reporting Use Case: Personalized Marketing, Unified Customer Experience, Mobile Shopping, Social Commerce, Click & Collect, Loyalty Programs Customer Segment: Specialty Stores, Department Chains, Online Retailers, Wholesale Distributors, Convenience Outlets, Boutique Shops |
| Companies Covered | Insider One, NewStore, Salesforce, Fluent Commerce, Omnisend, Adobe, Klaviyo, ActiveCampaign, Shopify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Omnichannel Retail Commerce Platform Market Shifts & Advancements
Headless commerce architectures are decoupling customer-facing interfaces from back-end systems, enabling retailers to experiment with front-end experiences without core platform disruption. This structural shift is accelerating vendor specialization and API standardization.
Composable commerce technology is consolidating merchant technology procurement around best-of-breed microservices rather than monolithic suites. Mid-market retailers in the United States are adopting this approach fastest, stitching together specialized vendors for search, payments, and fulfillment. The result is compressing incumbent platform pricing power and expanding vendor choice.
Europe's CSRD sustainability disclosure requirements are mandating supply chain emissions tracking from retail technology providers. Platform vendors must now embed carbon accounting APIs and supplier ESG scoring into core product roadmaps. German and French retailers face the earliest compliance deadlines and are driving vendor prioritization.
Merchant procurement patterns are favoring outcome-based pricing tied to transaction volume rather than fixed SaaS subscriptions. This shift transfers demand volatility risk to platform vendors while aligning incentives around conversion optimization. The model is most established among direct-to-consumer brands in California and New York.
Global Omnichannel Retail Commerce Platform Market Segmentation
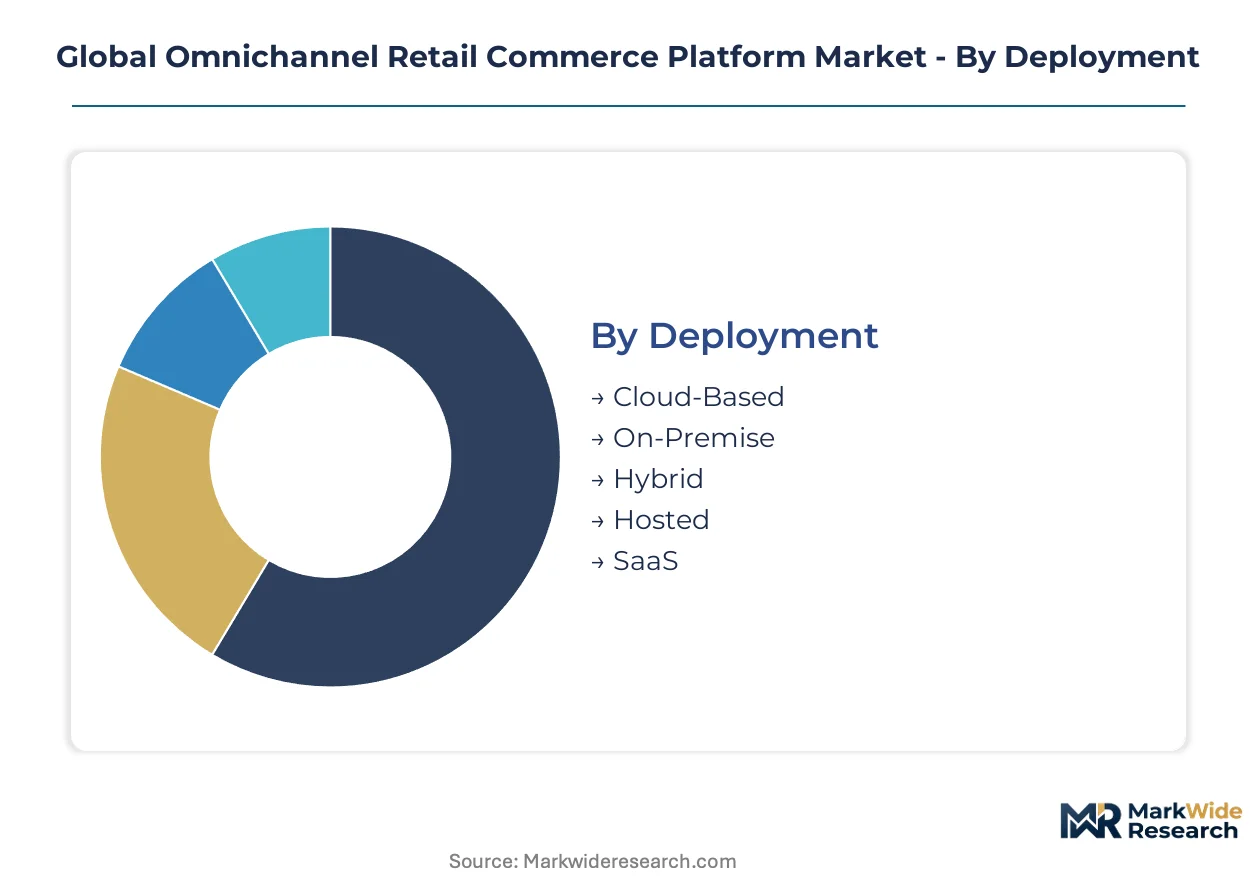
Platform architecture decisions cascade from deployment topology through solution configuration to end-use application. Each segmentation layer imposes distinct technical constraints and margin structures that shape vendor positioning and procurement patterns.
Deployment:
Cloud infrastructure concentration among hyper-scale providers in the United States is redrawing vendor economics and data sovereignty risk profiles across all deployment modes.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute provisioning dominate new procurement among mid-market retailers in Germany and Japan. API-first delivery enables rapid feature deployment without on-site hardware investment. Demand concentrates among specialty stores seeking to avoid capital expenditure while maintaining real-time inventory synchronization.
- SaaS:Subscription-native delivery with pre-integrated modules for order management and customer data platforms accelerates time-to-value for direct-to-consumer brands. California and New York merchants favor outcome-based pricing tied to transaction volume rather than fixed fees.
- Hybrid:Split architectures maintaining sensitive customer data on-premise while leveraging cloud elasticity for compute-intensive analytics workloads. German retailers deploy this mode to satisfy GDPR data localization requirements without sacrificing personalization capabilities.
- On-Premise:Dedicated hardware installations in retail data centers persist among large-format department chains with substantial legacy integration requirements.
- Hosted:Single-tenant managed services where vendors operate dedicated infrastructure on behalf of individual merchants, common among Japanese retailers with METI transparency compliance obligations.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
Solution Type:
Margin capture varies sharply across functional modules, with order orchestration commanding premium pricing due to direct revenue impact.
- Order Management:Distributed fulfillment logic coordinating ship-from-store, buy-online-pickup-in-store, and curbside workflows through unified inventory visibility. Specialty retailers in Germany repurpose physical locations as fulfillment nodes, driving demand for sophisticated allocation algorithms.
- Analytics & Reporting:Predictive demand forecasting engines integrating weather data and social sentiment analysis for anticipatory inventory positioning. California merchants lead adoption of customer lifetime value modeling capabilities.
- E-Commerce Integration:Headless storefront architectures decoupling presentation layers from transaction processing systems.
- Inventory Management:Real-time stock synchronization across warehouse, store, and in-transit positions through event-streaming infrastructure.
- Customer Relationship Management:Unified customer identity resolution spanning online browsing history and in-store purchase patterns.
- Payment Processing:Tokenized transaction handling with multi-currency support and regional payment method integration.
Order Management commands the highest functional premiums; Analytics & Reporting is gaining share fastest.
Use Case:
Merchant technology roadmaps prioritize use cases with measurable conversion impact over experiential enhancements.
- Click & Collect:Curbside fulfillment workflows and automated locker networks expanding transaction volume for grocery and big-box formats. Japanese convenience outlets deploy automated pickup infrastructure to reduce labor costs.
- Personalized Marketing:Algorithmic recommendation engines and dynamic pricing systems requiring EU AI Act compliance for transparency and auditability. German retailers upgrade from legacy siloed systems to unified platforms to satisfy algorithmic accountability mandates.
- Unified Customer Experience:Consistent branding and service levels across mobile, web, and physical touchpoints.
- Mobile Shopping:Progressive web applications and native applications optimized for conversion on smaller screens.
- Social Commerce:Native checkout integration within social media platforms and influencer-driven purchase flows.
- Loyalty Programs:Points-based and tiered membership systems with cross-channel earning and redemption.
Click & Collect dominates current implementation pipelines; Personalized Marketing is climbing the fastest.
Customer Segment:
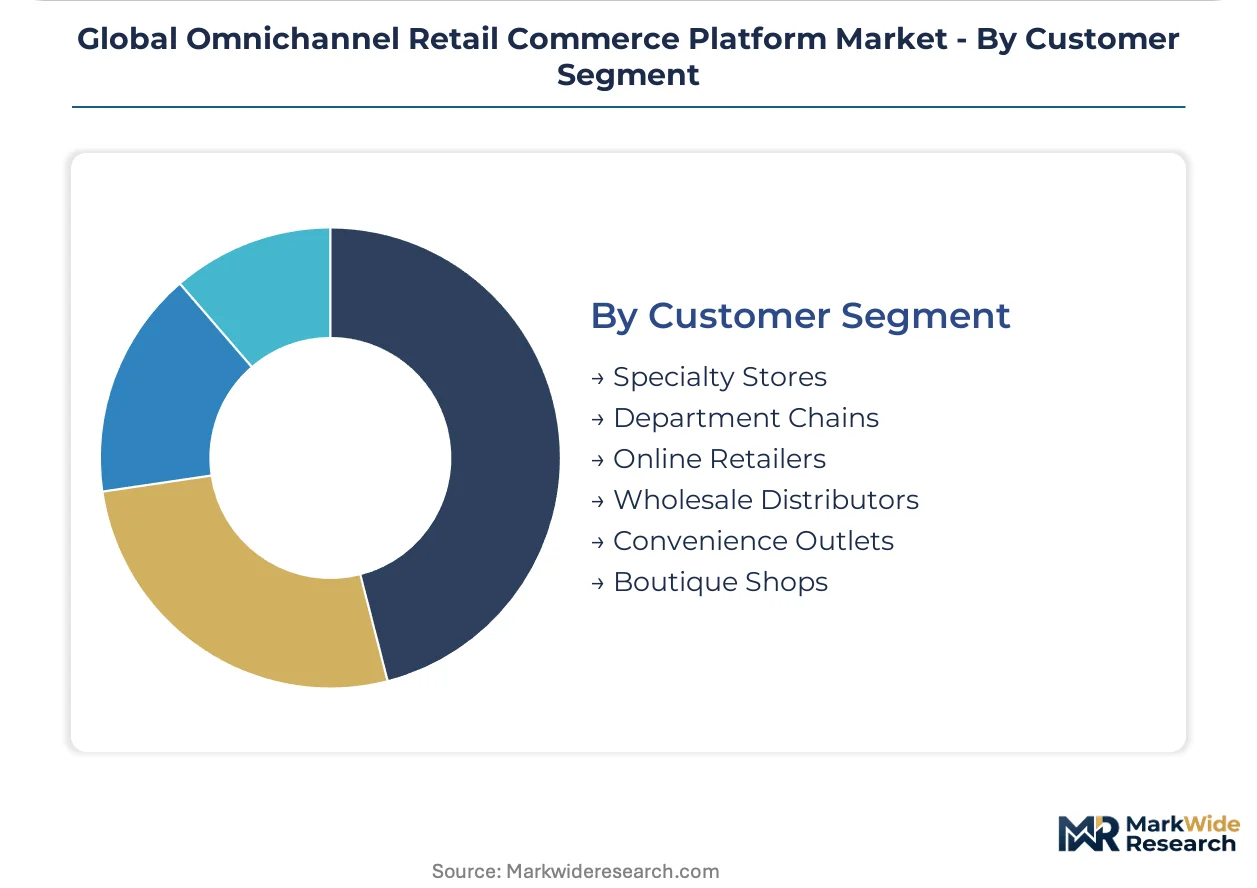
Procurement sophistication and integration complexity diverge sharply between format types, with department chains demanding extensive customization.
- Department Chains:Large-format retailers with heterogeneous brand portfolios requiring complex multi-entity inventory allocation and inter-store transfer capabilities. Legacy mainframe systems from the 1990s force expensive middleware layers or complete replacement.
- Specialty Stores:Focused-category retailers prioritizing deep product expertise and curated assortment over breadth. German and Japanese specialty retailers accelerate adoption of unified commerce systems to enable ship-from-store fulfillment.
- Online Retailers:Digital-native merchants with minimal physical infrastructure requiring robust returns management and cross-border logistics integration.
- Wholesale Distributors:B2B-focused operations with complex pricing tiers, volume breaks, and account-specific contract terms.
- Convenience Outlets:High-velocity, limited-assortment operators emphasizing speed of transaction and localized inventory optimization.
- Boutique Shops:Small-scale independent retailers with limited technical resources requiring simplified deployment and vernacular language support, particularly in India's fragmented kirana store sector.
Department Chains account for the largest contract values; Specialty Stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors platform innovation density, hosting multiple vendors architecting headless commerce systems for North American retailers. Demand concentrates in three metropolitan corridors where legacy retail infrastructure intersects with cloud-native modernization imperatives.
United States
Department chains in Chicago and New York Metro accelerate replacement of 1990s mainframe inventory systems with API-first cloud architectures. The California Consumer Privacy Act mandates consent management modules that increase platform deployment complexity. Los Angeles-based direct-to-consumer brands pioneer outcome-based pricing tied to transaction volume.
Germany
Specialty retailers in Munich and Hamburg repurpose physical locations as distributed fulfillment nodes for ship-from-store workflows. The EU AI Act forces algorithmic transparency upgrades for automated pricing engines. Berlin-Brandenburg hosts compliance-focused vendors embedding GDPR data localization controls into hybrid deployment architectures.
Japan
Convenience outlets in Tokyo deploy automated locker networks and curbside infrastructure to reduce labor costs. METI guidelines on digital platform transparency add technical requirements for Asia-Pacific deployments. Osaka-based department chains demand sophisticated multi-entity inventory allocation across heterogeneous brand portfolios.
India
Fragmented kirana stores in Maharashtra and Gujarat present white-space demand for lightweight mobile-first solutions with vernacular language support. The country's central bank guidelines on digital payments shape platform integration requirements. Bangalore technology clusters incubate API-first vendors targeting mid-market merchant modernization.
United Kingdom
London-based retailers prioritize unified customer identity resolution spanning online browsing and in-store purchase patterns. The UK Information Commissioner's Office enforces GDPR-aligned data handling standards post-Brexit. Manchester logistics corridors test predictive demand forecasting integrating weather data with social sentiment analysis.
Global Omnichannel Retail Commerce Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment complexity and compliance integration depth. The vendor base stratifies between enterprise CRM heritage platforms and merchant-centric SaaS tooling specialists. Three archetypes dominate: cloud-native API-first architects, legacy system modernizers with middleware expertise, and composable commerce orchestrators stitching best-of-breed microservices. M&A activity concentrates on event-streaming talent acquisition and regional compliance capability expansion.
Within the enterprise CRM heritage tier, Salesforce occupies a position exemplifying large-format retailer anchoring through unified data layer deployments. Shopify represents the merchant-centric SaaS archetype with simplified cross-channel inventory synchronization. Adobe sits within the experience-cloud convergence segment, bridging creative tooling with commerce infrastructure. These three vendors illustrate divergent strategic bets on buyer sophistication and implementation timeline preferences.
| Leading Market Players |
|---|
| Insider One |
| NewStore |
| Salesforce |
| Fluent Commerce |
| Omnisend |
| Adobe |
| Klaviyo |
| ActiveCampaign |
| Shopify |
| Others |
Supply & Pricing Matrix
API-first architecture premiums separate enterprise-grade order orchestration from lightweight SaaS entry tiers, with German retailers paying hybrid-deployment surcharges for GDPR data localization while California direct-to-consumer brands negotiate outcome-based contracts tied to transaction throughput. This bifurcation concentrates margin capture among vendors with real-time inventory synchronization capabilities and pushes commodity-priced entrants toward India's kirana modernization segment.
Pricing Analysis
Outcome-based contracts anchored to transaction volume and conversion uplift dominate procurement among California and New York direct-to-consumer brands, displacing fixed SaaS subscriptions. Price differentiation rests on compliance integration depth—EU AI Act auditability and GDPR localization controls command substantial premiums—while cloud concentration risk among United States hyper-scale providers intensifies cost compression in the mid-market SaaS tier. Department chains with 1990s mainframe legacy exhibit lowest price sensitivity due to replacement urgency; India's fragmented kirana sector remains most price-constrained.
Supply Chain Analysis
Direct-to-retailer cloud provisioning channels handle hyperscale demand from United States department chains, while value-added reseller networks serve German and Japanese mid-market specialty retailers with compliance-heavy deployments. Infrastructure supply concentrates in United States hyper-scale regions, with compute provisioning drawing from Virginia, Oregon, and Frankfurt data center clusters. Open-source event-streaming components and proprietary machine learning inference chips constitute critical input dependencies. Single-source vulnerability around United States cloud concentration creates tariff-exposure risk for European retailers facing data sovereignty mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first microservices architectures are displacing monolithic legacy suites, compressing implementation timelines from multi-year mainframe migrations to modular cloud deployments. This transition phase rewards vendors with event-streaming expertise and multi-jurisdiction compliance integration.
For Market Incumbents: Lock in enterprise relationships through embedded compliance modules addressing EU AI Act algorithmic transparency and GDPR localization requirements. Prioritize acquisition of Kafka and real-time data engineering talent to defend against cloud-native challengers. Extend hybrid deployment capabilities to capture German retailer demand for on-premise customer data residency.
For New Entrants and Emerging Players: Mobile-first SaaS distribution routes open white-space access to India's kirana store sector, where vernacular language support and lightweight inventory synchronization remain underserved. Target Maharashtra and Gujarat merchant clusters with API-first architectures that bypass heavy middleware requirements. Lead with outcome-based pricing to align incentives with transaction volume growth.
For Investors and Strategic Acquirers: Re-rating potential sits with event-streaming infrastructure specialists given the scarcity of Kafka talent and sub-second inventory synchronization demands. Long-term viability favors vendors with modular compliance architectures capable of absorbing evolving data sovereignty mandates without core system replacement. Watch for inflection when METI transparency guidelines expand beyond Japan into broader Asia-Pacific enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Integration | EU AI Act auditability features differentiate vendors for German specialty retailers facing algorithmic accountability mandates. |
| Event-Streaming Talent Acquisition | Kafka specialist hiring accelerates real-time inventory synchronization capabilities for ship-from-store fulfillment workflows. |
| Hybrid Deployment Architecture | Split cloud-on-premise configurations satisfy GDPR data localization without sacrificing personalization compute elasticity. |
| Outcome-Based Pricing Transition | Transaction-volume contracts align vendor incentives with California direct-to-consumer brand conversion optimization goals. |
| Vernacular Language Localization | Regional Indian language support unlocks kirana store penetration in Maharashtra and Gujarat technology corridors. |
Research Methodology
Multi-period observation of cloud procurement patterns, compliance spending trajectories, and API adoption rates anchored the trend analysis, supplemented by interviews with platform engineering directors, retail CTOs, GDPR compliance officers, and order management system integrators. Secondary validation drew from SEC 10-K filings of listed commerce vendors, hyperscaler capex disclosures, EU regulatory impact assessments, and METI transparency guideline documentation. Bottom-up merchant deployment tracking and top-down vendor revenue analysis were triangulated to constrain estimate variance.
Segment-weighting applied deployment model, solution type, and customer format dimensions across the analysis window, with order management and analytics modules receiving distinct growth coefficients reflecting functional premium capture. CAGRs were derived from logistic adoption curves fitted to cloud migration timelines and regulatory compliance deadlines. Forecast inputs incorporated EU AI Act implementation phases and Japan METI guideline expansion scenarios.
The model holds under stable data sovereignty enforcement and continued hyper-scale cloud concentration; deviation in tariff escalation or multi-cloud fragmentation would shift infrastructure cost assumptions. Forecasts reflect documented base-case conditions around regulatory timelines and technology substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
India Digital Gift Card Market