
 Global Product Design and Development Market | 2026-2036
Global Product Design and Development Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Design and Development Market Foresight
REACH is broadening the cost-of-entry calculus for firms serving European industrial clients, as substance compliance now extends through entire design traceability chains. Capgemini Engineering leverages its embedded systems heritage to anchor complex aerospace and automotive programs across Toulouse, Detroit, and Bangalore. Tata Consultancy Services sustains competitive intensity through manufacturing-scale digital twin deployments that compress validation cycles for industrial equipment clients. Frog Design differentiates by occupying the intersection of hardware ergonomics and software interface design, a margin pool where brand premiums concentrate.
Product design and development encompasses the systematic translation of user requirements, regulatory constraints, and manufacturing feasibility into validated product specifications through iterative modeling, simulation, and prototyping cycles. Computer-aided design platforms now integrate generative topology optimization and real-time thermal analysis, enabling engineers to evaluate hundreds of geometric permutations before physical prototyping. Simulation software captures the fastest expansion trajectory as multiphysics modeling replaces sequential single-domain testing in aerospace engineering and electronics manufacturing applications. Cloud-based deployment architectures are displacing on-premise installations among mid-market consumer goods and fashion brands seeking elastic compute capacity without capital intensity.
The FDA's digital health pre-certification framework and the EU AI Act's conformity assessment requirements are reshaping documentation standards for connected medical devices and autonomous systems, forcing design consultancies to embed regulatory validation into front-end concept phases. ECHA substance restrictions under REACH cascade into material selection protocols for packaging solutions and industrial equipment, where suppliers must certify full chemical composition transparency. ISO 13485 medical device quality management and IEC 62304 software lifecycle standards further segment vendor eligibility, creating accreditation moats that favor established engineering services networks. Stakeholders must monitor how convergence between product design and cybersecurity certification will restructure service bundling and client retention economics.
Market Dynamics
Embedded software architectures and electrification mandates are compressing traditional vehicle development timelines while forcing design consultancies to integrate hardware-software co-development capabilities.
Growth Catalysts
- EU AI Act conformity assessments:Mandatory algorithmic documentation for autonomous systems creates recurring revenue streams for engineering services firms with regulatory expertise.
- Electrification engineering:Automotive OEMs in Germany and China require thermal management and battery packaging design services that legacy mechanical studios cannot deliver.
- Generative topology optimization:Aerospace manufacturers deploy AI-driven lattice structures to reduce component weight while maintaining structural integrity under FAA certification pathways.
Market Restraints
- Specialized talent scarcity:Embedded systems engineers with IEC 62304 software lifecycle expertise command premium compensation that inflates project delivery costs.
- REACH substance traceability:Full chemical composition documentation through tier-three suppliers imposes compliance overhead that disqualifies smaller design studios from European industrial contracts.
- On-premise software lock-in:Legacy CAD installations at major automotive groups resist cloud migration, constraining elasticity for mid-market engineering consultancies.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives attract industrial equipment makers seeking localized design validation and digital twin deployment.
- Digital health pre-certification:FDA's streamlined pathway for connected medical devices enables front-loaded regulatory consulting engagements before physical prototyping begins.
- Multiphysics simulation convergence:Coupled thermal-structural-electromagnetic modeling replaces sequential testing, opening margin pools in electronics miniaturization applications.
Industry Challenges
- Cybersecurity certification integration:ISO 27001 and IEC 62443 requirements now overlap with functional safety standards, forcing consultancies to retrain quality assurance teams.
- Legacy PLM system interoperability:Decades-old product lifecycle management databases resist API integration with modern cloud-native simulation platforms.
- Cross-border IP fragmentation:Divergent patent recognition between US, European, and Chinese jurisdictions complicates co-development agreements for multinational programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Design and Development Market |
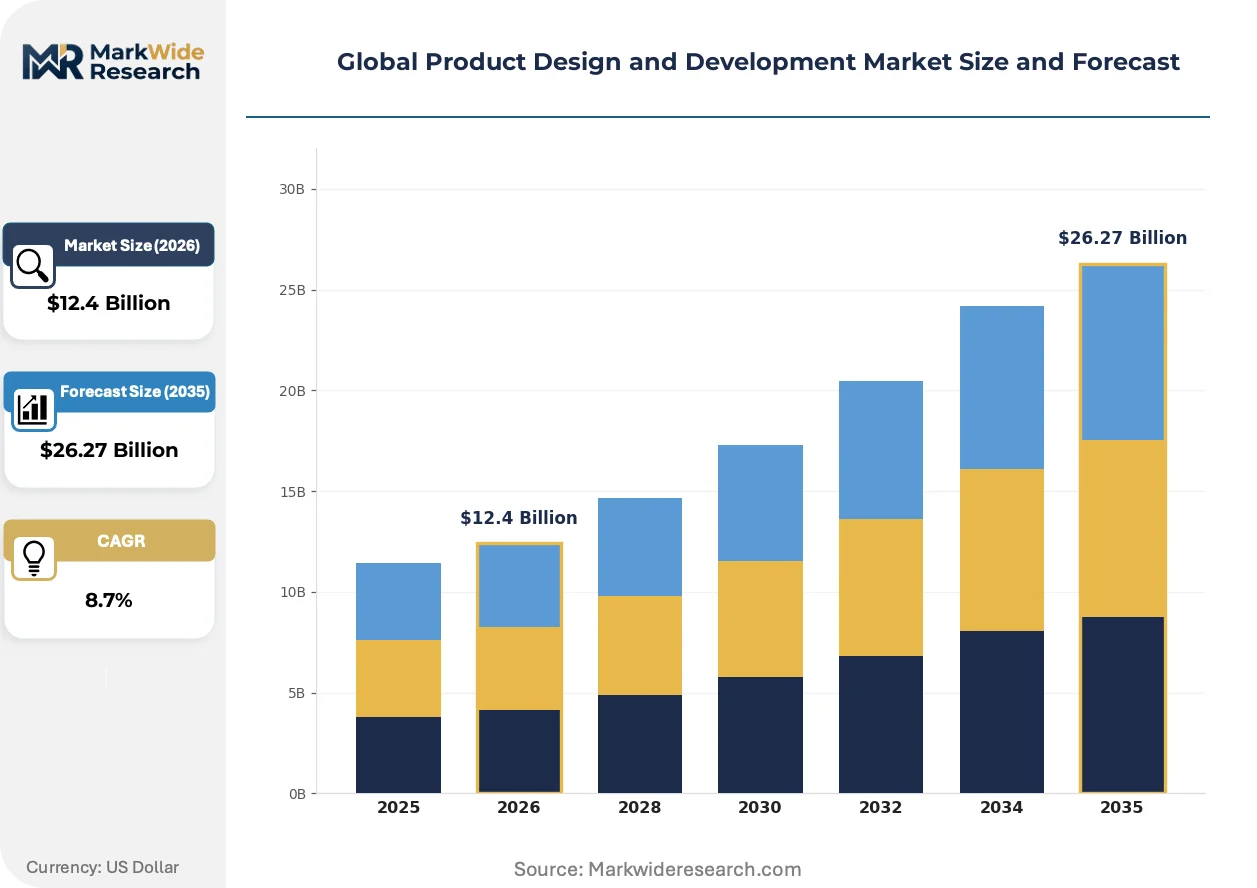
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computer-Aided Design, Simulation Software, Prototyping Tools, Innovation Management Platforms, Project Management Solutions Application: Consumer Goods, Aerospace Engineering, Industrial Equipment, Electronics Manufacturing, Packaging Solutions End User Industry: Automotive OEMs, Telecommunications Providers, Energy Firms, Defense Contractors, Fashion Brands Deployment: Cloud-Based, On-Premise, Hybrid, Software as a Service, Edge Computing |
| Companies Covered | Capgemini Engineering, Tata Consultancy Services, Accenture, HCLTech, L&T Technology Services, IDEO, Frog Design, Pentagram, StudioRed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Design and Development Market Shifts & Advancements
Real-time simulation and generative design tools are collapsing the iteration cycles between concept validation and manufacturing readiness across industrial verticals.
Generative design algorithms are absorbing constraint parameters from material properties, manufacturing processes, and regulatory load cases to autonomously propose geometric solutions. Automotive seating suppliers in Detroit and Stuttgart deploy these tools to evaluate hundreds of structural permutations before committing to physical tooling. The technology is absorbing weeks from traditional design-review schedules while elevating the analytical intensity required of engineering staff.
REACH substance restrictions under ECHA now cascade into material selection protocols for industrial equipment and packaging solutions. Full chemical composition transparency through tier-three suppliers has become a contractual prerequisite for European industrial procurement. Medical device manufacturers face the steepest documentation burden as MDR technical files must demonstrate biocompatibility traceability from raw material to finished sterile barrier.
Outcome-based service contracts are displacing time-and-materials billing for complex product development programs. Industrial equipment buyers in Germany and Japan now compensate engineering partners against milestone-based deliverables rather than hourly rates. This compression of commercial risk onto consultancies favors established networks with capital reserves to absorb iteration cycles without interim payment.
Global Product Design and Development Market Segmentation
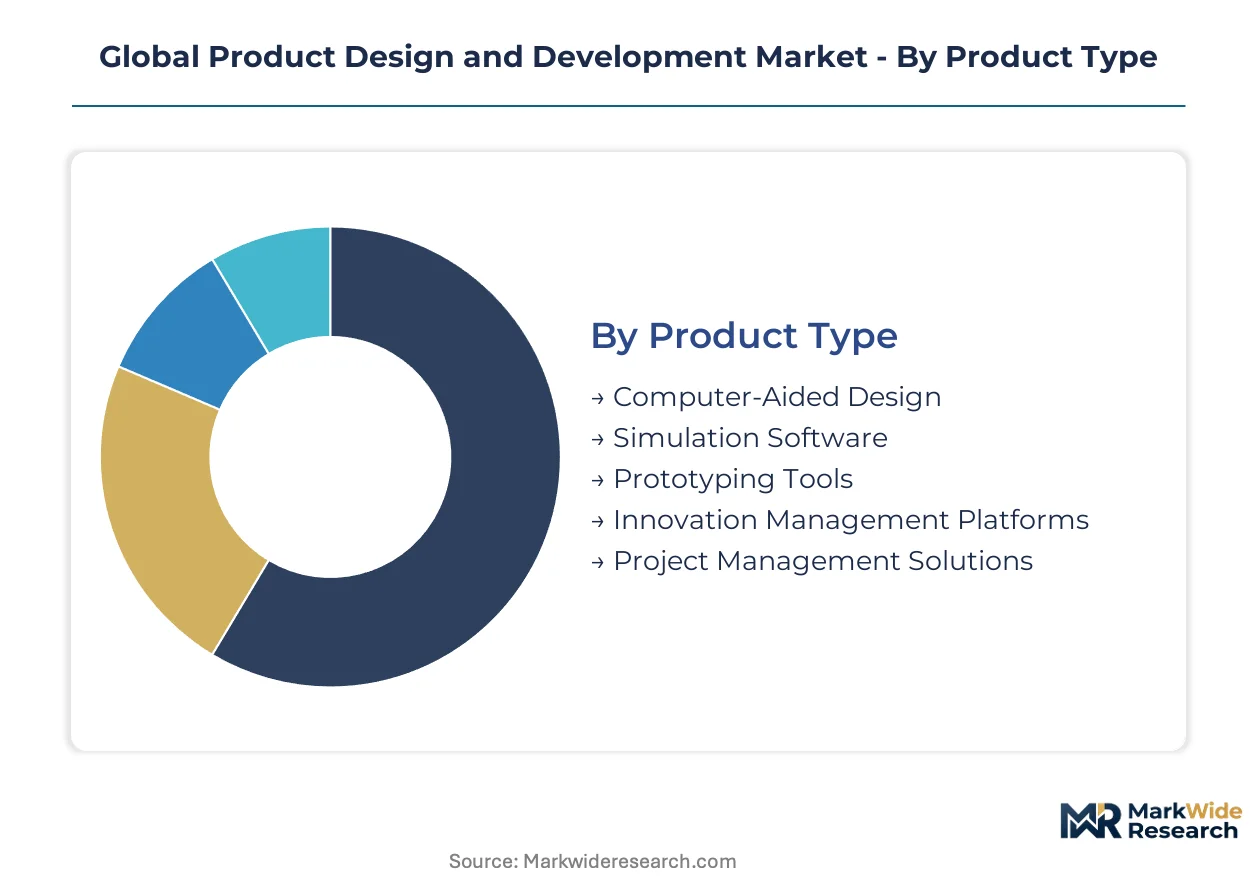
Segmentation in product design and development services reveals how procurement priorities diverge across technology maturity, regulatory exposure, and capital intensity. Buyers in aerospace and medical device verticals prioritize simulation fidelity and certification documentation, while consumer goods purchasers optimize for speed-to-market and elastic compute costs.
Product Type:
Buyers in this category separate by analytical intensity requirements and integration depth with legacy PLM architectures.
- Computer-Aided Design:Core geometric modeling platforms with parametric constraint engines and direct editing capabilities. Automotive OEMs in Germany and Japan anchor demand here, driven by electrification programs requiring rapid packaging iteration for battery modules and thermal management systems.
- Simulation Software:Multiphysics environments coupling thermal, structural, and electromagnetic solvers in unified workflows. Aerospace engineering applications in Toulouse and Seattle concentrate investment as FAA and EASA certification pathways demand predictive validation before physical prototyping.
- Prototyping Tools:Additive manufacturing preparation and CNC path generation systems with build-orientation optimization.
- Innovation Management Platforms:Ideation workflow engines with IP capture and stage-gate governance for distributed R&D teams.
- Project Management Solutions:Resource allocation and milestone tracking systems with Gantt visualization and critical path analysis.
Volume sits with Computer-Aided Design; growth tilts toward Simulation Software.
Application:
Application segmentation tracks how regulatory load and material complexity reshape service bundling and margin structures.
- Consumer Goods:Packaging structural design and shelf-ready aesthetics with rapid turnaround requirements. Fashion brands in Milan and New York drive elastic demand for cloud-based rendering farms that collapse seasonal concept-to-sample cycles without capital deployment.
- Aerospace Engineering:Airframe structural analysis and propulsion system integration under stringent FAA and EASA certification regimes. Thermal-structural coupled modeling absorbs the largest engineering services budgets as OEMs pursue weight reduction targets.
- Industrial Equipment:Heavy machinery frame optimization and hydraulic system packaging with REACH substance compliance protocols.
- Electronics Manufacturing:PCB layout and electromagnetic interference mitigation for miniaturized consumer devices.
- Packaging Solutions:Sustainable material substitution and barrier property modeling for food and pharmaceutical applications.
Revenue concentrates in Aerospace Engineering; Electronics Manufacturing climbs fastest on semiconductor packaging complexity.
End User Industry:
End user segmentation distinguishes between buyers with captive engineering capacity and those dependent on external services.
- Automotive OEMs:Full-vehicle development programs spanning exterior surfacing, interior ergonomics, and embedded software architecture. Battery electric vehicle platforms in Stuttgart, Detroit, and Shanghai compress traditional development timelines while demanding hardware-software co-development capabilities.
- Defense Contractors:Secure facility requirements and ITAR compliance protocols with long-cycle platform development. Cybersecurity certification integration with ISO 27001 and IEC 62443 standards elevates vendor qualification barriers.
- Telecommunications Providers:Network equipment thermal design and antenna integration for 5G infrastructure deployment.
- Energy Firms:Turbine blade aerodynamics and subsea equipment pressure vessel analysis.
- Fashion Brands:Footwear biomechanics and apparel pattern digitization with sustainability traceability requirements.
Procurement scale favors Automotive OEMs; Defense Contractors expand most quickly on classified program digitization mandates.
Deployment:
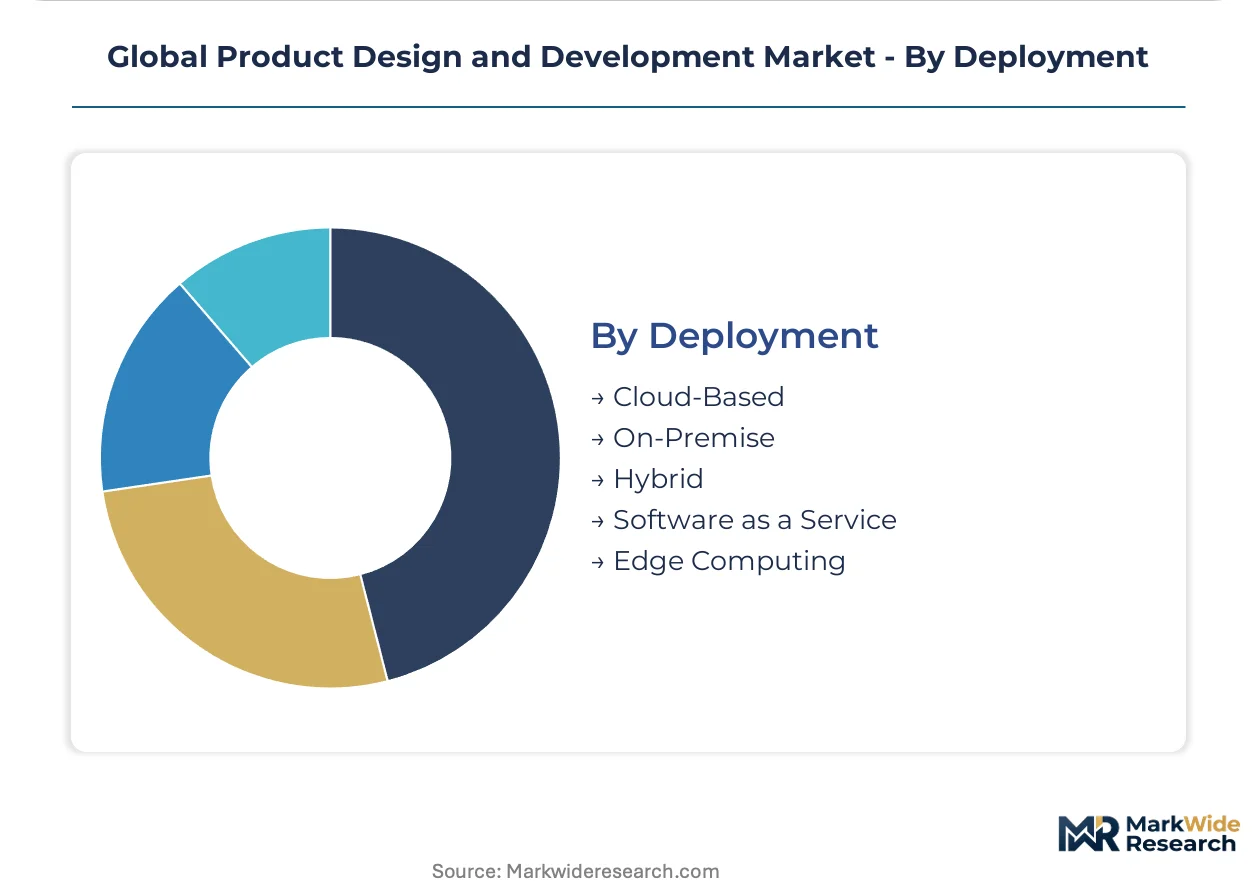
Deployment choices reflect data sovereignty requirements, latency sensitivity, and capital constraint profiles across buyer segments.
- Cloud-Based:Elastic compute provisioning with API-native simulation orchestration and consumption-based pricing. Mid-market consumer goods and fashion brands in Germany and the United States gravitate here to avoid on-premise hardware depreciation.
- Hybrid:Sensitive model encryption on-premise with burst compute offload to cloud infrastructure. Medical device manufacturers favor this architecture for FDA pre-submission data integrity requirements.
- On-Premise:Air-gapped installations with perpetual licensing for classified or export-controlled programs.
- Software as a Service:Browser-accessible design review and lightweight markup tools with subscription economics.
- Edge Computing:Localized simulation nodes for real-time generative design feedback in connected manufacturing environments.
Installed base remains On-Premise; Hybrid deployments gain share fastest on cross-border IP protection concerns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart, Detroit, and Shanghai concentrate automotive electrification engineering, while regulatory divergence across FDA, ECHA, and NMPA jurisdictions fragments compliance architectures for multinational product programs.
Germany
Automotive OEMs in Stuttgart and Munich drive battery packaging and thermal management design services as electrification mandates compress development cycles. The EU AI Act's conformity assessment requirements force consultancies to embed algorithmic documentation into front-end concept phases. Engineering services clusters in Baden-Württemberg anchor cross-border aerospace programs under EASA certification pathways.
United States
FDA's digital health pre-certification framework creates front-loaded regulatory consulting demand for connected medical device developers in Boston and Minneapolis. The FAA maintains stringent predictive validation requirements for aerospace engineering applications in Seattle and Wichita. Defense contractors in secure facilities elevate vendor qualification barriers through ITAR compliance and cybersecurity certification integration.
China
Dual carbon goals and NEV subsidies accelerate hardware-software co-development capabilities for battery electric vehicle platforms in Shanghai and Shenzhen. MIIT standards for embedded systems reshape documentation protocols for autonomous system architectures. Engineering services networks in the Yangtze River Delta serve as innovation anchors for cross-border industrial equipment programs.
India
PLI scheme incentives attract industrial equipment makers seeking localized design validation and digital twin deployment in Bangalore and Pune. BIS certification requirements for electronics manufacturing elevate analytical intensity for PCB layout and electromagnetic interference mitigation services. Tata Consultancy Services and L&T Technology Services anchor manufacturing-scale simulation deployments from their engineering hubs.
Global Product Design and Development Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. Global IT services networks with embedded systems heritage anchor complex aerospace and automotive programs, while boutique design studios capture margin pools at the hardware-software interface. Three archetypes dominate: diversified engineering consultancies, manufacturing-scale digital twin deployers, and ergonomics-software intersection specialists. Competitive moves concentrate on regulatory accreditation expansion and cloud-native simulation platform development.
Within the diversified engineering consultancy tier, Capgemini Engineering exemplifies the embedded systems heritage archetype across Toulouse, Detroit, and Bangalore. Tata Consultancy Services occupies a position among manufacturing-scale digital twin deployers that compress validation cycles. Frog Design anchors the hardware ergonomics and software interface design specialization where brand premiums concentrate.
| Leading Market Players |
|---|
| Capgemini Engineering |
| Tata Consultancy Services |
| Accenture |
| HCLTech |
| L&T Technology Services |
| IDEO |
| Frog Design |
| Pentagram |
| StudioRed |
| Others |
Supply & Pricing Matrix
Embedded systems engineering talent costs cascade from Bangalore and Stuttgart through project-based billing tiers, compressing margins for consultancies without offshore delivery networks while elevating premium pricing for firms with IEC 62304 certification depth.
Pricing Analysis
Short lead-time premiums of 30-40% separate urgent electrification programs from standard-cycle engagements in automotive OEM procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and regulatory documentation depth. Cost compression in mid-market simulation services is intensifying because cloud-native platforms displace perpetual license maintenance. Tier 1 automotive groups show least price sensitivity for FDA pre-certification consulting; fashion brands and consumer goods manufacturers anchor the economy tier with elastic SaaS consumption.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs now extend to engineering services networks, requiring qualified backup capacity in at least two regulatory jurisdictions. Talent supply concentrates in India, Germany, and the United States, with embedded firmware expertise drawing from aerospace and telecommunications crossover pools. Single-source vulnerability sits with IEC 62304-certified software lifecycle specialists, where training pipelines lag demand acceleration. Distribution runs through direct enterprise contracts with milestone-based deliverables, displacing time-and-materials intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory accreditation capacity props pricing power across compliance-heavy verticals, with IEC 62304 and EU AI Act documentation expertise commanding sustained premiums through the projection horizon.
For Market Incumbents: Acquire regulatory accreditation assets in FDA digital health and EU AI Act conformity assessment pathways. Consolidate position by embedding cybersecurity certification teams to capture ISO 27001 and IEC 62443 bundling demand from defense contractors. Add captive capacity in Bangalore or Pune to defend margin position against PLI-scheme entrants.
For New Entrants and Emerging Players: The 40% price-point gap between premium-tier regulatory consultancies and economy-tier SaaS tools opens white-space in hybrid deployment architecture services. Target mid-market medical device manufacturers in Minneapolis and Boston seeking FDA pre-submission support without full-service overhead. Lead with digital twin validation bundles that compress physical prototyping cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor manufacturing-scale digital twin deployers with established automotive OEM relationships in Germany and China. Long-term viability hinges on regulatory accreditation moats deepening through convergence with cybersecurity certification. Watch for inflection when REACH substance traceability mandates expand beyond tier-three to tier-four supplier documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Accreditation Expansion | EU AI Act and FDA digital health pre-certification expertise deepens client retention in medical device and autonomous systems verticals. |
| Cloud-Native Simulation Platform Development | API-native multiphysics environments displace on-premise installations among mid-market consumer goods and fashion brands. |
| Hardware-Software Co-Development Capability Buildout | Battery electric vehicle platforms in Stuttgart and Shanghai compress timelines and demand integrated thermal management design. |
| Geographic Talent Hub Expansion | India PLI scheme incentives attract localized validation services for industrial equipment makers seeking digital twin deployment. |
| Cybersecurity Certification Integration | ISO 27001 and IEC 62443 bundling with functional safety standards elevates vendor qualification barriers for defense contractors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across engineering services procurement leads, embedded systems directors, regulatory affairs managers, and PLM platform architects. Engineering services association membership directories, FDA 510(k) submission databases, ECHA REACH registration dossiers, and EU AI Act implementation guidance provided segmentation baselines. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Data-stream reconciliation across deployment model adoption curves, end-user industry capital expenditure patterns, and regulatory compliance cost surveys shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user industry, and deployment architecture. CAGRs derived from multivariate regression against electrification program timelines, digital health submission volumes, and aerospace certification backlogs.
Underlying measurement precision varies by segment; cloud-based deployment and consumer goods application data carry tighter precision than on-premise defense contractor estimates. Forecasts reflect documented assumptions about regulatory implementation timelines and talent supply elasticity. Deviation in EU AI Act enforcement intensity or REACH substance restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Digital BSS Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Location As a Service Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Data Broker Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Desktop Virtualization in Manufacturing Market