
 Visitor Identification Software Market | 2026-2036
Visitor Identification Software Market Size, Share, and Industry Trends Forecast 2026-2036
Visitor Identification Software Market Analytics
ISO/IEC 27001 certification for information security management is unwinding the competitive landscape, filtering out vendors that cannot demonstrate audited data protection controls. Leadinfo leverages its European base to sustain GDPR-aligned product architectures that appeal to risk-conscious buyers. ZoomInfo anchors its position through proprietary data graph scale, while 6sense differentiates via AI-driven intent orchestration capabilities.
Visitor identification software encompasses systems that deanonymize website traffic and physical premises visitors through IP intelligence, cookie matching, biometric capture, or RFID credentialing to enable personalized engagement and access governance. Cloud-based deployment leads the product type category due to faster implementation cycles and lower capital requirements, while biometric authentication within the technology dimension commands premium pricing from healthcare facilities and high-security commercial offices. Hybrid architectures are gaining traction among educational institutions seeking to bridge legacy on-premise access control with modern visitor management workflows.
The Federal Trade Commission enforces transparency requirements around data collection practices in the United States, while the EU AI Act imposes risk-classification obligations on biometric identification systems deployed in European member states. The California Consumer Privacy Act and emerging state-level statutes in Virginia and Colorado compound compliance complexity for vendors serving multi-jurisdictional accounts. Stakeholders must monitor regulatory divergence between federal and state frameworks when prioritizing product roadmap investments and geographic expansion sequencing.
Market Dynamics
AI-powered intent data integration is compressing sales cycles and forcing vendors to demonstrate measurable pipeline attribution or face churn from B2B marketing teams.
Growth Catalysts
- GDPR enforcement:European data protection authorities are imposing fines that compel enterprises to adopt compliant deanonymization tools, accelerating replacement of legacy tracking systems.
- Biometric authentication:Healthcare facilities in the United States are deploying palm-vein and facial recognition systems to eliminate badge-swapping and tailgating in sterile zones.
- Cloud migration:Mid-market SaaS vendors are abandoning on-premise visitor logs for API-first platforms that integrate with Salesforce and HubSpot within hours.
Market Restraints
- Cookie deprecation:Google's phase-out of third-party cookies in Chrome is degrading match rates for probabilistic identification, forcing reliance on costlier deterministic methods.
- Silicon concentration:Specialized edge AI chips for biometric inference rely on TSMC fabrication in Taiwan, exposing hardware vendors to single-point supply risk.
- Biometric false positives:Facial recognition systems still exhibit elevated error rates for darker skin tones, limiting deployment in diverse metropolitan districts.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting assembly of RFID readers and access control hardware to Gujarat and Tamil Nadu.
- EU AI Act compliance:Risk-classification requirements for biometric systems create consulting and certification revenue streams for vendors with documented audit trails.
- Convergence of physical-digital identity:Merging building access credentials with website visitor profiles enables unified scoring of prospect engagement across channels.
Industry Challenges
- ISO/IEC 27001 certification timelines:Audited information security management systems require 12-18 months to implement, delaying enterprise sales cycles for emerging vendors.
- Legacy access control integration:Educational institutions struggle to bridge 20-year-old on-premise badge systems with modern cloud visitor management workflows.
- Data residency fragmentation:Multi-jurisdictional accounts demand region-locked data storage, complicating architecture for vendors with centralized cloud infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visitor Identification Software Market |
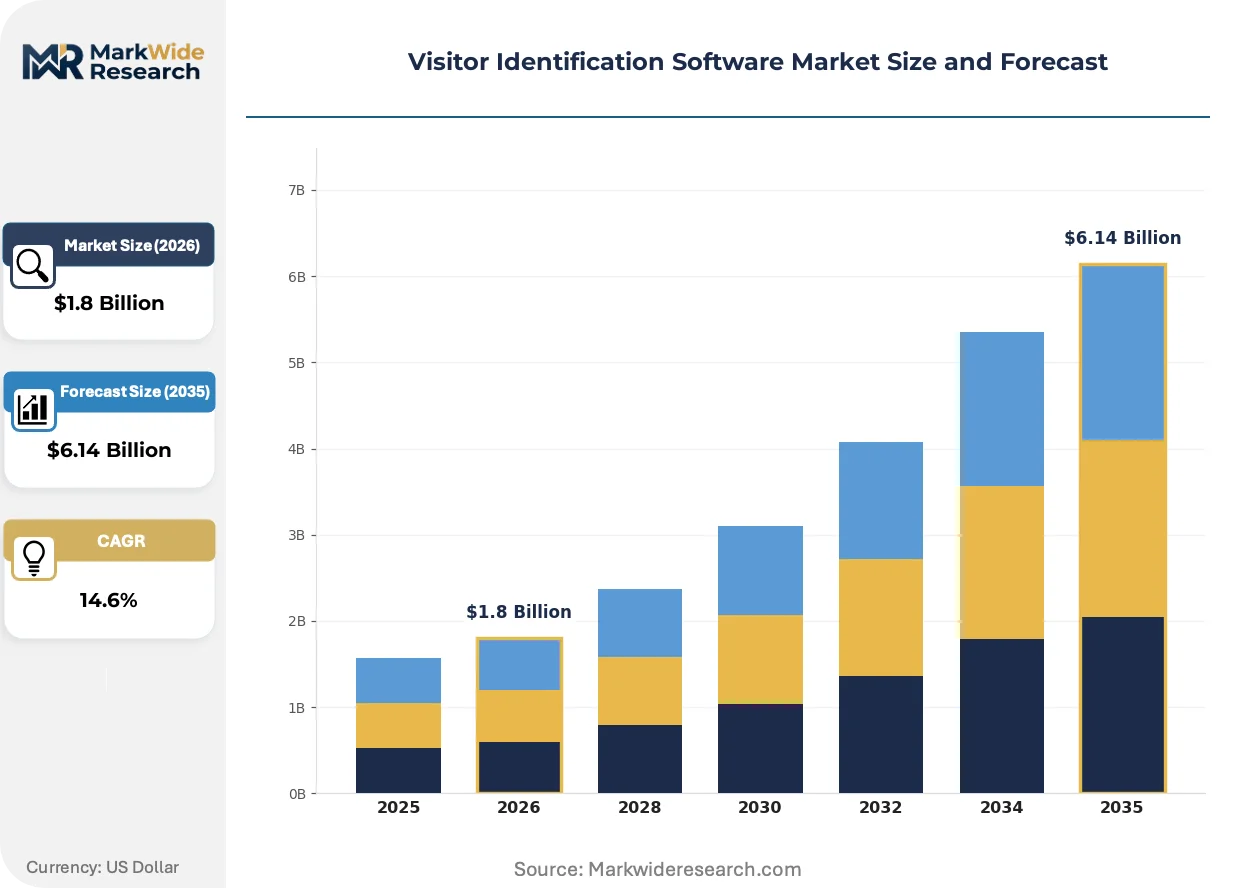
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Solutions End User: Retail Stores, Commercial Offices, Educational Institutions, Healthcare Facilities Technology: Facial Recognition, RFID, QR Code Scanning, Biometric Authentication Application: Security Monitoring, Access Control, Visitor Management, Event Registration |
| Companies Covered | Leadinfo, Leadpipe, Dealfront, Albacross, RB2B, 6sense, ZoomInfo, Lead Forensics, HubSpot Breeze Intelligence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visitor Identification Software Market Evolving Landscape
Edge AI inference is collapsing latency requirements and enabling real-time visitor scoring without round-trips to centralized servers, reshaping competitive requirements for responsiveness.
On-device facial recognition is miniaturizing through neural network pruning and dedicated NPU silicon. High-security commercial offices in London and Singapore are deploying palm-sized edge units that process biometric templates locally. This architecture is miniaturizing hardware footprints while eliminating cloud dependency for sensitive credential verification.
The EU AI Act's risk-classification framework for biometric identification is forcing vendors to document training data provenance and accuracy benchmarks across demographic groups. Systems deployed in French and German public buildings now require conformity assessments from notified bodies. Healthcare campuses across the Netherlands are accelerating procurement of certified solutions ahead of enforcement deadlines.
Enterprise buyers are unbundling implementation services from software licenses, demanding fixed-price deployment guarantees rather than time-and-materials consulting. This pattern is most visible among Fortune 500 manufacturers consolidating vendor relationships under procurement-led standardization programs. Responding vendors are certifying system integrator networks to absorb delivery risk.
Visitor Identification Software Market Segmentation
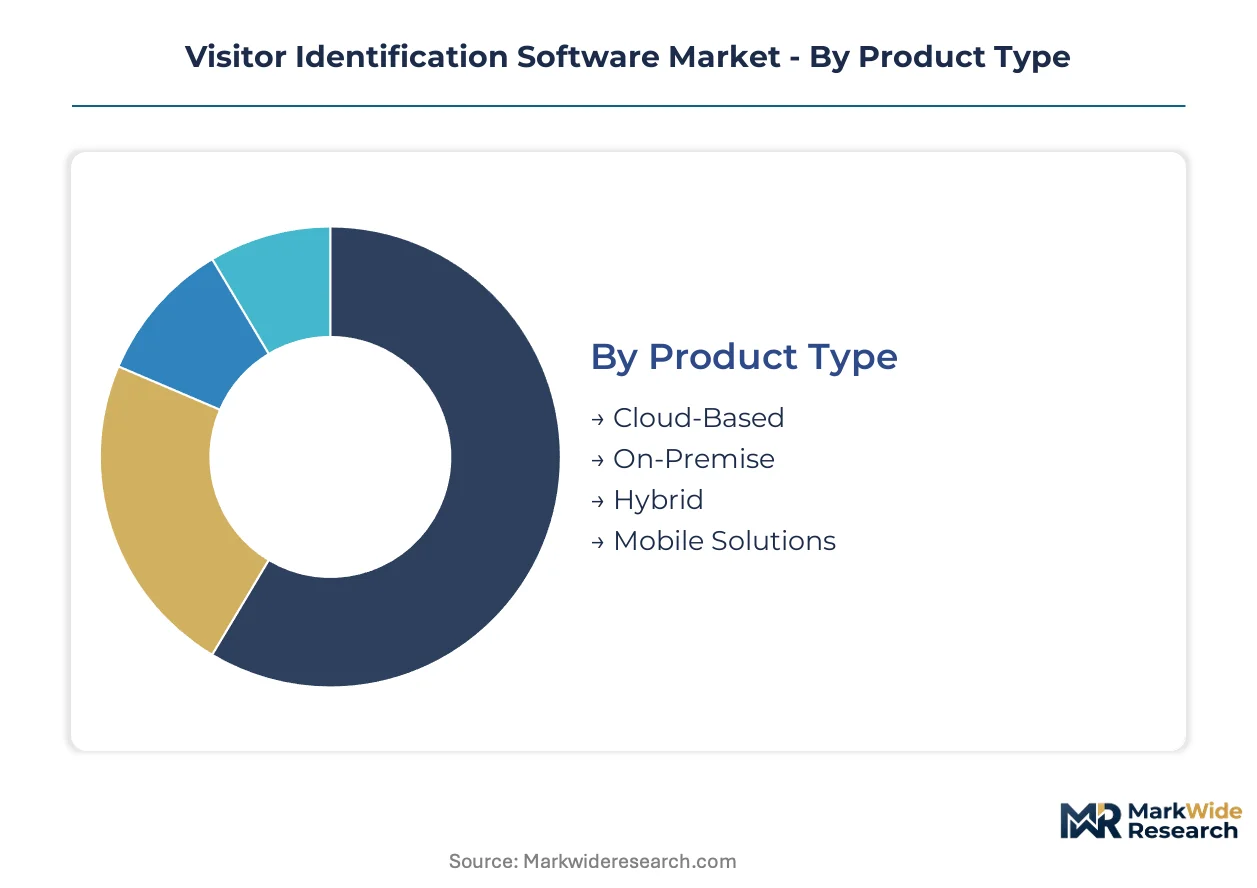
Segmentation in visitor identification software reveals divergent deployment economics across infrastructure types and regulatory exposure. Buyers select architectures based on data residency mandates, integration complexity, and the trade-off between operational control and capital efficiency.
Product Type:
Cloud-based systems dominate North American procurement while hybrid architectures find traction in European markets navigating GDPR data localization requirements.
- Cloud-Based:Multi-tenant SaaS architectures deliver API-first integration with CRM platforms and eliminate server maintenance overhead. Demand concentrates among mid-market B2B SaaS vendors in the United States seeking rapid deployment without capital expenditure.
- On-Premise:Dedicated hardware and software stacks installed within client data centers provide complete data sovereignty and offline operation. Financial services firms in Germany and Switzerland favor this model to satisfy national banking regulators' custody requirements.
- Hybrid:Split architectures process sensitive biometric templates locally while syncing anonymized analytics to cloud dashboards. Educational institutions across the United Kingdom deploy hybrid systems to bridge legacy badge infrastructure with modern visitor workflows.
- Mobile Solutions:Smartphone-based credentialing and QR code validation eliminate dedicated hardware for temporary event deployments. Stadium operators in Australia and convention centers in Singapore drive adoption for seasonal capacity surges.
Cloud-based deployment holds the largest share; momentum sits with hybrid architectures as data residency fragmentation intensifies.
End User:
Cost tier differentiation separates enterprise-grade biometric installations from budget-conscious retail implementations.
- Retail Stores:Foot traffic analytics and repeat customer recognition drive deployment in flagship locations. Luxury brands in Paris and Milan deploy facial recognition to personalize in-store experiences while managing opt-in consent workflows.
- Commercial Offices:Access control integration and visitor pre-registration dominate procurement specifications. High-security towers in London and New York require palm-vein authentication for sterile zone entry.
- Educational Institutions:Campus safety mandates and parent notification systems shape purchasing criteria. Universities in California and Texas balance open campus policies with emergency lockdown capabilities.
- Healthcare Facilities:Infection control and patient privacy regulations elevate biometric requirements. Dutch hospital networks accelerate certified solution procurement ahead of EU AI Act enforcement deadlines.
Commercial offices command premium pricing; healthcare facilities are expanding most quickly as regulatory deadlines approach.
Technology:
Technology maturity curves separate proven RFID deployments from emerging biometric modalities facing accuracy and bias scrutiny.
- Facial Recognition:Camera-based identification systems process visitors against watchlists and employee databases. Deployment in diverse metropolitan districts faces constraints from elevated false positive rates for darker skin tones.
- RFID:Credential-based access using proximity cards and active tags remains the volume leader. Manufacturing campuses in India's Gujarat industrial corridor standardize on UHF RFID for truck and contractor tracking.
- QR Code Scanning:Smartphone-generated credentials enable touchless entry for temporary visitors and event attendees. Exhibition centers in Singapore and Dubai deploy QR systems for multi-day conference management.
- Biometric Authentication:Fingerprint, iris, and palm-vein templates provide non-transferable identity verification. Healthcare sterile zones in the United States eliminate badge-swapping through palm-vein deployment.
RFID maintains volume leadership; biometric authentication is gaining share fastest as security requirements harden.
Application:
Application scope determines integration depth with adjacent physical security and marketing automation stacks.
- Security Monitoring:Real-time video analytics flag anomalies and unauthorized presence. Critical infrastructure sites in Saudi Arabia and the UAE deploy AI-enhanced monitoring for perimeter breach detection.
- Access Control:Credential verification gates entry based on time-bound permissions. Corporate headquarters in Switzerland integrate access systems with HR databases for automated onboarding.
- Visitor Management:Pre-registration, check-in workflows, and host notification streamline reception operations. Professional services firms in London and New York prioritize visitor experience metrics in vendor selection.
- Event Registration:High-throughput credentialing for conferences, concerts, and sporting venues. Expo centers in Shanghai and Tokyo deploy facial recognition for frictionless entry at scale.
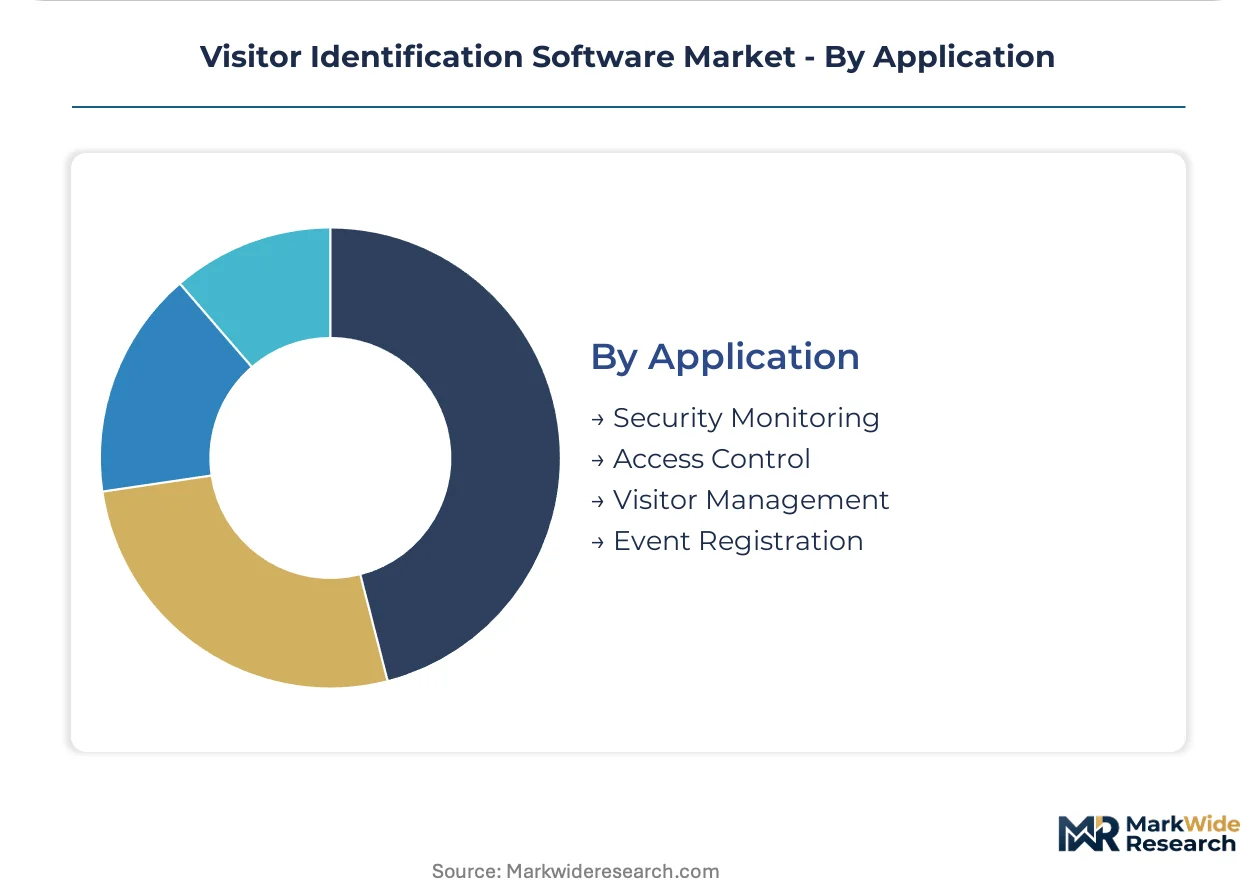
Access control commands the largest installed base; visitor management shows the steepest expansion trajectory as workplace hospitality standards elevate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun County data center corridor underwrites the United States' dominance in cloud-hosted visitor identification infrastructure, while submarine cable landings at Marseille and Singapore anchor European and Asian-Pacific data gravity for compliance-bound deployments.
United States
Enterprise procurement of AI-powered intent data concentrates among B2B SaaS vendors in San Francisco and Boston. The Federal Trade Commission enforces transparency mandates around data collection practices. Healthcare facilities in Texas deploy palm-vein biometric systems for sterile zone access control.
Germany
Financial services firms in Frankfurt demand on-premise architectures to satisfy BaFin custody requirements for visitor data. The EU AI Act imposes risk-classification obligations on biometric identification systems. Industrial manufacturers in Baden-Württemberg integrate RFID tracking for contractor management at Stuttgart-area campuses.
United Kingdom
Professional services firms in London prioritize visitor experience metrics for reception automation. The Information Commissioner's Office enforces GDPR-aligned consent workflows for facial recognition deployments. Educational institutions across the Midlands deploy hybrid systems bridging legacy badge infrastructure with cloud analytics.
India
Electronics manufacturing incentives under the PLI scheme attract RFID reader assembly to Gujarat and Tamil Nadu. The Bureau of Indian Standards issues certification requirements for biometric device accuracy. IT parks in Bangalore and Hyderabad drive mid-market adoption of API-first visitor management platforms.
Netherlands
Hospital networks accelerate procurement of EU AI Act-certified solutions ahead of enforcement deadlines. The Dutch Data Protection Authority mandates documented training data provenance for biometric systems. Rotterdam port logistics operators deploy UHF RFID for truck driver identification at container terminals.
Visitor Identification Software Market Competitive Landscape
Listed leaders compete with private specialists across data graph scale and compliance architecture dimensions. The vendor landscape stratifies between proprietary data aggregators, AI-native intent platforms, and GDPR-aligned European specialists. Three archetypes dominate: data graph scale players, AI orchestration specialists, and compliance-first regional vendors. Competitive moves concentrate on M&A for data asset accumulation and strategic partnerships with system integrators to absorb implementation risk.
Within the compliance-first tier, Leadinfo and Dealfront exemplify European specialists leveraging GDPR-aligned product architectures to serve risk-conscious buyers. At the scale-driven end, ZoomInfo occupies a position representing data graph breadth advantages. Among AI-native platforms, 6sense sits within the intent orchestration archetype, anchoring the predictive analytics segment. These three companies collectively represent the strategic positioning vectors—regulatory alignment, data scale, and AI differentiation—that define competitive boundaries in this market.
| Leading Market Players |
|---|
| Leadinfo |
| Leadpipe |
| Dealfront |
| Albacross |
| RB2B |
| 6sense |
| ZoomInfo |
| Lead Forensics |
| HubSpot Breeze Intelligence |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month ISO/IEC 27001 certification timelines compress vendor pricing power while amplifying procurement leverage for enterprise buyers negotiating multi-year SaaS contracts. This lead-time band concentrates margin pressure on emerging vendors unable to absorb audit costs, tilting contract structures toward outcome-based pricing with implementation guarantees.
Pricing Analysis
Volume-discount tiering structures stratify across premium API-intensive deployments, standard mid-market SaaS tiers, and economy self-service offerings with limited CRM integrations. Pricing differentiation hinges on ISO/IEC 27001 certification status and GDPR-aligned data residency architecture, with certified vendors commanding 20-40% premiums over uncertified competitors. Cost compression in the economy tier intensifies because Google's cookie deprecation forces reliance on costlier deterministic identification methods. Mid-market B2B SaaS vendors exhibit highest price sensitivity, while financial services firms in Germany and Switzerland demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes into European and North American markets fluctuate with container availability at Singapore and Rotterdam port clusters, exposing hardware-dependent biometric vendors to working capital strain. Specialized edge AI chips for facial recognition inference draw from TSMC fabrication in Taiwan, while RFID reader assembly concentrates in Gujarat and Tamil Nadu under India's PLI scheme. Single-source vulnerability in semiconductor fabrication creates supply chain risk for vendors deploying palm-vein and iris authentication hardware. Distribution runs through certified system integrator networks that absorb implementation risk for enterprise accounts demanding fixed-price deployment guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Visitor identification software functions as a service-attach opportunity where recurring compliance consulting and ISO/IEC 27001 certification support expand faster than one-time hardware margins. Annual audit preparation and EU AI Act conformity assessments generate sticky revenue streams that outpace license growth.
For Market Incumbents: Secure data graph scale advantages through proprietary IP intelligence accumulation while fortifying GDPR-aligned architectures against emerging European specialists. Cookie deprecation threatens probabilistic identification match rates, demanding accelerated investment in deterministic methods and first-party data partnerships. Vertical integration into edge AI chip design reduces TSMC dependency exposure for biometric hardware portfolios. For New Entrants and Emerging Players: Anchor in hybrid deployment architectures for educational institutions struggling to bridge legacy badge infrastructure with cloud analytics, the most penetrable segment due to procurement budget constraints and integration complexity barriers. India's PLI scheme for electronics manufacturing offers geographic white space with government-subsidized assembly costs. A channel-centric go-to-market through certified system integrators deflects enterprise sales cycle risk. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory divergence between GDPR, EU AI Act, and emerging US state-level privacy statutes creates persistent demand for multi-jurisdictional certification expertise. Acquisition targets with documented audit trails and notified body relationships in France and Germany command structural scarcity premiums. The signal to watch is enforcement velocity of EU AI Act biometric risk-classification deadlines accelerating hospital procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures with Salesforce and HubSpot connectors compress implementation cycles for mid-market SaaS vendors. |
| Acquisition of Specialist Firm | Documented EU AI Act conformity assessment capabilities from notified bodies accelerate compliance roadmap execution. |
| Strategic Partnership | Certified system integrator networks absorb fixed-price deployment risk demanded by Fortune 500 procurement programs. |
| Geographic Expansion | PLI scheme utilization in Gujarat and Tamil Nadu reduces landed costs for RFID and biometric hardware assembly. |
| Product Launch | On-device facial recognition with neural network pruning eliminates cloud dependency for high-security sterile zone deployments. |
Research Methodology
A spread of perspectives from chief technology officers, IT procurement officers at B2B SaaS vendors, platform integration specialists, and data protection officers converged on the working assumptions shaping this analysis. Primary fieldwork with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, GDPR enforcement databases, and EU AI Act implementation guidance. Bottom-up triangulation of vendor-reported deployment metrics and top-down reconciliation against addressable market sizing anchored quantitative outputs.
Segmentation dimensions modeled span deployment architecture, end-user vertical, identification technology modality, and application scope across the analysis window. CAGRs derive from logistic adoption curve fitting calibrated to historical SaaS penetration patterns and regulatory enforcement timelines. Cloud migration velocity among mid-market vendors and biometric accuracy improvement trajectories constitute industry-specific forecast inputs.
Material uncertainties — regulatory enforcement delays, supply chain disruption in Taiwan semiconductor fabrication, and accelerated cookie deprecation timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance cost trajectories and enterprise procurement standardization programs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Audit Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Web Framework Software Market
Software & Services
Global Nosql Software Market
Software & Services
Automotive Customization Software Market
Software & Services
Global Voting Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Global DevOps Software Market
Software & Services
Federal Government Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Legal Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Global Accreditation Management Software Market