
 Global Enterprise Architecture Tools Market | 2026-2036
Global Enterprise Architecture Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Architecture Tools Market Foresight
Subscription-based delivery is rebalancing how enterprise architecture capabilities reach buyers, shifting capital expenditure into recurring operational budgets. Software AG leverages its dual heritage in integration and architecture to sustain premium positioning across European banking clients. LeanIX anchors cloud-native deployment momentum with API-first repository design. Sparx Systems competes through deep specialization in systems modeling languages, occupying a defensible niche among defense and aerospace engineering teams.
Enterprise architecture tools comprise software platforms that model, analyze, and govern the relationships between business processes, information systems, technology infrastructure, and organizational strategy through standardized frameworks such as TOGAF, ArchiMate, and UML. These systems enable organizations to map application portfolios, assess technical debt, simulate transformation scenarios, and enforce compliance across multi-cloud environments. Cloud-based deployment leads absolute growth as regulated industries overcome latency and sovereignty concerns through hybrid configurations, while repository tools capture expanding margin pools as data gravity intensifies across distributed architectures. Analysis tools represent the fastest-advancing segment, driven by AI-assisted pattern recognition in legacy system interdependencies.
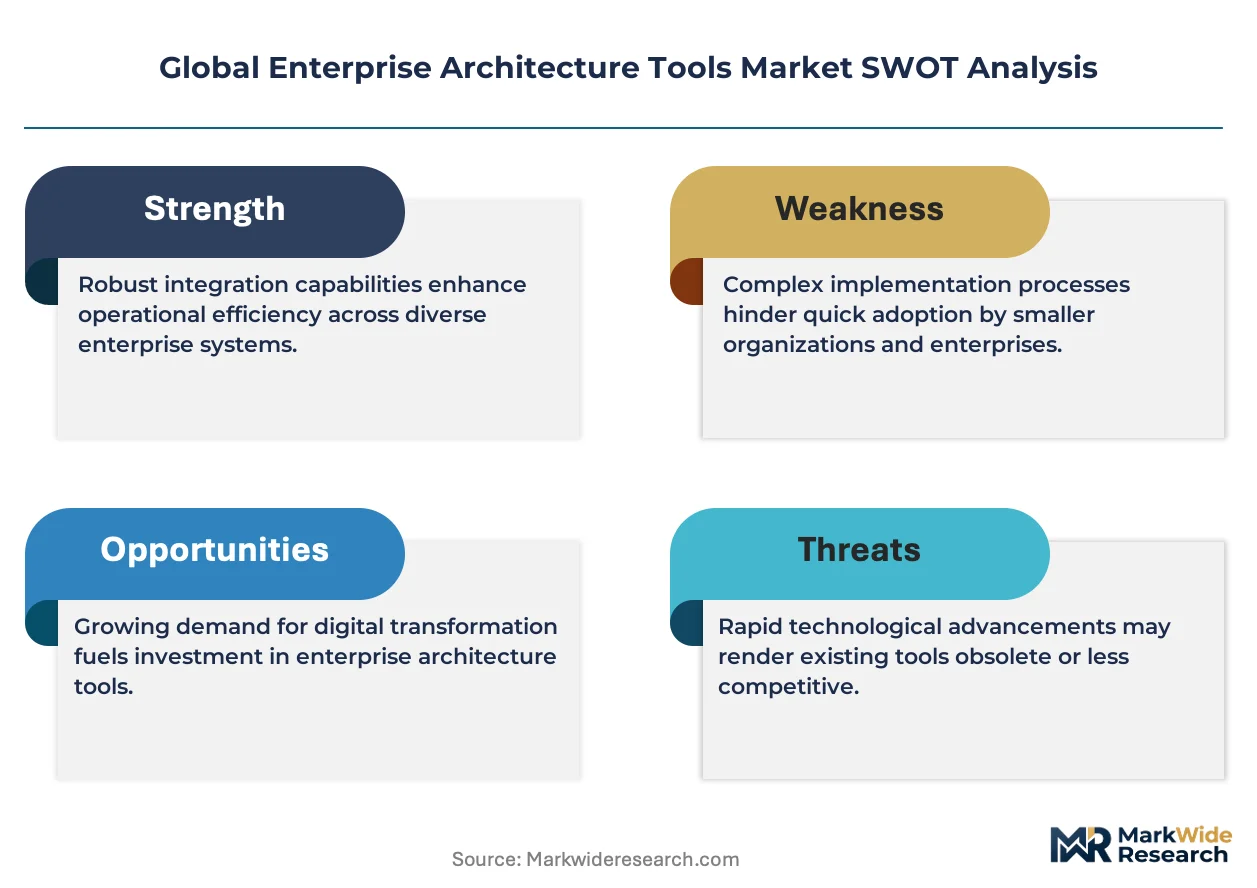
The EU AI Act imposes documentation and traceability obligations that directly expand architecture tool deployment scope, while GDPR Article 30 records of processing activities require maintained system maps that these platforms automate. ISO 27001 and IEC 62304 standards further harden requirements for controlled, auditable IT asset governance across healthcare and critical infrastructure sectors. Stakeholders must monitor how emerging sustainability disclosure rules under CSRD extend architecture mandates into carbon-accounting data lineage and supplier emissions tracking.
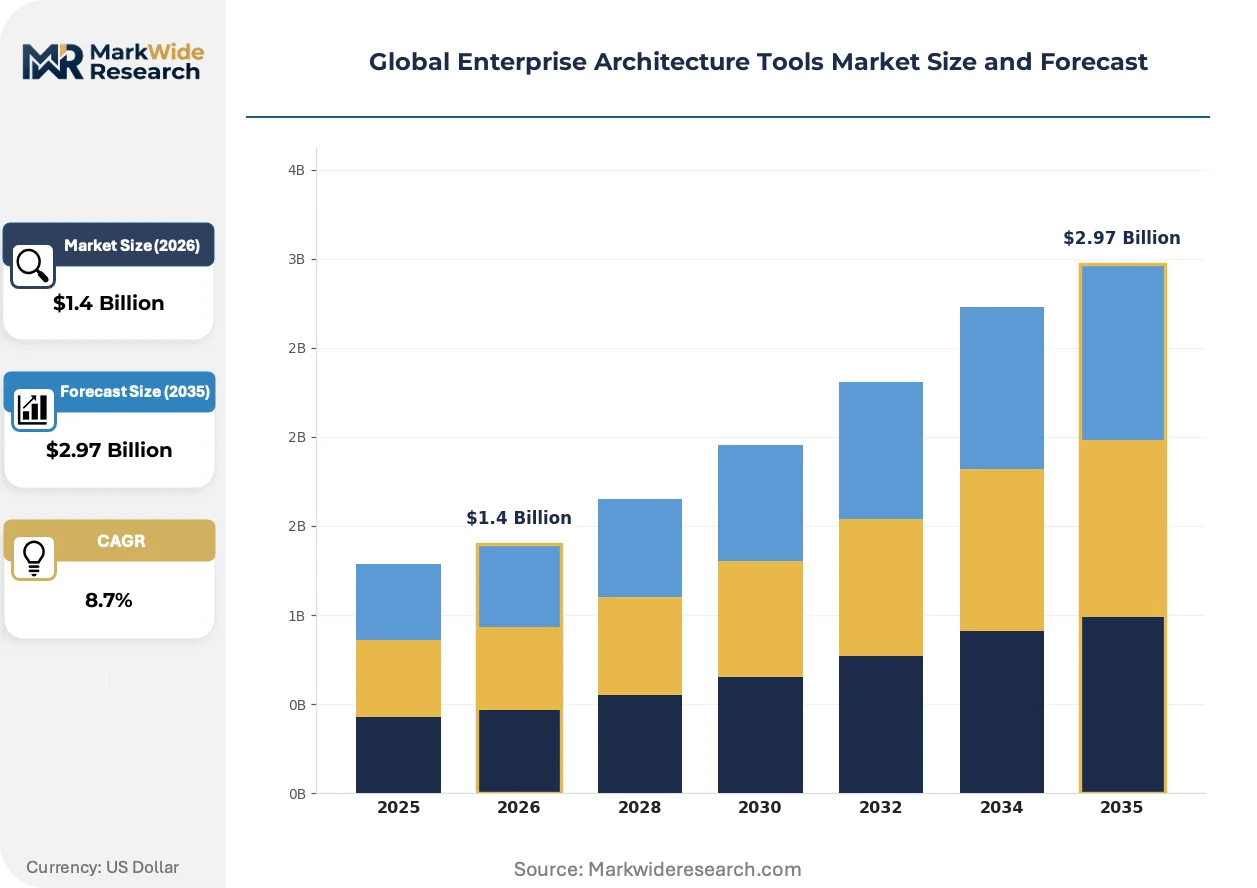
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR compliance requirements are accelerating procurement of architecture modeling platforms, compressing traditional on-premise deployment cycles and forcing vendor consolidation around API-first repository designs.
Growth Catalysts
- EU AI Act documentation obligations:Financial services institutions in Frankfurt and Paris must maintain traceable system maps, expanding architecture tool deployment scope across banking IT governance frameworks.
- GDPR Article 30 automation:Records of processing activities require maintained system maps that enterprise architecture platforms automate, driving replacement of manual spreadsheet-based inventory management.
- Automotive IT governance sophistication:German automotive and industrial conglomerates maintain complex multi-cloud environments that demand advanced architecture modeling for supplier integration and technical debt assessment.
Market Restraints
- Specialized talent scarcity:Shortage of professionals fluent in TOGAF, ArchiMate, and UML modeling languages constrains implementation velocity and extends deployment timelines.
- Hybrid configuration complexity:Latency and data sovereignty concerns force regulated industries into costly dual-stack deployments rather than pure cloud migration.
- Legacy system integration friction:Decades-old COBOL and mainframe environments resist standardized API connectivity, limiting architecture tool coverage in insurance and government sectors.
Strategic Opportunities
- CSRD sustainability disclosure extension:Emerging carbon-accounting data lineage requirements will mandate architecture tools that track supplier emissions across distributed value chains.
- Healthcare ISO 27001 convergence:IEC 62304 medical device software standards create demand for controlled, auditable IT asset governance platforms in hospital systems and device manufacturers.
- AI-assisted pattern recognition:Machine learning integration into analysis tools enables automated detection of legacy system interdependencies, compressing assessment cycles from months to weeks.
Industry Challenges
- Framework standardization delays:Competing modeling languages and certification pathways fragment buyer decision-making and extend vendor evaluation periods.
- Multi-cloud orchestration complexity:Architecture teams struggle to maintain coherent governance across AWS, Azure, and Google Cloud environments with divergent native tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Architecture Tools Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Private Cloud, Community Cloud Tool Type: Modeling Tools, Repository Tools, Analysis Tools, Reporting Tools, Collaboration Tools Application Area: Business Process Management, IT Infrastructure Management, Risk Management, Digital Transformation, Compliance Management Enterprise Sector: Banking Institutions, Telecommunications Providers, Manufacturing Firms, Government Agencies, Educational Organizations |
| Companies Covered | Software AG, MEGA International, Avolution, BiZZdesign, LeanIX, Orbus Software, Sparx Systems, BOC Group, QualiWare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Architecture Tools Market Shifts & Advancements
Subscription delivery models are rebalancing how enterprise architecture capabilities reach buyers, while AI integration and regulatory automation reshape platform functionality across regulated industries.
Repository tools with API-first design are consolidating market position as data gravity intensifies across distributed architectures. Financial services institutions in Germany and the Netherlands adopt these platforms fastest, replacing document-centric legacy systems. The technology is consolidating vendor margins around recurring revenue streams rather than perpetual license models.
GDPR and EU AI Act compliance automation is mandating architecture tool deployment across European banking and insurance sectors. The regulations require maintained, auditable system maps that manual processes cannot sustain. Healthcare providers in France and critical infrastructure operators in Sweden are responding with accelerated procurement of hybrid cloud configurations.
Buyer preference for integrated analysis capabilities over standalone modeling is compressing vendor competitive sets. Procurement teams now demand AI-assisted technical debt assessment and transformation scenario simulation within single platforms. This pattern appears most pronounced among German automotive conglomerates and Dutch financial institutions with sophisticated IT governance maturity.
Global Enterprise Architecture Tools Market Segmentation
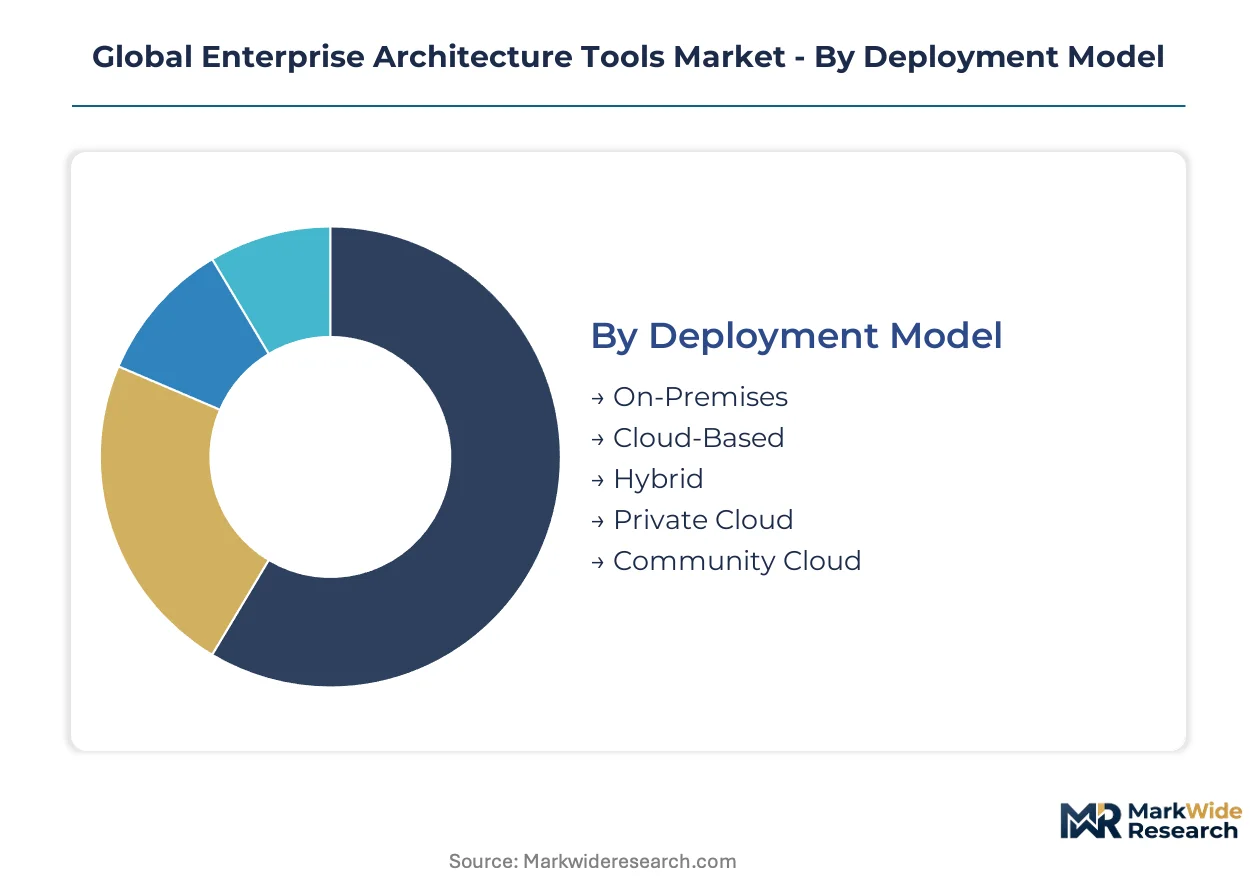
Deployment configurations, tool functionalities, and sector-specific compliance demands fragment the enterprise architecture tools landscape into distinct procurement clusters. Buyers prioritize segments aligning with regulatory exposure, cloud maturity, and legacy system density. Understanding these axes clarifies where vendor R&D investments and pricing power concentrate.
Deployment Model:
Cloud-native infrastructure governs how architecture capabilities reach regulated buyers, with latency tolerance and data sovereignty dictating configuration choices across financial services and healthcare.
- On-Premises:Hardware-resident installations maintain full data custody within organizational firewalls. Defense contractors in France and German automotive conglomerates with classified supplier networks sustain procurement despite higher capital intensity, driven by national security clearance requirements and industrial espionage concerns.
- Cloud-Based:Multi-tenant SaaS delivery eliminates infrastructure ownership while enabling elastic scaling. Dutch financial institutions and Swedish healthcare providers accelerate adoption fastest, responding to GDPR Article 30 automation mandates and the EU AI Act's documentation obligations through API-first repository designs.
- Hybrid:Split-stack configurations partition sensitive workloads on-premise while leveraging cloud analytics. Banks in Frankfurt and Paris deploy this architecture to reconcile latency-sensitive core banking systems with cloud-based AI-assisted pattern recognition tools.
- Private Cloud:Single-tenant cloud environments dedicated to one organization. Telecommunications providers in Germany favor this model for network function virtualization governance.
- Community Cloud:Shared infrastructure among organizations with common compliance requirements. Healthcare consortia in the Netherlands adopt this for IEC 62304 medical device software standard adherence.
Cloud-Based leads on scale; Hybrid leads on momentum as regulated industries navigate sovereignty constraints.
Tool Type:
Functional specialization determines margin capture, with integrated platforms displacing point solutions as procurement teams consolidate vendor relationships.
- Modeling Tools:Platforms rendering business processes, system interdependencies, and technology landscapes through TOGAF, ArchiMate, and UML frameworks. Aerospace engineering teams in France and defense contractors across Europe sustain demand for Sparx Systems' deep systems modeling specialization, where precision outweighs integration breadth.
- Repository Tools:Centralized data stores with API-first architectures enabling federated metadata management. These platforms consolidate market position as data gravity intensifies across distributed multi-cloud environments, with German banking IT governance frameworks driving fastest replacement of document-centric legacy systems.
- Analysis Tools:AI-assisted engines for technical debt assessment and transformation scenario simulation. Machine learning integration enables automated detection of legacy system interdependencies, compressing assessment cycles from months to weeks among automotive conglomerates.
- Reporting Tools:Automated documentation generators for regulatory submission and stakeholder communication. CSRD sustainability disclosure requirements extend demand into carbon-accounting data lineage tracking.
- Collaboration Tools:Stakeholder engagement platforms for distributed architecture teams. Multi-cloud orchestration complexity across AWS, Azure, and Google Cloud environments drives procurement among telecommunications providers.
Repository Tools command the largest revenue pools; Analysis Tools gain share fastest through AI integration.
Application Area:
Use-case specificity shapes feature roadmaps, with compliance automation and risk quantification commanding premium pricing.
- Business Process Management:End-to-end workflow mapping and optimization capabilities. Manufacturing firms in Germany deploy these for supplier integration across complex value chains.
- IT Infrastructure Management:Asset inventory, capacity planning, and lifecycle governance. Cloud migration mandates under the EU AI Act accelerate procurement among Frankfurt banking institutions.
- Risk Management:Vulnerability assessment and continuity planning tools. ISO 27001 convergence in healthcare and critical infrastructure sectors hardens requirements for controlled, auditable IT asset governance.
- Digital Transformation:Scenario modeling for legacy modernization and cloud migration. Automotive IT governance sophistication drives demand for technical debt assessment capabilities.
- Compliance Management:Automated regulatory mapping and audit trail generation. GDPR and EU AI Act obligations expand deployment scope across European banking and insurance sectors.
IT Infrastructure Management anchors current spending; Compliance Management climbs fastest on regulatory expansion.
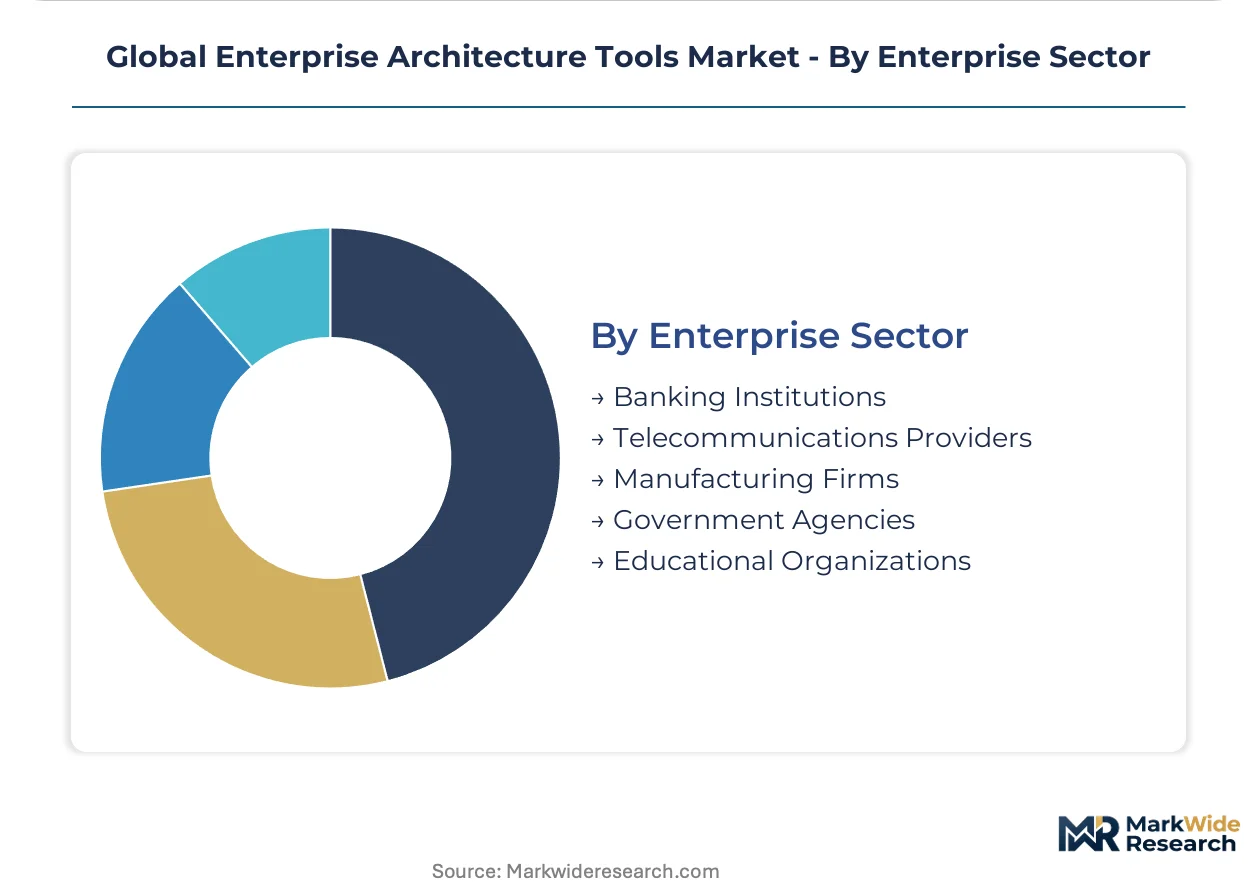
Enterprise Sector:
Sector-specific regulatory density and IT governance maturity create divergent willingness-to-pay curves across buyer categories.
- Banking Institutions:Financial services with complex multi-cloud environments and stringent documentation requirements. Frankfurt and Paris institutions lead procurement velocity, replacing manual spreadsheet-based inventory management with automated platform solutions.
- Telecommunications Providers:Network operators managing distributed infrastructure and spectrum assets. German providers with 5G rollout obligations sustain sophisticated architecture modeling for vendor integration.
- Manufacturing Firms:Industrial conglomerates with global supplier networks and technical debt accumulation. German automotive firms maintain the most mature IT governance frameworks, driving demand for advanced modeling capabilities.
- Government Agencies:Public sector organizations with transparency and interoperability mandates. Defense and critical infrastructure operators face ISO 27001 and IEC 62304 compliance pressures.
- Educational Organizations:Universities and research institutions with federated IT environments. Limited procurement scale constrains vendor customization investment.
Banking Institutions generate the deepest revenue; Manufacturing Firms expand fastest on supplier integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing as GDPR and EU AI Act documentation obligations standardize compliance costs across European banking centers, while latency-sensitive manufacturing clusters in Germany and East Asia sustain premium on-premise deployments despite higher capital intensity.
Germany
Automotive conglomerates in Stuttgart and Munich maintain sophisticated IT governance frameworks for supplier integration across multi-cloud environments. The EU AI Act imposes traceability mandates that accelerate procurement of hybrid architecture configurations among industrial manufacturers. Frankfurt banking institutions replace manual spreadsheet systems with automated repository platforms to satisfy GDPR Article 30 records requirements.
United States
Financial services institutions in New York and Chicago expand adoption of cloud-native architecture modeling for technical debt assessment and transformation scenario simulation. SEC disclosure rules and state-level privacy regulations in California create documentation obligations that mirror European compliance pressures. Defense contractors in Virginia sustain demand for on-premise installations with full data custody requirements.
France
Aerospace engineering teams in Toulouse and defense contractors across the Île-de-France region sustain procurement of specialized systems modeling platforms. ANSM and CNIL enforcement of healthcare data governance creates demand for ISO 27001-aligned architecture tools in Paris hospital systems. Critical infrastructure operators respond to IEC 62304 standards with accelerated hybrid cloud procurement.
Netherlands
Dutch financial institutions in Amsterdam lead European adoption of API-first repository designs for GDPR automation. Healthcare consortia deploy community cloud configurations to satisfy medical device software standards under IEC 62304. The country's centralized IT governance maturity enables fastest replacement of document-centric legacy systems among banking and insurance sectors.
Sweden
Telecommunications providers in Stockholm favor private cloud deployments for 5G network function virtualization governance. Critical infrastructure operators accelerate hybrid architecture procurement in response to EU AI Act documentation mandates. Healthcare providers align with IEC 62304 standards through controlled, auditable IT asset governance platforms.
Global Enterprise Architecture Tools Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors consolidating position as procurement teams reduce vendor counts. The vendor base concentrates around three tiers: legacy integration specialists with dual heritage capabilities, cloud-native entrants with API-first repository designs, and deep specialists in standardized modeling languages. M&A activity targets technical debt assessment capabilities, while strategic partnerships address multi-cloud orchestration complexity.
Within the integration heritage tier, Software AG exemplifies premium positioning sustained across European banking relationships. Cloud-native momentum anchors around LeanIX, which occupies a position defined by repository-first architecture. Deep specialization in systems modeling languages concentrates with Sparx Systems, representing defensible niche positioning among defense and aerospace engineering teams where precision requirements outweigh integration breadth.
| Leading Market Players |
|---|
| Software AG |
| MEGA International |
| Avolution |
| BiZZdesign |
| LeanIX |
| Orbus Software |
| Sparx Systems |
| BOC Group |
| QualiWare |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in enterprise architecture software have consolidated vendor tiers across Germany and the Netherlands, compressing mid-market pricing bands while sustaining premium capture among Frankfurt banking clients with complex GDPR compliance requirements. Their ownership structure rewards recurring revenue predictability over perpetual license spikes, disciplining supply-side investment toward API-first repository architectures that lock in switching costs.
Pricing Analysis
Capacity additions in Dutch cloud-native entrants are reshaping price floors for mid-tier repository tools, forcing legacy integration specialists toward value-based bundling. Three-tier pricing structure across premium, standard, and economy levels now stratifies by GDPR automation depth and AI-assisted analysis inclusion. Cost compression in standard tiers stems from open-source modeling language commoditization. Banking institutions in Frankfurt exhibit lowest price sensitivity, while educational organizations in Sweden face procurement freezes.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data centers concentrated in Ireland, Germany, and Sweden, with latency-sensitive edge nodes tethered to Frankfurt and Amsterdam financial districts. Specialized talent pipelines draw from French aerospace engineering programs and German technical universities. Single-source vulnerability concentrates in TOGAF-certified consulting capacity. Distribution runs through direct enterprise sales teams with embedded customer success functions, supplemented by systems integrator partnerships for legacy mainframe integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU AI Act documentation mandates and lighter US state-level privacy regimes creates geographic cost differentials, favoring hybrid deployment specialists with transatlantic compliance architectures.
For Market Incumbents: Deepen vertical integration into AI-assisted pattern recognition engines, acquiring technical debt assessment capabilities before cloud-native entrants achieve feature parity. Fortify channel control through exclusive systems integrator partnerships in German automotive corridors. Certification investment in ISO 27001-aligned healthcare modules addresses IEC 62304 convergence before specialized rivals consolidate Paris hospital procurement. For New Entrants and Emerging Players: Enter via CSRD sustainability disclosure extension, targeting carbon-accounting data lineage gaps among Dutch manufacturing consortia with immature IT governance. White-space concentrates in community cloud configurations for healthcare providers in the Netherlands seeking IEC 62304 adherence without capital-intensive private infrastructure. Go-to-market leverage: pre-built regulatory mapping templates for EU AI Act Article 11 traceability obligations. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone modeling tool vendors with aerospace defense exposure but limited API connectivity. Long-term viability favors repository-first platforms with federated metadata management over document-centric legacy systems. Acquisition target archetype: technical debt assessment engines with automotive OEM validation. Signal to watch: procurement consolidation among German banking IT governance frameworks toward integrated analysis-modeling bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships among Frankfurt institutions replacing spreadsheet-based inventory management. |
| Acquisition of Specialist Firm | Adds Sparx Systems' systems modeling depth to broaden defense and aerospace engineering coverage. |
| Strategic Partnership | Addresses multi-cloud orchestration complexity across AWS, Azure, and Google Cloud environments. |
| Product Launch | Introduces AI-assisted pattern recognition compressing legacy system assessment cycles from months to weeks. |
| Geographic Expansion | Captures GDPR Article 30 automation demand among Dutch financial institutions and Swedish healthcare providers. |
Research Methodology
Coverage spans Germany, France, Netherlands, Sweden, and United States, with primary inputs from each regional cluster combining executive interviews with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation. Triangulation draws from SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement databases. Bottom-up deployment model sizing and top-down regulatory mandate quantification cross-verify segment allocations.
Rate-of-change decomposition separates cloud migration velocity from compliance automation intensity across the projection horizon. Segmentation dimensions modeled include deployment configuration, tool functionality, application area, and enterprise sector maturity tier. CAGRs derive from fitted adoption curves calibrated to GDPR enforcement timelines and EU AI Act implementation phases. Industry-specific inputs incorporate technical debt accumulation rates in German automotive supplier networks and healthcare ISO 27001 certification velocity.
Inputs from hyperscaler infrastructure disclosures and regulatory consultation documents were available through the study window; gaps in private-cloud deployment cost structures introduce uncertainty bands around hybrid configuration forecasts. Forecasts reflect documented assumptions about EU AI Act enforcement consistency and GDPR fine trajectory. Regulatory delay, talent pipeline constriction, and legacy system integration friction warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Interactive Digital Signage Software Market
Software & Services
Stock Media Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Marketing Automation Software Market
Software & Services
Software Consulting Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
Content Moderation Software Market
Software & Services
Codeless Testing Market
Software & Services
Photo Editing Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
VFX Software Market
Software & Services
Global Voting Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Software-Defined Machine Market