
 Handheld Optical Gas Imaging Camera Market | 2026-2036
Handheld Optical Gas Imaging Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Optical Gas Imaging Camera Market Insights
Buyer concentration in the oil and gas sector is pivoting toward integrated supermajors and midstream operators running large-scale leak detection and repair programs. Teledyne FLIR leverages its cooled infrared core technology to anchor the premium segment for methane-sensitive applications. Honeywell International competes through its distributed safety instrumentation channel, while Sensia Solutions specializes in combining optical gas imaging with analytics platforms for real-time emission quantification.
A handheld optical gas imaging camera detects hydrocarbon and volatile organic compound leaks by capturing infrared radiation absorbed at specific wavelengths, typically employing cooled quantum well infrared photodetector arrays operating in the 3-5 µm or 7-14 µm spectral bands for parts-per-million sensitivity. The device's primary industrial purpose is to visualize otherwise invisible gas plumes during facility walkdowns, enabling operators to pinpoint emission sources without shutdown. Portable camera configurations lead unit shipments due to their flexibility across refinery turnarounds and pipeline surveys, while advanced imaging systems integrating spectroscopic validation command the strongest margin pools. Thermal imaging technology dominates the installed base, though optical sensors are gaining traction in compact units targeting confined-space inspections.
EPA methane regulations and LDAR requirements under the Clean Air Act shape North American demand by mandating periodic optical gas imaging surveys at production and transmission facilities. OSHA process safety management standards and state-level air quality rules in Texas and California reinforce equipment deployment across chemical and power generation sites. Stakeholders must monitor evolving EPA enforcement priorities and state waiver dynamics to calibrate product certification roadmaps and channel investments.
Market Dynamics
Cooled quantum well infrared photodetector arrays are compressing detection thresholds for methane-sensitive applications, forcing incumbent suppliers to recalibrate certification roadmaps around EPA enforcement timelines.
Growth Catalysts
- EPA Methane Regulations:Leak detection and repair mandates under the Clean Air Act compel oil and gas operators to deploy optical gas imaging for quarterly facility surveys.
- Pipeline Integrity Management:United States midstream operators face PHMSA pressure to eliminate fugitive emissions across transmission corridors.
- Thermal Imaging Advances:Cooled detector sensitivity improvements enable visualization of smaller hydrocarbon plumes without process shutdown.
Market Restraints
- Detector Supply Concentration:Cooled infrared sensor fabrication concentrates among limited specialty foundries, creating input bottlenecks.
- Capital Intensity:Cooled quantum well photodetector arrays require cryogenic cooling systems that inflate unit manufacturing costs.
- Uncooled Sensor Substitution:Lower-cost microbolometer alternatives threaten share in non-critical inspection applications.
Strategic Opportunities
- European F-Gas Regulation:Mandatory fluorinated gas monitoring creates inspection demand across chemical refrigeration facilities.
- Drone Integration:Optical gas imaging payloads mounted on unmanned aerial systems enable rapid pipeline corridor sweeps.
- India Petrochemical Expansion:Reliance Industries and state-owned refiners are building LDAR capabilities at new Jamnagar and Paradip complexes.
Industry Challenges
- Calibration Certification:Factory calibration drift requires annual NIST-traceable recertification that strains field service networks.
- Spectroscopic Validation:Integrating tunable diode laser absorption spectroscopy for leak quantification demands firmware architecture redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Optical Gas Imaging Camera Market |
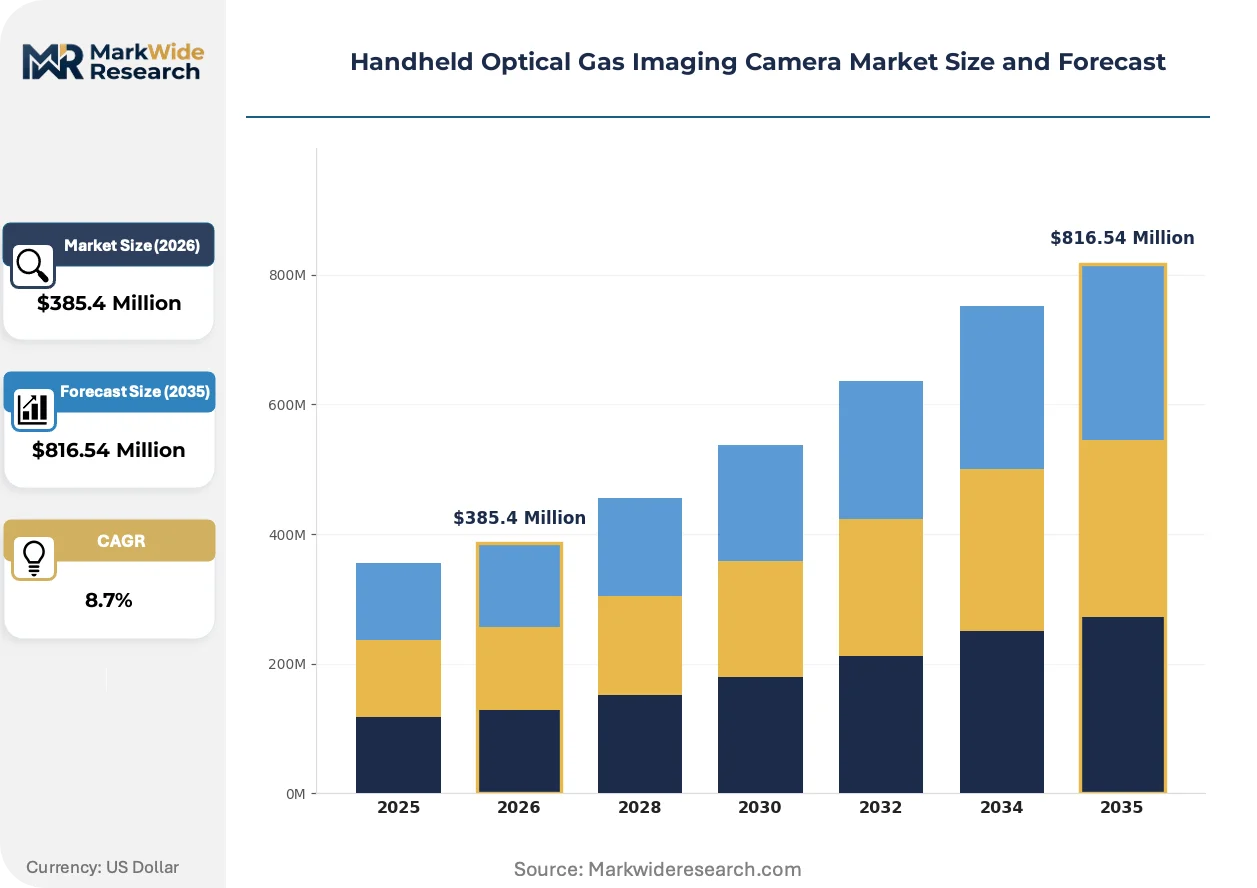
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Camera, Fixed Camera, In-Field Camera, Advanced Imaging System Technology: Infrared Detection, Thermal Imaging, Optical Sensors, Spectroscopy Application: Leak Detection, Emissions Monitoring, Preventive Maintenance, Safety Inspections End User: Oil & Gas, Chemical Industry, Power Generation, Environmental Agencies |
| Companies Covered | Sensia Solutions, Testo SE & Co. KGaA, Teledyne FLIR, Workswell, Honeywell International, Opgal Optronic Industries, Sierra-Olympic Technologies, LumaSense Technologies, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Optical Gas Imaging Camera Market Trends and Innovations
Detection sensitivity thresholds are compressing across portable imaging platforms, while regulatory enforcement timelines compress procurement cycles. Three developments dominate competitive positioning.
Multi-spectral imaging cores are expanding into compact handheld configurations previously limited to fixed-mount installations. Refinery turnaround contractors now specify these units for confined-space vessel inspections. The technology is expanding into mid-tier price bands that previously excluded cooled detector architectures.
OSHA process safety management standards are tightening documentation requirements for emission source identification. Chemical facility operators must archive geotagged thermal imagery for incident investigation. Texas and California state environmental agencies now accept only timestamped optical gas imaging records for compliance verification.
Integrated service contracts are displacing equipment-only procurement at supermajor operators. Bundled offerings combine hardware, cloud analytics, and certified technician deployment. This pattern concentrates in the Permian Basin where staffing shortages complicate in-house LDAR program execution.
Handheld Optical Gas Imaging Camera Market Segmentation
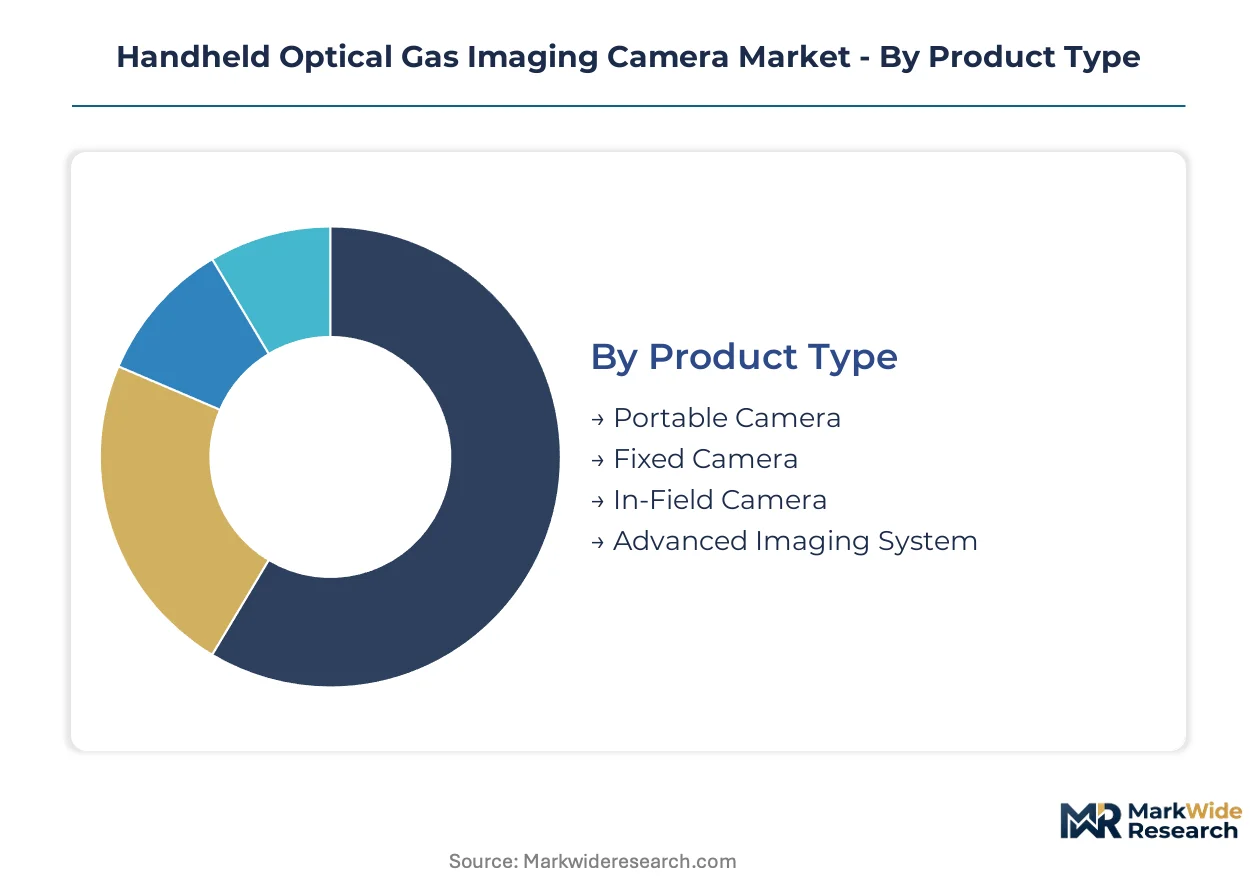
Handheld optical gas imaging camera procurement patterns diverge sharply between high-volume portable units for field crews and premium fixed installations for continuous monitoring. Understanding these segment boundaries clarifies where cooled detector investments concentrate versus where uncooled alternatives erode margins.
Product Type:
Portable configurations dominate unit shipments while advanced imaging systems capture the strongest margin pools, creating a bifurcated revenue structure across the product hierarchy.
- Portable Camera:Battery-powered units weighing under 3 kg enable single-operator walkdowns during refinery turnarounds and pipeline surveys. Demand concentrates among Permian Basin independent producers running lean LDAR crews under EPA quarterly survey mandates.
- Advanced Imaging System:Multi-spectral cores integrating spectroscopic validation command 3-5x pricing premiums over standard portable units. Oil and gas supermajors deploy these for methane quantification required under evolving EPA enforcement protocols.
- Fixed Camera:Permanently mounted installations for perimeter fence-line monitoring at chemical processing facilities.
- In-Field Camera:Ruggedized variants with ATEX certification for hazardous zone inspections in offshore platform environments.
Today's leader: Portable Camera. Tomorrow's challenger: Advanced Imaging System.
Technology:
Cost tier separation runs deepest here, with cryogenic-cooled architectures defending premium positions against uncooled microbolometer encroachment in price-sensitive applications.
- Thermal Imaging:Cooled quantum well infrared photodetector arrays operating in 3-5 µm spectral bands deliver parts-per-million methane sensitivity. United States midstream operators specify these for PHMSA-mandated pipeline integrity surveys where leak visualization thresholds determine compliance.
- Infrared Detection:Uncooled microbolometer alternatives sacrifice sensitivity for 40-60% cost reductions. Environmental agencies in Texas and California accept these for qualitative screening surveys where quantitative emission rates remain secondary.
- Optical Sensors:Compact diode-based architectures gaining traction in confined-space vessel inspections.
- Spectroscopy:Tunable diode laser absorption spectroscopy integration enables leak quantification for carbon accounting disclosures.
Thermal Imaging anchors current procurement volumes. Spectroscopy integration is climbing the fastest as emission quantification requirements tighten.
Application:
Customer type dictates specification intensity, with oil and gas operators demanding certified documentation trails that chemical facilities often bypass.
- Leak Detection:Primary use case encompassing fugitive emission identification at valves, flanges, and compressor seals. Oil and gas operators in the United States deploy handheld units across 400,000+ well sites under Clean Air Act LDAR programs.
- Emissions Monitoring:Continuous or periodic measurement for regulatory reporting and carbon intensity benchmarking. Power generation utilities in California integrate these readings with state cap-and-trade compliance submissions.
- Preventive Maintenance:Predictive inspection schedules reducing unplanned shutdowns at petrochemical crackers.
- Safety Inspections:Confined-space entry protocols requiring gas visualization before personnel deployment.
Leak Detection commands installed base dominance. Emissions Monitoring represents the steepest expansion trajectory as methane pricing mechanisms mature.
End User:
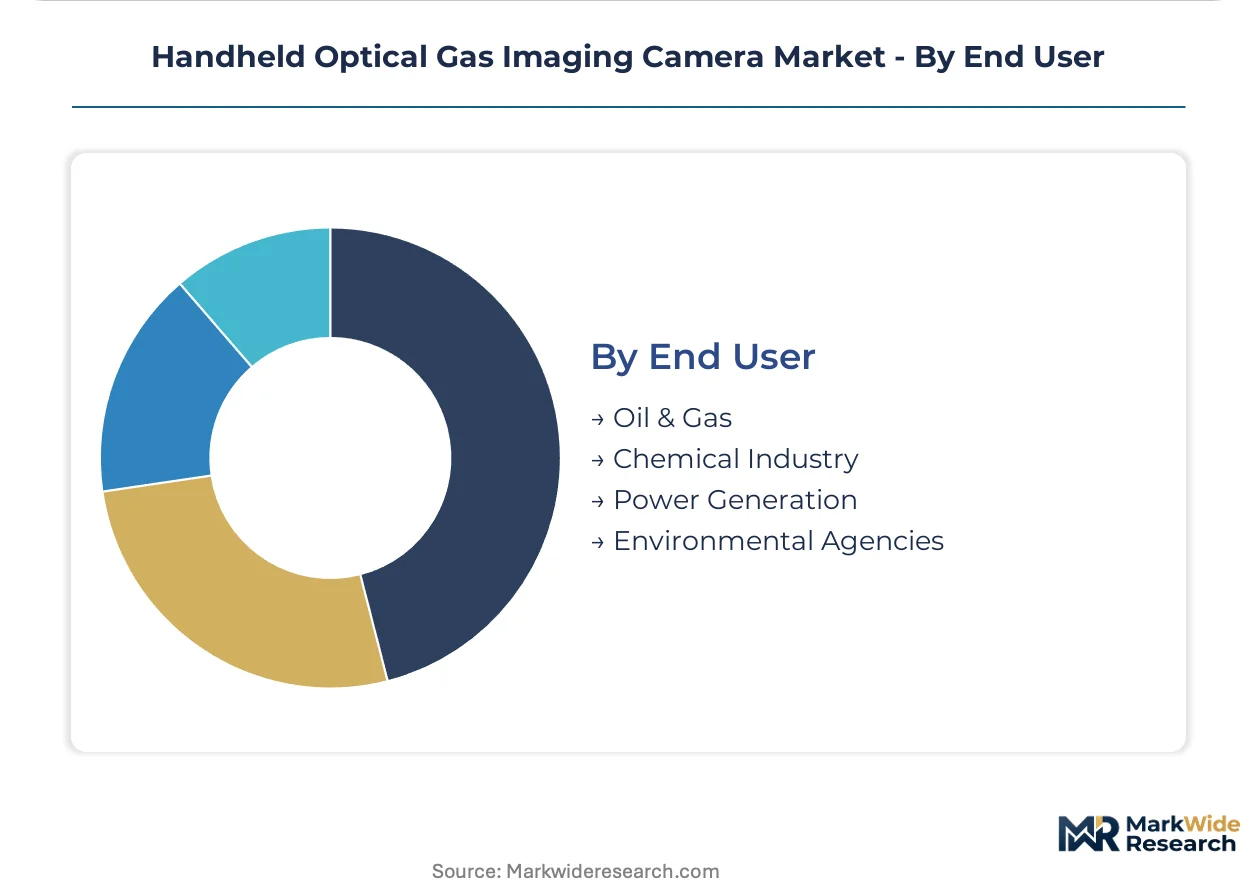
Volume concentration versus margin extraction splits across customer categories, with integrated supermajors bundling service contracts while independents prioritize equipment ownership.
- Oil & Gas:Upstream, midstream, and downstream operators account for the majority of cooled detector procurement. United States shale producers face the most stringent EPA methane survey frequencies globally, driving replacement cycles.
- Chemical Industry:OSHA process safety management standards mandate emission source documentation. Texas Gulf Coast petrochemical complexes specify timestamped thermal imagery for incident investigation archives.
- Power Generation:Natural gas combined cycle plants monitoring turbine fuel system integrity.
- Environmental Agencies:State-level air quality enforcement divisions conducting third-party verification surveys.
Oil & Gas maintains procurement leadership. Chemical Industry adoption is gaining share fastest as OSHA documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized LDAR technicians and certified thermographers concentrate in shale basins and industrial corridors where fugitive emission enforcement is most rigorous. Their geographic clustering shapes procurement patterns across national markets.
United States
Permian Basin independent producers and Gulf Coast petrochemical operators drive cooled detector demand under EPA quarterly methane survey mandates. PHMSA pipeline integrity rules compel midstream operators across Texas and Louisiana to deploy handheld units for transmission corridor inspections. Houston anchors the largest concentration of LDAR service contractors, with equipment procurement cycles accelerating ahead of enforcement deadline shifts.
Germany
Chemical conglomerates along the Rhine-Ruhr industrial belt invest in multi-spectral imaging for fluorinated gas monitoring under EU F-Gas Regulation phase-down schedules. ECHA enforcement of refrigerant leak reporting intensifies inspection protocols at BASF and Bayer manufacturing complexes. Ludwigshafen's chemical park operators specify timestamped thermal documentation for process safety management audits.
China
State-owned refiners at Sinopec and PetroChina expand LDAR capabilities under MEE air quality improvement targets for the Beijing-Tianjin-Hebei region. National carbon intensity benchmarking drives optical gas imaging deployment at new petrochemical complexes in Ningbo and Dalian. Yangtze River Delta environmental inspectors mandate leak visualization for VOC emission permits at pharmaceutical manufacturing clusters.
Canada
Alberta oil sands operators face provincial methane reduction regulations requiring optical gas imaging for in-situ extraction facilities. Environment and Climate Change Canada enforcement of federal methane rules intensifies survey frequencies at British Columbia natural gas processing plants. Calgary-based midstream companies specify cooled detector units for Montney Formation gathering system integrity programs.
Saudi Arabia
Saudi Aramco's Master Gas System expansion drives procurement of ruggedized imaging systems for hazardous zone inspections at Shaybah and Khurais fields. The kingdom's national industrial regulator mandates leak detection protocols for new petrochemical investments at Jubail Industrial City. SABIC affiliates at Yanbu specify ATEX-certified portable cameras for turnaround inspections at olefins crackers.
Handheld Optical Gas Imaging Camera Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated structure where premium-tier cooled detector architectures defend margin pools against uncooled alternatives. The vendor base stratifies into three archetypes: thermal imaging technology originators, safety instrumentation conglomerates with distributed channel access, and analytics-integrated specialists bundling hardware with cloud platforms. Consolidation pressure concentrates among mid-tier uncooled sensor assemblers facing component supply bottlenecks. Dominant competitive moves include strategic partnerships for drone payload integration and backward integration into cooled sensor fabrication.
Within the premium technology tier, Teledyne FLIR and Honeywell International exemplify divergent channel strategies—one leveraging specialized infrared core expertise, the other deploying industrial safety distribution networks. Sensia Solutions occupies a position combining optical hardware with real-time emission quantification analytics. These three anchors illustrate how competitive positioning separates around detector architecture sophistication versus service bundling depth.
| Leading Market Players |
|---|
| Sensia Solutions |
| Testo SE & Co. KGaA |
| Teledyne FLIR |
| Workswell |
| Honeywell International |
| Opgal Optronic Industries |
| Sierra-Olympic Technologies |
| LumaSense Technologies |
| Fluke Corporation |
| Others |
Pricing and Supply Chain Analysis
Cryogenic cooler backward integration among United States and German sensor fabricators anchors both supply security and premium-tier pricing power for methane-sensitive detector architectures. EPA enforcement timelines compress procurement cycles, while cooled quantum well photodetector foundry concentration limits price competition at the performance threshold.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for uncooled microbolometer alternatives, forcing recalibration across mid-tier portable configurations. Three-tier pricing structure across premium cooled-detector, standard uncooled-thermal, and economy optical-sensor levels separates EPA-certified quantification units from qualitative screening devices. Price differentiation rests on NIST-traceable calibration certification and cryogenic cooling system reliability grades. Pricing pressure stems from microbolometer substitution in non-critical Texas and California screening applications where environmental agencies accept reduced sensitivity. Independent Permian Basin producers exhibit highest price sensitivity due to lean LDAR crew structures, while integrated supermajors prioritize quantification accuracy over unit cost.
Supply Chain Analysis
Domestic-content mandates under United States Buy American provisions and India's PLI scheme for precision instrumentation are reshaping sourcing patterns for final assembly and detector packaging operations. Cooled infrared sensor fabrication concentrates in the United States, Germany, and Israel, drawing from indium antimonide, mercury cadmium telluride, and gallium arsenide substrate supplies. Cryogenic cooler subsystems and quantum well photodetector arrays create single-source vulnerability at specialty foundry nodes. Distribution runs through industrial safety instrumentation channels anchored by Houston and Ludwigshafen logistics clusters, supplemented by direct OEM relationships for supermajor bundled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States EPA enforcement premiums and European F-Gas Regulation inspection mandates, with cost differentials favoring midstream service bundling in North American shale basins over standalone equipment sales in EU chemical corridors.
For Market Incumbents: Anticipate uncooled microbolometer encroachment by accelerating spectroscopic validation integration for methane quantification compliance, defending premium positioning against emerging analytics-integrated specialists. Backward integration into cryogenic cooler fabrication secures supply continuity as specialty foundry bottlenecks intensify. Channel control through certified technician networks in the Permian Basin reinforces bundling economics against equipment-only competitors. For New Entrants and Emerging Players: Begin with drone payload integration for pipeline corridor sweeps, exploiting white-space in unmanned aerial system optical gas imaging where incumbent hardware architectures require miniaturization redesign. India's Jamnagar and Paradip petrochemical complexes represent the most penetrable geography, with state-owned refiners building LDAR capabilities absent entrenched supplier relationships. Cloud analytics partnerships with established industrial software platforms accelerate credibility without captive sensor fabrication investment. For Investors and Strategic Acquirers: Roll-up economics work for regional LDAR service contractors because supermajor bundled procurement concentrates demand among technicians with EPA certification and geotagged documentation capabilities. Five-to-ten year viability hinges on methane pricing mechanism maturation and enforcement protocol harmonization across jurisdictions. Acquisition targets should demonstrate certified thermographer density in shale basins. The signal to watch is EPA waiver dynamics and state-level enforcement delegation patterns that shift procurement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Drone Payload Miniaturization | Unmanned aerial systems enable rapid PHMSA-mandated pipeline corridor inspections without ground crew deployment. |
| Spectroscopic Validation Integration | Tunable diode laser absorption spectroscopy firmware architectures satisfy evolving EPA methane quantification protocols. |
| Certified Technician Network Expansion | Geotagged thermal imagery documentation meets OSHA process safety management tightening in Texas and California. |
| Cryogenic Cooler Backward Integration | In-house quantum well photodetector cooling system production secures supply against specialty foundry concentration. |
| Cloud Analytics Platform Partnership | Real-time emission quantification bundling displaces equipment-only procurement at Permian Basin supermajors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with LDAR program managers, optical gas imaging equipment procurement leads at oil and gas operators, EPA regional enforcement officers, certified thermographer service contractors, and cooled infrared sensor fabrication engineers with secondary validation. EPA enforcement guidance documents, PHMSA pipeline integrity filings, state air quality board inspection records, and industrial safety equipment customs data anchored supply-side calibration. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-weighting approaches distributed value across portable camera, advanced imaging system, fixed camera, and in-field camera configurations, with technology tiers disaggregating cooled thermal imaging, uncooled infrared detection, optical sensors, and spectroscopy integration. Application segmentation captured leak detection, emissions monitoring, preventive maintenance, and safety inspection demand patterns. End-user weighting reflected oil and gas, chemical industry, power generation, and environmental agency procurement intensity. CAGRs derived from enforcement timeline elasticity and replacement cycle compression under quarterly survey mandates. Detector sensitivity threshold improvements and drone payload adoption curves informed technology transition assumptions.
Several conditions sit outside the modeled scope, including specific EPA enforcement deadline shifts, state waiver granting timelines, and cryogenic cooler supply disruption scenarios. Forecasts reflect documented assumptions about regulatory harmonization and methane pricing mechanism implementation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market