
 Asia-Pacific Small Signal Transistor Market | 2026-2036
Asia-Pacific Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Small Signal Transistor Market Insights
Modular packaging configurations is rebalancing procurement patterns across the Asia-Pacific Small Signal Transistor Market, as buyers shift from discrete component sourcing to pre-validated SMD and DIP module sets. On Semi leverages its integrated manufacturing footprint in the region to sustain cost competitiveness for high-volume bipolar junction transistor lines. Toshiba Corporation anchors premium positioning through proprietary trench isolation processes that differentiate its field effect transistor portfolio.
Asia-Pacific small signal transistors are low-power semiconductor devices engineered for current amplification, switching, and signal conditioning in circuits operating below one watt, typically fabricated through epitaxial planar diffusion or ion implantation on silicon or silicon-germanium substrates. Their primary commercial purpose spans precision voltage regulation in portable electronics and logic-level interfacing across industrial control systems. Field effect transistors command the widest margin pools due to gate-leakage performance advantages in battery-powered designs, while phototransistor demand accelerates fastest from optical sensor proliferation in automotive electronics. Darlington transistor configurations retain mature positioning in industrial motor drive segments where high current gain remains non-negotiable.
China's MIIT enforces GB standards for semiconductor reliability and power efficiency that directly shape product qualification requirements for domestic and imported devices. Japan's METI coordinates JIS standards with METI-funded consortia to maintain technical leadership in discrete component miniaturization. South Korea's MFDS and KCC frameworks govern electromagnetic compatibility testing that gates market access for telecommunications-grade transistors. Stakeholders must monitor how China's dual carbon goals cascade into material sourcing restrictions and carbon-intensity disclosure mandates for component suppliers.
Market Dynamics
China's dual carbon goals are compressing supplier qualification timelines as carbon-intensity disclosure mandates cascade from finished goods manufacturers down to discrete component vendors. Foundry capacity concentration in the Yangtze River Delta amplifies vulnerability to localized disruption.
Growth Catalysts
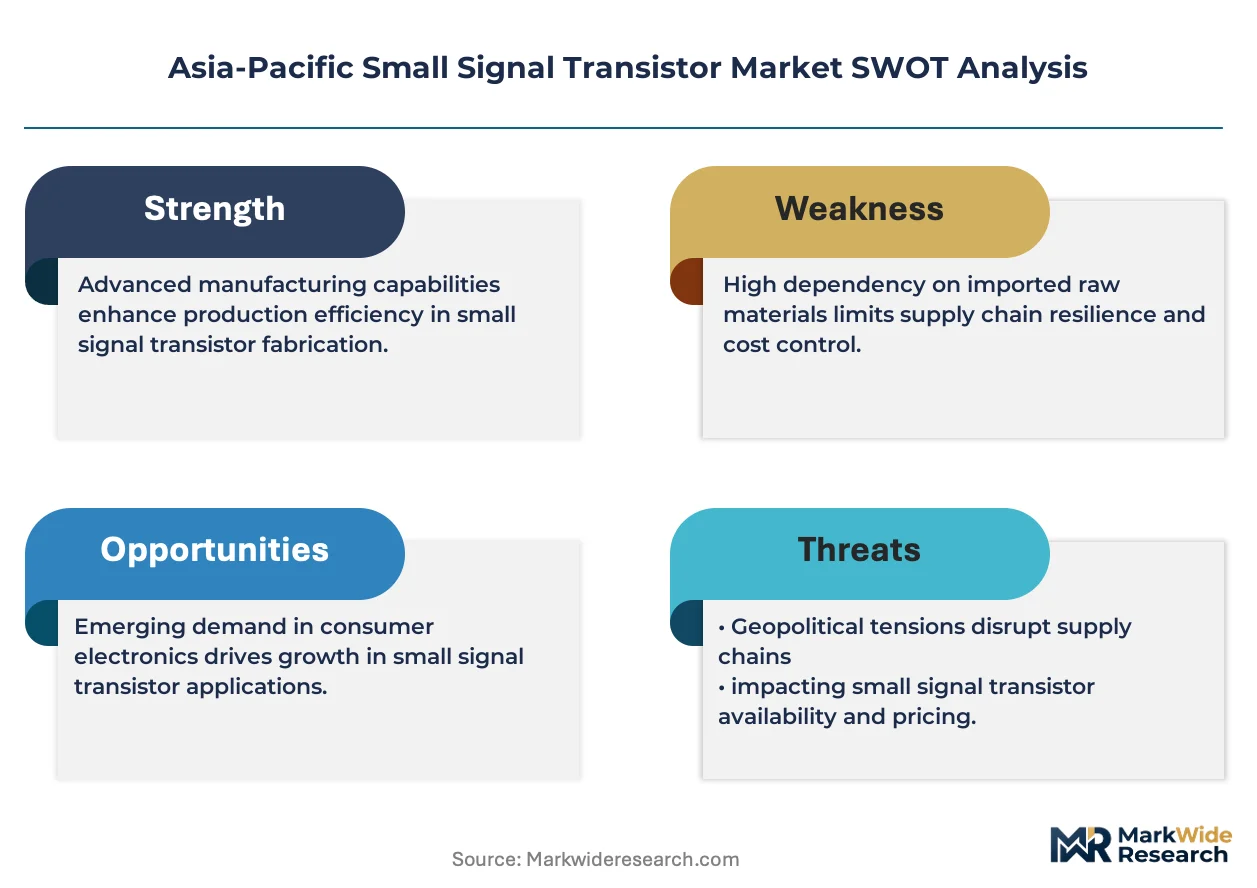
- Automotive electronics demand:EV powertrain control modules require precision signal switching for battery management systems. South Korean and Japanese automakers are expanding local sourcing requirements for Tier 2 semiconductor content.
- MIIT efficiency standards:China's GB standards for electronic component efficiency tighten performance thresholds, disqualifying legacy suppliers and consolidating procurement toward qualified vendors.
- SiGe substrate adoption:Silicon-germanium epitaxial processes deliver superior high-frequency performance for 5G telecommunications infrastructure. Japanese foundries are expanding SiGe line capacity to capture base station module contracts.
Market Restraints
- Raw material concentration:High-purity silicon wafer supply concentrates among Japanese and South Korean ingot manufacturers, exposing buyers to geopolitical friction and shipping lane disruption.
- Phototransistor substitution pressure:Integrated optical sensor SoCs with embedded signal conditioning are capturing design wins in automotive LiDAR and industrial automation, compressing discrete phototransistor sockets.
- MEE environmental enforcement:China's Ministry of Ecology and Environment is tightening wastewater discharge permits for semiconductor fabrication facilities, extending permitting timelines for new capacity additions.
Strategic Opportunities
- Vietnam manufacturing expansion:Electronics assembly migration from China creates demand for localized small signal transistor packaging and testing services. Ho Chi Minh City industrial zones are attracting module-level investment.
- India PLI scheme leverage:Production-linked incentive schemes for electronics manufacturing are creating import substitution opportunities for telecom-grade discrete semiconductors. Domestic handset assembly is scaling rapidly.
- Optical sensor convergence:Phototransistor-LED paired modules for biometric authentication in smartphones and wearables represent a high-margin application segment. Japanese and South Korean OEMs are specifying custom spectral response curves.
Industry Challenges
- Packaging engineer scarcity:Advanced SMD and QFN package design expertise concentrates among senior engineers at Japanese and Taiwanese OSATs. Succession planning gaps threaten knowledge transfer for miniaturized thermal management.
- AEC-Q101 certification timelines:Automotive-grade qualification for small signal transistors requires extended temperature cycling and humidity testing. Validation bottlenecks at third-party labs are extending time-to-revenue for new product introductions.
- Legacy equipment integration:Industrial control system upgrades require pin-compatible replacements for obsolete through-hole transistor footprints. Engineering resources for drop-in replacement design are stretched across multiple end-of-life programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small Signal Transistor Market |
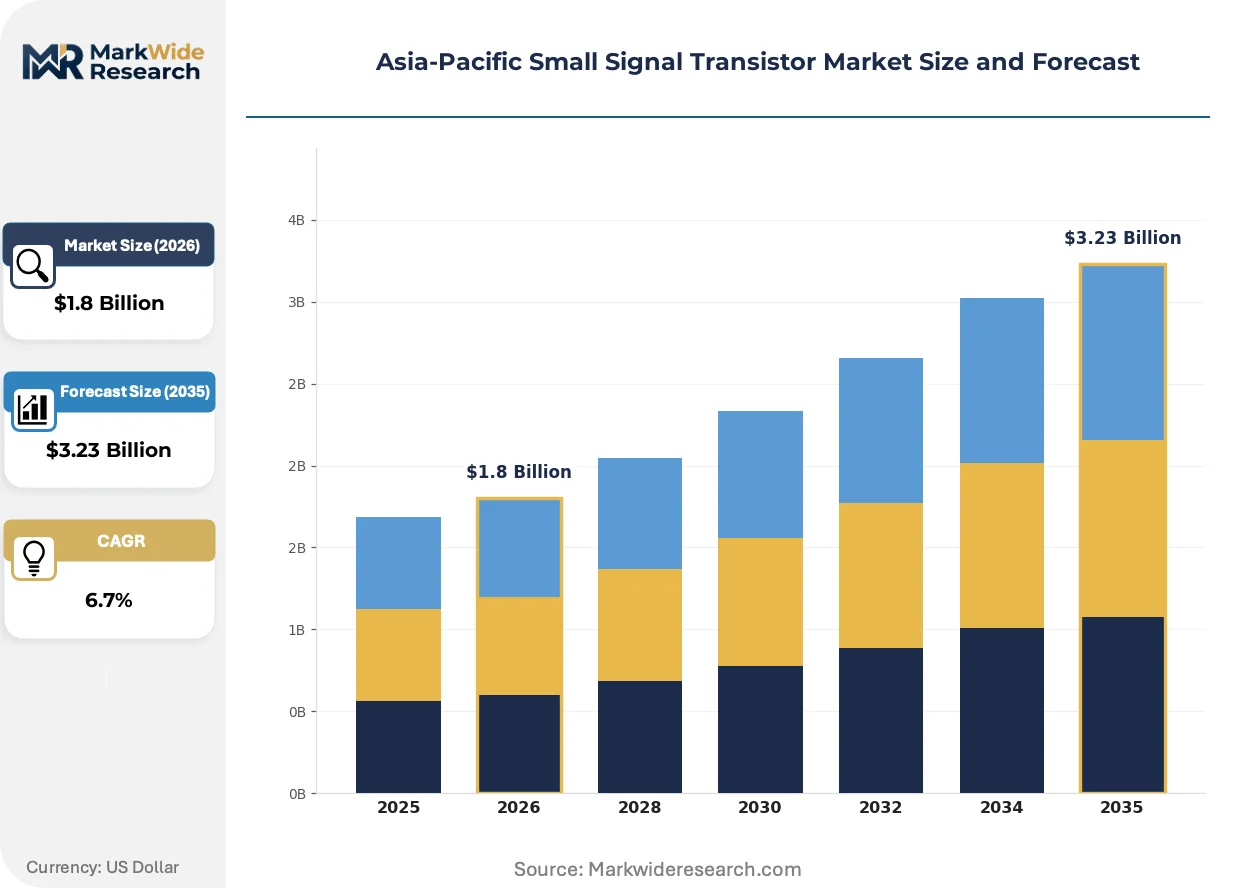
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, Darlington Transistor, Phototransistor End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment Packaging Type: DIP, SMD, TO-220, TO-92 Application: Amplifiers, Switching, Signal Processing, Voltage Regulation |
| Companies Covered | On Semi, STMicroelectronics, ROHM, Toshiba Corporation, Nexperia, Fuji Electric, NXP Semiconductors, Diodes Incorporated, Infineon Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small Signal Transistor Market Trends and Innovations
Epitaxial planar processes are yielding to more precise ion implantation techniques as device geometries shrink below 350 nanometers. Regulatory pressure on manufacturing emissions is accelerating wet chemistry substitution in fabrication.
Silicon-germanium heterojunction bipolar transistors are overtaking conventional silicon BJTs in 5G millimeter-wave front-end modules. South Korean base station OEMs have specified SiGe LNA designs for sub-6 GHz and mmWave bands. The technology is compressing noise figure specifications that legacy silicon processes cannot achieve, forcing foundry investment in SiGe epitaxy capability.
METI-funded consortia in Japan are coordinating JIS standard revisions for discrete component miniaturization with national technology roadmaps. The alignment accelerates adoption of 0201 and 01005 metric package sizes in consumer electronics. South Korean telecommunications equipment manufacturers are most affected, redesigning filter and switch modules around the smaller footprints to achieve board space targets.
Module-level procurement is consolidating purchasing authority away from component engineers toward platform sourcing teams at major OEMs. Pre-validated SMD and DIP module sets are displacing discrete component qualification for non-critical signal paths. The shift is most visible in China's Yangtze River Delta contract manufacturing ecosystem, where EMS providers are bundling transistor content into subsystem quotes.
Asia-Pacific Small Signal Transistor Market Segmentation
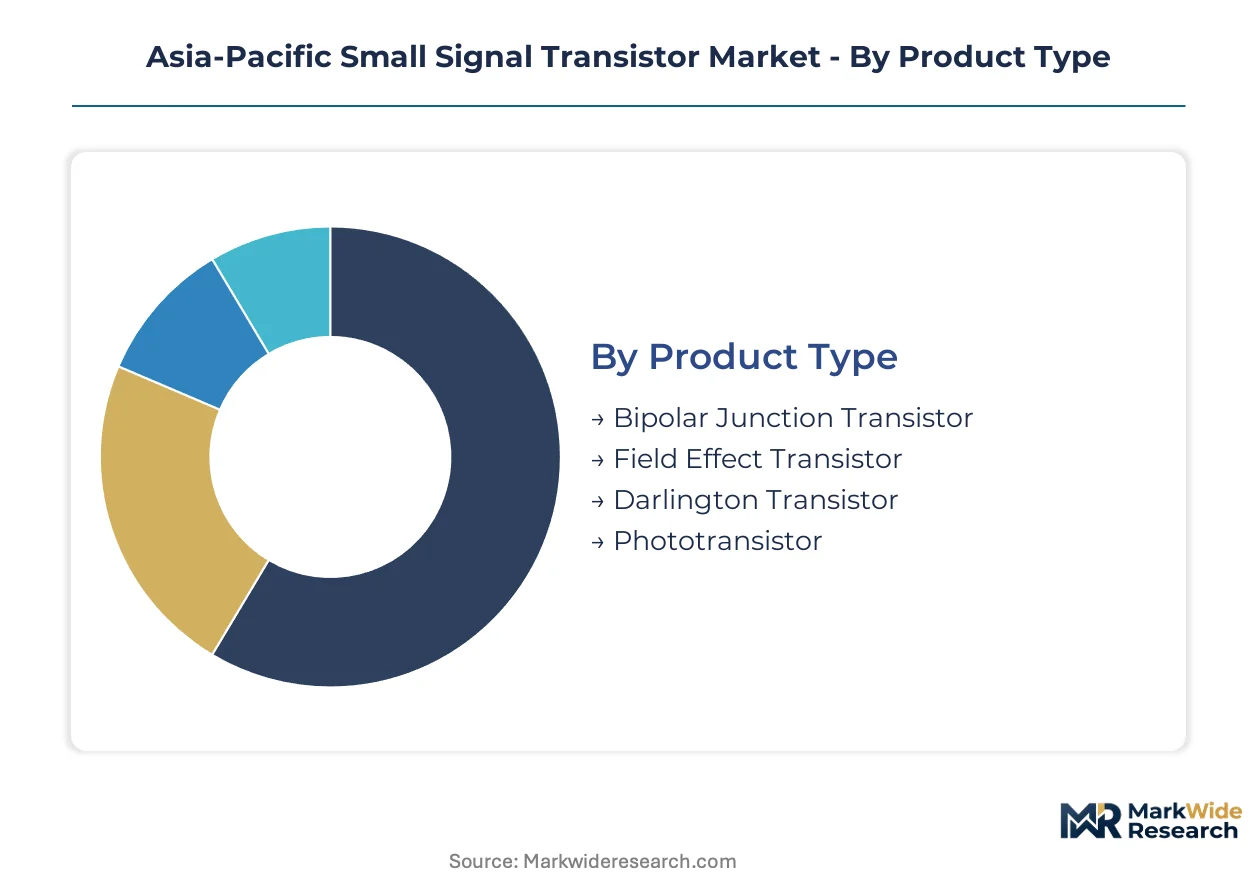
Segmentation in the Asia-Pacific Small Signal Transistor Market reveals how procurement authority is consolidating around module-level sourcing decisions. Buyers now evaluate transistor specifications through the lens of subsystem integration rather than discrete component performance. Each dimension below tracks a different axis of technical and commercial differentiation shaping supplier selection.
Product Type:
Buyers prioritize gate-leakage performance and current gain specifications when selecting transistor architectures for battery-powered or precision analog designs.
- Field Effect Transistor:Metal-oxide-semiconductor structures deliver superior input impedance and minimal power dissipation for portable electronics. South Korean smartphone OEMs specify FETs for power management ICs in foldable handset designs where thermal budgets are constrained.
- Bipolar Junction Transistor:Current-controlled devices fabricated through epitaxial planar diffusion excel in linear amplification circuits. China's Yangtze River Delta contract manufacturers source high-volume BJT lines for white goods motor control modules where cost-per-unit dominates selection criteria.
- Darlington Transistor:Cascaded NPN or PNP pairs deliver composite current gain exceeding 1000 for industrial motor drives requiring precise torque control.
- Phototransistor:Light-sensitive variants with base current modulated by optical input serve proximity detection and ambient light sensing functions.
Volume sits with Bipolar Junction Transistor for mature industrial applications; growth tilts toward Field Effect Transistor for 5G telecommunications and wearable electronics.
End User:
Application-specific qualification requirements create divergent procurement patterns across vertical markets, with automotive-grade certification commanding extended validation timelines.
- Automotive Electronics:EV powertrain control modules and battery management systems demand AEC-Q101 qualified devices with extended temperature ranges. Japanese Tier 1 suppliers are localizing small signal transistor sourcing to meet South Korean and Chinese automaker traceability mandates.
- Consumer Electronics:Portable devices prioritize miniature SMD footprints and sub-milliwatt quiescent power draw. India's domestic handset assembly expansion under PLI schemes is creating import substitution demand for telecom-grade discrete components.
- Telecommunications:Base station front-end modules require low-noise amplification with minimal noise figure degradation at millimeter-wave frequencies.
- Industrial Equipment:Programmable logic controllers and motor drives specify through-hole alternatives for legacy system compatibility and field-service replaceability.
Procurement volume concentrates in Consumer Electronics; Automotive Electronics exhibits the steepest expansion trajectory as electrification accelerates across China, Japan, and South Korea.
Packaging Type:
Assembly technology selection directly determines thermal dissipation capability, board space utilization, and automated placement compatibility in high-volume manufacturing.
- SMD:Surface-mount devices in 0201 and 01005 metric footprints enable dense PCB layouts for wearables and TWS earbuds. Japanese METI-funded consortia are driving JIS standard revisions that accelerate miniaturization adoption across South Korean telecommunications equipment supply chains.
- DIP:Dual in-line packages retain dominance in industrial control retrofits requiring pin-compatible replacements for obsolete through-hole designs. Engineering resources for drop-in replacement programs are stretched across multiple end-of-life initiatives in China's manufacturing base.
- TO-220:Through-hole metal tab packages handle elevated thermal loads for linear regulator applications in power supply modules.
- TO-92:Molded plastic through-hole housings serve cost-sensitive consumer applications with moderate power dissipation requirements.
Module-level procurement favors SMD for new designs; DIP maintains residual demand from industrial equipment refresh cycles.
Application:
Functional specification determines whether buyers prioritize linearity, switching speed, or precision voltage reference characteristics in transistor selection.
- Switching:Fast transition times and minimal storage charge enable efficient power conversion in DC-DC regulators. SiGe heterojunction bipolar processes from Japanese foundries are displacing conventional silicon for 5G millimeter-wave switch applications.
- Amplifiers:High gain-bandwidth product and low noise figure specifications serve audio preamplification and sensor signal conditioning. South Korean base station OEMs specify SiGe LNA designs for sub-6 GHz infrastructure deployment.
- Signal Processing:Matched pair configurations and tight parameter tolerance support analog filter and mixer implementations.
- Voltage Regulation:Precision reference characteristics and temperature coefficient stability enable LDO and shunt regulator designs.
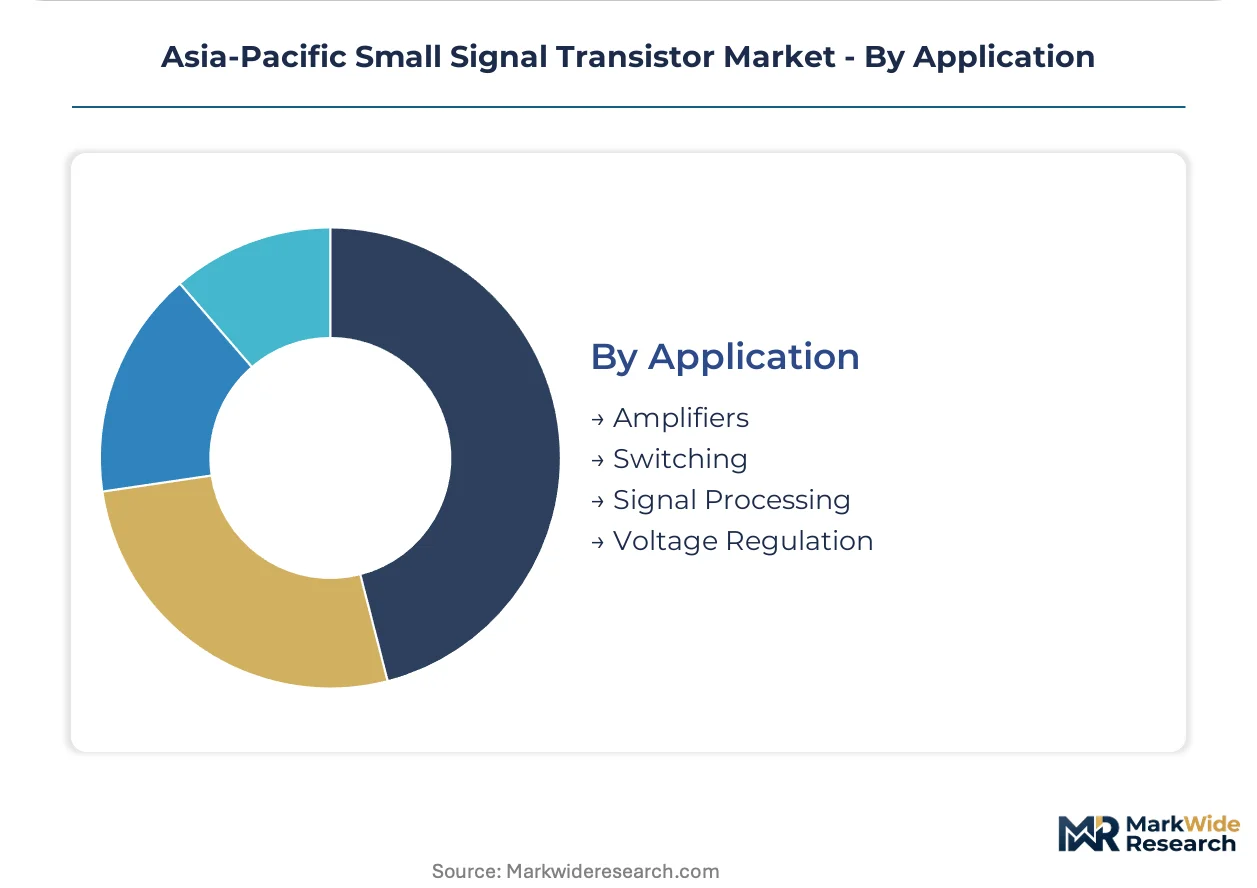
Switching applications capture the largest shipment volumes; Amplification functions are climbing the fastest as 5G infrastructure deployment intensifies across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta semiconductor cluster generates the majority of regional small signal transistor foundry output, yet consumption spreads across automotive assembly hubs in Japan, South Korea, and Southeast Asia. This production-consumption divide shapes logistics networks and qualification requirements.
China
MIIT enforces GB standards for electronic component efficiency that disqualify legacy suppliers from battery management system contracts. The dual carbon goals cascade into carbon-intensity disclosure mandates for component vendors supplying EV powertrain modules. Foundry capacity concentrates in the Yangtze River Delta, where Shanghai and Suzhou house co-located fabrication and advanced packaging ecosystems serving domestic automakers.
Japan
METI-funded consortia coordinate JIS standard revisions for discrete component miniaturization with national technology roadmaps. The alignment accelerates adoption of 0201 and 01005 metric package sizes in consumer electronics. Kanto and Kansai industrial corridors host precision epitaxial fabrication facilities supplying SiGe heterojunction bipolar transistors for 5G millimeter-wave infrastructure.
South Korea
MFDS and KCC frameworks govern electromagnetic compatibility testing that gates market access for telecommunications-grade transistors. Local automakers are expanding Tier 2 semiconductor sourcing requirements to domestic vendors. The Seoul Capital Area anchors design activity while Busan-Ulsan handles packaging and test operations for smartphone power management ICs.
Vietnam
Electronics assembly migration from China creates demand for localized small signal transistor packaging and testing services. Ho Chi Minh City industrial zones attract module-level investment from contract manufacturers serving consumer electronics brands. The country's national semiconductor regulator enforces import standards that favor pre-qualified component vendors with regional headquarters.
India
Production-linked incentive schemes for electronics manufacturing create import substitution opportunities for telecom-grade discrete semiconductors. Domestic handset assembly scales rapidly under PLI scheme disbursements. Karnataka and Tamil Nadu host the majority of EMS operations requiring localized sourcing of SMD transistor modules for smartphone and wearable production.
Asia-Pacific Small Signal Transistor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific small signal transistor market, creating a tiered structure where scale-driven portfolios face off against process-technology differentiation. The vendor base organizes around three strategic archetypes: integrated device manufacturers with captive fabrication, fabless design houses leveraging regional foundry partnerships, and specialized discrete component pure-plays. Capacity expansion in SiGe epitaxy and strategic partnerships for automotive qualification represent the dominant competitive moves reshaping positioning.
Within the integrated manufacturing tier, On Semi leverages its regional footprint to sustain cost competitiveness for high-volume bipolar junction transistor lines, while Toshiba Corporation anchors premium positioning through proprietary trench isolation processes. ROHM occupies a position bridging automotive-grade reliability requirements with consumer electronics miniaturization trends. These three exemplify how process specialization and end-market focus determine competitive boundaries.
| Leading Market Players |
|---|
| On Semi |
| STMicroelectronics |
| ROHM |
| Toshiba Corporation |
| Nexperia |
| Fuji Electric |
| NXP Semiconductors |
| Diodes Incorporated |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
High-purity silicon wafer spot indices from Japanese and South Korean ingot manufacturers cascade through three distinct pricing tiers across the Asia-Pacific small signal transistor market. Automotive-grade AEC-Q101 qualified devices command premium positioning against standard industrial and economy consumer tiers, with China's MIIT carbon-intensity disclosure mandates adding compliance cost layers that qualified vendors pass through to OEM procurement teams.
Pricing Analysis
Margin tightening in the automotive tier reflects extended AEC-Q101 validation timelines and third-party lab bottlenecks that compress time-to-revenue. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q101 certified devices from industrial-grade alternatives and cost-optimized consumer lines. Price differentiation traces to certification grade and volume scale, with China's Yangtze River Delta contract manufacturers exhibiting highest price sensitivity on high-volume BJT lines while Japanese Tier 1 suppliers absorb premiums for traceability compliance.
Supply Chain Analysis
Direct-to-OEM channels handle automotive Tier 1 demand, while distributor networks serve industrial retrofit and consumer electronics procurement. Supply concentrates in China's Yangtze River Delta fabrication cluster, Japan's Kanto and Kansai epitaxial facilities, and South Korea's Seoul Capital Area design houses. Raw material dependencies center on high-purity silicon wafers, gold bonding wire, and epoxy molding compounds. Single-source vulnerability in Japanese ingot manufacturing exposes buyers to shipping lane disruption and geopolitical friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT GB standards for electronic component efficiency operate as a cost-of-compliance moat that consolidates procurement toward qualified vendors and disqualifies legacy suppliers from EV powertrain contracts.
For Market Incumbents: Cement qualification leadership by accelerating SiGe epitaxy capacity additions in Japan's Kanto corridor to capture 5G base station LNA contracts. Deepen backward integration into high-purity silicon wafer supply through long-term offtake agreements with South Korean ingot manufacturers, insulating against raw material concentration risk that threatens margin stability. For New Entrants and Emerging Players: Capture module-level packaging opportunities in Vietnam's Ho Chi Minh City industrial zones as electronics assembly migration from China creates localized demand for SMD and DIP transistor sets. Target India's PLI scheme disbursement window for telecom-grade discrete component import substitution, leveraging domestic handset assembly scaling to establish foundry partnerships with Karnataka and Tamil Nadu EMS operations. For Investors and Strategic Acquirers: Distressed-cycle entries favor SiGe process-capable mid-cap specialists in Japan facing METI-funded consortium consolidation pressure. Long-term viability hinges on automotive qualification infrastructure and 5G telecommunications design wins. Monitor AEC-Q101 certification backlog clearance at third-party labs as the inflection signal for new product introduction velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| SiGe Epitaxy Capacity Expansion | Japanese foundries capture 5G millimeter-wave base station contracts from South Korean OEMs. |
| AEC-Q101 Certification Investment | Automotive-grade qualification opens EV powertrain procurement to Tier 1 suppliers in China. |
| Vietnam Packaging Localization | Ho Chi Minh City module-level investment serves consumer electronics assembly migration. |
| India PLI Scheme Leverage | Domestic handset assembly scaling creates import substitution demand for telecom-grade components. |
| Backward Integration into Wafers | Long-term ingot offtake agreements reduce exposure to Japanese supply concentration risk. |
Research Methodology
SEC filings, customs trade databases, and MIIT regulatory bulletins formed the secondary backbone, cross-referenced against primary interviews with semiconductor procurement managers at Japanese Tier 1 automotive suppliers, foundry operations directors in China's Yangtze River Delta, and packaging engineers at Taiwanese OSATs. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across product architectures.
Bottom-up modeling aggregated unit economics by transistor type, packaging format, and end-use vertical, while top-down checks anchored against regional electronics production indices. Segmentation dimensions included product architecture, packaging technology, application function, and geographic production cluster. CAGRs derived from regression analysis of historical foundry capacity utilization and OEM procurement cycle timing, with SiGe adoption curves and automotive electrification penetration as semiconductor-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT efficiency standard revisions, MEE environmental enforcement tightening, and phototransistor substitution by integrated optical sensor SoCs. Forecasts reflect documented assumptions on foundry capacity expansion timelines and automotive qualification bottlenecks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Multi-Mode Receiver Market
RF Components
Global Inductors Market
RF Components
LTCC Power Dividers Market
RF Components
Smart Antenna Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
Global RF Plasma Generator Market
RF Components
US RFID Tags Market
RF Components
Small Signal Mosfets Market
RF Components
RF Tester Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Europe Small Signal Transistor Market
RF Components
High Power RF Amplifier Module Market
RF Components
RF Mixers Market
RF Components
Multiband Booster Market
RF Components
RF Power Amplifiers Market