
 Global EMI Shielding Market | 2026-2036
Global EMI Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Global EMI Shielding Market Intelligence
The increasing density of components within miniaturized electronic devices is reshaping the requirements for effective electromagnetic interference management. Parker Hannifin Corporation specializes in high-performance engineered materials for critical aerospace and defense applications. Laird Technologies leverages its expertise in custom solutions for the telecommunications industry. Meanwhile, 3M Company provides a broad portfolio of conductive tapes and absorbers for diverse electronic assemblies.
EMI shielding involves the use of conductive or magnetic materials to create a barrier that blocks electromagnetic fields. These solutions are designed to achieve specific attenuation levels, often measured in decibels, to protect sensitive electronics and ensure signal integrity. Conductive coatings represent a fast-growing product type due to their suitability for complex device housings. The consumer electronics and telecommunications applications remain the largest end-use segments, driven by the proliferation of wireless devices.
Regulatory compliance is a fundamental market requirement, governed by standards like FCC Part 15 in the United States and the EU's EMC Directive. These mandates set strict limits on electromagnetic emissions and immunity for commercial electronics. Consequently, material selection and shielding design must evolve to counter interference from higher frequency bands used in next-generation wireless technologies.
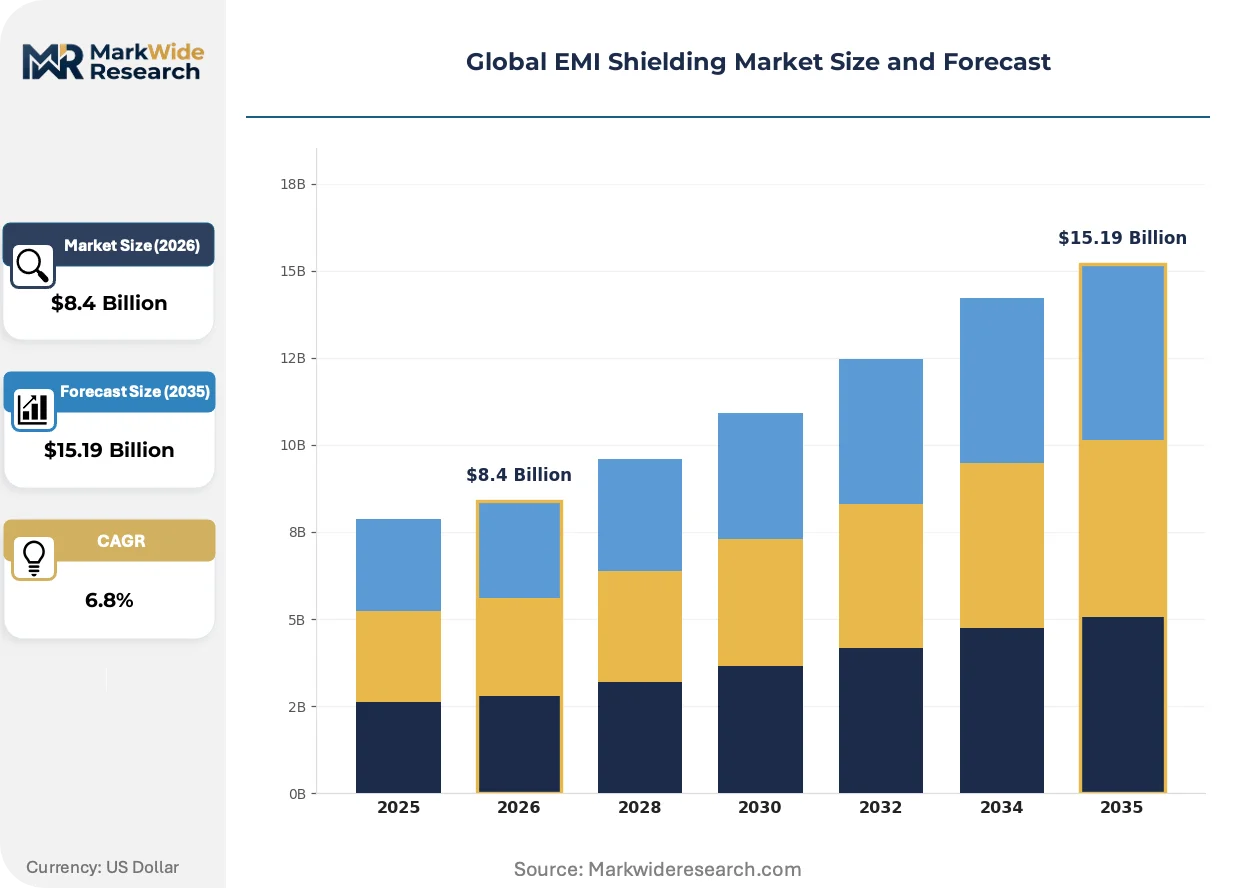
Market Dynamics
The convergence of device miniaturization with the deployment of higher-frequency 5G and emerging 6G networks is the central force defining EMI shielding requirements. This necessitates materials that offer superior attenuation in a smaller, more complex physical footprint.
Growth Catalysts
- 5G and IoT Expansion:The global rollout of 5G infrastructure and the proliferation of Internet of Things devices in industrial and residential settings create a substantial need for shielding to prevent signal interference.
- Regulatory Enforcement:Stricter enforcement of standards like the EU's EMC Directive and the FCC's Part 15 rules compels electronics manufacturers to incorporate effective shielding to achieve market compliance.
- Automotive Electrification:The increasing electronic content in electric vehicles, including battery management systems and advanced driver-assistance systems (ADAS), requires robust shielding to ensure operational safety and reliability.
Market Restraints
- Raw Material Price Volatility:The market is exposed to price fluctuations in key conductive materials like copper, silver, and nickel, which can compress manufacturer margins and impact end-product costs.
- Shielding for Flexible Electronics:Developing effective and durable EMI shielding for flexible and foldable displays presents significant technical hurdles, limiting performance in next-generation form factors.
- Supply Chain Concentration:A high concentration of processing for specific materials, such as certain rare earth elements used in magnetic shielding, within China creates potential supply chain vulnerabilities.
Strategic Opportunities
- Biomedical Device Shielding:An opportunity exists in developing biocompatible shielding for implantable and wearable medical devices, such as pacemakers and insulin pumps, to protect them from external interference.
- Advanced Material Development:Commercializing novel materials like graphene composites and conductive polymers offers the potential for lightweight, transparent, or flexible shielding solutions that outperform traditional metals.
- Aerospace and Defense Modernization:Upgrades to avionics, radar, and military communication systems under frameworks like MIL-STD-461 create demand for high-performance shielding that can withstand harsh environments.
Industry Challenges
- Thermal Management Integration:A primary challenge is designing shielding that effectively blocks EMI without trapping heat, a critical issue in densely packed, high-power electronics that can lead to performance degradation.
- Complex Certification Pathways:Navigating the lengthy and expensive testing processes for multiple jurisdictions, such as obtaining both CE marking for Europe and FCC approval for the US, delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EMI Shielding Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Shielding, Conductive Coatings, Shielding Fabrics, Metal Mesh, Paints Technology: Absorptive Shielding, Reflective Shielding, Magnetic Shielding, Hybrid Shielding Application: Consumer Electronics, Aerospace & Defense, Telecommunications, Industrial Equipment End User: Telecom Operators, Aircraft Manufacturers, Factory Automation Providers, Electronic Device Assemblers |
| Companies Covered | 3M Company, PPG Industries, Parker Hannifin Corporation, Henkel AG & Co. KGaA, Laird Technologies, Tech-Etch, RTP Company, Leader Tech, Schaffner Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EMI Shielding Market Strategic Shifts & Innovations
Innovation in the EMI shielding market is pivoting toward multifunctional materials and digital design workflows. This evolution prioritizes solutions that can be validated early in the product lifecycle and that solve multiple engineering problems simultaneously.
EMI simulation software allows engineers to model and predict electromagnetic interference patterns in a digital environment. The aerospace and automotive sectors are rapidly adopting this technology to de-risk complex electronic system designs. This software is virtualizing the expensive and time-consuming process of building and testing multiple physical prototypes, significantly compressing product development timelines.
China's Ministry of Industry and Information Technology (MIIT) enforces stringent EMC standards for telecommunications hardware and connected devices. These regulations mandate higher attenuation levels and broader frequency band protection, particularly for 5G equipment. The network infrastructure segment is most affected, compelling suppliers to redesign and re-qualify components to access the Chinese market.
A behavioral shift among OEMs is driving demand for shielding solutions that are pre-integrated with other components, such as thermal interfaces or structural gaskets. This change challenges the traditional model of selling discrete shielding products, favoring suppliers capable of co-designing custom modules. This pattern is most pronounced in the consumer electronics vertical for devices like smartphones and wearables.
Global EMI Shielding Market Segmentation
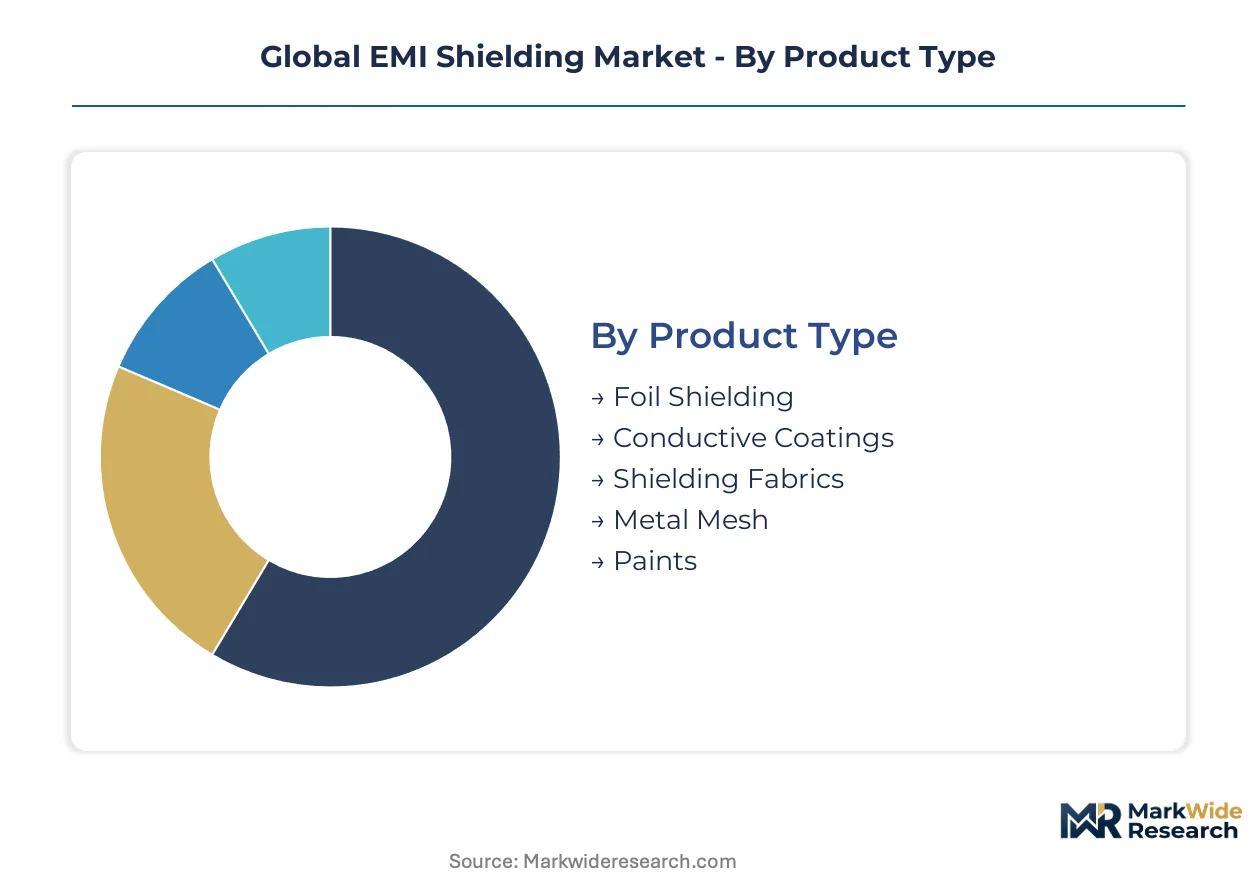
The EMI shielding market's segmentation reflects the diverse technical requirements and application environments across various industries. Understanding these distinct segments is crucial for manufacturers to tailor solutions effectively and for market participants to identify areas of concentrated demand or technological innovation.
Product Type:
The lifecycle of EMI shielding product types varies significantly, with some undergoing rapid innovation cycles while others maintain long-standing performance in established applications.
- Foil Shielding:These materials, typically made from copper, aluminum, or nickel alloys, provide a conductive barrier against electromagnetic interference. Demand for foil shielding remains high in consumer electronics manufacturing in China, driven by cost-effectiveness and ease of application in high-volume production.
- Conductive Coatings:These are paints or sprays containing conductive particles like silver, copper, or nickel, applied directly to device enclosures. Their suitability for complex geometries and lightweight properties makes them attractive for next-generation portable devices and automotive electronic control units.
- Shielding Fabrics:Woven or non-woven textiles impregnated with conductive metals offer flexible and lightweight shielding solutions.
- Metal Mesh:Fine wire mesh, often made from copper or stainless steel, provides transparent shielding for displays and enclosures requiring airflow.
- Paints:Conductive paints offer a cost-effective method for shielding plastic enclosures, particularly in industrial and commercial electronics.
Foil Shielding dominates the installed base across many electronic devices. Conductive Coatings is where expansion concentrates due to its versatility and suitability for miniaturized form factors.
Technology:
Different EMI shielding technologies are engineered to address distinct interference challenges across varied operating environments.
- Reflective Shielding:This common method uses conductive materials to reflect electromagnetic waves away from sensitive components, preventing interference. Reflective shielding is widely adopted in telecommunications equipment in South Korea, where signal integrity is paramount for network performance.
- Hybrid Shielding:These solutions combine multiple shielding principles, such as reflective and absorptive materials, to provide superior performance across a broad frequency spectrum. The complexity of 5G infrastructure in Germany increasingly requires hybrid shielding to manage dense electromagnetic environments.
- Absorptive Shielding:Materials designed to absorb electromagnetic energy convert it into heat, reducing reflections and secondary emissions.
- Magnetic Shielding:This technology uses high-permeability materials to redirect low-frequency magnetic fields, protecting sensitive components like sensors.
Reflective Shielding remains a foundational approach for many applications. Hybrid Shielding solutions are gaining traction for complex, multi-frequency environments.
Application:
Market demand for EMI shielding solutions is heavily influenced by the volume and sophistication of electronic devices within specific application sectors.
- Consumer Electronics:This segment includes smartphones, laptops, wearables, and home appliances, requiring cost-effective and compact shielding solutions. The rapid refresh cycles of consumer devices in Japan drive continuous demand for integrated shielding components.
- Telecommunications:Shielding is critical for base stations, network equipment, and user devices to ensure reliable signal transmission and regulatory compliance. The global rollout of 5G networks, particularly in the United States, necessitates robust shielding for high-frequency components.
- Aerospace & Defense:High-performance shielding protects sensitive avionics, radar systems, and communication equipment from harsh electromagnetic environments.
- Industrial Equipment:EMI shielding safeguards control systems, automation machinery, and medical devices from operational interference.
Consumer Electronics drives the largest volume of shielding material procurement. Aerospace & Defense applications present significant growth potential for high-performance solutions.
End User:
The procurement patterns for EMI shielding vary considerably among different end-user segments, reflecting distinct technical requirements and supply chain structures.
- Electronic Device Assemblers:These companies integrate various components into final products, requiring a wide range of EMI shielding materials for their assembly lines. Assemblers in Taiwan, a hub for electronics manufacturing, frequently specify shielding solutions for diverse product categories.
- Telecom Operators:As owners and operators of communication networks, they specify shielding requirements for network infrastructure and customer premises equipment. Operators in the UK are increasingly demanding advanced shielding to optimize 5G network performance and minimize interference.
- Aircraft Manufacturers:These entities require specialized, high-reliability shielding solutions for critical aerospace systems.
- Factory Automation Providers:Shielding is essential for industrial control systems and robotic equipment to maintain operational integrity in electromagnetically noisy factory environments.
Electronic Device Assemblers exert substantial influence over material specifications and volumes. Telecom Operators are increasingly dictating advanced shielding requirements for network infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for EMI shielding materials concentrates in major electronics manufacturing hubs, driven by the need for high-volume production and stringent regulatory compliance. Electronic device assemblers and telecommunication operators significantly influence material specifications and procurement patterns. This global market reflects diverse regional drivers across key industrial nations.
China
China's extensive consumer electronics manufacturing base and rapid 5G network expansion drive substantial EMI shielding demand. The Ministry of Industry and Information Technology (MIIT) enforces stringent EMC standards for telecommunications hardware. The Yangtze River Delta region, centered around Shanghai, anchors high-volume production of shielded consumer devices.
United States
The United States experiences significant demand from its extensive 5G network rollout and aerospace and defense modernization. FCC Part 15 rules on electronic emissions compel manufacturers to integrate advanced shielding. Silicon Valley in California remains a hub for high-performance shielding solutions for telecommunications and computing devices.
Germany
Germany's robust automotive electrification initiatives and advanced industrial equipment sectors necessitate high-performance EMI shielding. The EU's EMC Directive mandates strict limits on electromagnetic emissions for critical automotive and industrial control systems. Bavaria, with its strong automotive base, drives demand for robust shielding in advanced driver-assistance systems.
Japan
Japan's rapid refresh cycles in consumer electronics and sophisticated telecommunications infrastructure create continuous demand for integrated shielding. The Ministry of Economy, Trade and Industry (METI) influences industrial standards, impacting component design and shielding. Tokyo's electronics manufacturing sector consistently procures compact and high-performance shielding solutions.
South Korea
South Korea's leadership in advanced telecommunications equipment and high-volume consumer device manufacturing fuels substantial EMI shielding requirements. The Ministry of Food and Drug Safety (MFDS) sets standards for medical devices, impacting specialized shielding. The Seoul Capital Area concentrates on developing reflective shielding solutions for next-generation 5G consumer electronics.
Global EMI Shielding Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for EMI shielding solutions. The market exhibits a mix of large, diversified material science companies and specialized manufacturers focused on specific shielding technologies. Strategic archetypes include integrated material suppliers, custom solution providers, and niche component fabricators. Companies prioritize strategic partnerships for technology co-development and portfolio diversification to address evolving application requirements across industries.
Integrated material science companies, such as 3M Company, offer a broad portfolio of conductive tapes and absorbers, serving diverse electronic assemblies. Meanwhile, Parker Hannifin Corporation exemplifies suppliers specializing in high-performance engineered materials, particularly for critical aerospace and defense applications. Laird Technologies occupies a position among custom solution providers, leveraging expertise in tailored shielding for the telecommunications industry. These entities anchor different segments of the value chain, from raw material conversion to application-specific component delivery, defining competitive dynamics.
| Leading Market Players |
|---|
| 3M Company |
| PPG Industries |
| Parker Hannifin Corporation |
| Henkel AG & Co. KGaA |
| Laird Technologies |
| Tech-Etch |
| RTP Company |
| Leader Tech |
| Schaffner Holding AG |
| Others |
Cost & Logistics Intelligence
China's centralized processing of specific conductive materials, like rare earth elements for magnetic shielding, directly influences global pricing and margin distribution across the EMI shielding value chain.
Pricing Analysis
Cost-plus contracts with raw material indexation are common for high-volume EMI shielding components. Price differentiation stems from the material's attenuation performance, measured in decibels, and the certification level required for aerospace or medical applications. Pricing softness reflects intense competition in the consumer electronics segment, driven by high-volume manufacturing in Asia. Electronic device assemblers are highly price-sensitive, while aerospace and defense contractors prioritize performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities frequently support the procurement of EMI shielding materials. Geographic supply concentration for key inputs, such as copper and nickel, centers on China, Chile, and Indonesia. The market's raw material dependencies include conductive metals and specialized polymers. Single-source vulnerability for specific rare earth elements in magnetic shielding presents a structural risk. Distribution runs through a network of specialized material distributors and direct sales to large OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMI shielding market is experiencing a significant buyer-power shift, driven by consolidation among telecommunications operators and large electronics manufacturers.
For Market Incumbents: Entrench core market share by investing in advanced material R&D for graphene composites and conductive polymers, crucial for next-generation devices. Deepen vertical integration into specialized coating application services to counter margin pressure from commoditized foil products. Secure long-term supply agreements for critical raw materials to mitigate price volatility. Focus on expanding high-performance shielding solutions for aerospace and defense modernization, a segment less susceptible to rapid technological obsolescence.
For New Entrants and Emerging Players: Establish a beachhead in niche applications like biomedical device shielding, targeting biocompatible and flexible solutions. The medical device segment offers a penetrable entry point due to specialized regulatory requirements and lower volume production. Develop simulation software tools to offer co-design services, providing a value-added go-to-market angle that reduces OEM development cycles. Focus on innovative manufacturing processes for flexible electronics, addressing a current technical hurdle.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science companies possessing proprietary advanced shielding technologies. These firms often hold patents for novel conductive coatings or hybrid shielding solutions that cater to 5G and 6G frequency bands. The long-term viability of the market is strong, driven by persistent regulatory enforcement and device miniaturization trends. A signal to watch is the increasing adoption of pre-integrated shielding modules in high-volume consumer electronics, indicating a shift towards system-level solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Graphene Composite Development | Creates lightweight, transparent shielding for next-generation flexible displays in consumer electronics. |
| Expand Conductive Coating Application Services | Captures higher value in custom solutions for complex device geometries in automotive ECUs. |
| Secure Long-Term Raw Material Contracts | Mitigates price volatility of copper and silver, stabilizing production costs for manufacturers. |
| Develop EMI Simulation Software Tools | Accelerates product development cycles for OEMs by de-risking complex electronic designs. |
| Target Biocompatible Shielding for Medical Devices | Addresses a specialized demand for implantable devices, ensuring operational safety and reliability. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research validation. Primary data involved conversations with R&D directors, procurement managers, regulatory affairs specialists, and product engineers across telecommunications, automotive, and consumer electronics sectors. Secondary sources included technical journals, patent databases, government regulations from the FCC and MIIT, and company annual reports, triangulated to ensure data accuracy and breadth.
Forecast inputs considered the market's segmentation across product types like foil shielding and conductive coatings, technologies such as reflective and hybrid shielding, and end-use applications including consumer electronics and aerospace. The analytical framework modeled volume and value projections across the analysis window, deriving compound annual growth rates from historical trends and anticipated technological shifts. Key industry-specific forecast inputs included 5G infrastructure deployment rates and electric vehicle production forecasts.
Sensitivities concentrate around shifts in raw material prices and the pace of regulatory enforcement for electromagnetic compatibility. Forecasts reflect assumptions regarding technological advancements and market adoption rates for next-generation devices. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market