
 Coaxial Connectors (RF) Market | 2026-2036
Coaxial Connectors (RF) Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Connectors (RF) Market Insights
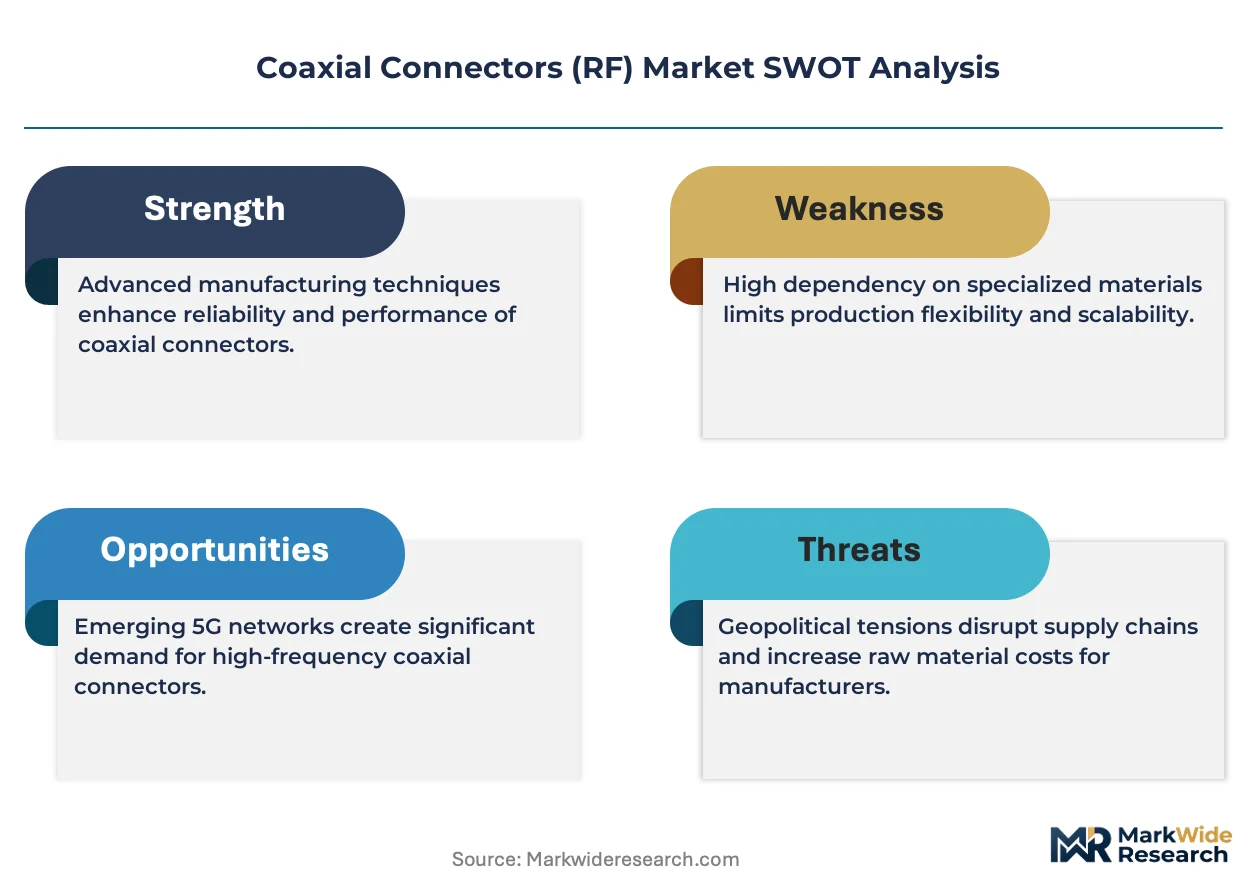
The performance gap between premium and commodity coaxial connectors is shifting from a cost distinction to a reliability threshold governed by insertion loss and voltage standing wave ratio tolerances. Amphenol RF leverages vertical integration across precision machining and plating operations to sustain margin pools in aerospace-qualified product lines. TE Connectivity anchors its position through backward integration into dielectric materials and cable assembly pairing, while Rosenberger competes by dominating European automotive radar connector specifications.
Coaxial connectors (RF) are electromechanical interfaces designed to transmit radio-frequency signals with controlled impedance, typically 50 or 75 ohms, using a central conductor separated from an outer shield by a dielectric layer. These components maintain signal integrity across microwave and millimeter-wave bands in telecommunications infrastructure, defense electronics, and test instrumentation. The high-frequency product category leads absolute value contribution as 5G mmWave and satellite communications push operating bands past 40 GHz. Low-loss variants represent the fastest-expanding margin pool because base station densification and phased-array antennas demand minimized attenuation per connection point.
The FCC in the United States enforces electromagnetic compatibility and spectrum efficiency rules that mandate connector performance at designated frequency bands, directly shaping procurement specifications for telecom providers. ETSI in Europe and China's MIIT impose analogous type-approval frameworks that restrict market access to certified interface designs. Defense agencies including the U.S. Department of Defense and NATO member procurement offices layer MIL-STD-348 and MIL-PRF-39012 requirements atop commercial standards, creating a dual-compliance burden for suppliers. Stakeholders must monitor whether spectrum auctions in additional countries expand the addressable market for high-frequency interconnects or fragment certification requirements across incompatible national standards.
Market Dynamics
Defense procurement cycles and spectrum reallocation mandates are compressing supplier qualification timelines while fragmenting certification requirements across incompatible national standards. This structural tension forces manufacturers to maintain parallel compliance architectures for commercial and military-qualified product lines.
Growth Catalysts
- 5G mmWave densification:Base station deployment in China and India requires precision RF interfaces operating above 24 GHz, pulling demand for low-loss variants with sub-0.1 dB insertion loss specifications.
- FCC spectrum reallocation:Mandates in the United States compel telecom providers to upgrade legacy infrastructure, accelerating replacement cycles for sub-6 GHz and mmWave-compatible connector systems.
- Satellite ground station builds:Commercial and defense constellations in low-Earth orbit drive procurement of hermetic, radiation-tolerant interconnects for gateway facilities across Australia, Chile, and Norway.
Market Restraints
- Silver and palladium price volatility:Electroplating chemistry for corrosion-resistant contacts exposes margins to precious metals market swings, particularly affecting aerospace-qualified product lines.
- Dielectric material concentration:PTFE and fluoropolymer supply chains concentrate among Japanese and German specialty chemical producers, creating single-source vulnerability for high-frequency variants.
- MIL-STD-348 dual-compliance burden:Defense agencies require suppliers to maintain separate production lines and test protocols atop commercial standards, elevating fixed costs for mid-tier manufacturers.
Strategic Opportunities
- Indian telecom infrastructure:Reliance Jio and Bharti Airtel's 5G rollout creates demand for cost-optimized RF interfaces that bridge performance gaps between commodity and premium tiers.
- Automotive radar convergence:77-81 GHz antenna modules for advanced driver-assistance systems require miniaturized board-to-board connectors with controlled impedance tolerances.
- EU Green Deal material mandates:REACH restrictions on per- and polyfluoroalkyl substances incentivize development of bio-based dielectric formulations with comparable dielectric constant stability.
Industry Challenges
- Millimeter-wave test technician scarcity:Vector network analyzer operation and calibration expertise concentrates among defense contractors and Tier-1 suppliers, constraining quality assurance scaling.
- Interoperability with legacy 50-ohm systems:Backward compatibility requirements for existing telecom infrastructure complicate migration to 75-ohm optimized designs for broadcast applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Connectors (RF) Market |
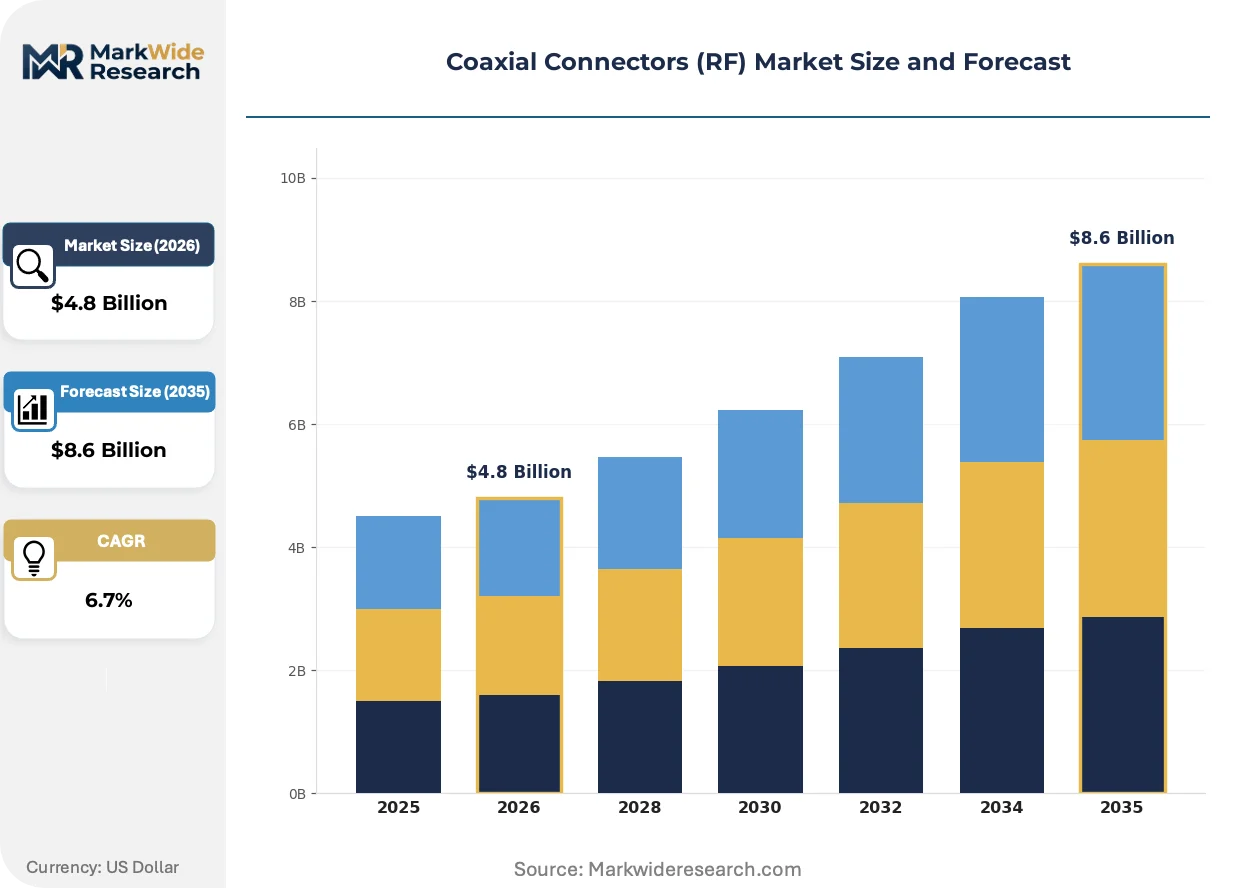
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Low Loss, High Frequency, Reverse Polarity Application: Telecommunications, Internet of Things, Broadcasting, Aerospace Installation: Indoor, Outdoor, Fixed, Mobile End User: Telecom Providers, Broadcasting Companies, Defense Agencies, Automotive Manufacturers |
| Companies Covered | Amphenol RF, TE Connectivity, HUBER+SUHNER, Rosenberger, Molex, Radiall, Hirose Electric, Samtec, Smiths Interconnect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Connectors (RF) Market Trends and Innovations
Miniaturization pressures and operating frequency escalation are converging to redefine interface geometries and material stacks. Suppliers now compete on simulation-to-production velocity rather than catalog breadth alone.
Glass-reinforced liquid crystal polymer dielectrics are expanding into board-level RF modules where thermal cycling resistance and dimensional stability outweigh cost premiums. Automotive radar suppliers in Germany and Japan adopt these materials for 79 GHz antenna-in-package designs. The technology is expanding into satellite payload applications where outgassing constraints previously limited polymer selection.
ETSI's harmonized standards for 5G backhaul equipment mandate electromagnetic compatibility testing at extended temperature ranges, forcing connector redesigns for outdoor cabinet deployments. Equipment vendors in Sweden and Finland must now qualify interfaces across -40°C to +85°C operational windows. The policy compresses time-to-market for European suppliers while creating compliance barriers for non-certified imports.
Defense procurement offices now unbundle connector supply from integrated cable assembly contracts, enabling direct sourcing of qualified interfaces by subsystem integrators. This disintermediation shifts specification authority from prime contractors to module designers in the United States and United Kingdom. The pattern is most visible in electronic warfare and signals intelligence programs where rapid technology refresh cycles conflict with traditional bundled procurement timelines.
Coaxial Connectors (RF) Market Segmentation
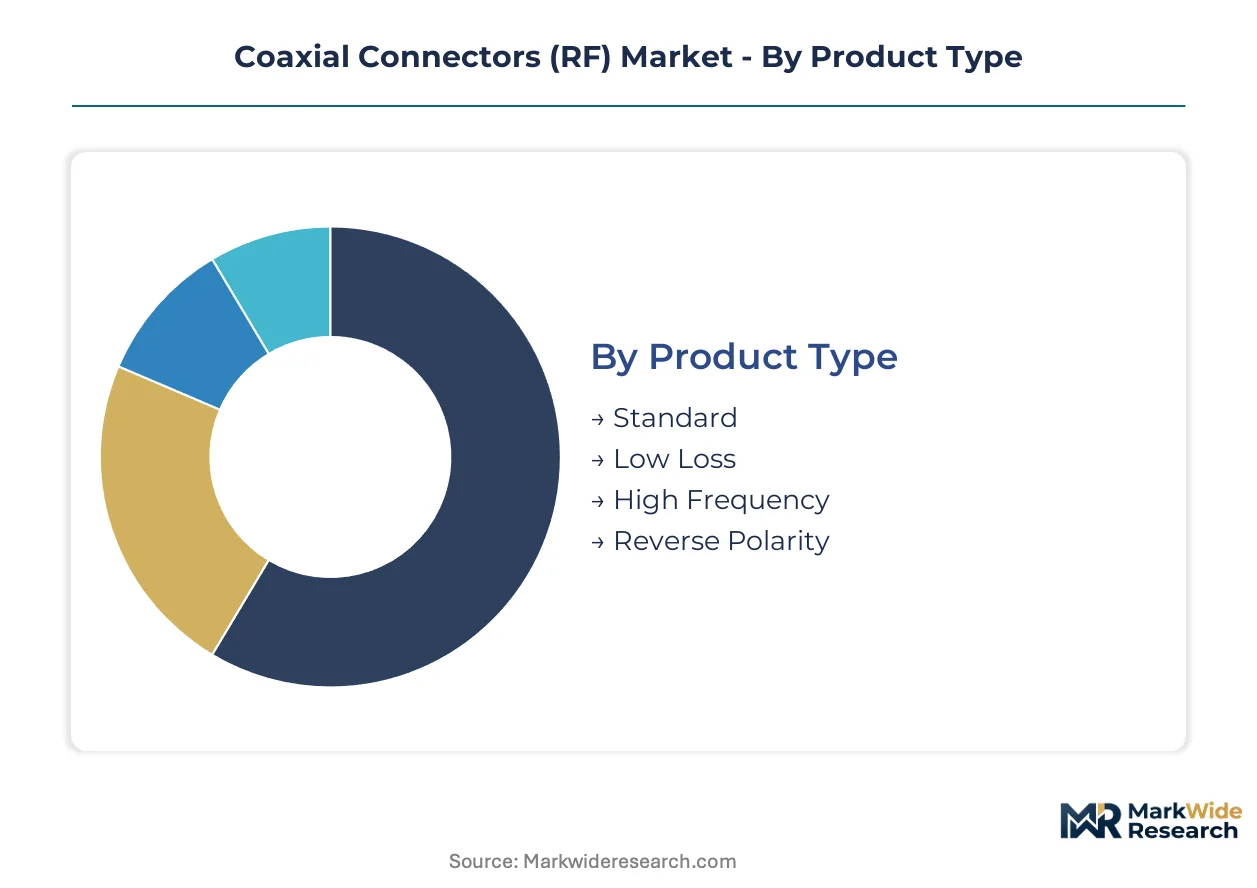
Coaxial connector segmentation maps directly to certification burdens, with MIL-STD-348 governing defense-qualified variants and FCC Part 15 shaping commercial telecom procurement. Each dimension carries distinct margin structures and qualification timelines that determine supplier positioning.
Product Type:
High-frequency variants demand MIL-PRF-39012 or ETSI EN 302 567 certification depending on defense versus commercial end-use, while standard products face lighter type-approval requirements.
- High Frequency:Precision interfaces engineered for millimeter-wave bands above 40 GHz with sub-0.1 dB insertion loss tolerances. Chinese 5G base station densification and satellite ground station builds in Australia and Chile concentrate procurement of these hermetic, radiation-tolerant designs.
- Low Loss:Dielectric-optimized connectors minimizing attenuation per connection point through advanced PTFE or fluoropolymer formulations. Phased-array antenna deployment for defense radar and commercial satellite communications in Norway and the United States drives qualification volumes.
- Standard:General-purpose 50-ohm interfaces for sub-6 GHz infrastructure with commercial-grade plating specifications.
- Reverse Polarity:Mechanically keyed variants preventing mismating in dense RF environments, common in Wi-Fi access point manufacturing.
Standard connectors sit at the top of the volume ranking, with low loss variants climbing the fastest.
Application:
Margin concentration varies sharply by application, with aerospace programs commanding 3-5x commercial telecom pricing due to dual-compliance architectures and extended qualification cycles.
- Telecommunications:Infrastructure-grade connectors for cellular base stations, fiber-to-the-antenna links, and backhaul equipment. India's Reliance Jio and Bharti Airtel 5G rollout generates demand for cost-optimized interfaces bridging commodity and premium performance tiers.
- Aerospace:Hermetic, vibration-resistant interconnects for satellite payloads, electronic warfare systems, and avionics with MIL-STD-348 and MIL-PRF-39012 certification. U.S. Department of Defense and NATO procurement offices now unbundle connector supply from integrated cable assembly contracts.
- Internet of Things:Miniaturized board-to-board connectors for sensor networks and industrial automation with relaxed environmental specifications.
- Broadcasting:75-ohm optimized designs for terrestrial and satellite content distribution, constrained by backward compatibility requirements with legacy 50-ohm infrastructure.
Telecommunications captures the largest absolute revenue pool, though aerospace exhibits the steepest expansion trajectory.
Installation:
Environmental exposure ratings determine IP classification requirements and material stack selection, with outdoor variants demanding extended temperature range qualification per ETSI harmonized standards.
- Outdoor:Weatherproof connectors with -40°C to +85°C operational windows for cell tower and satellite gateway deployments. Swedish and Finnish equipment vendors must qualify these interfaces under ETSI's electromagnetic compatibility mandates for 5G backhaul.
- Mobile:Vibration-resistant designs for tactical communications, unmanned platforms, and portable test instrumentation with rapid-deployment requirements.
- Indoor:Climate-controlled environment connectors with standard IP ratings for data center and laboratory applications.
- Fixed:Permanent-installation interfaces for broadcast transmission facilities and ground station infrastructure with 20-year service life specifications.
Outdoor installations dominate procurement volumes, while mobile configurations gain share fastest.
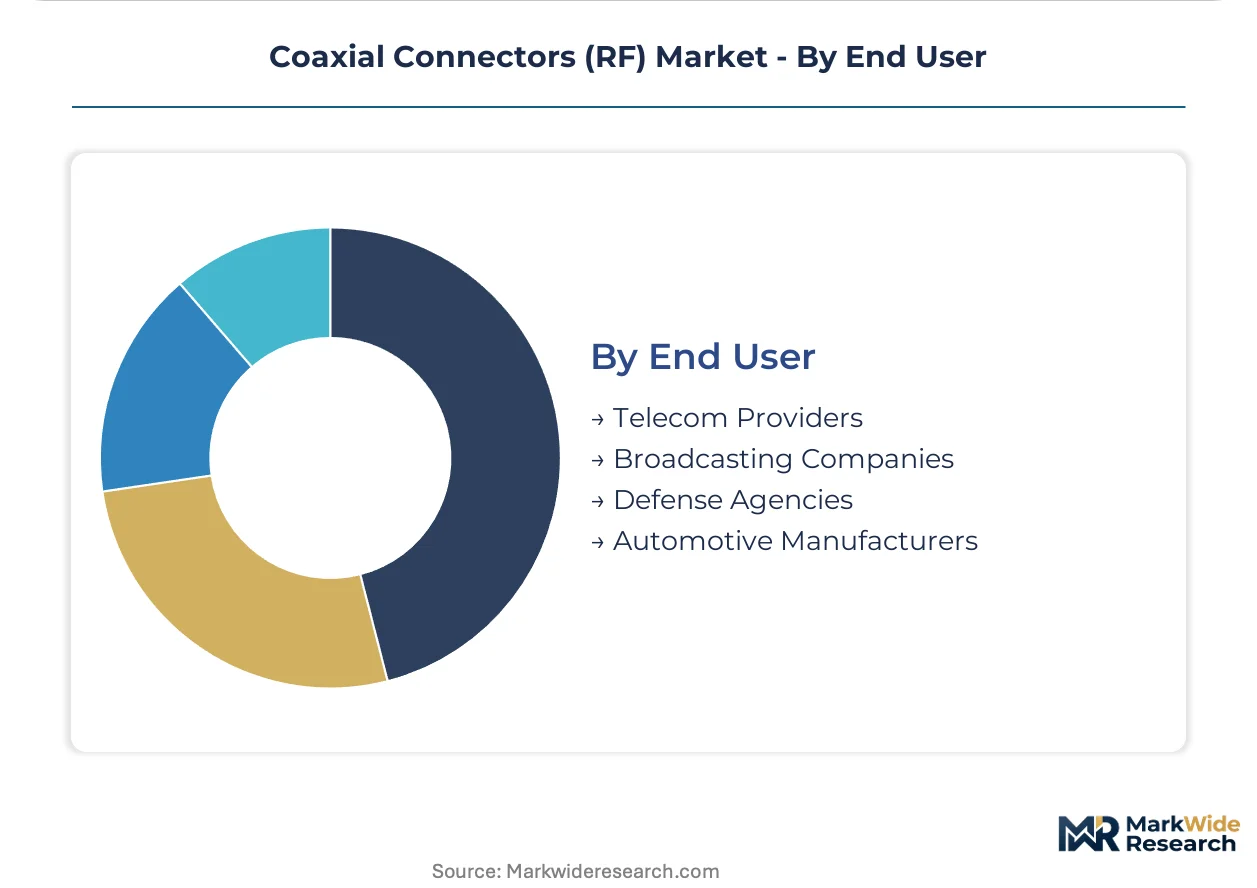
End User:
Defense agencies impose the most stringent qualification protocols, requiring separate production lines and test protocols that elevate fixed costs for mid-tier suppliers serving multiple customer types.
- Defense Agencies:U.S. Department of Defense and NATO member procurement offices specifying MIL-STD-348 and MIL-PRF-39012 qualified interconnects for secure communications, electronic warfare, and signals intelligence programs. Direct sourcing by subsystem integrators is displacing traditional bundled procurement.
- Telecom Providers:FCC-mandated spectrum reallocation in the United States compels upgrade cycles for legacy infrastructure, accelerating replacement of sub-6 GHz and mmWave-compatible connector systems.
- Broadcasting Companies:Content distributors requiring 75-ohm impedance matching for satellite downlink and terrestrial transmission with minimal signal degradation.
- Automotive Manufacturers:German and Japanese radar module suppliers specifying 77-81 GHz miniaturized board-to-board connectors with controlled impedance tolerances for advanced driver-assistance systems.
Telecom providers represent the largest addressable base, with automotive manufacturers expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest procurement volumes for precision RF interfaces, while India generates the fastest qualification cycles for cost-optimized variants bridging commodity and premium tiers.
United States
The FCC's spectrum reallocation mandates compel telecom providers to upgrade legacy infrastructure with sub-6 GHz and mmWave-compatible connector systems. Defense agencies including the U.S. Department of Defense impose MIL-STD-348 and MIL-PRF-39012 requirements atop commercial standards, creating dual-compliance architectures. Subsystem integrators in the Greater Boston and Pacific Northwest clusters now source qualified interfaces directly rather than through bundled cable assembly contracts.
China
MIIT type-approval frameworks restrict market access to certified interface designs for 5G base station densification and satellite ground station builds. The MIIT governs electromagnetic compatibility and spectrum efficiency rules that shape procurement specifications for domestic telecom providers. Yangtze River Delta manufacturers concentrate production of hermetic, radiation-tolerant interconnects for low-Earth orbit gateway facilities.
Germany
Automotive radar module suppliers specify 77-81 GHz miniaturized board-to-board connectors with controlled impedance tolerances for advanced driver-assistance systems. ETSI harmonized standards mandate electromagnetic compatibility testing at extended temperature ranges for 5G backhaul equipment. Bavaria-based fabricators qualify interfaces across -40°C to +85°C operational windows for outdoor cabinet deployments.
India
Reliance Jio and Bharti Airtel's 5G rollout creates demand for cost-optimized RF interfaces that bridge performance gaps between commodity and premium tiers. TRAI spectrum auction frameworks shape procurement timelines for telecom infrastructure upgrades. Maharashtra and Karnataka clusters concentrate qualification volumes for phased-array antenna deployment in defense radar applications.
Sweden
Equipment vendors must qualify outdoor connectors under ETSI's electromagnetic compatibility mandates for 5G backhaul, compressing time-to-market for European suppliers. The EU Green Deal REACH restrictions on per- and polyfluoroalkyl substances incentivize development of bio-based dielectric formulations. Stockholm-based subsystem designers source qualified interfaces directly for electronic warfare and signals intelligence programs.
Coaxial Connectors (RF) Market Competitive Landscape
Top-tier vendors anchor premium-tier certification pools, while mid-tier specialists occupy cost-optimized segments serving regional telecom rollouts. The vendor base stratifies across three archetypes: vertically integrated precision machiners, dielectric material backward integrators, and specification-dominant automotive radar specialists. Consolidation pressure intensifies as defense procurement offices unbundle connector supply from integrated cable assembly contracts. Competitive moves center on parallel compliance architectures for commercial and military-qualified product lines, alongside simulation-to-production velocity investments.
Among U.S.-based interconnect specialists, Amphenol RF and TE Connectivity exemplify tier-one positioning through captive supply of precision machining and dielectric materials respectively. Rosenberger occupies a position within the European automotive radar specification tier. These three anchors represent distinct strategic archetypes: vertical integration across plating operations, backward integration into cable assembly pairing, and dominance of regional automotive connector standards.
| Leading Market Players |
|---|
| Amphenol RF |
| TE Connectivity |
| HUBER+SUHNER |
| Rosenberger |
| Molex |
| Radiall |
| Hirose Electric |
| Samtec |
| Smiths Interconnect |
| Others |
Pricing and Supply Chain Analysis
Vector network analyzer calibration specialists in the Greater Boston cluster command wage premiums that compress margin spreads between aerospace-qualified and commercial-grade connector tiers. Labor-cost differentials between defense-hub engineering centers and Asian manufacturing zones amplify pricing stratification across certification levels.
Pricing Analysis
Bundled cable assembly contracts are fragmenting into direct component sourcing, forcing suppliers to unbundle pricing for connectors separately from installation services. Pricing stratifies across MIL-PRF-39012 certified, ETSI-compliant, and standard commercial tiers, with certification level and precious metals plating content as primary differentiation drivers. Cost compression in standard-grade products is intensifying because Chinese base station manufacturers consolidate procurement volumes. Telecom providers in India exhibit highest price sensitivity, while U.S. defense agencies prioritize reliability over unit cost.
Supply Chain Analysis
Freight cost volatility for precision-machined brass and beryllium copper components from Germany and Japan elevates landed costs for North American fabricators. Manufacturing concentrates in China, Germany, and the United States, with PTFE dielectric formulations drawing from Japanese and German specialty chemical producers. Single-source vulnerability for fluoropolymer resins creates qualification bottlenecks when supply disruptions hit. Distribution runs through authorized distributors for defense-qualified lines and direct OEM contracts for telecom infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in low-loss variants where dielectric material innovation permits premium positioning against commodity competition. Unbundling of connector supply from cable assemblies shifts specification authority toward subsystem designers willing to pay for qualification velocity.
For Market Incumbents: To counter direct-sourcing disintermediation by defense subsystem integrators, anchor position through captive certification laboratories that compress MIL-STD-348 qualification timelines. Deepen upstream control over precision plating chemistry to buffer silver and palladium price swings affecting aerospace product lines. For New Entrants and Emerging Players: Capture cost-optimized RF interface demand in India's 5G rollout by bridging performance gaps between commodity and premium tiers through TRAI-compliant designs. Target automotive radar module suppliers in Germany with 79 GHz miniaturized board-to-board connectors qualified to ETSI temperature-range specifications. For Investors and Strategic Acquirers: Defense prime contractors are the most active acquirer in this space, seeking qualified interface suppliers to rebuild bundled offering margins. Over the medium-term horizon, prioritize targets with parallel MIL-STD-348 and commercial certification architectures. Watch for FCC spectrum auction announcements as volume inflection signals for high-frequency interconnect procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Certification Architecture Investment | Dual MIL-STD-348 and ETSI compliance accelerates defense and telecom qualification velocity simultaneously. |
| Dielectric Material Backward Integration | In-house PTFE formulation development buffers Japanese and German supply concentration risks. |
| Precision Plating Chemistry Captive Supply | Internal electroplating operations insulate margins from silver and palladium commodity volatility. |
| Simulation-to-Production Velocity Investment | Reduced design iteration cycles attract automotive radar suppliers with compressed time-to-market requirements. |
| Direct Subsystem Integrator Channel Buildout | Bypassing traditional prime contractor bundling captures specification authority in U.S. and U.K. defense programs. |
Research Methodology
Multiple input streams — procurement officer interviews at defense agencies, technical director discussions at telecom equipment vendors, and supply chain manager conversations at connector distributors — were reconciled against secondary validation. Primary fieldwork engaged RF test engineers, dielectric materials specialists, and MIL-STD-348 compliance auditors. Secondary sources included FCC spectrum allocation filings, ETSI harmonized standard publications, MIIT type-approval registries, and customs trade data for precious metals plating inputs. Bottom-up connector shipment estimates were triangulated against top-down infrastructure capex allocations.
Historical qualification cycle data was cross-referenced against panel input from subsystem integrators regarding procurement timeline compression. The analytical framework segmented volume and value across product type, application, installation environment, and end-user category throughout the forecast period. CAGRs were derived from infrastructure deployment schedules for 5G mmWave densification and low-Earth orbit satellite constellations. Modeled inputs included TRAI spectrum auction timelines, Reliance Jio and Bharti Airtel base station rollout commitments, and EU Green Deal REACH restriction implementation trajectories.
Underlying measurement precision varies by segment; telecommunications and automotive applications carry tighter precision than aerospace programs where classification limits data availability. Forecasts reflect assumptions regarding spectrum reallocation pacing, precious metals price stability, and dielectric material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Small Signal Mosfets Market
RF Components
Radio Frequency Counter Market
RF Components
Radio Frequency Front End Module Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
LTCC Power Dividers Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Europe Small Signal Transistor Market
RF Components
Japan Small Signal Transistor Market
RF Components
Gaas RF Switch Market
RF Components
Toroid Inductor Market
RF Components
RF Microwave MLCC Market
RF Components
High Reliability Oscillators Market
RF Components
Radio Frequency Duplexer Market
RF Components
Latin America RFID Tags Market
RF Components
RF Gan Market