
 Gan RF Semiconductor Devices Market | 2026-2036
Gan RF Semiconductor Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Gan RF Semiconductor Devices Market Analysis
Defense electronics procurement is broadening the end-use vertical mix for GaN RF devices, pulling capacity away from legacy telecommunications basestation deployments. Wolfspeed, Inc. leverages its vertically integrated SiC and GaN substrate operations to dominate North American defense supply chains. Qorvo, Inc. sustains competitive positioning through specialized GaN-on-SiC foundry services for phased-array radar modules. Sumitomo Electric Device Innovations anchors Asian demand with advanced GaN-on-Sapphire epitaxy for satellite communication terminals.
GaN RF semiconductor devices are wide-bandgap compound semiconductor components fabricated on silicon carbide, sapphire, or silicon substrates, operating at frequencies from L-band through millimeter-wave with power densities exceeding gallium arsenide by five to ten times. Power amplifiers occupy the largest revenue pool due to basestation and radar transmit requirements, while low noise amplifiers capture premium margins in aerospace receiver chains where thermal noise coefficients determine system performance. GaN-on-SiC technology leads in high-power military and telecommunications applications, whereas GaN-on-Si variants compete on cost in emerging consumer electronics and automotive radar segments.
The FCC enforces stringent out-of-band emission standards that compel GaN RF manufacturers to invest in harmonic suppression and linearization circuitry for 5G massive MIMO deployments. The EU AI Act and CE marking directives under the Radio Equipment Directive shape market access by mandating cybersecurity and spectrum efficiency benchmarks for connected infrastructure. Stakeholders must monitor evolving export control classifications for wide-bandgap substrates, as sovereign semiconductor policies in the United States, China, and Germany increasingly restrict cross-border technology transfer.
Market Dynamics
Defense procurement programs are systematically reallocating GaN RF fabrication capacity from commercial telecommunications toward classified radar and electronic warfare platforms, compressing lead times for civilian basestation deployments.
Growth Catalysts
- Defense Modernization Mandates:Pentagon procurement directives prioritize GaN-on-SiC power amplifiers for next-generation active electronically scanned array radar, pulling capacity toward military specifications.
- REACH and RoHS Compliance:European environmental directives phase out legacy gallium arsenide processes containing restricted substances, accelerating substrate migration toward wide-bandgap alternatives.
- Millimeter-Wave Spectrum Allocation:FCC auctions of 24-47 GHz bands for 5G-Advanced deployment drive demand for linearized GaN power amplifiers with superior thermal performance.
Market Restraints
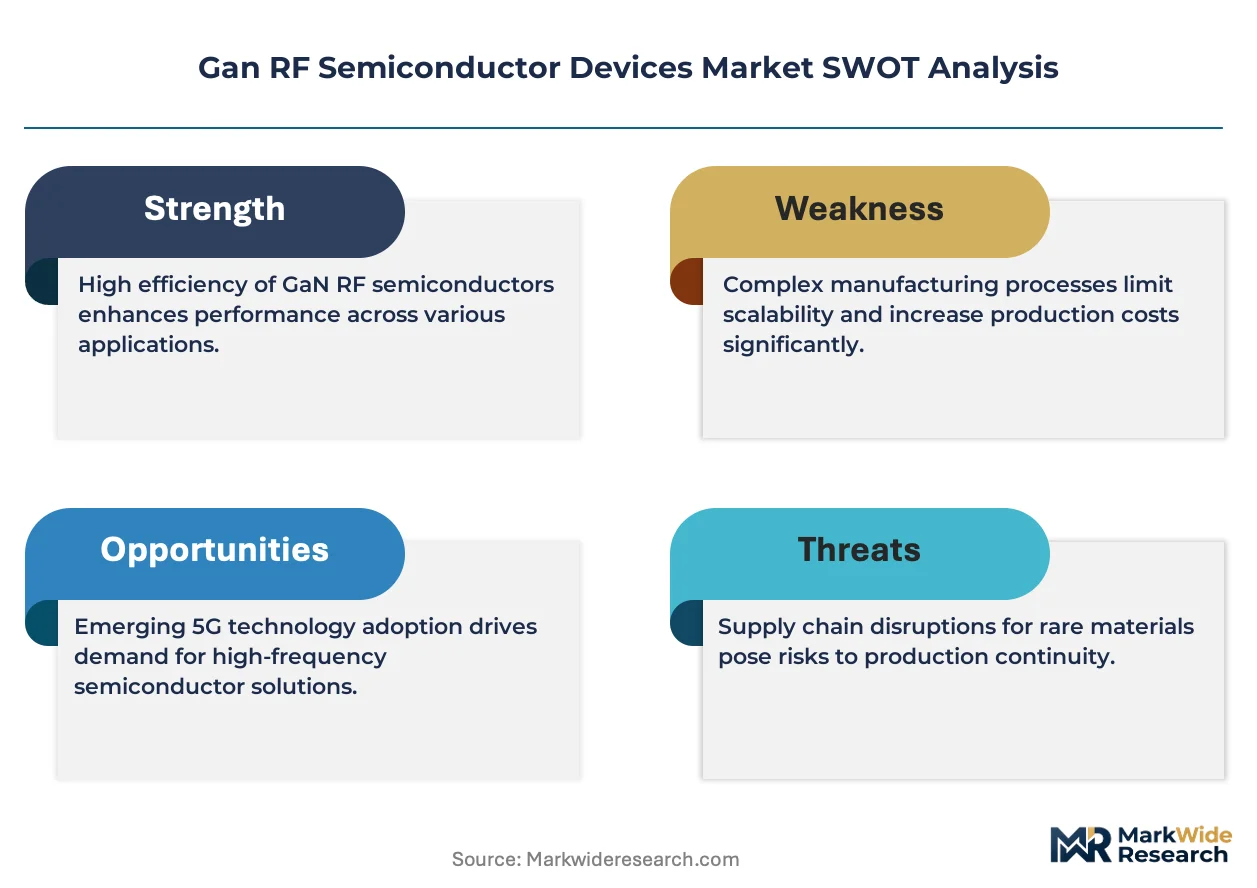
- Substrate Supply Concentration:High-purity silicon carbide wafers concentrate among Japanese and US suppliers, exposing defense contractors to single-source vulnerability for 150mm and 200mm diameters.
- Epitaxy Equipment Lead Times:Metal-organic chemical vapor deposition reactors from German and US equipment vendors face 18-24 month delivery queues, capping foundry expansion velocity.
- GaAs Persistence in Low-Power Segments:Gallium arsenide amplifiers retain cost advantages below 6 GHz for consumer electronics, constraining GaN penetration in price-sensitive handset front-end modules.
Strategic Opportunities
- Automotive Radar Integration:Tier-1 automotive suppliers adopt GaN-on-Si low-noise amplifiers for 77-81 GHz frequency-modulated continuous-wave radar, opening volume production pathways absent in defense-only business models.
- India PLI Scheme Incentives:Production-linked incentive frameworks for compound semiconductors attract substrate and epitaxy investments previously concentrated in East Asian manufacturing clusters.
- Satellite Constellation Density:Low-earth orbit terminal manufacturers specify GaN-on-Sapphire for Ka-band phased arrays, creating demand orthogonal to terrestrial basestation cycles.
Industry Challenges
- Compound Semiconductor Talent Scarcity:Foundries report acute shortages of epitaxial growth engineers and RF device physicists capable of managing defect density in wide-bandgap heterostructures.
- ITAR and EAR Classification Complexity:Dual-use export controls on GaN HEMT power densities above specified thresholds fragment supply chains, requiring country-specific product variants and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan RF Semiconductor Devices Market |
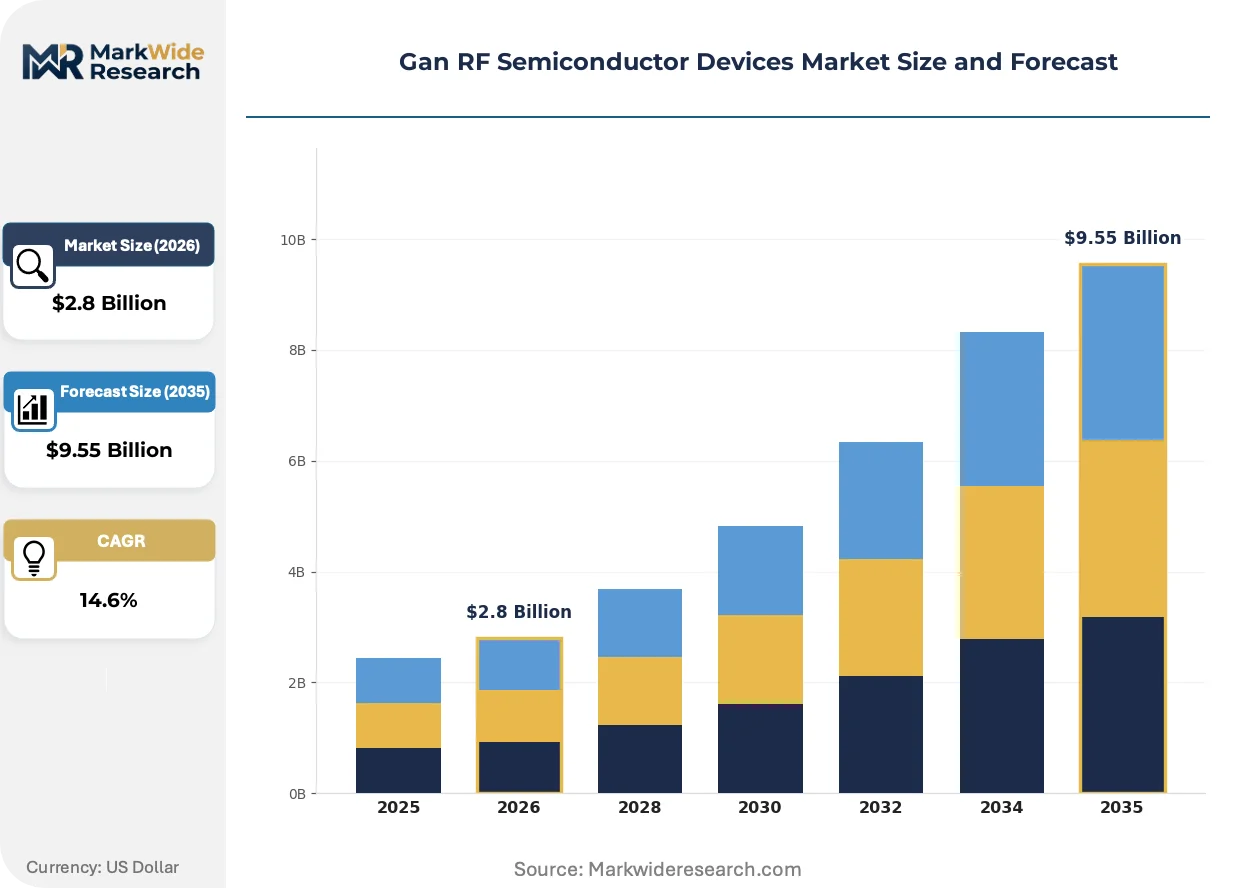
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Amplifiers, Low Noise Amplifiers, Transmitters, Oscillators Technology: GaN-on-Si, GaN-on-Sapphire, GaN-on-GaN, Hybrid End User: Telecommunications, Aerospace, Defense, Consumer Electronics Application: Power Systems, Wireless Communication, Radar Systems, Satellite Communication |
| Companies Covered | Wolfspeed, Inc., Qorvo, Inc., NXP Semiconductors, MACOM Technology Solutions, Sumitomo Electric Device Innovations, Infineon Technologies AG, Analog Devices, Inc., STMicroelectronics, Ampleon Netherlands B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan RF Semiconductor Devices Market Emerging Trajectories
Process integration advances and sovereign capability investments are compressing development cycles for GaN RF devices, while regulatory pressure on spectrum efficiency forces architectural reconsideration of power amplifier linearization.
GaN-on-SiC technology is absorbing the highest-value military and telecommunications applications through its superior thermal conductivity and breakdown voltage characteristics. Prime defense contractors specify this substrate combination for X-band through Ka-band radar transmit chains where power-added efficiency directly determines platform cooling budgets. The technology is absorbing market share previously held by traveling-wave tube amplifiers in satellite uplink terminals, collapsing the addressable space for legacy vacuum electronics.
The EU AI Act imposes cybersecurity and resilience requirements on critical digital infrastructure components, including 5G basestation radio units containing GaN RF front-ends. Equipment vendors must demonstrate supply chain traceability and vulnerability management for wide-bandgap semiconductor sourcing to achieve CE marking under Radio Equipment Directive harmonized standards. German network operators now specify AI Act compliance documentation as a mandatory procurement criterion, filtering qualified supplier pools before technical evaluation begins.
Defense agencies are consolidating GaN RF procurement under long-term strategic supply agreements that guarantee wafer starts in exchange offtake commitments, displacing spot-market purchasing patterns. This contractual evolution compresses pricing transparency and locks capacity years ahead of delivery, forcing commercial telecommunications vendors into secondary allocation queues. The phenomenon is most pronounced in US and UK defense procurement frameworks, where national security waivers override commercial priority scheduling at foundries with dual-use qualifications.
Gan RF Semiconductor Devices Market Segmentation
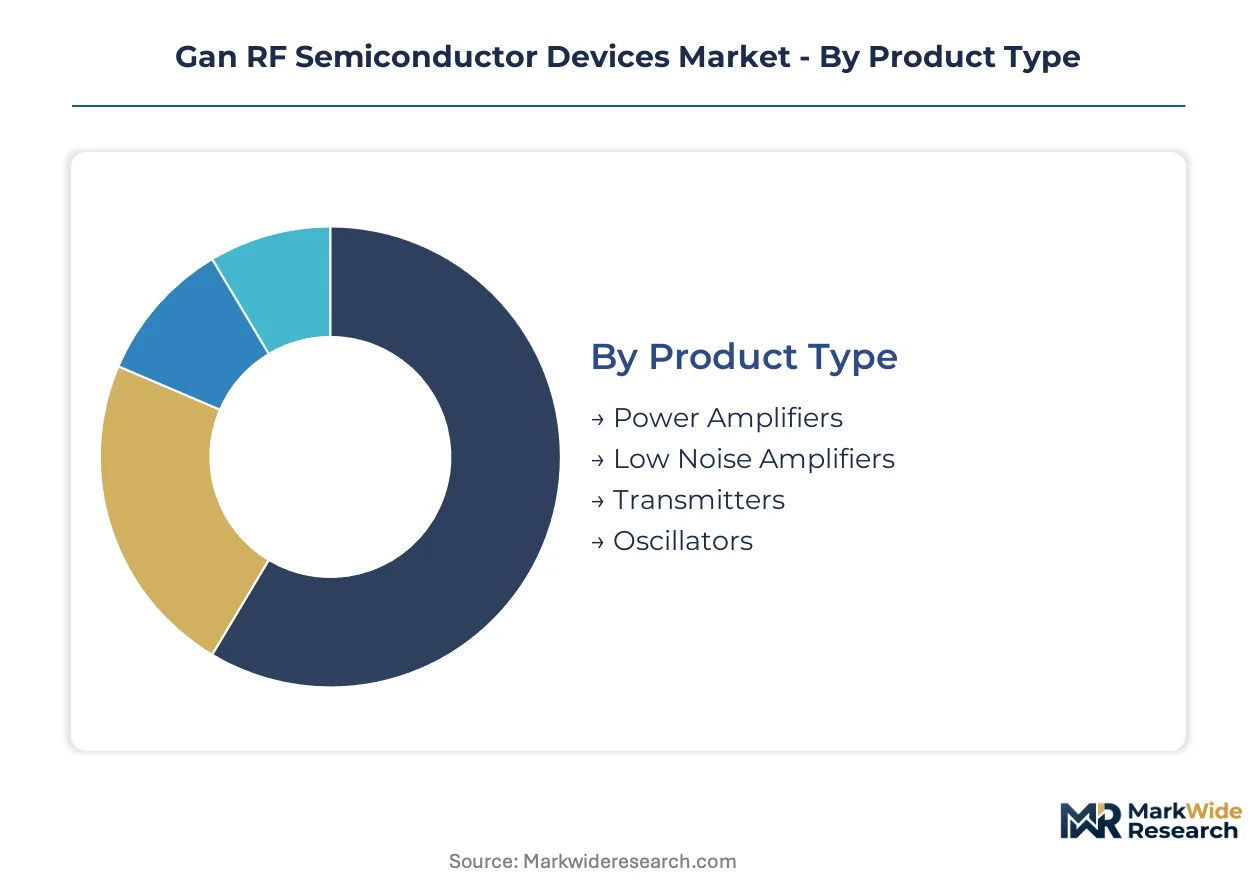
GaN RF semiconductor devices fragment across four critical dimensions that determine foundry allocation, substrate sourcing, and margin capture. Product type and technology choices dictate thermal budgets and frequency ceilings. End-user concentration in defense and aerospace compresses civilian supply availability.
Product Type:
Supply concentration for high-power RF modules tilts heavily toward amplifier categories that absorb the majority of SiC substrate throughput.
- Power Amplifiers:These devices convert DC input to RF output at efficiencies exceeding 60% in L-band through Ka-band operation. Pentagon procurement for active electronically scanned array radar dominates demand, pulling Wolfspeed and Qorvo capacity toward military specifications and away from 5G basestation customers.
- Low Noise Amplifiers:Positioned at receiver chain front-ends, these components amplify weak incoming signals while adding minimal thermal noise. Aerospace terminal manufacturers in Germany and Japan specify these for satellite downlink applications where noise figure below 1 dB determines system viability.
- Transmitters:Integrated modules combining amplification with filtering and switching functions for basestation radio units. FCC out-of-band emission requirements drive harmonic suppression features into these designs.
- Oscillators:Frequency reference components leveraging GaN's low phase noise characteristics for radar local oscillator chains. Defense contractors specify these for electronic warfare platforms requiring rapid frequency hopping.
Power Amplifiers absorb the bulk of installed capacity; Low Noise Amplifiers are expanding most quickly.
Technology:
Substrate selection creates a three-tier cost-performance hierarchy that segments foundry customer bases by thermal budget and frequency requirement.
- GaN-on-SiC:The dominant high-power platform combining gallium nitride epitaxy with silicon carbide's 3.5 W/cm·K thermal conductivity. US and Japanese defense primes specify this exclusively for X-band radar and electronic warfare, consuming the majority of 150mm and 200mm SiC wafer supply.
- GaN-on-Sapphire:Lower thermal conductivity substrate preferred for millimeter-wave applications where cost constraints limit SiC adoption. Ka-band satellite terminal manufacturers specify this for phased-array antennas in low-earth orbit constellations.
- GaN-on-Si:Silicon substrate integration targeting cost-sensitive automotive radar and consumer electronics below 6 GHz. Tier-1 automotive suppliers in Germany evaluate this for 77-81 GHz frequency-modulated continuous-wave radar modules.
- Hybrid:Multi-substrate integration combining GaN power amplification with silicon CMOS control circuitry. Emerging approach for software-defined radio platforms requiring digital predistortion linearization.
GaN-on-SiC commands premium positioning in defense and telecommunications; GaN-on-Si is climbing the fastest as automotive radar volumes materialize.
End User:
Customer concentration patterns reveal a bifurcation between sovereign-funded defense procurement and commercially driven telecommunications deployment.
- Telecommunications:5G-Advanced massive MIMO basestation deployments drive volume demand for linearized power amplifiers. German network operators now require EU AI Act compliance documentation as mandatory procurement criteria.
- Aerospace:Satellite constellation terminal manufacturers specify radiation-hardened GaN devices for geostationary and low-earth orbit applications. Sumitomo Electric anchors Asian demand with GaN-on-Sapphire epitaxy for this segment.
- Defense:Classified radar and electronic warfare programs systematically reallocate foundry capacity through long-term strategic supply agreements. US and UK procurement frameworks lock capacity years ahead of delivery.
- Consumer Electronics:Emerging demand for Wi-Fi 7 front-end modules and handset power amplifiers. GaAs retains cost advantages below 6 GHz, constraining GaN penetration in price-sensitive applications.
Defense absorbs the bulk of high-reliability capacity; Aerospace is gaining share fastest as satellite constellation density accelerates.
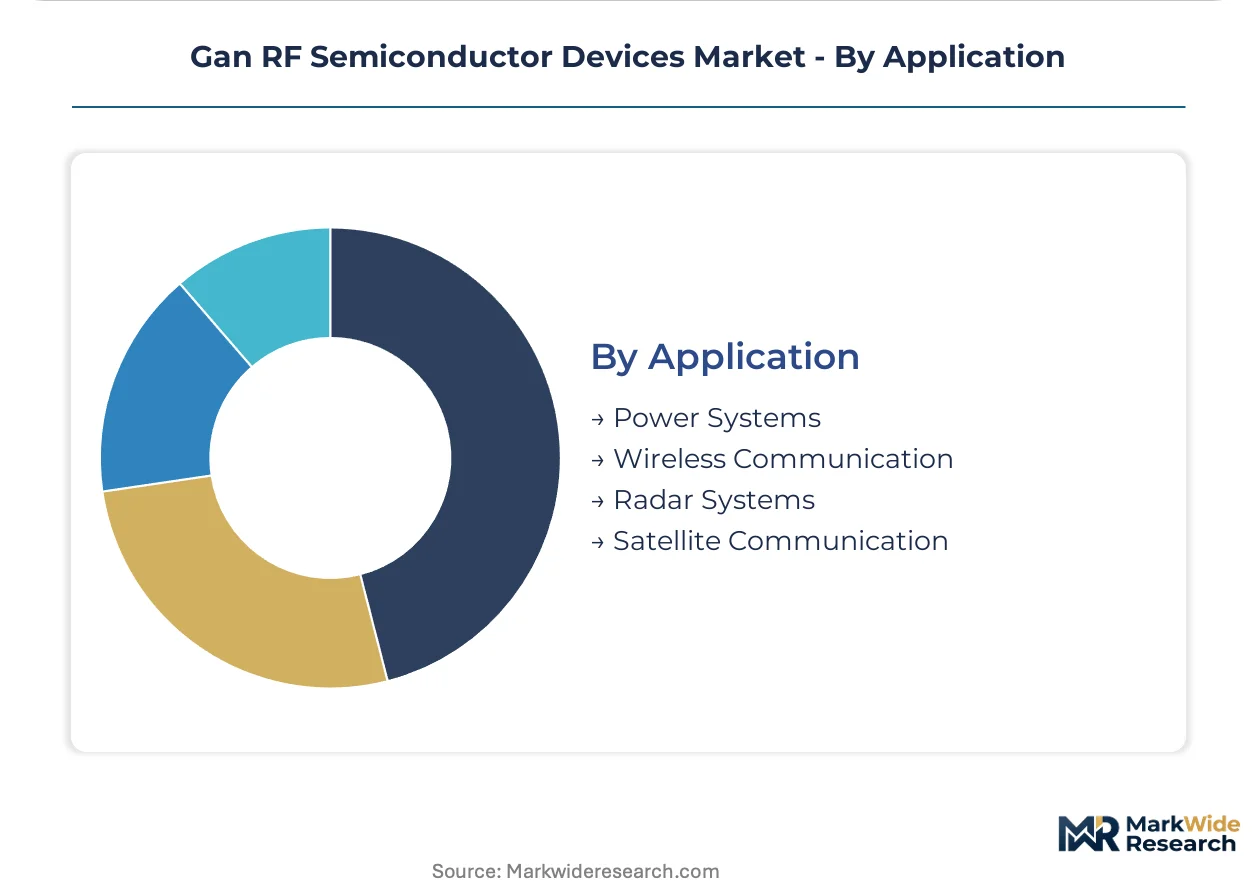
Application:
Functional application requirements determine frequency band, power level, and linearization specifications that cascade through substrate and foundry selection.
- Power Systems:High-voltage switching applications leveraging GaN's breakdown voltage advantages for radar modulators and power converters. Military platforms specify these for reduced thermal management mass.
- Wireless Communication:5G basestation and backhaul infrastructure requiring broadband linearized amplification. FCC 24-47 GHz spectrum auctions drive demand for devices with superior thermal performance.
- Radar Systems:Active electronically scanned array transmit chains demanding high power-added efficiency. Pentagon procurement directives prioritize GaN-on-SiC for next-generation platforms.
- Satellite Communication:Ka-band and Q-band phased arrays for geostationary and low-earth orbit terminals. GaN-on-Sapphire technology addresses this application with cost-thermal tradeoffs distinct from defense radar.
Radar Systems command the majority of defense-qualified foundry output; Satellite Communication is expanding most quickly as constellation deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Malaysia, Vietnam, and the Philippines are attracting compound semiconductor packaging investments previously concentrated in East Asian manufacturing clusters. Sovereign capability programs in the United States, Germany, and China are reshaping substrate supply geography through production-linked incentives and export control frameworks.
United States
Pentagon procurement directives for active electronically scanned array radar dominate GaN-on-SiC demand, pulling fabrication capacity toward military specifications. The FCC enforces stringent out-of-band emission standards that compel harmonic suppression investments for 5G massive MIMO deployments. Defense contractors cluster around Research Triangle Park in North Carolina and the Pacific Northwest, where Wolfspeed anchors vertically integrated substrate production.
China
MIIT spectrum allocations for 5G-Advanced and satellite communication drive domestic demand for millimeter-wave power amplifiers. The country's dual carbon goals accelerate substrate migration away from legacy gallium arsenide processes toward wide-bandgap alternatives. Manufacturing concentrates in the Yangtze River Delta, where state-backed foundries expand 150mm and 200mm silicon carbide wafer capacity under sovereign semiconductor policies.
Germany
Network operators now require EU AI Act compliance documentation as mandatory procurement criteria for 5G basestation radio units. The REACH directive phases out restricted substances in legacy semiconductor processes, accelerating adoption of environmentally compliant wide-bandgap alternatives. Industrial demand clusters in Bavaria and Baden-Württemberg, where automotive Tier-1 suppliers evaluate GaN-on-Si for 77-81 GHz radar modules.
Japan
METI production-linked incentive frameworks attract epitaxy equipment investments previously concentrated in German and US vendor queues. JIS standards for electromagnetic compatibility shape device qualification requirements for telecommunications infrastructure. Substrate supply concentrates among Japanese wafer vendors in Kyushu and the Kansai region, exposing defense contractors to single-source vulnerability for high-purity silicon carbide diameters.
India
The PLI scheme for compound semiconductors draws substrate and epitaxy investments away from East Asian manufacturing clusters. TRAI spectrum allocation timelines for 5G-Advanced drive demand forecasting for linearized power amplifiers. Emerging fabrication capacity clusters in Gujarat and Karnataka target automotive radar and satellite terminal applications orthogonal to terrestrial basestation cycles.
Gan RF Semiconductor Devices Market Vendor Landscape
Top-tier vendors anchor defense-qualified foundry output, while mid-tier specialists occupy automotive and consumer electronics niches with cost-optimized GaN-on-Si platforms. The vendor base stratifies across three tiers: vertically integrated substrate producers commanding premium military specifications, specialized foundry services for phased-array radar modules, and emerging challengers targeting volume automotive radar. Strategic moves concentrate on long-term supply agreements locking capacity years ahead of delivery, and sovereign capability investments securing domestic epitaxy equipment pipelines.
Among North American fabricators, Wolfspeed, Inc. and Qorvo, Inc. occupy positions within the defense-tier archetype, representing vertically integrated and foundry-specialist models respectively. Sumitomo Electric Device Innovations anchors Asian demand from a Japanese base, exemplifying the satellite communication specialist tier with GaN-on-Sapphire capabilities. These three entities represent distinct competitive vectors: captive substrate supply, outsourced foundry services, and millimeter-wave frequency specialization.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Qorvo, Inc. |
| NXP Semiconductors |
| MACOM Technology Solutions |
| Sumitomo Electric Device Innovations |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| STMicroelectronics |
| Ampleon Netherlands B.V. |
| Others |
Supply Flow & Price Mechanics
GaN-on-SiC substrate migration from 150mm to 200mm wafer diameters compresses unit economics while concentrating bargaining power among Japanese and US wafer vendors. Pentagon procurement directives lock fabrication capacity years ahead of delivery, forcing commercial telecommunications buyers into secondary allocation queues with elongated lead-time premiums.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as defense procurement frameworks override commercial priority scheduling at dual-use qualified foundries. Three-tier pricing structure across ITAR-restricted defense grades, CE-marked telecommunications tiers, and unqualified commercial lots reflects certification-driven differentiation. Cost compression in GaN-on-Si automotive radar modules intensifies as Tier-1 suppliers in Germany negotiate volume scale discounts. Consumer electronics manufacturers exhibit highest price sensitivity, while aerospace terminal manufacturers absorb premiums for radiation-hardened specifications.
Supply Chain Analysis
Returns and refurbishment flows for metal-organic chemical vapor deposition reactors create secondary equipment markets as German and US vendors face 18-24 month delivery queues. High-purity silicon carbide substrate supply concentrates in Japan and the United States, with epitaxy equipment sourcing anchored in German and US manufacturing clusters. Gallium metal feedstock draws from Chinese and Kazakh mining operations, exposing foundries to tariff volatility under evolving export control classifications. Distribution runs through defense-qualified prime contractors, telecommunications equipment OEMs, and automotive Tier-1 suppliers with divergent qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal-organic chemical vapor deposition reactor lead times constitute the binding capacity constraint, propping pricing power for substrate vendors with qualified equipment pipelines. Foundries without secured epitaxy equipment slots face effective exclusion from defense procurement frameworks.
For Market Incumbents: To counter foundry capacity reallocation toward classified defense programs, Wolfspeed and Qorvo should deepen backward integration into captive silicon carbide substrate production and secure long-term strategic supply agreements with Pentagon procurement offices. Certification investment in EU AI Act compliance documentation filters German network operator procurement pools before technical evaluation, creating channel control advantages. For New Entrants and Emerging Players: Begin with GaN-on-Si automotive radar modules for 77-81 GHz frequency-modulated continuous-wave applications, where cost-thermal tradeoffs favor silicon substrate integration absent in defense-qualified supply chains. India's PLI scheme for compound semiconductors offers the most penetrable geography for substrate and epitaxy investments previously concentrated in East Asian manufacturing clusters. Direct engagement with Tier-1 automotive suppliers in Bavaria and Baden-Württemberg bypasses telecommunications incumbent channel lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by defense primes seeking captive foundry capacity, with long-term viability hinging on 5-10 year sovereign semiconductor policy continuity. Acquisition target archetypes include GaN-on-Sapphire specialists with Ka-band satellite terminal qualifications orthogonal to terrestrial basestation cycles. Monitor TRAI spectrum allocation timelines and FCC 24-47 GHz auction implementation as inflection indicators for millimeter-wave power amplifier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Strategic Supply Agreement | Pentagon procurement frameworks lock Wolfspeed capacity years ahead of delivery, displacing spot-market purchasing. |
| Backward Integration into Substrate Production | Vertically integrated SiC wafer operations insulate North American defense contractors from Japanese single-source vulnerability. |
| EU AI Act Compliance Certification | German network operators now mandate documentation as procurement criterion, filtering qualified supplier pools. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme incentives attract epitaxy investments away from Yangtze River Delta concentration. |
| Technology Licensing for GaN-on-Si Platforms | Tier-1 automotive suppliers in Germany evaluate licensed processes for cost-sensitive 77-81 GHz radar modules. |
Methodological Framework
Independent corroboration across epitaxial growth engineers, RF device physicists, defense procurement officers, and telecommunications equipment procurement managers underwrites the qualitative findings in this study. Primary interviews with foundry operations executives and substrate vendor sales directors combined with secondary validation from FCC spectrum auction records, EU Radio Equipment Directive harmonized standards documentation, Pentagon procurement directive releases, and METI production-linked incentive framework filings. Bottom-up wafer start projections and top-down defense budget allocation analysis triangulate market sizing.
Rate-of-change decomposition across product type, substrate technology, end-user vertical, and geographic regulatory cluster dimensions structures the analytical framework. CAGRs derive from segmented volume projections calibrated against historical capacity expansion trajectories and announced epitaxy equipment installations. Modeled inputs include metal-organic chemical vapor deposition reactor delivery queues, ITAR and EAR classification threshold evolution, and sovereign semiconductor policy incentive disbursement schedules.
Underlying measurement precision varies by segment; defense procurement volumes carry tighter precision than classified electronic warfare program allocations. Forecasts reflect documented assumptions regarding FCC spectrum auction timing and EU AI Act implementation enforcement. Practitioners should monitor MIIT 5G-Advanced spectrum allocations and export control reclassification proceedings for early signals of capacity reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Switches Market
RF Components
RF Filters Market
RF Components
5G Gain Block Amplifier Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Power Amplifier Market
RF Components
Multilayer Coupled Inductor Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF Microwave MLCC Market
RF Components
Radio Frequency Front End Market
RF Components
Global Inductors Market
RF Components
5G Driver Amplifier Market
RF Components
Analog Phase Shifter Market
RF Components
Digital Phase Shifter Market
RF Components
Millimeter Wave Equipment Market
RF Components
RF Interconnect Market
RF Components
Multi-Mode Receiver Market