
 Multi-Head Filling Machines Market | 2026-2036
Multi-Head Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Head Filling Machines Market Analysis
Germany is rewriting capacity dynamics for precision filling equipment as Bosch Packaging Technology leverages its Stuttgart engineering base to sustain servo-motor integration leadership. Krones Group AG anchors high-speed beverage line deployments across European bottling corridors. Coesia Group competes through modular platform architectures that allow rapid format changeovers for contract packagers.
Multi-head filling machines deploy synchronized dispensing nozzles operating at throughputs exceeding 600 containers per minute, with servo-controlled volumetric accuracy within plus or minus 0.5 percent for pharmaceutical liquids. Automatic systems dominate capital deployment in dairy and beverage bottling where line integration with upstream blow-molders and downstream cappers determines total cost of ownership. Servo technology captures margin pools in pharmaceutical and cosmetics applications requiring validated batch records and reject-rate minimization, while gravity-based configurations retain cost advantages for low-viscosity, non-foaming chemicals in emerging manufacturing clusters.
FDA's 21 CFR Part 11 electronic records requirements and EMA's Annex 1 sterile manufacturing revisions compel pharmaceutical buyers to specify equipment with embedded audit-trail capabilities and isolator-compatible designs. India's CDSCO has aligned with PIC/S guidelines, forcing domestic formulation exporters to upgrade from pneumatic to servo-electric filling systems for EU and US market access. Stakeholders must weigh total validation burden against throughput flexibility when selecting between integrated turnkey lines and standalone modular units.
Market Dynamics
Servo-electric actuation is compressing pneumatic system margins as pharmaceutical buyers prioritize validated batch traceability and reject-rate minimization over upfront equipment cost. This technological displacement is redrawing competitive boundaries between precision-dosing specialists and legacy gravity-filling suppliers.
Growth Catalysts
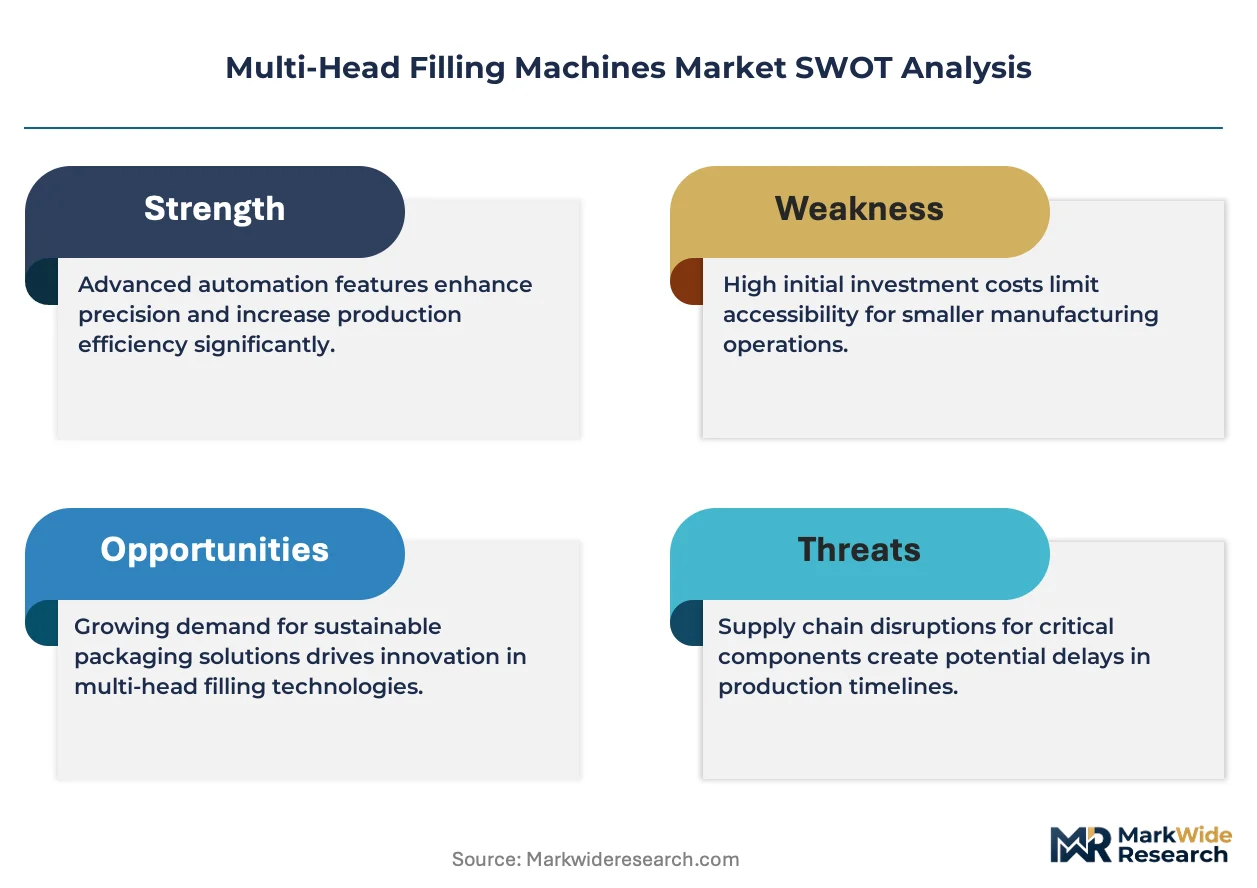
- EMA Annex 1 sterile manufacturing revisions:European pharmaceutical manufacturers are replacing open-filling architectures with isolator-compatible multi-head systems to maintain EU GMP certification for biologics export.
- Biologics formulation expansion:High-viscosity monoclonal antibody and vaccine suspensions require servo-controlled volumetric accuracy that gravity-based systems cannot achieve, pulling investment toward precision-dosing platforms.
- India's CDSCO packaging integrity mandates:Domestic sterile injectable exporters must upgrade to servo-electric filling lines to secure PIC/S-aligned market access for EU and US shipments.
Market Restraints
- Stainless steel and servo-motor input cost volatility:Precision multi-head systems depend on specialized alloys and high-torque electric drives subject to supply chain price swings that compress OEM margins.
- Validation burden concentration:Pharmaceutical equipment buyers face 18-24 month qualification timelines for FDA 21 CFR Part 11 compliance, extending replacement cycles and freezing capital deployment.
- Gravity-based system substitution in chemicals:Low-viscosity, non-foaming industrial formulations in emerging manufacturing clusters retain cost advantages with pneumatic legacy equipment.
Strategic Opportunities
- Contract packaging service expansion:Modular platform architectures enabling sub-30-minute format changeovers capture volume from pharmaceutical CDMOs managing multiple SKUs on shared lines.
- Cosmetics precision dosing convergence:Skincare serum and fragrance manufacturers are adopting pharmaceutical-grade servo filling to support premium positioning and ingredient-integrity claims.
- Dairy aseptic bottling retrofit demand:Extended shelf-life milk and probiotic drink producers in Germany and France require isolator-integrated multi-head systems to replace aging hot-fill lines.
Industry Challenges
- Servo-drive commissioning expertise scarcity:Pharmaceutical manufacturers struggle to source automation engineers capable of integrating multi-axis motion control with serialized track-and-trace databases.
- Legacy line integration complexity:Brownfield dairy and beverage facilities face mechanical incompatibility when retrofitting servo filling heads onto existing conveyor and capping infrastructure.
- Multi-jurisdiction qualification timeline compression:Equipment suppliers must simultaneously satisfy FDA, EMA, and CDSCO validation protocols, fragmenting engineering resources across divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Head Filling Machines Market |
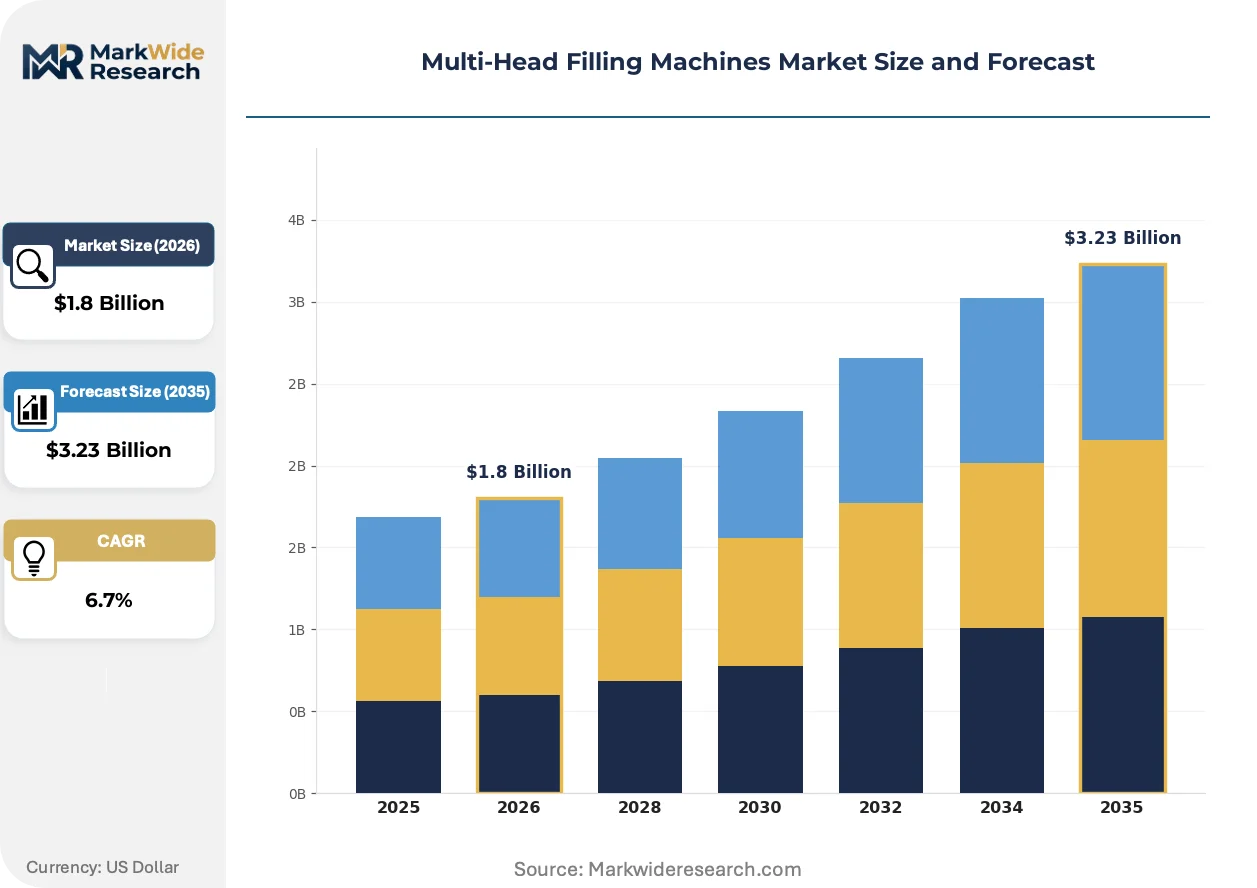
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
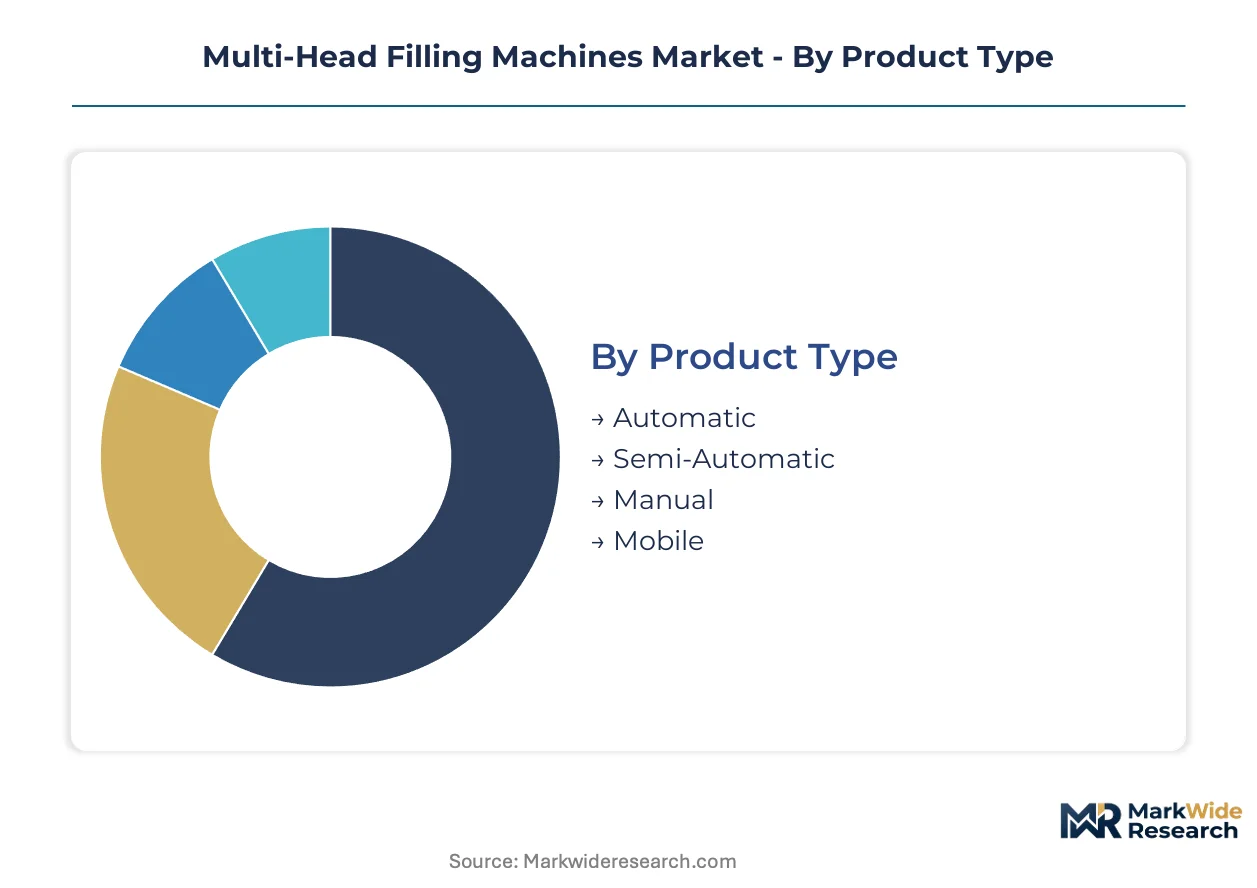
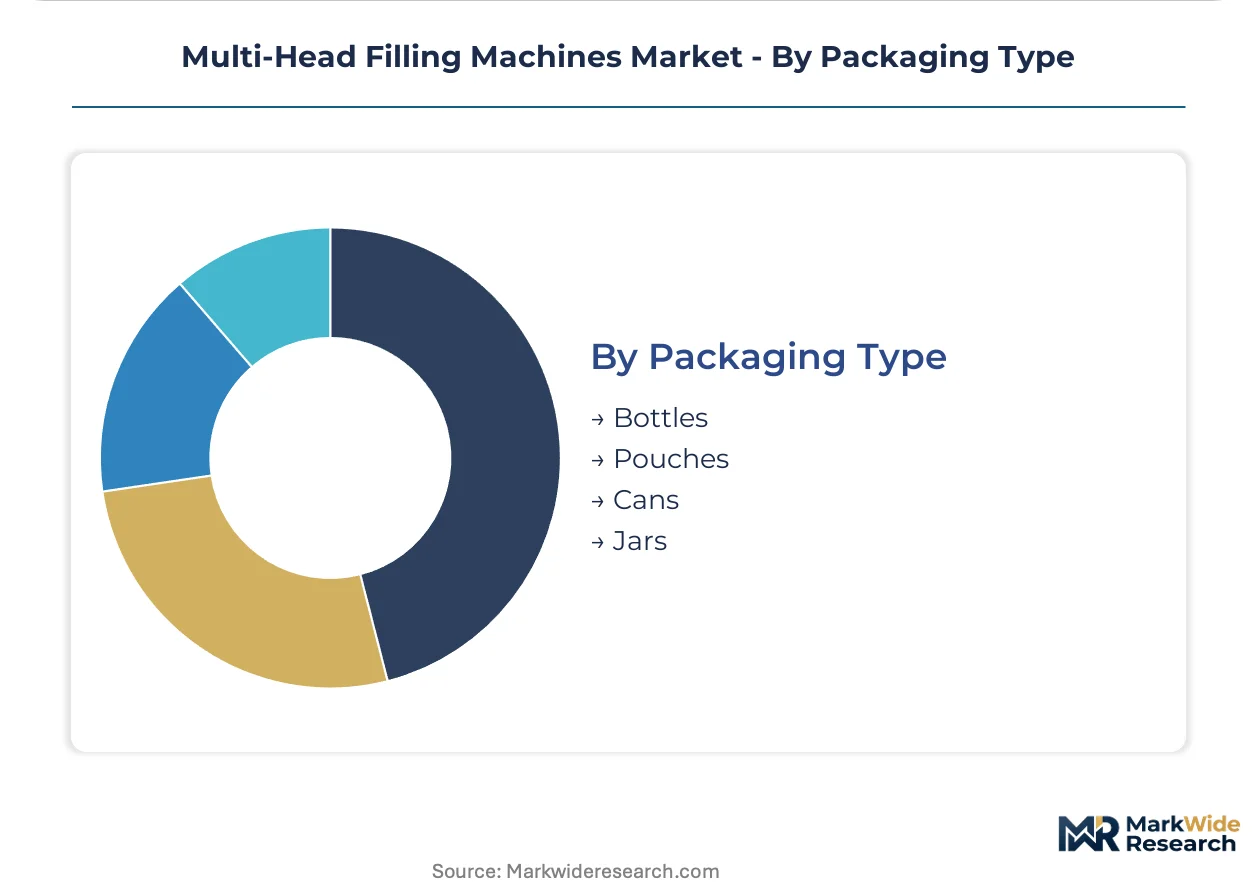
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Mobile End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Electric, Servo, Gravity Packaging Type: Bottles, Pouches, Cans, Jars |
| Companies Covered | Accutek Packaging Equipment Companies, Krones Group AG, Tetra Laval, Coesia Group, KHS GmbH, JBT Corporation, Bosch Packaging Technology, Smurfit Kappa Group, PER-FIL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Head Filling Machines Market Emerging Trajectories
Active substitution of mechanical control architectures by digital feedback systems is compressing development cycles and enabling real-time process adjustment. This shift is redefining how filling equipment suppliers structure R&D investment and field service organizations.
Servo-driven volumetric dosing is migrating from high-end pharmaceutical applications into mid-tier cosmetic and nutraceutical production. Contract manufacturers serving multiple brand owners are adopting these platforms to minimize changeover downtime and support just-in-time batch sizes. The technology is migrating from premium positioning into volume segments, compressing price realization for gravity-based alternatives.
India's CDSCO alignment with PIC/S guidelines is forcing domestic equipment buyers to specify embedded audit-trail capabilities and electronic batch recording. This regulatory harmonization is disqualifying pneumatic legacy systems from export-oriented sterile injectable lines. Domestic formulation exporters are responding by consolidating procurement with suppliers offering integrated validation packages.
After-sales service unbundling is disrupting traditional capital-equipment pricing in European beverage bottling. Major dairies and soft-drink producers are separating hardware acquisition from maintenance contracts, forcing OEMs to compete on transparent hourly service rates. This procurement model change is most visible in Germany, where multi-site operators standardize across brands to leverage volume-based service agreements.
Multi-Head Filling Machines Market Segmentation
Multi-head filling machine procurement patterns diverge sharply across automation tiers, end-use compliance burdens, and dosing precision requirements. Understanding these segment boundaries reveals where capital deployment concentrates and which technology trajectories command premium pricing.
Product Type:
Automation intensity maps directly to throughput requirements and labor cost structures across pharmaceutical, beverage, and chemical packaging corridors.
- Automatic:Synchronized servo-driven nozzle arrays achieve throughputs exceeding 600 containers per minute with volumetric accuracy within plus or minus 0.5 percent. German pharmaceutical manufacturers specify these systems to satisfy EMA Annex 1 isolator-compatibility mandates for biologics export.
- Semi-Automatic:Operator-fed container handling with automated dosing heads bridges mid-volume production where full line integration is capital-prohibitive. Indian CDSCO-aligned sterile injectable exporters deploy these for batch-scale flexibility during qualification phases.
- Manual:Hand-operated multi-head configurations serve artisanal cosmetics and specialty chemical niches where batch sizes fall below automated changeover economic thresholds.
- Mobile:Skid-mounted portable units enable contract packagers to redeploy filling capacity across multiple production halls without fixed infrastructure commitment.
Established volume favors Automatic; emerging adoption favors Mobile.
End User:
Regulatory stringency and formulation complexity create divergent equipment specifications across consuming industries.
- Pharmaceuticals:FDA 21 CFR Part 11 electronic records requirements and EMA sterile manufacturing revisions compel isolator-integrated servo systems with embedded audit-trail capabilities. High-viscosity monoclonal antibody formulations demand precision dosing unavailable from gravity-based alternatives.
- Food & Beverage:Extended shelf-life dairy and probiotic drink producers in France and Germany require aseptic multi-head systems to replace aging hot-fill infrastructure, with line integration determining total cost of ownership.
- Cosmetics:Skincare serum and fragrance manufacturers adopt pharmaceutical-grade servo filling to support premium positioning and ingredient-integrity claims, compressing price realization for pneumatic alternatives.
- Chemicals:Low-viscosity, non-foaming industrial formulations in emerging manufacturing clusters retain cost advantages with gravity-based and pneumatic legacy equipment where validation burdens remain minimal.
Margin concentration sits with Pharmaceuticals; volume expansion favors Food & Beverage.
Technology:
Actuation architecture determines precision ceilings, energy efficiency, and qualification burden for regulated end-uses.
- Servo:Multi-axis motion control with real-time feedback enables validated batch traceability and reject-rate minimization for biologics and high-viscosity vaccines. CDSCO's PIC/S alignment is disqualifying pneumatic systems from India's export-oriented sterile injectable lines.
- Electric:Simplified motor-driven mechanisms serve mid-tier cosmetic and nutraceutical production where pharmaceutical-grade validation is unnecessary but pneumatic precision proves inadequate.
- Pneumatic:Compressed air actuation retains installed base in chemical and legacy beverage applications where upfront capital constraints outweigh total cost of ownership considerations.
- Gravity:Passive flow systems dominate low-viscosity, non-foaming formulations in price-sensitive emerging markets with minimal regulatory oversight.
Technology displacement favors Servo; residual cost advantage sustains Gravity.
Packaging Type:
Container geometry and material compatibility dictate nozzle design, changeover complexity, and downstream integration requirements.
- Bottles:Glass and PET container handling dominates pharmaceutical liquid and beverage applications, with blow-molder integration and capping synchronization determining line efficiency.
- Pouches:Flexible film formats require specialized sealing-head compatibility and are gaining traction in single-serve dairy and cosmetic sampler markets.
- Cans:Aluminum beverage containers command dedicated filling heads with foam-control engineering for carbonated products.
- Jars:Wide-mouth glass and plastic containers serve viscous cosmetics, spreads, and chemical pastes requiring positive-displacement pumping rather than gravity feed.
Integration maturity centers on Bottles; format innovation favors Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy and servo-motor supply chains cluster in Germany, Japan, and the United States, concentrating precision filling equipment manufacturing near automotive and robotics component ecosystems. Equipment buyers in India and China face extended lead times for validated pharmaceutical-grade systems as export-oriented manufacturers prioritize EMA and FDA compliance.
Germany
Stuttgart and Bavaria host engineering centers for servo-motor integration and isolator-compatible system design. EMA Annex 1 sterile manufacturing revisions compel domestic biologics exporters to replace open-filling architectures with validated multi-head lines. Bosch Packaging Technology leverages its Stuttgart base to sustain leadership in precision-dosing platforms for monoclonal antibody formulations.
United States
FDA 21 CFR Part 11 electronic records requirements drive pharmaceutical manufacturers toward embedded audit-trail capabilities and serialized track-and-trace integration. Extended validation timelines of 18-24 months freeze capital deployment cycles for sterile injectable producers. Greater Boston and New Jersey pharmaceutical corridors concentrate demand for isolator-integrated servo systems.
India
CDSCO alignment with PIC/S guidelines forces domestic sterile injectable exporters to upgrade from pneumatic to servo-electric filling lines for EU and US market access. Maharashtra and Gujarat pharmaceutical clusters accelerate replacement of legacy equipment as packaging integrity rules tighten. Contract manufacturers consolidate procurement with suppliers offering integrated validation packages.
China
NMPA standards for pharmaceutical equipment qualification are converging with international GMP benchmarks, pressuring domestic manufacturers to adopt servo-controlled volumetric accuracy. Yangtze River Delta biologics producers invest in precision-dosing platforms for high-viscosity vaccine suspensions. Shanghai and Suzhou industrial zones attract multi-head system deployment for export-oriented formulation facilities.
France
Extended shelf-life dairy and probiotic drink producers in Normandy and Brittany require aseptic multi-head systems to replace aging hot-fill infrastructure. ANSM oversight of pharmaceutical packaging integrity pushes Paris-region biologics manufacturers toward isolator-compatible architectures. Food and beverage line integration with upstream blow-molders determines total cost of ownership calculations.
Multi-Head Filling Machines Market Vendor Landscape
Precision-dosing specialists and diversified packaging conglomerates split the market along validation-capability and throughput-flexibility vectors. Consolidation pressures concentrate among mid-tier European fabricators facing stainless steel input cost volatility and extended pharmaceutical qualification timelines. Three archetypes dominate: integrated turnkey line suppliers, modular platform specialists, and regional gravity-filling legacy players. Competitive dynamics center on M&A activity to secure servo-drive commissioning expertise and strategic partnerships with contract packaging service providers.
Within the precision-dosing tier, Krones Group AG and Bosch Packaging Technology exemplify integrated engineering capabilities spanning servo-motor control and isolator compatibility. Coesia Group occupies a position emphasizing modular architectures that enable rapid format changeovers. Among diversified packaging conglomerates, Tetra Laval represents scale-driven beverage and dairy line integration. These anchors reflect the market's bifurcation between pharmaceutical-grade validation requirements and high-volume food and beverage throughput optimization.
| Leading Market Players |
|---|
| Accutek Packaging Equipment Companies |
| Krones Group AG |
| Tetra Laval |
| Coesia Group |
| KHS GmbH |
| JBT Corporation |
| Bosch Packaging Technology |
| Smurfit Kappa Group |
| PER-FIL Industries |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Frankfurt freight corridor shapes cost dynamics for stainless steel and servo-motor deliveries, concentrating supply leverage with German precision engineering clusters while forcing Indian and Chinese buyers to absorb logistics premiums that widen price differentiation between validated pharmaceutical tiers and standard beverage configurations.
Pricing Analysis
FDA 21 CFR Part 11 and EMA Annex 1 revisions dictate the pricing tier structure across pharmaceutical-grade servo systems, standard electric platforms for cosmetics, and gravity-based economy configurations for chemicals. Price differentiation rests on validation documentation depth and isolator-compatibility certification, with pharmaceutical buyers showing lowest sensitivity due to compliance-driven procurement mandates. Cost compression in mid-tier electric systems is intensifying because servo technology migration from biologics into cosmetics narrows performance gaps. Chemical sector buyers in emerging manufacturing clusters exhibit highest price sensitivity, retaining pneumatic legacy equipment despite higher total cost of ownership.
Supply Chain Analysis
Specialized servo motors and precision stainless steel alloys draw from concentrated manufacturing bases in Germany, Japan, and the United States. Component sourcing hinges on rare-earth magnet supply from Chinese processing facilities and high-grade austenitic steel from German and Swedish mills. Single-source vulnerability for torque-dense servo drives creates exposure to export licensing restrictions on motion-control technology. Distribution runs through OEM-direct channels for pharmaceutical validation packages and regional distributor networks for beverage and chemical standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi-head filling machines market is entering a cyclical recovery phase as EMA Annex 1 compliance deadlines force replacement of open-filling architectures across European biologics production. This regulatory-driven equipment refresh creates asymmetric opportunity for precision-dosing specialists.
For Market Incumbents: Build regulatory certification moats by embedding FDA 21 CFR Part 11 and EMA Annex 1 validation documentation as standard deliverables rather than premium add-ons. Consolidate servo-drive commissioning expertise through targeted hiring in Stuttgart and Boston pharmaceutical corridors to counter automation engineer scarcity. Deepen backward integration into motion-control component supply to offset stainless steel and rare-earth magnet price volatility.
For New Entrants and Emerging Players: Pursue modular platform architectures enabling sub-30-minute format changeovers for Indian and Chinese contract packaging service providers managing multiple SKUs on shared lines. Target Maharashtra and Gujarat pharmaceutical clusters where CDSCO PIC/S alignment forces domestic exporters to upgrade from pneumatic legacy systems without established supplier relationships. Lead with integrated validation packages that compress 18-24 month qualification timelines.
For Investors and Strategic Acquirers: Servo-electric filling specialists with isolator-compatible system designs represent priority acquisition targets given technology displacement of pneumatic alternatives across regulated end-uses. Frame long-term viability around 5-10 year pharmaceutical serialization and sterile manufacturing compliance cycles that sustain replacement demand regardless of macroeconomic conditions. Watch CDSCO enforcement intensity against non-compliant sterile injectable exporters as inflection indicator for Indian market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation Package Integration | Compresses EMA and FDA qualification timelines from 24 months toward 12 months for pharmaceutical buyers. |
| Servo-Drive Commissioning Academy | Addresses automation engineer scarcity plaguing pharmaceutical manufacturers in Greater Boston and New Jersey corridors. |
| Modular Platform Architecture | Enables contract packagers to execute sub-30-minute format changeovers across multiple SKUs on shared production lines. |
| Backward Integration into Motion Control | Captures margin pools from rare-earth magnet and high-torque servo motor supply chain concentration. |
| Isolator-Compatible System Design | Aligns with EMA Annex 1 sterile manufacturing revisions compelling replacement of open-filling architectures. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA inspection reports, CDSCO manufacturing license databases, and trade flow data from German, Japanese, and US customs authorities. Interviews with pharmaceutical plant engineers, beverage line integration specialists, contract packaging operations directors, and OEM aftermarket service heads inform equipment procurement decision patterns. Secondary validation draws from SEC 10-K disclosures of diversified packaging conglomerates, ISO certification registries, and pharmaceutical serialization implementation trackers. Bottom-up equipment shipment analysis triangulates against top-down pharmaceutical and beverage production capacity estimates.
Forecast inputs include automation tier adoption curves, regulatory compliance deadline clustering, and end-use industry capital expenditure cycles across the projection horizon. Segmentation modeling incorporates product type, end-user compliance burden, technology actuation architecture, and packaging format compatibility. CAGRs derive from equipment replacement cycle analysis, greenfield facility announcements, and brownfield retrofit demand indicators. Industry-specific inputs encompass EMA Annex 1 implementation phasing and CDSCO PIC/S alignment enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, rare-earth magnet export licensing, or pharmaceutical capital expenditure cycles would shift the trajectory. Cross-checking against pharmaceutical industry CAPEX survey data and beverage bottling line announcement trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Flow Wrapper Market