
 Tray Packing Machine Market | 2026-2036
Tray Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Packing Machine Market Analytics
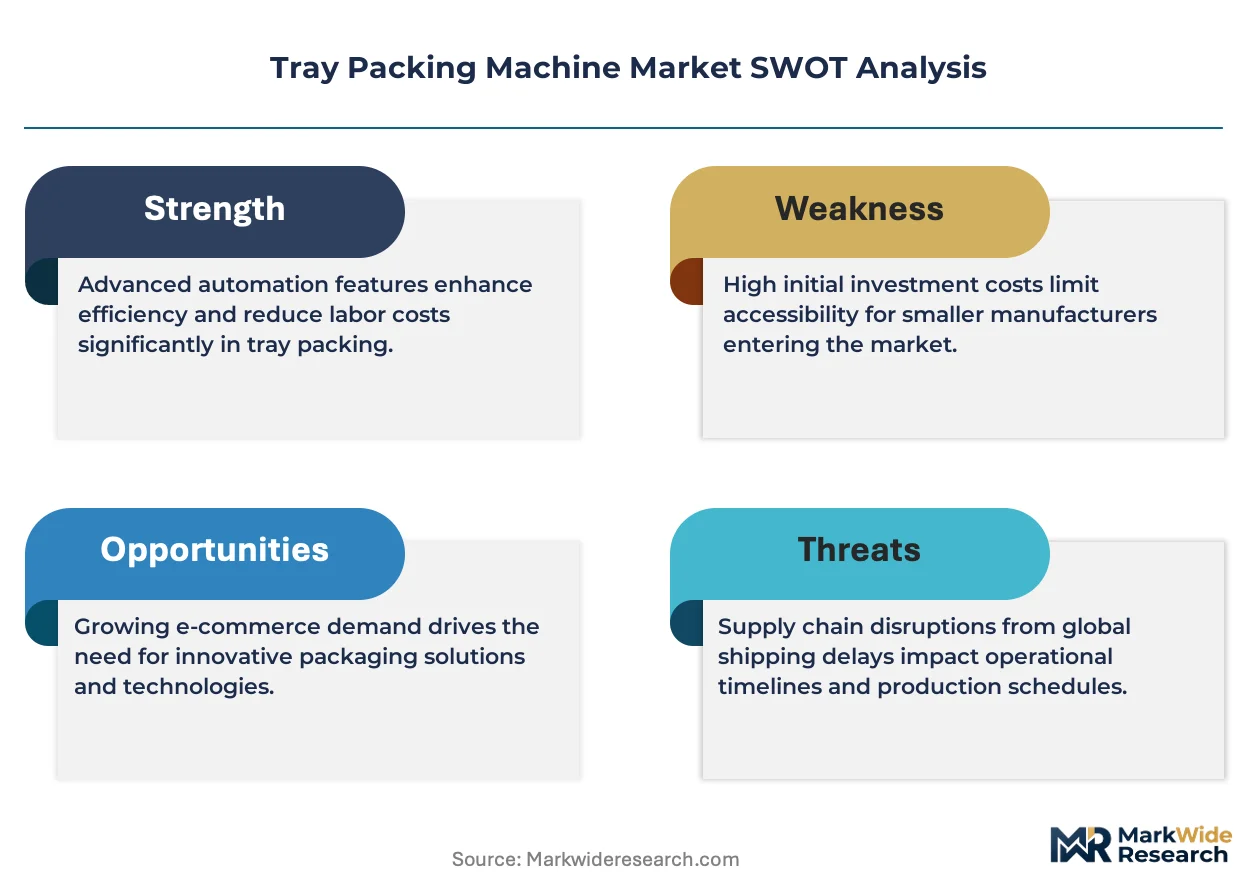
Recyclable fiber-based tray materials are realigning total cost of ownership calculations for end-line equipment buyers. Proseal leverages its vacuum and gas-flushing expertise to anchor high-barrier fresh-protein applications. MULTIVAC sustains technology leadership in thermoforming-to-tray integration, while Sealpac GmbH dominates the premium skin-pack segment for retail-ready meat.
A tray packing machine forms, fills, and seals preformed or thermoformed trays at speeds typically ranging from 30 to 240 packs per minute, using heat-sealing, vacuum, or modified-atmosphere processes to extend shelf life and protect product integrity. Automatic units command the largest installed base as labor-cost pressures intensify across European and North American processing floors. Horizontal flow wrap technology leads in baked-goods and ready-meal applications where hermetic seals and high throughputs matter most, while shrink wrapping retains cost advantages in bulk distribution channels with lower barrier requirements.
The US Food and Drug Administration enforces Title 21 CFR requirements for food-contact surfaces and sanitary design, compelling machine builders to prioritize stainless-steel construction and clean-in-place compatibility. The EU Machinery Directive and CE marking framework mandate risk assessments and safety interlocks that extend engineering cycles but raise barriers to non-compliant imports. Stakeholders must monitor how evolving extended producer responsibility rules in France and Germany reshape material specifications and end-of-life obligations for packaging equipment purchasers.
Market Dynamics
Europe's F-Gas Regulation is forcing mechanical vacuum alternatives into modified-atmosphere packaging lines, compressing engineering cycles while opening premium positioning for compliant equipment builders.
Growth Catalysts
- Regulatory phase-down mandates:The EU F-Gas Regulation accelerates hydrofluorocarbon replacement across meat and dairy processing clusters, creating pull-through demand for gas-flushing equipment with mechanical vacuum architecture.
- Fresh-protein automation:German meat processors are expanding automated tray sealing capacity to meet retail presentation standards and extended shelf-life requirements for export-grade products.
- Fiber-based material transition:Recyclable fiber tray substrates are realigning total cost of ownership calculations, incentivizing end-line equipment upgrades compatible with heat-sealing barrier coatings.
Market Restraints
- Stainless steel input volatility:Equipment builders face margin pressure from nickel and chromium price swings, compressing returns on sanitary-design machines built to FDA Title 21 CFR specifications.
- Supply concentration in drive systems:Precision servo motors and heat-sealing controllers concentrate among German and Japanese component suppliers, exposing assemblers to extended lead times.
- Technical ceiling on throughput:Vacuum cycle physics limits modified-atmosphere sealing speeds below thermoforming line rates, creating bottleneck friction in high-volume fresh-protein operations.
Strategic Opportunities
- Underpenetrated ready-meal automation:French and Italian prepared-food processors lag German automation rates, presenting equipment deployment opportunities in Mediterranean manufacturing clusters.
- Skin-pack retail transition:Premium meat retailing is pivoting toward skin-pack presentation formats, opening white space for sealing technology optimized for high-barrier film adhesion.
- Extended producer responsibility tailwinds:French and German packaging waste regulations are shifting end-of-life obligations onto equipment purchasers, creating consultative service revenue streams for compliance-integrated vendors.
Industry Challenges
- Mechatronics talent scarcity:Equipment builders struggle to source control systems engineers capable of integrating servo-driven sealing heads with clean-in-place sanitation protocols.
- CE marking timeline compression:The EU Machinery Directive's risk assessment requirements extend engineering validation cycles, delaying revenue recognition on custom line configurations.
- Legacy integration complexity:Brownfield protein processing facilities require retrofit interfaces with existing thermoformers and labeling systems, inflating commissioning costs and acceptance testing duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Packing Machine Market |
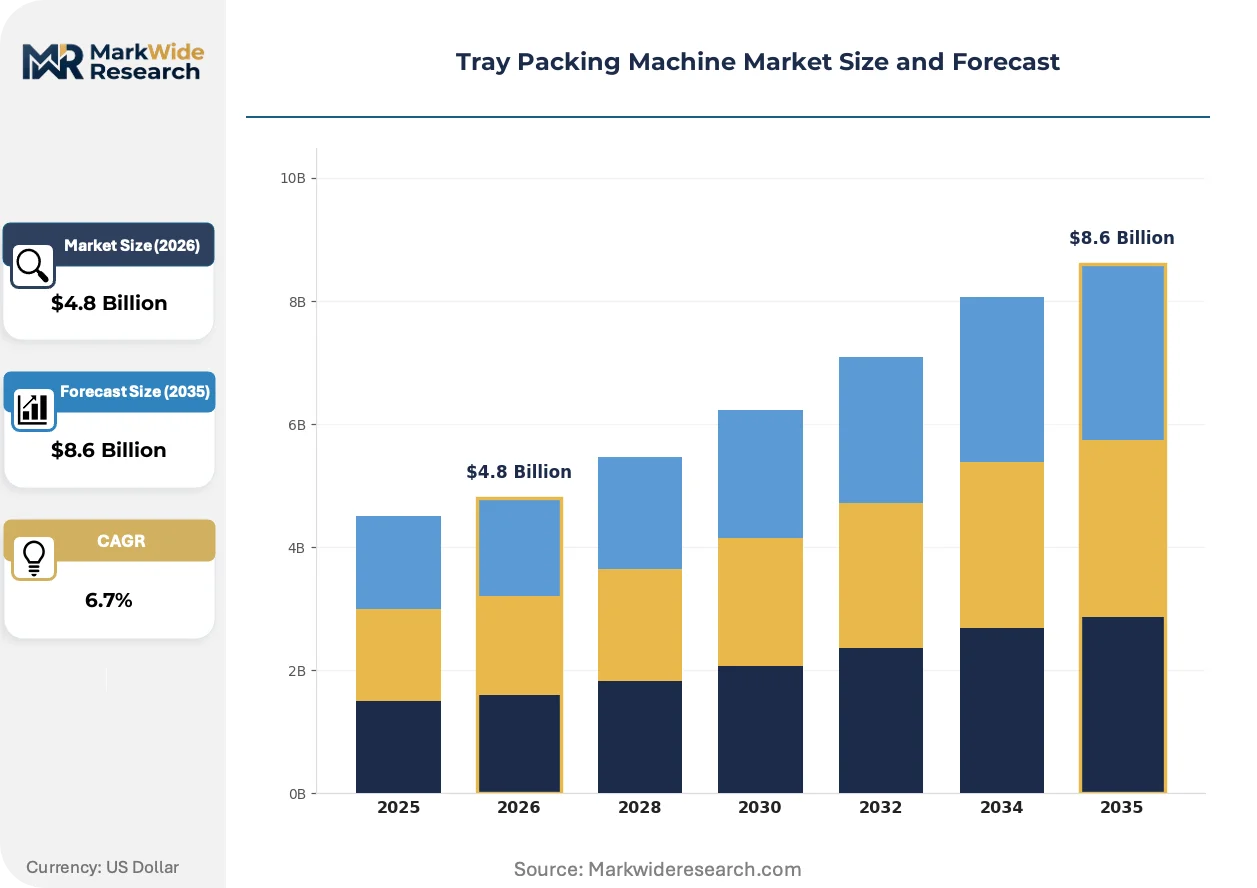
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customizable Technology: Horizontal Flow Wrap, Vertical Form Fill Seal, Shrink Wrapping, Stretch Wrapping End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Machine Size: Compact, Standard, Large, Custom Size |
| Companies Covered | Proseal, Coesia Group, MULTIVAC, Ishida, ILPRA SPA, Syntegon Technology, IMA Group, Sealpac GmbH, ProMach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Packing Machine Market Evolving Landscape
Mechanical vacuum technology is displacing gas-dependent sealing architectures across European protein packaging, while fiber-based tray materials and outcome-based service models restructure buyer-supplier relationships.
Ultrasonic sealing technology is expanding into modified-atmosphere applications previously dominated by thermal impulse methods. German dairy processors are piloting ultrasonic systems for hermetic seals on fiber-based trays with aqueous barrier coatings. This shift is expanding into high-moisture cheese and fresh pasta segments where heat degradation compromises product integrity, compressing the addressable market for conventional hot-bar systems.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is restructuring equipment specification criteria across the European Economic Area. Modified-atmosphere packaging lines must now demonstrate mechanical vacuum capability or qualify for narrow refrigerant exemptions, raising engineering costs but creating regulatory moats for compliant builders. Fresh-meat operations in Germany, the Netherlands, and Denmark face the most acute retrofit pressure given their installed base of gas-flush-dependent equipment.
Outcome-based equipment contracting is displacing traditional capital purchase models among mid-cap European processors. French and Belgian ready-meal manufacturers are contracting for guaranteed throughput and seal integrity metrics rather than machine ownership, transferring operational risk to OEM service organizations. This reconfiguration is most visible in Benelux protein co-packing operations where volume volatility makes fixed asset ownership economically unattractive.
Tray Packing Machine Market Segmentation
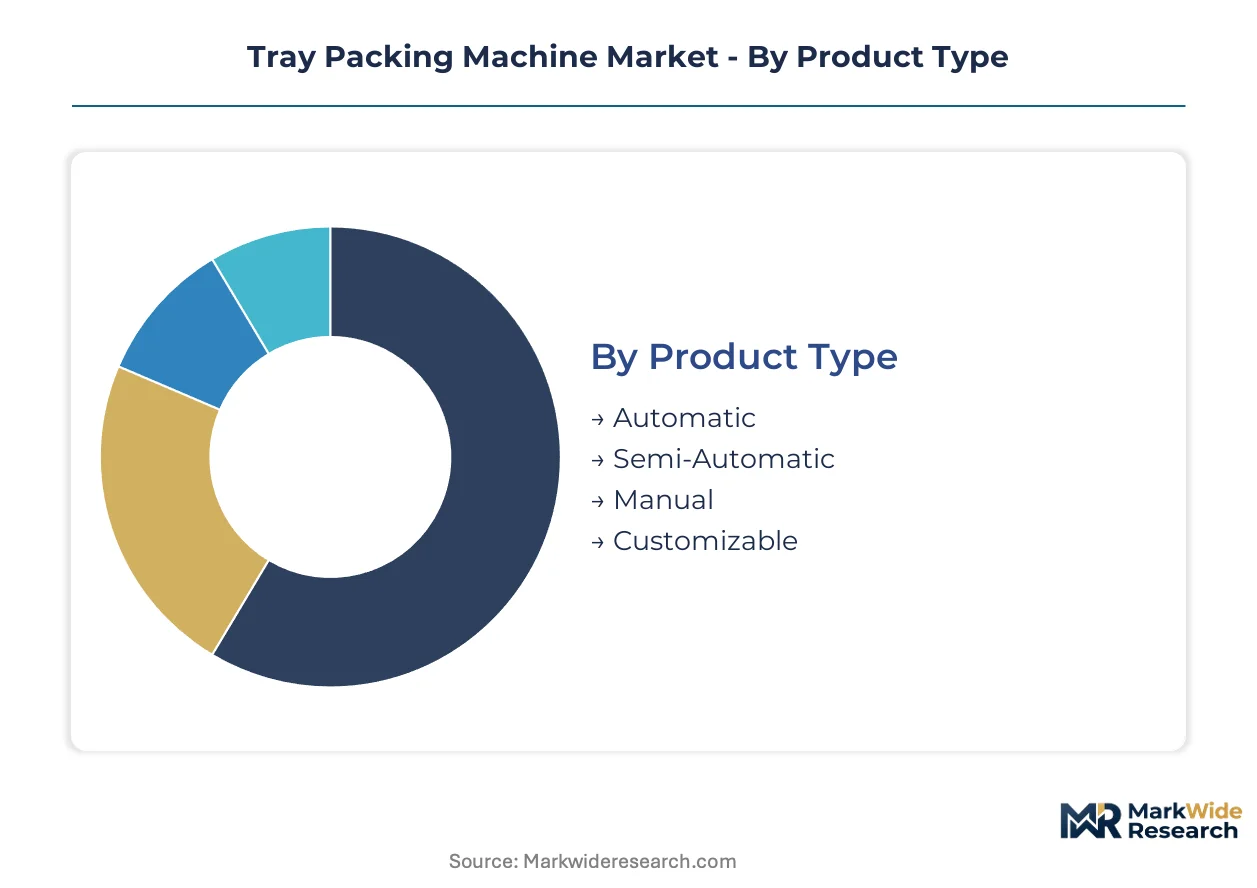
Tray packing machine procurement decisions hinge on line integration complexity, labor cost trajectories, and material compatibility requirements. Equipment specification varies sharply across protein processing, ready-meal manufacturing, and pharmaceutical packaging environments where seal integrity standards diverge.
Product Type:
Replacement cycles accelerate where labor inflation and throughput reliability dominate capital planning.
- Automatic:These units integrate servo-driven sealing heads with programmable logic controllers for continuous operation at 120-240 packs per minute. German meat processors favor automatic lines for export-grade fresh protein where vacuum cycle consistency determines shelf-life compliance. The installed base concentrates in high-volume dairy and ready-meal facilities facing 24/7 production schedules.
- Semi-Automatic:Operator-fed tray loading with automated sealing cycles bridges manual and fully automatic throughput tiers. French prepared-food co-packers deploy semi-automatic units for seasonal volume spikes where capital flexibility outweighs labor cost sensitivity.
- Manual:Foot-pedal or hand-operated sealing for micro-batch artisan producers and pilot-scale R&D operations. German craft cheese makers and Italian cured-meat specialists retain manual equipment for heritage product lines.
- Customizable:Modular architectures permitting retrofitted gas-flushing heads, extended sealing bars, or fiber-tray handling adaptations. Benelux protein processors specify customizable frames to accommodate shifting retail packaging formats.
Volume placements concentrate in Automatic; the faster expansion belongs to Customizable.
Technology:
Seal architecture selection tracks barrier requirements, product moisture content, and downstream distribution channel specifications.
- Horizontal Flow Wrap:Continuous film feeding with rotary sealing jaws produces hermetic packages for baked goods and refrigerated ready meals. Italian pasta manufacturers and German bakery chains specify horizontal flow wrap for shelf-stable and chilled distribution where oxygen exclusion determines product integrity.
- Vertical Form Fill Seal:Film tube formation from roll stock enables gravity-fed filling of free-flowing granular products. Limited penetration in tray packing proper; pharmaceutical tablet counting operations represent the primary deployment niche.
- Shrink Wrapping:Heat-shrinkable film enclosures for multi-pack collation and bulk distribution pallets. Cost advantages persist in beverage multipacks and non-perishable consumer goods where barrier performance requirements remain minimal.
- Stretch Wrapping:Elastic film tensioning for pallet load stabilization without heat application. Warehouse distribution centers deploy stretch wrapping as a terminal logistics operation rather than primary product packaging.
Horizontal Flow Wrap claims the dominant placement share; Shrink Wrapping retains the steepest cost-driven trajectory in bulk channels.
End User:
Regulatory exposure and product liability thresholds reshape equipment specification priorities across customer verticals.
- Food & Beverage:Modified-atmosphere and vacuum sealing for fresh meat, dairy, and prepared meals dominates absolute demand. FDA Title 21 CFR compliance and EU F-Gas Regulation alignment drive stainless-steel sanitary design and mechanical vacuum architecture specifications.
- Pharmaceuticals:Barrier sealing for unit-dose blister packs and medical device trays requires validated seal integrity documentation. EMA and FDA cGMP standards mandate IQ/OQ/PQ qualification protocols extending commissioning timelines.
- Consumer Goods:Cosmetic and household product tray presentation formats emphasize retail shelf impact over extended shelf life. Heat-sealing cycle flexibility for diverse substrate combinations takes priority.
- Electronics:Anti-static film handling and desiccant integration for moisture-sensitive component protection. Cleanroom compatibility and particulate contamination control differentiate specification criteria.
Food & Beverage anchors volume demand; Pharmaceuticals generates the premium pricing tier.
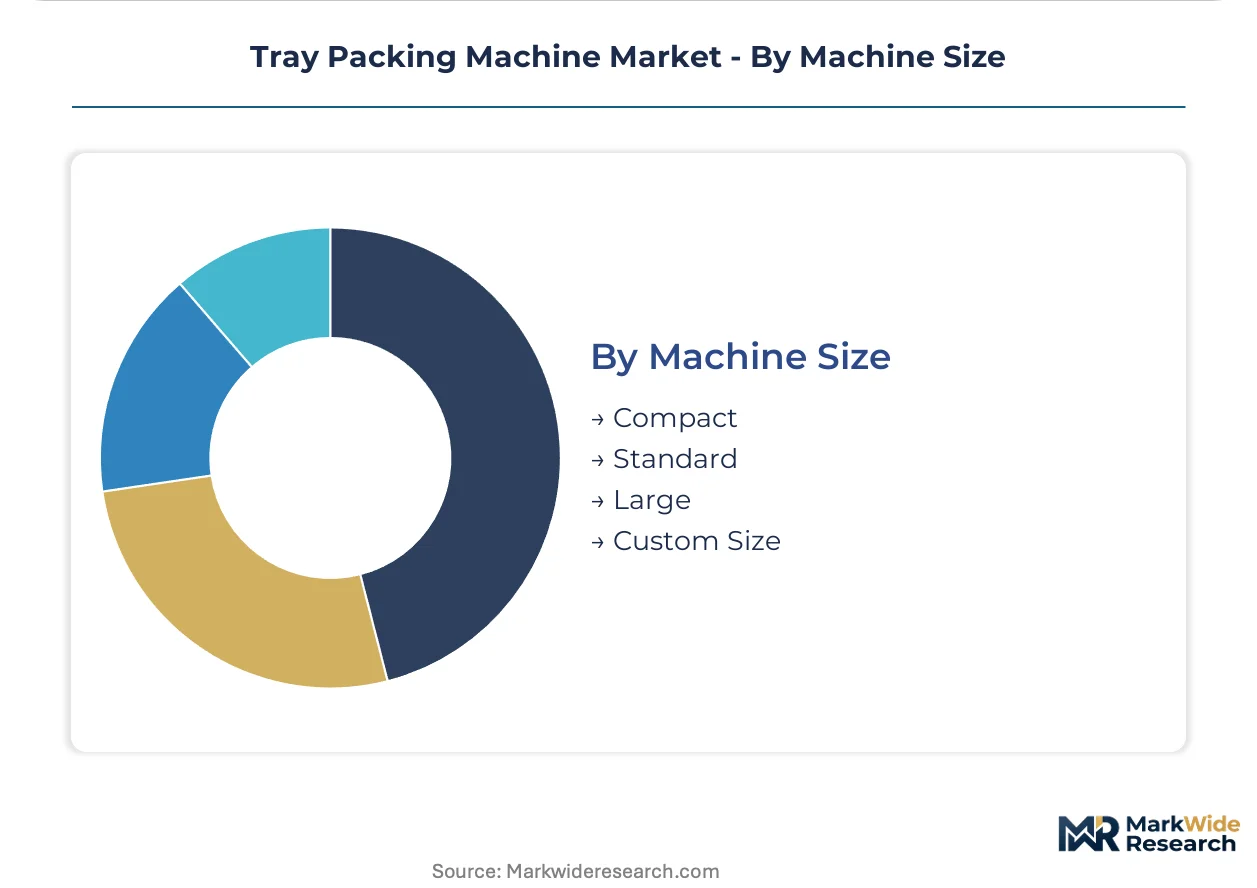
Machine Size:
Facility footprint constraints and line integration density determine dimensional specification trade-offs.
- Compact:Floor-space-optimized frames for urban processing facilities and pilot-scale operations. French urban ready-meal producers and German downtown deli operations specify compact units where real estate costs constrain expansion.
- Standard:Mid-scale configurations balancing throughput and flexibility for multi-product manufacturing environments. Benelux protein co-packers favor standard sizes for contract manufacturing versatility.
- Large:Extended sealing stations and multi-lane configurations for dedicated high-volume production lines. German export-focused meat processors deploy large machines for continuous-shift operation.
- Custom Size:Purpose-engineered dimensions for retrofit brownfield integration or specialized product geometries. Italian fresh pasta manufacturers specify custom widths for irregular tray formats.
Standard sizes claim the broadest placement base; Compact configurations are climbing fastest in urban manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat and dairy processors command the densest concentration of automated tray sealing capacity worldwide. Equipment procurement clusters in export-oriented protein manufacturing corridors where shelf-life compliance determines market access.
Germany
Fresh-protein automation rates run highest among European manufacturing clusters, with meat processors expanding vacuum-sealing lines for retail-ready export products. The F-Gas Regulation accelerates hydrofluorocarbon phase-downs across modified-atmosphere packaging operations. Bavarian and Lower Saxon processing corridors drive retrofit demand for mechanical vacuum alternatives.
United States
FDA Title 21 CFR sanitary design requirements compel stainless-steel construction and clean-in-place compatibility in food-contact equipment. Labor-cost pressures intensify across Midwest and Southeast processing floors, pushing automatic tray sealing adoption. Chicago and Omaha protein packaging hubs anchor North American demand for high-throughput lines.
France
Prepared-food processors lag German automation rates, presenting deployment opportunities in ready-meal manufacturing. Extended producer responsibility rules reshape material specifications and end-of-life obligations for equipment purchasers. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate co-packing operations contracting for outcome-based equipment metrics.
Italy
Horizontal flow wrap technology dominates baked-goods and fresh pasta applications where hermetic seals protect product integrity. Italian cured-meat specialists retain manual equipment for heritage product lines alongside automated expansion. Emilia-Romagna and Lombardy anchor the machinery demand corridor for thermoforming-to-tray integration.
Netherlands
Benelux protein co-packing operations drive customizable frame specifications to accommodate shifting retail packaging formats. Volume volatility makes fixed asset ownership economically unattractive, accelerating outcome-based contracting models. The Randstad manufacturing belt concentrates demand for modular architectures permitting retrofitted gas-flushing adaptations.
Tray Packing Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automatic line builders commanding premium positioning against semi-automatic assemblers. The vendor base organizes around three archetypes: integrated thermoforming-to-sealing system builders, standalone tray sealing specialists, and modular component suppliers serving retrofit markets. Consolidation pressure concentrates among mid-scale European fabricators facing CE marking timeline compression and mechatronics talent scarcity. Dominant competitive moves include backward integration into servo motor supply chains and geographic expansion into underpenetrated Mediterranean manufacturing clusters.
Among Germany-based system builders, MULTIVAC and Sealpac GmbH exemplify divergent specialization vectors within premium-tier equipment supply. MULTIVAC occupies a position representing integrated thermoforming-to-tray architecture, while Sealpac GmbH anchors the high-barrier skin-pack segment for retail-ready meat presentation. UK-based Proseal sits within the vacuum and gas-flushing specialist tier, its expertise aligned with fresh-protein shelf-life extension requirements. These three entities collectively represent the strategic archetypes—integration depth, format specialization, and process expertise—through which competitive positioning is currently restructuring.
| Leading Market Players |
|---|
| Proseal |
| Coesia Group |
| MULTIVAC |
| Ishida |
| ILPRA SPA |
| Syntegon Technology |
| IMA Group |
| Sealpac GmbH |
| ProMach |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel price volatility cascades through tray packing machine manufacturing, compressing margins on stainless-steel sanitary designs while forcing tiered pricing stratification across premium FDA-compliant and standard CE-marked equipment tiers.
Pricing Analysis
High-volume automatic lines sacrifice margin for placement share while customized modular configurations command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates German-built integrated systems from Asian-assembled semi-automatic units and entry-level manual sealers. Pricing pressure stems from nickel and chromium input cost swings, particularly acute for FDA Title 21 CFR compliant stainless-steel construction. Mid-cap European processors exhibit highest price sensitivity due to outcome-based contracting preferences, whereas export-focused German meat processors prioritize seal integrity over capital cost.
Supply Chain Analysis
Freight cost inflation from German and Japanese precision component suppliers has compressed landed cost advantages for equipment assemblers sourcing servo motors and heat-sealing controllers. Manufacturing concentration in Germany, Italy, and China shapes tiered availability of thermoforming-to-sealing integration modules. Component sourcing draws from Taiwanese PLC manufacturers, Swiss sensor specialists, and domestic stainless-steel fabricators. Single-source vulnerability concentrates in precision drive systems, exposing assemblers to extended lead times. Distribution runs through regional equipment dealers and direct OEM sales forces serving protein processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tray packing machine sector sits in a technology-transition phase where mechanical vacuum architecture displaces gas-dependent sealing systems under EU F-Gas Regulation pressure.
For Market Incumbents: Anchor market position through backward integration into servo motor supply chains and captive production of heat-sealing controller modules. Proseal and MULTIVAC must defend against ultrasonic sealing entrants by accelerating clean-in-place sanitation protocol integration. CE marking timeline compression demands pre-validated modular platforms that reduce custom engineering cycles. For New Entrants and Emerging Players: Regional equipment dealers in France and Italy represent the most accessible channel partners for penetrating underautomated ready-meal manufacturing clusters. Mediterranean protein co-packers offer white-space deployment opportunities where German automation rates have yet to penetrate. Target outcome-based service contracting models in Benelux to bypass capital purchase barriers among volume-volatile processors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fabricators with CE marking capabilities and existing thermoformer integration expertise in Germany and the Netherlands. Long-term viability hinges on mechanical vacuum technology transition completion and fiber-based tray material compatibility. Watch for F-Gas Regulation enforcement intensity as the inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vacuum Technology Transition | EU F-Gas Regulation compliance creates regulatory moats for gas-flushing equipment builders with certified architectures. |
| Backward Integration into Servo Supply | Captive motor production mitigates lead-time exposure from concentrated German and Japanese component suppliers. |
| Fiber-Tray Material Compatibility Investment | Heat-sealing barrier coating expertise aligns equipment specifications with recyclable substrate transition requirements. |
| Outcome-Based Service Contracting | Benelux protein co-packers prefer guaranteed throughput metrics over fixed asset ownership in volatile volume environments. |
| Geographic Expansion into Mediterranean Clusters | French and Italian ready-meal processors lag German automation rates, presenting deployment opportunities for modular systems. |
Research Methodology
Multi-period observation of equipment procurement cycles, regulatory filing patterns, and raw material price indices anchored the trend analysis, supplemented by interviews with plant engineers at German meat processors, maintenance directors at Benelux dairy facilities, procurement leads at French ready-meal manufacturers, and aftermarket service heads at Italian pasta producers. Secondary validation drew from EU F-Gas Regulation implementation documents, FDA Title 21 CFR equipment guidance, stainless-steel trade flow data, and machinery sector SEC filings. Bottom-up unit placement estimates triangulated against top-down market sizing from capital expenditure disclosures across protein processing clusters.
The input-output matrix framed demand modeling across automatic, semi-automatic, manual, and customizable product types; horizontal flow wrap, shrink wrap, and stretch wrap technologies; food and beverage, pharmaceutical, consumer goods, and electronics end users; and compact, standard, large, and custom machine sizes throughout the forecast period. CAGRs were derived from regression analysis of historical placement rates against protein processing automation indices and labor cost trajectories. Key inputs included F-Gas Regulation phase-down schedules, fiber-based tray material adoption curves, and servo motor supply lead-time fluctuations.
Caveats apply where EU regulatory enforcement intensity, nickel price volatility, or ultrasonic sealing technology maturation could materially shift the outlook for mechanical vacuum equipment demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Bakery Packaging Machine Market