
 Vial Filling and Capping Machines Market | 2026-2036
Vial Filling and Capping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vial Filling and Capping Machines Market Analytics
The vial filling and capping equipment sector is restructuring around a sharp split between high-containment isolator systems for cytotoxic biologics and standard open-restricted access barrier configurations for generic sterile liquids. Groninger & Co. GmbH leverages its German engineering base to dominate isolator-integrated lines for oncology vials. Syntegon Technology GmbH anchors its position through servo-driven filling platforms that compete on throughput precision for COVID-era expanded manufacturing capacity. Marchesini Group specializes in modular architectures that let pharmaceutical clients reconfigure lines across multiple drug formats without full replacement.
Vial filling and capping machines are electromechanical systems designed to dose sterile liquids, suspensions, or lyophilized powders into glass or polymer vials under ISO 5/Grade A air quality, then seal them with aluminum crimp caps or screw closures at rates from 100 to 600 vials per minute. Their primary purpose is to maintain product sterility and dosing accuracy throughout aseptic pharmaceutical manufacturing. Automatic machines command the largest installed base due to regulatory mandates for closed-system processing, yet robotic systems represent the fastest-expanding category as gloveless isolator integration reduces human intervention and contamination risk. Servo technology leads on precision dosing for high-value biologics, while pneumatic systems retain share in emerging-market facilities where compressed air infrastructure dominates capital planning.
FDA's guidance on aseptic processing and EMA's Annex 1 revision on contamination control strategy both mandate physical barrier separation between operators and sterile products, directly accelerating isolator-based machine demand. The EU MDR and ISO 13485 quality system requirements further constrain market access for equipment lacking validated clean-in-place protocols. Stakeholders must weigh total cost of isolator ownership against regulatory inspection risk when selecting between retrofit upgrades and greenfield robotic installations.
Market Dynamics
Isolator-integrated robotic filling lines are compressing equipment replacement cycles as biopharmaceutical manufacturers race to comply with tightened contamination control mandates from FDA and EMA. This technological inflection is forcing capital allocation trade-offs between retrofitting legacy pneumatic systems and deploying greenfield servo-driven platforms.
Growth Catalysts
- EMA Annex 1 Revision:The updated contamination control strategy mandates physical barrier separation between operators and sterile products, directly accelerating demand for gloveless isolator configurations across European contract manufacturing facilities.
- Lyophilized Biologics Expansion:Rising production of freeze-dried oncology therapeutics requires precision powder dosing capabilities that only servo-driven filling platforms can reliably deliver under ISO 5 conditions.
- German Precision Engineering Clusters:Concentrated supplier networks in Baden-Württemberg and Bavaria enable rapid customization of integrated aseptic lines for multi-format vial processing.
Market Restraints
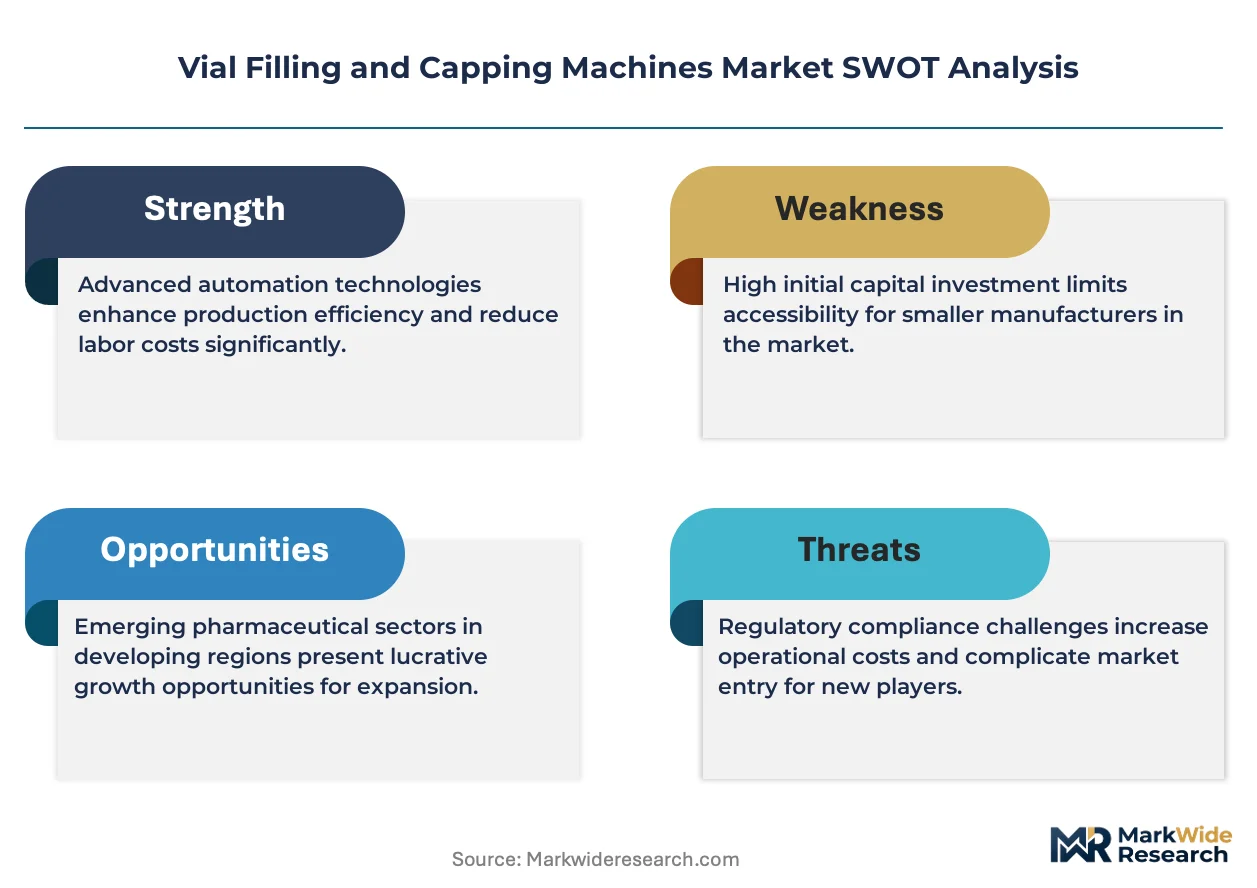
- Isolator Total Cost of Ownership:Validation, maintenance, and decontamination cycles for restricted access barrier systems impose capital burdens that deter mid-tier generic manufacturers from upgrading open-restricted configurations.
- Stainless Steel Supply Concentration:Dependence on specialized 316L pharmaceutical-grade steel from limited European foundries creates input cost volatility and extended lead times for custom machine fabrication.
- Pneumatic Infrastructure Lock-in:Emerging-market facilities with sunk investments in compressed air distribution resist servo technology migration despite precision advantages for high-value biologics.
Strategic Opportunities
- India CDMO Expansion:Contract manufacturing organizations in Hyderabad and Bangalore seek modular filling architectures that accommodate rapid format changeovers between COVID-era vaccine capacity and emerging biosimilar portfolios.
- Single-Use Component Convergence:Integration of disposable fluid pathways with permanent electromechanical bases reduces cleaning validation burden and accelerates batch turnaround for multi-product facilities.
- EU MDR Equipment Certification:Medical device regulation compliance creates premium positioning for machine builders offering pre-validated documentation packages that compress regulatory approval timelines for pharmaceutical clients.
Industry Challenges
- Isolator Integration Engineering:Retrofitting existing cleanroom infrastructure to accommodate gloveless robotic filling systems demands specialized HVAC and pressure differential expertise that outstrips available qualified contractor capacity.
- Multi-Format Validation Complexity:Pharmaceutical manufacturers face extended timeline compression when reconfiguring modular lines across vial sizes, closure types, and product viscosities while maintaining continuous regulatory compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vial Filling and Capping Machines Market |
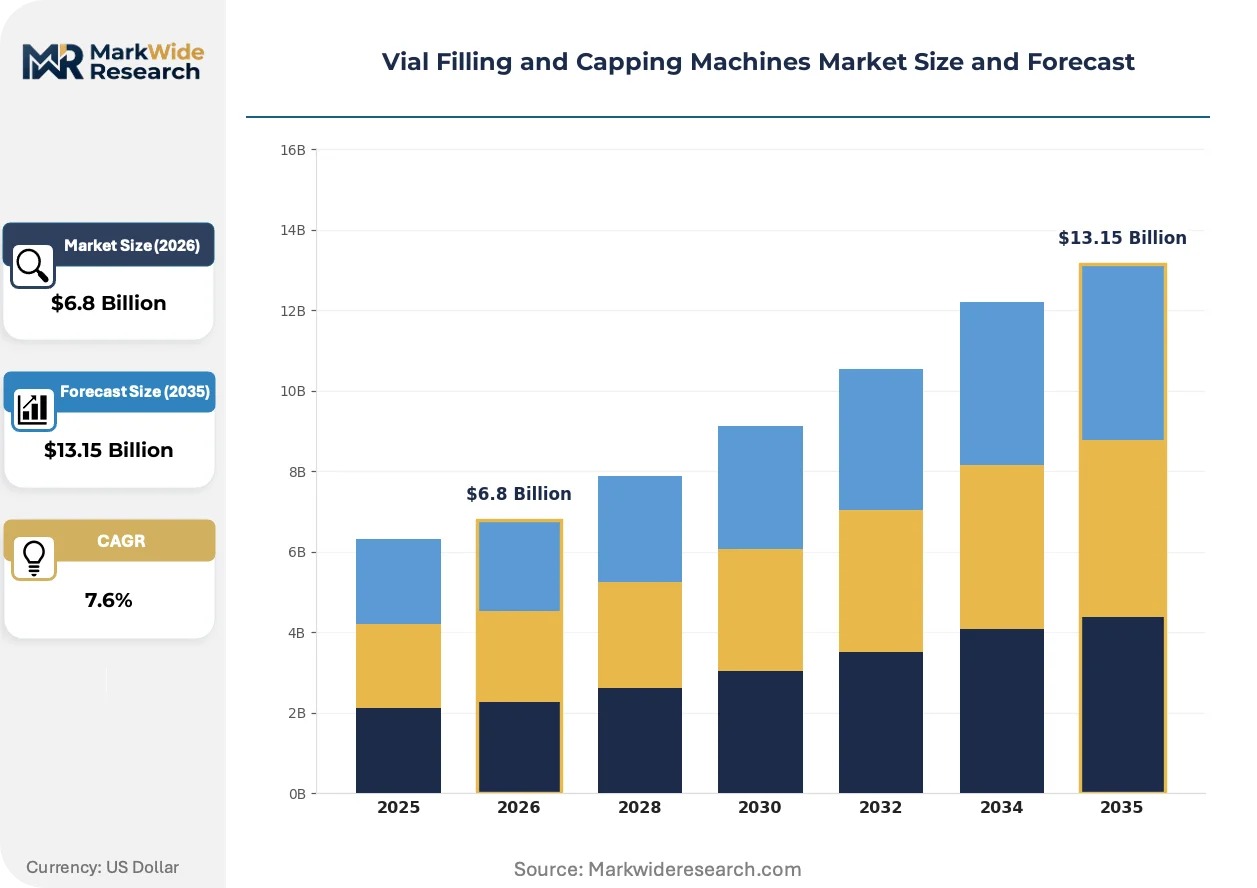
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Robotic Systems End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturing Organizations, Research Laboratories Technology: Pneumatic Technology, Servo Technology, Hydraulic Technology, Electromechanical Technology Application: Aqueous Solutions, Oil-Based Products, Suspensions, Others |
| Companies Covered | Groninger & Co. GmbH, Optima Pharma, Syntegon Technology GmbH, Dara Pharma, Marchesini Group, IMA Group, Cozzoli Machine Company, Acasi, Bausch+Ströbel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vial Filling and Capping Machines Market Evolving Landscape
Equipment architectures are fragmenting between permanent electromechanical bases and rapidly replaceable single-use fluid contact components, enabling pharmaceutical manufacturers to compress batch changeover validation timelines. This structural shift is redrawing competitive boundaries between traditional stainless steel fabricators and disposable technology specialists.
Servo-driven dosing technology is modularizing around standardized motion control platforms that separate precision pump mechanisms from format-specific change parts. Biopharmaceutical manufacturers in Switzerland and Germany are adopting these architectures to reduce spare parts inventory while maintaining dosing accuracy for high-value monoclonal antibodies. The technology is modularizing supplier relationships as pharmaceutical clients mix permanent machine bases from established builders with disposable fluid pathways from specialized component vendors.
FDA's aseptic processing guidance and EMA's Annex 1 revision together mandate documented contamination control strategies that prioritize physical separation over procedural controls. Pharmaceutical manufacturers must now justify any open-system processing with extensive risk documentation, driving preference for isolator-integrated lines regardless of product hazard classification. Oncology biologics and cytotoxic compounds face the most stringent interpretation, with inspectors in Germany and France rejecting barrier configurations that lack active pressure differential monitoring.
After-sales service contracts are unbundling from equipment purchase agreements as pharmaceutical manufacturers seek specialized validation support separate from mechanical maintenance. Contract manufacturing organizations in Ireland and the Netherlands now procure isolator decontamination cycle development and media fill protocol execution from third-party specialists rather than original equipment manufacturers. This fragmentation is most visible among mid-scale biologics facilities that lack in-house aseptic processing expertise but operate under intense regulatory scrutiny from both FDA and national competent authorities.
Vial Filling and Capping Machines Market Segmentation
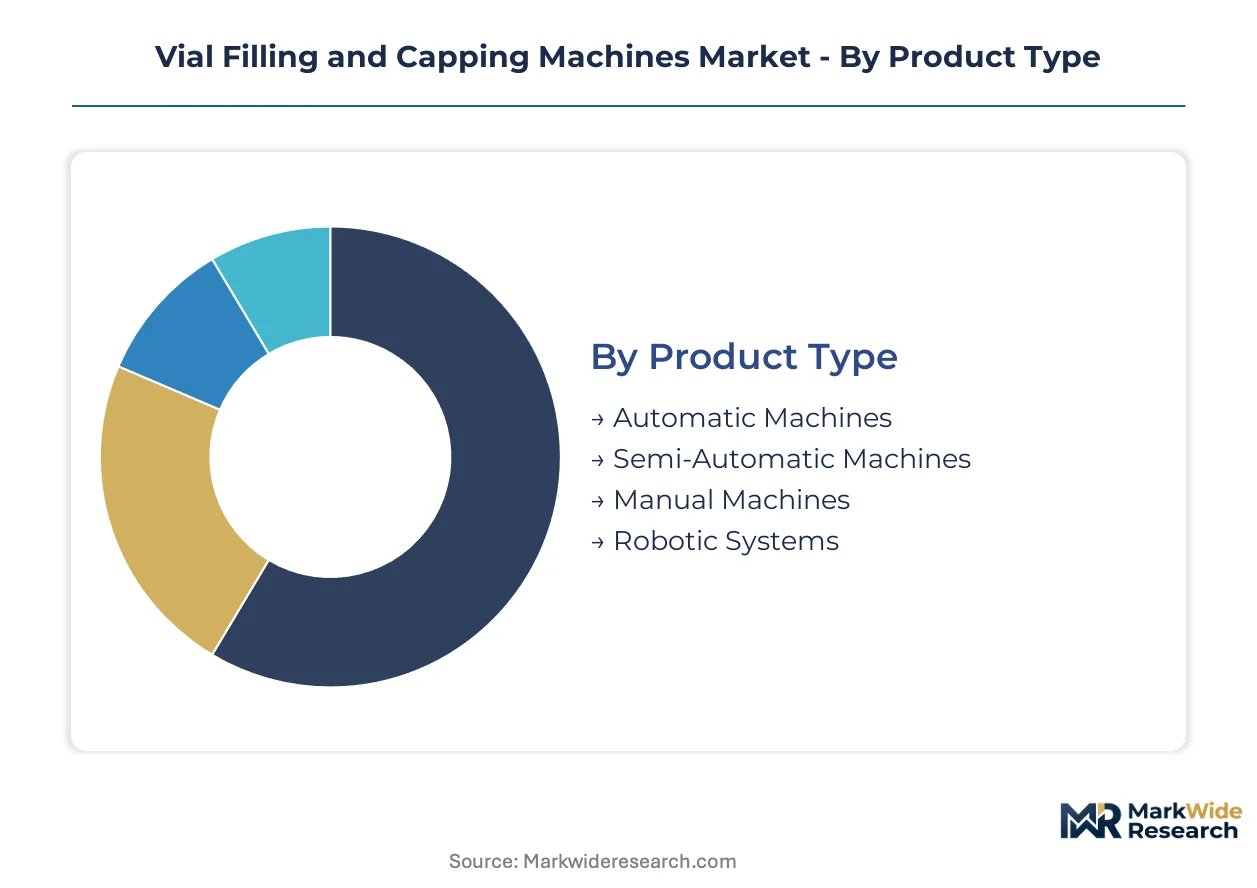
Vial filling and capping equipment purchasing decisions split sharply between high-containment isolator configurations for oncology biologics and standard open-restricted barrier systems for generic sterile liquids. Segmentation reveals how capital allocation priorities differ across buyer types, from multinational biopharmaceuticals seeking gloveless robotic integration to emerging-market generic manufacturers optimizing pneumatic infrastructure.
Product Type:
Capital intensity and regulatory exposure separate buyers in this category, with contamination control mandates driving divergence between isolator-integrated and open-system configurations.
- Automatic Machines:Closed-system electromechanical platforms process 200-600 vials per minute under ISO 5 conditions with minimal operator intervention. Pharmaceutical manufacturers in Germany and Switzerland deploy these for high-volume monoclonal antibody filling where FDA aseptic processing guidance mandates physical barrier separation.
- Robotic Systems:Gloveless isolator-integrated configurations eliminate human intervention through SCARA or Cartesian robot arms for cytotoxic biologics handling. Demand concentrates in Baden-Württemberg engineering clusters supplying contract manufacturing organizations across Europe under EMA Annex 1 contamination control requirements.
- Semi-Automatic Machines:Hybrid configurations balance throughput with format flexibility for mid-scale biologics facilities in Ireland and the Netherlands.
- Manual Machines:Open-restricted barrier systems retain niche demand in research laboratories and early-stage clinical manufacturing where batch volumes remain below 1,000 units.
Automatic machines lead volumes today; robotic systems are gaining share fastest.
End User:
Regulatory scrutiny intensity and product portfolio complexity shape procurement specifications across buyer organizations.
- Pharmaceutical Companies:Multinational drug manufacturers with approved biologics portfolios demand servo-driven precision dosing for high-value oncology therapeutics. Facilities in Germany and Switzerland prioritize isolator-integrated lines that satisfy both FDA and EMA inspection protocols for sterile processing.
- Contract Manufacturing Organizations:CDMOs in Hyderabad and Bangalore seek modular architectures enabling rapid format changeovers between COVID-era vaccine capacity and emerging biosimilar production. These buyers unbundle validation services from equipment purchase to compress regulatory approval timelines.
- Biotechnology Firms:Venture-backed developers of novel biologics favor single-use component integration to reduce cleaning validation burden across multi-product facilities.
- Research Laboratories:Academic and government research centers prioritize compact footprint machines with simplified changeover protocols for preclinical and Phase I material production.
Pharmaceutical companies dominate current installed base; contract manufacturing organizations show steepest expansion trajectory.
Technology:
Precision requirements and infrastructure sunk costs determine technology migration paths across facility vintages.
- Servo Technology:Closed-loop motion control systems deliver dosing accuracy within ±0.5% for high-value lyophilized biologics and suspensions. German precision engineering clusters in Bavaria specialize in modular servo platforms that separate permanent electromechanical bases from format-specific change parts.
- Pneumatic Technology:Compressed air-driven systems retain substantial share in emerging-market facilities where sunk infrastructure investments resist migration despite precision limitations. Indian generic manufacturers in Ahmedabad and Vadodara continue specifying pneumatic fillers for standard aqueous solutions.
- Electromechanical Technology:Hybrid architectures combining servo precision with simplified mechanical drive trains serve mid-tier European facilities seeking upgrade paths from legacy pneumatic systems.
- Hydraulic Technology:High-force configurations for viscous product handling maintain limited application in specialty pharmaceutical manufacturing.
Servo technology commands premium positioning; electromechanical hybrids are climbing the fastest as retrofit demand accelerates.
Application:
Product physical properties dictate filling mechanism specifications and isolator configuration requirements.
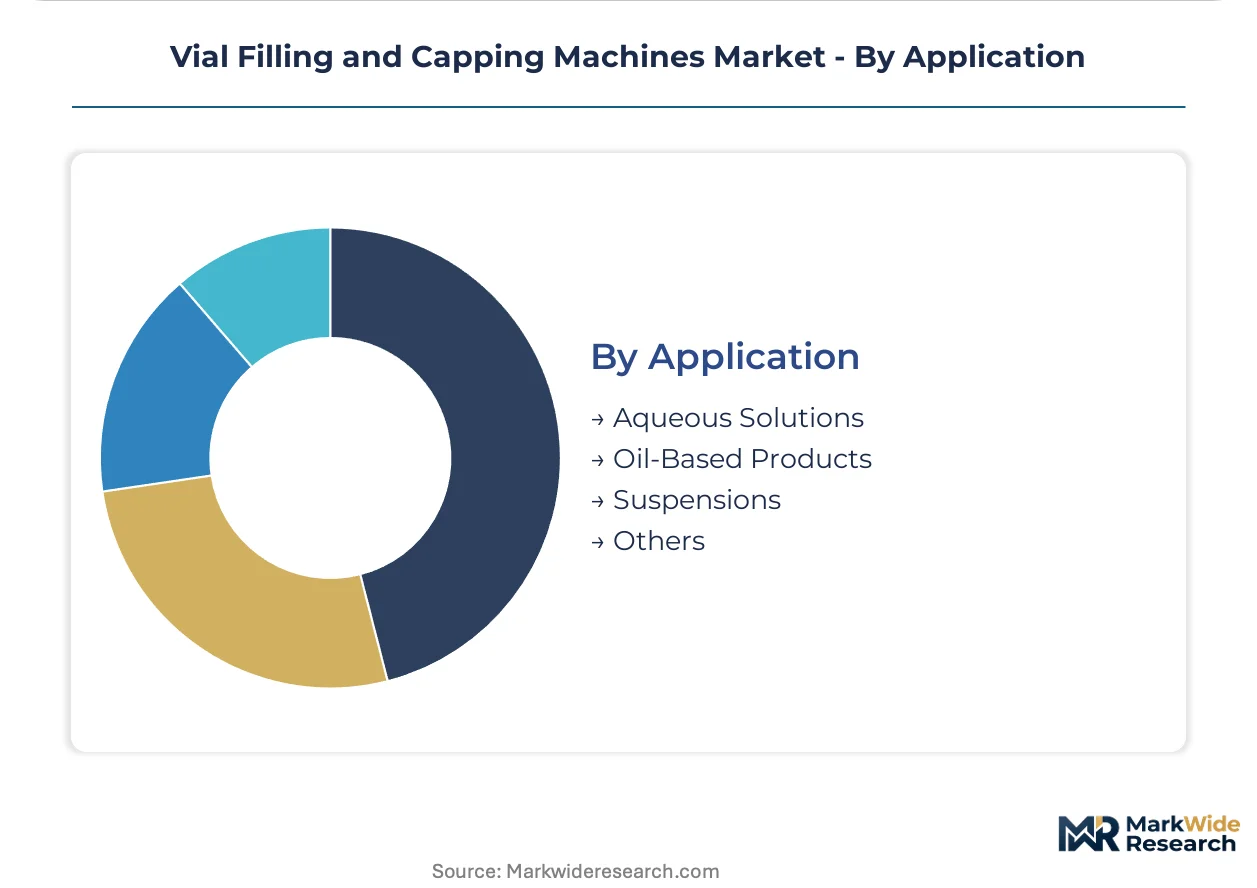
- Aqueous Solutions:Low-viscosity sterile liquids for injectable generics and vaccines process through standard peristaltic or piston pump configurations. High-volume demand in India and China sustains throughput-optimized automatic machine specifications.
- Suspensions:Particulate-laden formulations including vaccine adjuvants and complex biologics require specialized agitation and dosing systems to maintain homogeneity. Swiss and German facilities lead adoption of servo-driven suspension fillers with integrated in-process weight verification.
- Oil-Based Products:Viscous formulations including certain hormonal therapies and depot injections demand positive-displacement pump technologies with heated product pathways.
- Others:Lyophilized powders, dual-chamber systems, and novel drug-device combination products drive custom engineering requirements.
Aqueous solutions generate highest unit volumes; suspensions show strongest technology upgrade momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters supply integrated aseptic lines across Europe, while Indian CDMOs expand modular capacity for vaccine and biosimilar production. Swiss and Irish facilities concentrate high-value biologics filling under dual FDA-EMA inspection protocols.
Germany
Baden-Württemberg and Bavaria engineering clusters dominate isolator-integrated line fabrication for oncology biologics. EMA Annex 1 contamination control mandates accelerate gloveless robotic system deployment among contract manufacturers. Stuttgart-based fabricators customize servo-driven platforms for multi-format vial processing across European pharmaceutical facilities.
United States
Massachusetts and North Carolina biopharma corridors drive demand for high-containment isolator systems in monoclonal antibody production. FDA aseptic processing guidance mandates physical barrier separation, compressing equipment replacement cycles. Greater Boston facilities prioritize robotic filling integration to satisfy intensified regulatory inspection protocols.
India
Hyderabad and Bangalore CDMOs seek modular architectures enabling rapid format changeovers between vaccine capacity and biosimilar portfolios. CDSCO manufacturing standards tighten sterile processing requirements for export-oriented facilities. Gujarat pharmaceutical clusters sustain pneumatic system demand for generic injectable production despite precision limitations.
Switzerland
Basel-region biologics manufacturers anchor European demand for servo-driven lyophilized powder dosing systems. Swissmedic inspection protocols enforce ISO 5 compliance documentation exceeding standard EMA requirements. Zug and Geneva facilities specialize in high-value oncology therapeutic filling under dual regulatory jurisdiction.
Ireland
Dublin and Cork pharmaceutical manufacturing hubs concentrate FDA-inspected sterile processing capacity for North American market access. National competent authority oversight aligns with EMA contamination control strategy implementation. Mid-scale biologics facilities unbundle validation services from equipment procurement to compress regulatory approval timelines.
Vial Filling and Capping Machines Market Competitive Landscape
Top-tier vendors anchor precision isolator integration, while mid-scale fabricators compete on modular reconfigurability and regional service density. The vendor base stratifies between German engineering specialists commanding premium positioning in high-containment oncology applications and Italian-Indian fabricators optimizing throughput economics for generic sterile liquids. Two dominant competitive moves structure rivalry: strategic partnerships between stainless steel fabricators and single-use component specialists, and geographic expansion through validation service unbundling in Ireland and the Netherlands.
Within the German precision engineering tier, Groninger & Co. GmbH and Syntegon Technology GmbH occupy positions exemplifying isolator-integrated and servo-driven platform specialization respectively. Marchesini Group represents the modular architecture archetype, enabling pharmaceutical clients to reconfigure lines across multiple drug formats. These three anchors illustrate how competitive positioning fragments between permanent electromechanical base specialists and disposable technology integrators.
| Leading Market Players |
|---|
| Groninger & Co. GmbH |
| Optima Pharma |
| Syntegon Technology GmbH |
| Dara Pharma |
| Marchesini Group |
| IMA Group |
| Cozzoli Machine Company |
| Acasi |
| Bausch+Ströbel |
| Others |
Value Network & Pricing Analysis
316L pharmaceutical-grade stainless steel procurement costs cascade through three distinct equipment pricing tiers, with Baden-Württemberg fabricators commanding premium positioning for isolator-integrated lines while Indian pneumatic system suppliers compete on capital efficiency for generic sterile liquid processing.
Pricing Analysis
Bundled after-sales service contracts are unbundling from equipment purchase agreements as pharmaceutical manufacturers seek specialized validation support separate from mechanical maintenance. Pricing stratifies across premium isolator-integrated configurations for oncology biologics, standard servo-driven platforms for high-volume monoclonal antibodies, and economy pneumatic systems for emerging-market generic manufacturers. Cost compression in the economy tier is intensifying because Indian CDMOs negotiate aggressively on capital equipment amid biosimilar portfolio expansion. Contract manufacturing organizations in Hyderabad and Bangalore demonstrate highest price sensitivity, while Swiss biologics facilities prioritize contamination control certification over capital expenditure minimization.
Supply Chain Analysis
Workforce availability constraints in Bavaria and Baden-Württemberg precision engineering clusters are extending lead times for custom isolator fabrication despite concentrated supplier networks. Manufacturing draws from specialized 316L pharmaceutical-grade steel from limited European foundries, servo motor assemblies from German automation specialists, and single-use fluid pathway components from disposable technology vendors. Single-source vulnerability concentrates in pharmaceutical-grade steel supply from Austrian and German foundries. Distribution runs through direct OEM relationships with multinational pharmaceutical manufacturers and CDMO procurement consortiums in Europe and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in isolator-integrated robotic systems where EMA Annex 1 and FDA contamination control mandates justify premium pricing, while cost-down potential resides in modular single-use component convergence that reduces cleaning validation burden.
For Market Incumbents: Deepen backward integration into 316L pharmaceutical-grade steel supply through captive foundry relationships or long-term offtake agreements with Austrian and German suppliers to defend against input cost volatility. Anchor premium positioning through pre-validated documentation packages that compress regulatory approval timelines for pharmaceutical clients facing intensified FDA and EMA inspection protocols. For New Entrants and Emerging Players: Contract manufacturing organization procurement consortiums in Hyderabad and Bangalore represent the most penetrable channel for modular servo-driven platforms that accommodate rapid format changeovers between vaccine and biosimilar production. Target mid-scale biologics facilities in Ireland and the Netherlands with unbundled validation service offerings that address in-house aseptic processing expertise gaps under dual regulatory jurisdiction. For Investors and Strategic Acquirers: Consolidation pressure builds where validation service fragmentation and single-use component specialization outstrip organic R&D capabilities of traditional stainless steel fabricators. Five-to-ten-year viability favors equipment builders with demonstrated isolator integration engineering expertise and established relationships with German precision engineering clusters. Monitor CDSCO manufacturing standard tightening for export-oriented Indian facilities as inflection indicator for modular architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | Gloveless robotic configurations satisfy EMA Annex 1 physical barrier mandates for oncology biologics. |
| Single-Use Component Convergence | Disposable fluid pathways reduce cleaning validation burden for multi-product CDMO facilities. |
| Validation Service Unbundling | Specialized media fill protocol execution compresses regulatory approval timelines for Irish biologics sites. |
| Servo Platform Modularization | Standardized motion control separates permanent bases from format-specific change parts for Swiss manufacturers. |
| Backward Integration into Steel Supply | Captive 316L pharmaceutical-grade sourcing defends against Austrian and German foundry concentration risk. |
Research Methodology
Direct dialogue with equipment procurement directors at multinational pharmaceutical manufacturers, validation specialists at contract manufacturing organizations, and aftermarket service heads at German precision engineering clusters grounded qualitative insights in operational reality. Secondary validation drew from FDA aseptic processing guidance documents, EMA Annex 1 revision submissions, ISO 13485 quality system records, and SEC filings of publicly traded equipment manufacturers. Bottom-up and top-down triangulation cross-checked segment-level demand assumptions against aggregate market sizing.
Installed base projections across the analysis window reflect equipment replacement cycle compression driven by regulatory mandate tightening, with segmentation modeling across automatic, robotic, semi-automatic, and manual machine categories by technology type and end-user archetype. CAGRs were derived from historical capital expenditure patterns at biopharmaceutical manufacturing facilities, weighted by regulatory inspection intensity and contamination control strategy implementation timelines. Forecast inputs incorporated lyophilized biologics capacity expansion trajectories and CDMO modular architecture adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel supply disruption, isolator integration engineering contractor availability, and regulatory interpretation divergence between FDA and national competent authorities. Forecasts reflect assumptions about sustained EMA Annex 1 enforcement intensity and continued biopharmaceutical outsourcing to Indian CDMOs. Practitioners should monitor CDSCO manufacturing standard harmonization progress and German precision engineering cluster workforce expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Kraft Paper Machines Market