
 Industrial Filling Machine Market | 2026-2036
Industrial Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Filling Machine Market Foresight
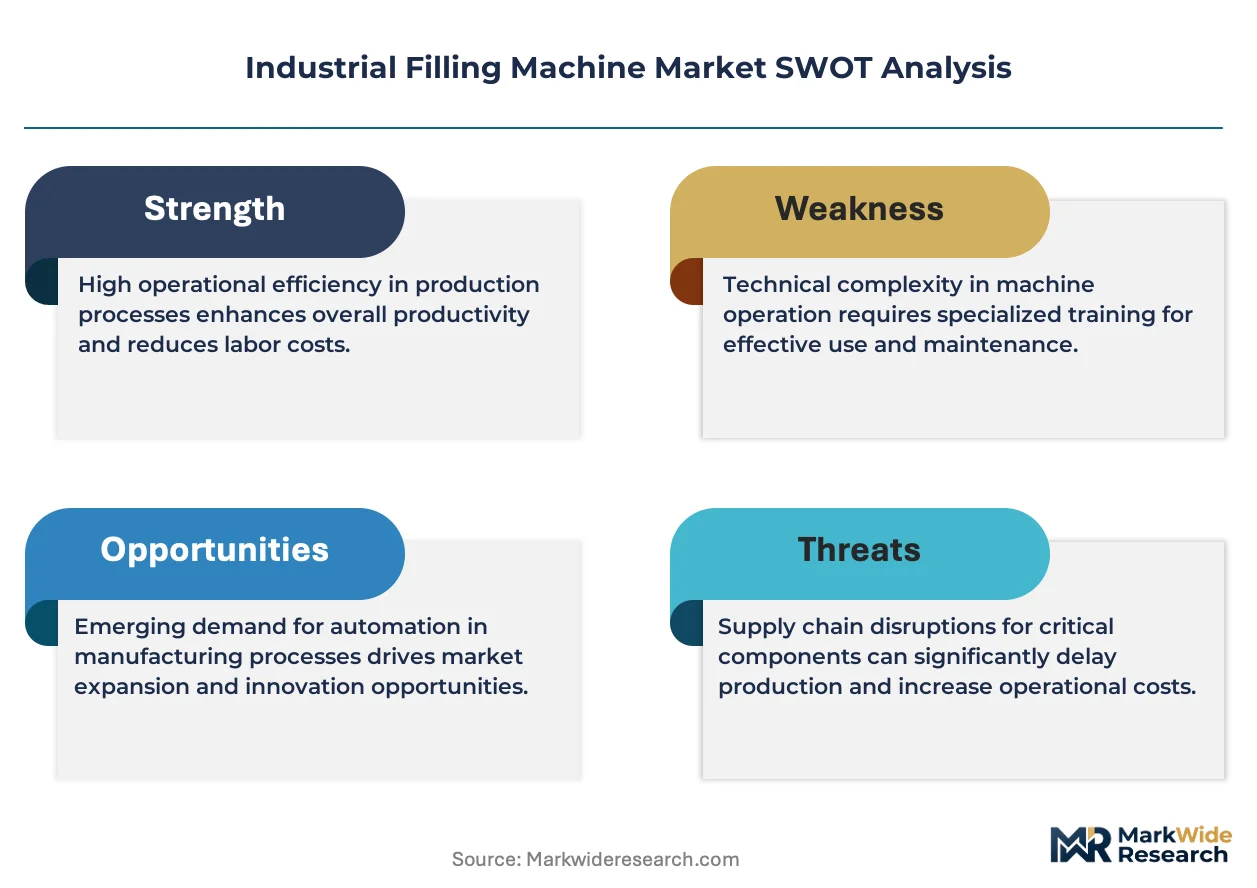
Automation engineering talent is rotating from legacy mechanical systems toward mechatronics and IoT-enabled controls, tightening the labor pool for conventional filling machine service. Groninger & Co. GmbH leverages its Stuttgart engineering base to sustain dominance in pharmaceutical aseptic filling. Krones AG anchors beverage sector demand through integrated bottling-to-palletizing lines. Syntegon Technology differentiates via modular machine platforms that cut changeover time for contract packagers.
An industrial filling machine dispenses measured quantities of liquid, powder, paste, or granular products into containers, bottles, pouches, or vials with tolerances typically ranging from ±0.5% to ±2% depending on product viscosity and fill volume. These systems integrate conveyors, dosing mechanisms, capping units, and inspection stations to achieve throughputs from 50 to 1,200 units per minute in high-volume operations. Liquid fillers command the largest installed base due to universal demand across beverages, pharmaceuticals, and chemicals, though powder fillers capture expanding margin pools as nutraceutical and protein supplement volumes rise. Automatic technology leads capital deployment as manufacturers replace semi-automatic lines to reduce direct labor exposure and satisfy lot-level traceability mandates.
FDA validation protocols and EU MDR conformity requirements shape pharmaceutical filling equipment specifications, forcing vendors to supply exhaustive documentation for IQ/OQ/PQ qualification. EPA and OSHA frameworks govern chemical sector installations, particularly where volatile solvents or hazardous powders demand explosion-proof enclosures and operator exposure controls. Stakeholders must weigh total cost of ownership against speed-to-compliance when specifying machines for regulated versus non-regulated production environments.
Market Dynamics
The migration from mechanical to mechatronic filling architectures is compressing service margins for legacy equipment vendors while accelerating capital refresh cycles among multinational CPG producers. This technology rotation is forcing incumbent suppliers to retrain field engineering teams or cede aftermarket revenue to specialized IoT integrators.
Growth Catalysts
- EU MDR validation mandates:Pharmaceutical manufacturers in Germany and Italy are replacing legacy lines with aseptic systems capable of exhaustive IQ/OQ/PQ documentation to satisfy notified body scrutiny.
- Contract manufacturing expansion:India's CDMO sector is scaling powder filling capacity to serve regulated export markets for nutraceuticals and protein supplements.
- Explosion-proof enclosure demand:Chemical producers handling volatile solvents are retrofitting facilities with EPA and OSHA-compliant filling systems to satisfy exposure control mandates.
Market Restraints
- Stainless steel alloy volatility:Price swings in 316L and 304 grades compress margins for European fabricators already facing energy cost pressure.
- Precision component concentration:Servo motors and load cells from Japanese and German suppliers create single-source vulnerability for mid-tier machine builders.
- Validation timeline friction:FDA 21 CFR Part 11 compliance documentation extends qualification periods by 4-8 months for pharmaceutical installations.
Strategic Opportunities
- Brazilian ANVISA alignment:Local pharmaceutical packaging lines require upgrading to meet international GMP standards, opening retrofit demand for European and North American vendors.
- Cell and gene therapy filling:Aseptic isolator technology convergence with single-use disposable pathways creates new equipment categories for personalized medicine production.
- Modular platform architectures:Syntegon-style reconfigurable systems cut changeover time for contract packagers serving multiple SKU portfolios.
Industry Challenges
- Mechatronics talent scarcity:Automation engineers with PLC and HMI programming skills command premium wages, draining conventional mechanical service pools.
- Legacy system integration friction:Brownfield pharmaceutical facilities struggle to synchronize new IoT-enabled fillers with 1990s-era SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Filling Machine Market |
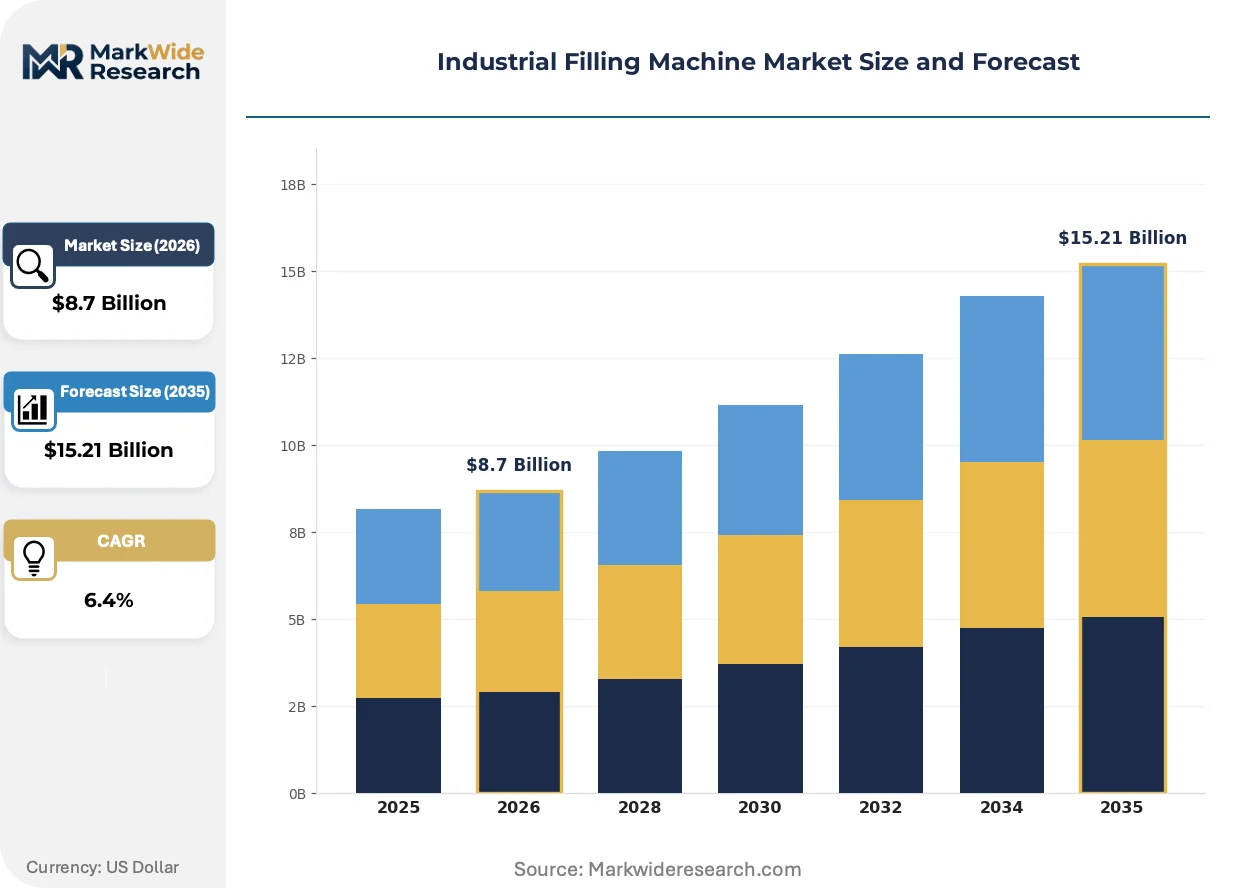
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Powder Fillers, Paste Fillers, Granule Fillers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Food Industry, Pharmaceutical Industry, Chemical Industry, Beverage Industry Technology: Automatic, Semi-Automatic, Manual, Electronic |
| Companies Covered | GEA Group, Syntegon Technology, Krones AG, Barry-Wehmiller Companies Inc., Sidel Group, JBT Corporation, IMA Life, Groninger & Co. GmbH, PACKO Filling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Filling Machine Market Shifts & Advancements
Digital twin simulation and predictive maintenance algorithms are rewriting equipment specification criteria. Buyers now weight total cost of ownership models more heavily than upfront capital expenditure, compressing traditional sales cycles and favoring vendors with software-enabled service portfolios.
Magnetic flow meter dosing systems are displacing piston and peristaltic mechanisms in high-viscosity pharmaceutical applications. Biologics manufacturers in Switzerland and Massachusetts are adopting these contactless measurement technologies to eliminate shear stress on protein formulations. This shift is displacing legacy pump suppliers from premium aseptic segments while opening sensor calibration service contracts to specialized metrology firms.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cooling systems out of temperature-controlled filling lines. Equipment vendors are pivoting to CO2-based refrigeration or solid-state cooling for vaccines and biologics. Pharmaceutical producers in the Netherlands and Denmark are front-running these mandates to secure early-mover qualification advantages with EMA inspectors.
Outcome-based performance contracts are displacing traditional equipment sale-plus-maintenance arrangements in beverage and dairy sectors. Packagers in Australia and New Zealand are contracting for guaranteed uptime and throughput rather than owning depreciating assets. This compresses vendor revenue recognition timelines while transferring operational risk to equipment suppliers with superior remote diagnostics capability.
Industrial Filling Machine Market Segmentation
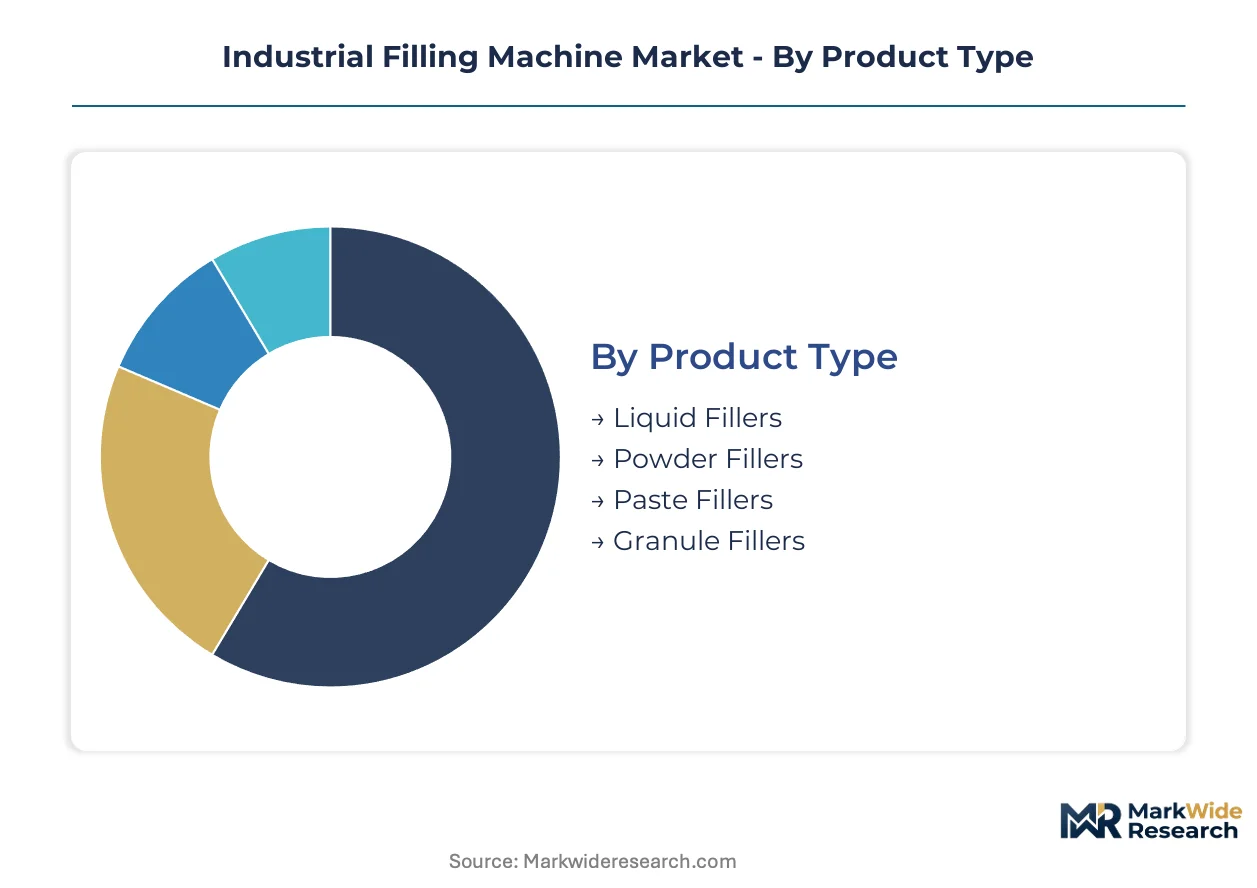
Segmentation in industrial filling equipment reveals how regulatory complexity, automation maturity, and end-use contamination risks create divergent specification requirements across customer portfolios. Vendors must configure machine architectures, validation documentation, and service models to match the compliance intensity and throughput demands of each segment cluster.
Product Type:
Regulatory frameworks differentiate filling equipment specifications sharply — FDA 21 CFR Part 11 and EU MDR impose distinct validation burdens on liquid versus powder systems in pharmaceutical applications.
- Liquid Fillers:Piston, peristaltic, and magnetic flow meter dosing mechanisms handle aqueous solutions through high-viscosity syrups. Beverage bottlers in Germany and pharmaceutical manufacturers in Switzerland drive replacement demand as magnetic flow technologies displace mechanical pumps for protein formulations.
- Powder Fillers:Auger, cup, and net-weight systems dose free-flowing and cohesive powders with explosion-proof enclosures for hazardous chemicals. India's contract manufacturing sector scales capacity for nutraceutical exports to regulated markets, tightening documentation requirements.
- Paste Fillers:Positive displacement pumps and heated hoppers manage thixotropic materials with viscosity control systems. Cosmetic and adhesive producers specify servo-driven dosing for precise volume repeatability.
- Granule Fillers:Volumetric cup and weigh-scale configurations package seeds, fertilizers, and detergent beads. Agricultural chemical facilities in Brazil retrofit lines to meet ANVISA alignment with international GMP standards.
Liquid fillers handle the majority of throughput; powder fillers are the fastest mover on share.
Deployment:
Cost tier separation between capital-intensive on-premises installations and subscription-model cloud architectures determines vendor revenue recognition patterns and customer total cost of ownership calculations.
- On-Premises:Dedicated hardware with local PLC and SCADA control dominates pharmaceutical and chemical installations where data sovereignty and validation documentation requirements preclude external hosting. German and Italian manufacturers prioritize this architecture for EU MDR compliance.
- Cloud-Based:Remote monitoring and predictive maintenance platforms reduce field service costs for beverage and dairy packagers. Australian and New Zealand operators adopt outcome-based performance contracts with guaranteed uptime rather than asset ownership.
- Hybrid:Edge computing with cloud analytics backup balances latency-sensitive control with centralized diagnostics. Mid-tier CPG producers deploy this architecture during brownfield modernization of legacy mechanical lines.
- Mobile:Skid-mounted and containerized filling units serve remote chemical processing and disaster relief pharmaceutical production. Limited validation documentation constrains adoption in regulated drug manufacturing.
On-premises deployment retains the dominant installed base; cloud-based configurations are expanding most quickly in beverage sectors.
End User:
Application-specific contamination risks and throughput requirements shape machine architecture — aseptic isolator integration for biologics versus explosion-proofing for solvents creates non-overlapping vendor specializations.
- Food Industry:Stainless steel 316L construction with CIP/SIP capability and allergen segregation protocols. FSSAI compliance drives specification changes for Indian dairy and edible oil processors scaling for export markets.
- Pharmaceutical Industry:Aseptic filling lines with isolator technology and single-use disposable pathways for cell and gene therapy production. FDA and EMA validation protocols extend qualification timelines by 4-8 months.
- Chemical Industry:EPA and OSHA-mandated explosion-proof enclosures, vapor recovery systems, and operator exposure controls for volatile solvents and hazardous powders. Retrofit demand concentrates in facilities handling REACH-restricted substances.
- Beverage Industry:Integrated bottling-to-palletizing lines with high-speed rotary fillers achieving 1,200 units per minute. Carbonated soft drink and craft beer producers drive modular platform adoption for rapid SKU changeover.
Pharmaceutical end users impose the most stringent specification burdens; food industry applications are gaining share fastest in emerging markets.
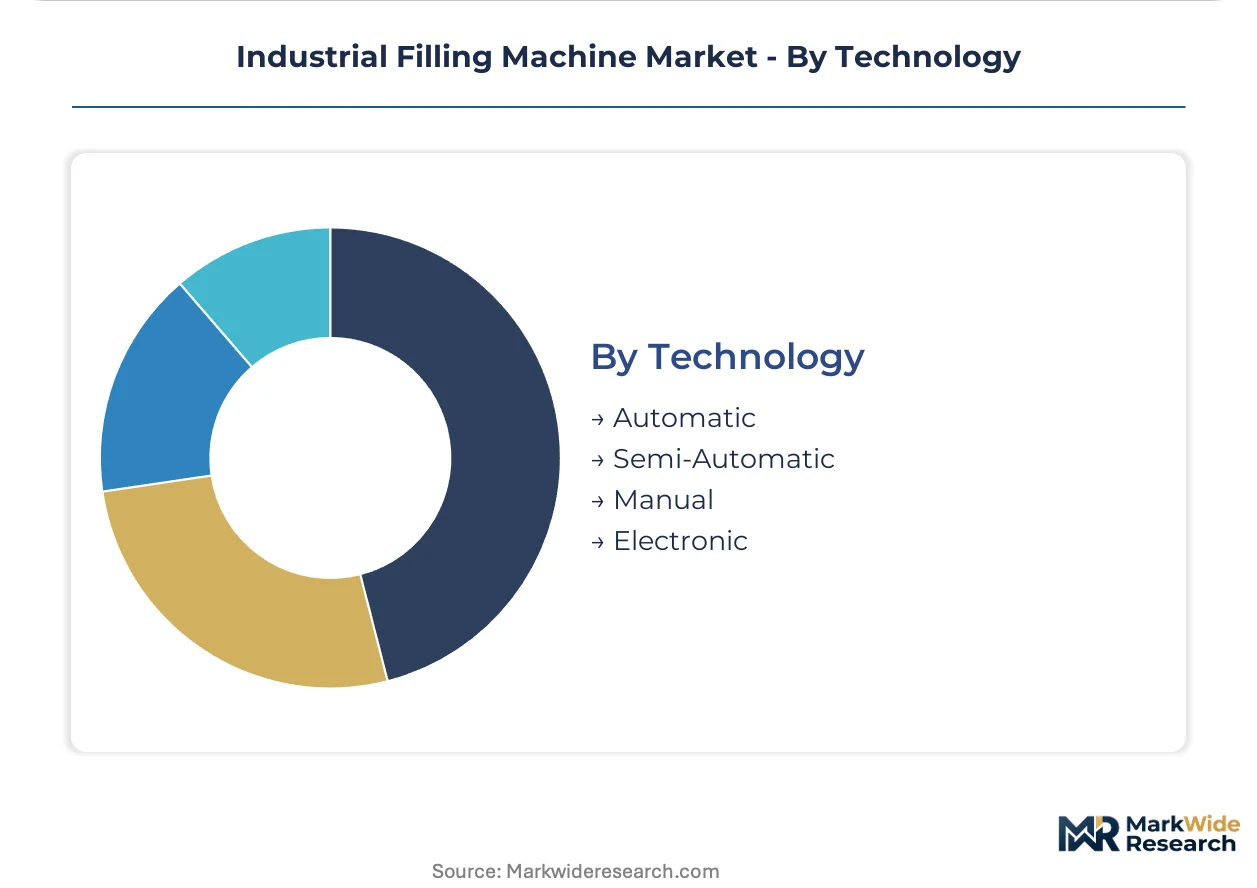
Technology:
Customer type stratification separates multinational CPG producers with capital for full automation from regional packagers retaining semi-automatic flexibility for variable batch sizes.
- Automatic:Servo-driven dosing, machine vision inspection, and robotic handling with lot-level traceability and electronic batch records. Multinational manufacturers replace semi-automatic lines to reduce labor exposure and satisfy serialization mandates.
- Semi-Automatic:Operator-assisted loading with automated dosing and capping for mid-volume contract packagers serving multiple SKU portfolios. Lower capital barriers sustain demand in India's domestic API sector.
- Manual:Hand-operated filling for pilot-scale production, clinical trial materials, and artisanal food processors. Limited to volumes below regulatory thresholds for automated validation.
- Electronic:Digital control systems with HMI interfaces and IoT connectivity retrofitting legacy mechanical architectures. Brownfield pharmaceutical facilities struggle to synchronize with 1990s-era SCADA infrastructure.
Automatic technology commands the dominant capital deployment; electronic control retrofits are climbing the fastest as mechatronics talent scarcity accelerates modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA validation protocols anchor demand in the United States, while EU MDR mandates reshape procurement across Germany, Italy, and Switzerland. India's contract manufacturing sector scales capacity for regulated exports, and Brazil's ANVISA alignment drives retrofit demand.
United States
Biologics manufacturers in Massachusetts and North Carolina accelerate aseptic filling line upgrades to satisfy FDA 21 CFR Part 11 documentation requirements. The EPA governs explosion-proof enclosures for chemical facilities handling volatile solvents. Boston-area pharmaceutical clusters adopt magnetic flow meter dosing to eliminate shear stress on protein formulations.
Germany
Pharmaceutical producers in Stuttgart and Frankfurt replace legacy mechanical lines with mechatronic systems capable of exhaustive IQ/OQ/PQ qualification. EU MDR tightens validation requirements for sterile drug delivery systems. Groninger & Co. GmbH leverages its Stuttgart engineering base to sustain dominance in aseptic filling equipment.
India
Domestic API producers in Maharashtra and Gujarat scale powder filling capacity to serve regulated nutraceutical export markets. CDSCO and FSSAI compliance documentation tightens for contract manufacturers targeting US and European buyers. Mumbai-Pune pharmaceutical corridors concentrate CDMO investments in modular packaging platforms.
Switzerland
Swissmedic oversight drives specification standards for cell and gene therapy filling systems in Basel and Zurich. Biologics manufacturers adopt aseptic isolator technology with single-use disposable pathways. Basel-area pharmaceutical clusters front-run REACH substance restrictions and EU F-Gas Regulation phase-down schedules for temperature-controlled lines.
Brazil
ANVISA alignment with international GMP standards forces pharmaceutical packaging line upgrades in São Paulo and Rio de Janeiro. Agricultural chemical facilities retrofit granule fillers to satisfy exposure control mandates. São Paulo-state industrial corridors concentrate demand for explosion-proof enclosures and vapor recovery systems.
Industrial Filling Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around full-line capability versus modular component expertise. German and Italian engineering houses dominate pharmaceutical aseptic segments, while beverage-focused integrators anchor high-throughput bottling-to-palletizing systems. Strategic archetypes separate validation-heavy documentation specialists from speed-oriented CPG packagers. Competitive moves concentrate on M&A for IoT-enabled controls capability and geographic expansion into Indian and Brazilian contract manufacturing markets.
Among German-based fabricators, Groninger & Co. GmbH and Krones AG occupy positions at opposite ends of the specialization spectrum, with the former exemplifying pharmaceutical-grade validation expertise and the latter representing integrated beverage line scale. Syntegon Technology sits within the modular platform tier, reconfigurable systems that cut changeover time for contract packagers. These three anchors illustrate how vendor positioning maps to end-use contamination risk and throughput requirements rather than geographic coverage alone.
| Leading Market Players |
|---|
| GEA Group |
| Syntegon Technology |
| Krones AG |
| Barry-Wehmiller Companies Inc. |
| Sidel Group |
| JBT Corporation |
| IMA Life |
| Groninger & Co. GmbH |
| PACKO Filling Systems |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation requirements gate both supplier qualification and price differentiation in pharmaceutical filling equipment, forcing vendors to absorb documentation costs while tiering offerings by certification completeness. This regulatory filter simultaneously constrains the supplier base and stratifies pricing power across validation-heavy versus standard-configured machine tiers.
Pricing Analysis
Long-term offtake contracts with embedded service bundles dominate capital equipment procurement, though spot purchases persist for brownfield retrofit components. Three-tier pricing structure across premium aseptic isolator systems, standard automatic lines, and economy semi-automatic configurations reflects documentation depth and servo motor specification grades. Cost compression in mid-tier fabrications is intensifying because Japanese and German precision component suppliers command fixed pricing, squeezing margins for European machine builders already facing energy cost pressure. Contract packagers in India exhibit the highest price sensitivity due to working capital constraints, while multinational pharmaceutical manufacturers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Strategic stockpiling of 316L and 304 stainless steel grades characterizes European fabricator procurement given alloy price volatility, whereas Asian assemblers maintain leaner just-in-time inventories. Component sourcing concentrates in Germany and Japan for servo motors and load cells, with India and China supplying fabricated structural frames and conveyor subassemblies. Single-source vulnerability for precision dosing mechanisms from Japanese suppliers creates supply chain risk for mid-tier machine builders lacking dual-qualification alternatives. Distribution runs through direct OEM sales forces for pharmaceutical validation-heavy installations, while beverage sector equipment moves through regional distributor networks with aftermarket service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in this market, as FDA and EU MDR validation documentation imposes switching costs that lock pharmaceutical manufacturers into incumbent supplier relationships for multi-year replacement cycles.
For Market Incumbents: Compound validation documentation advantages by deepening IQ/OQ/PQ qualification libraries for emerging cell and gene therapy formats, insulating against modular platform disruptors. Secure captive supply of Japanese servo motors through preferred supplier agreements or backward integration into motion control subassemblies. Add capacity in Maharashtra and Gujarat to capture India's CDMO expansion without ceding margin to freight-adjusted European competitors. For New Entrants and Emerging Players: ANVISA fast-track certification for Brazilian pharmaceutical packaging retrofits offers lower competitive density than FDA or EMA pathways, enabling qualification cost amortization across Latin American contract manufacturing demand. Target granule filling equipment for agricultural chemical facilities in São Paulo-state industrial corridors, where explosion-proof enclosure requirements are less documentation-intensive than pharmaceutical aseptic standards. Lead with remote diagnostics software subscriptions to bypass capital-intensive machine fabrication barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechatronics integrators possessing IoT-enabled controls capability but lacking pharmaceutical validation expertise. Five-to-ten year viability hinges on regulatory documentation depth rather than throughput specifications alone. Watch for FDA warning letter volume against aseptic filling line operators as an inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Expansion | Deepening IQ/OQ/PQ libraries for cell and gene therapy formats locks in pharmaceutical switching costs. |
| Precision Component Backward Integration | Captive supply of servo motors and load cells insulates margins from Japanese supplier pricing power. |
| Modular Platform Architecture Development | Reconfigurable systems cut changeover time for contract packagers serving multiple SKU portfolios. |
| Remote Diagnostics Capability Buildout | Software-enabled service portfolios compress sales cycles and transfer operational risk to vendors. |
| ANVISA Certification Fast-Track Investment | Brazilian regulatory alignment opens retrofit demand for international GMP standard upgrades. |
Research Methodology
A standing panel of pharmaceutical plant engineers, beverage production managers, chemical facility maintenance directors, and contract manufacturing procurement leads provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K equipment supplier disclosures, and trade flow records from German and Italian engineering export statistics. Bottom-up unit demand estimates triangulated against top-down capital expenditure surveys across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning liquid versus powder versus paste filler architectures, on-premises versus cloud versus hybrid deployment modes, and automatic versus semi-automatic versus electronic control technology tiers. CAGRs derived from regression-weighted historical shipment patterns and forward-looking replacement cycle assumptions, incorporating stainless steel alloy price indices and pharmaceutical regulatory inspection frequency as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EU MDR enforcement intensity and stable precision component supply from Japanese and German sources; material deviation would warrant model refresh. Revision becomes warranted when regulatory inspection backlogs or alloy price volatility cross thresholds that alter replacement cycle timing or fabrication cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Industrial Bulk Packaging Market