
 Volumetric Boom Filling Machine Market | 2026-2036
Volumetric Boom Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Boom Filling Machine Market Analytics
Contract packaging organizations are unwinding share toward in-house beverage and pharmaceutical producers seeking direct control over fill accuracy and batch traceability. Krones AG leverages its rotary filling platform dominance to anchor European brewery retrofits. Sidel Group competes through aseptic blow-fill-seal integration that sustains margin in dairy and juice applications. GEA Group specializes in pharmaceutical-grade isolator systems that command premium positioning in sterility-critical installations.
Volumetric boom filling machines dispense predetermined liquid volumes through piston-driven or flow-metered boom assemblies, typically achieving fill tolerances within plus or minus 0.5 percent for viscosities ranging from water-thin to thousand-centipoise syrups. Electronic technology variants are displacing pneumatic systems in pharmaceutical cleanrooms where programmable recipe management and electronic batch recording eliminate manual changeover errors. Multi-head fillers capture the fastest growth trajectory as personal care and home care brands scale parallel processing to match SKU proliferation without line duplication.
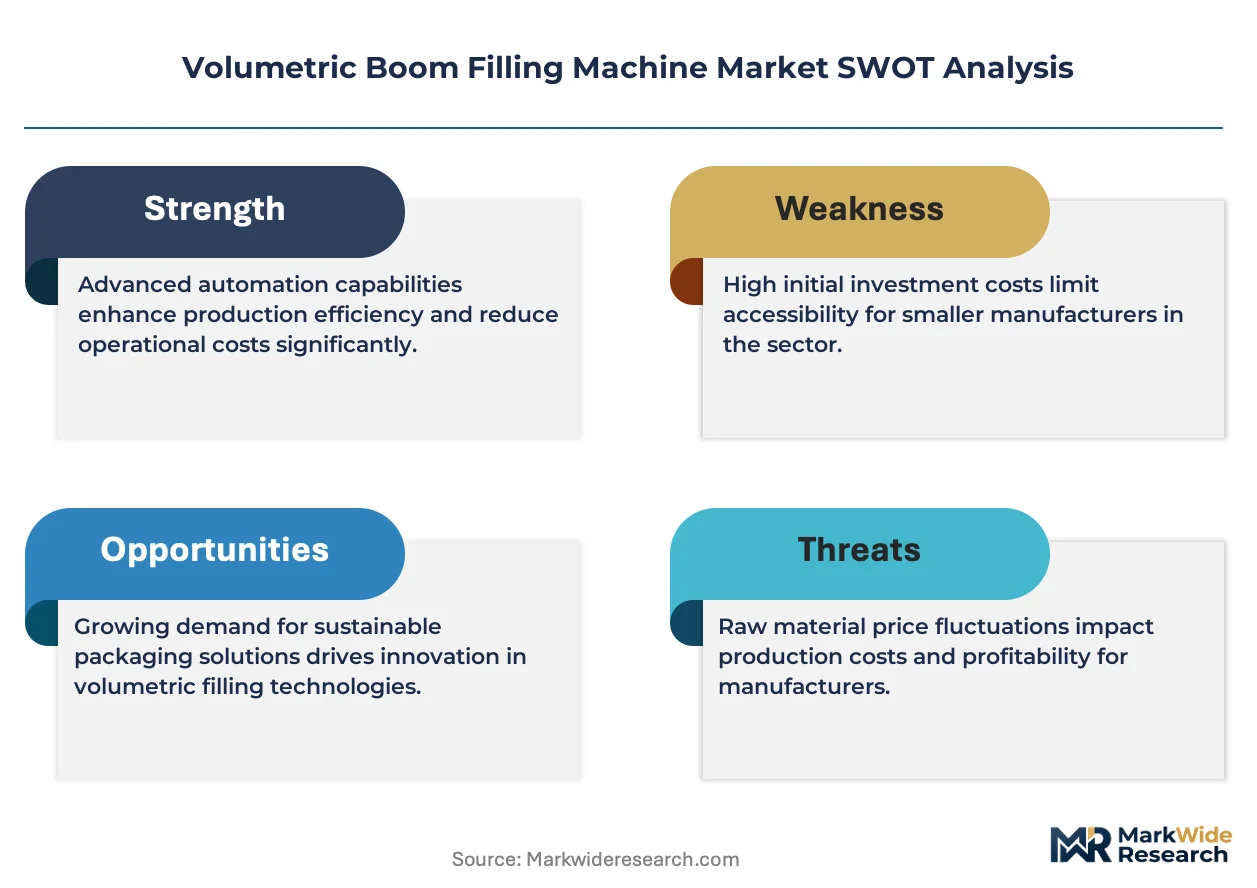
FDA cGMP enforcement and EU MDR traceability mandates compel pharmaceutical end users to specify equipment with embedded audit trails and material certificates. EPA spill prevention rules and OSHA lockout-tagout protocols shape chemical sector procurement criteria for hazardous liquid containment. Stakeholders must weigh total cost of ownership against modular upgrade paths as regulatory digitization and sustainability reporting obligations deepen capital planning complexity.
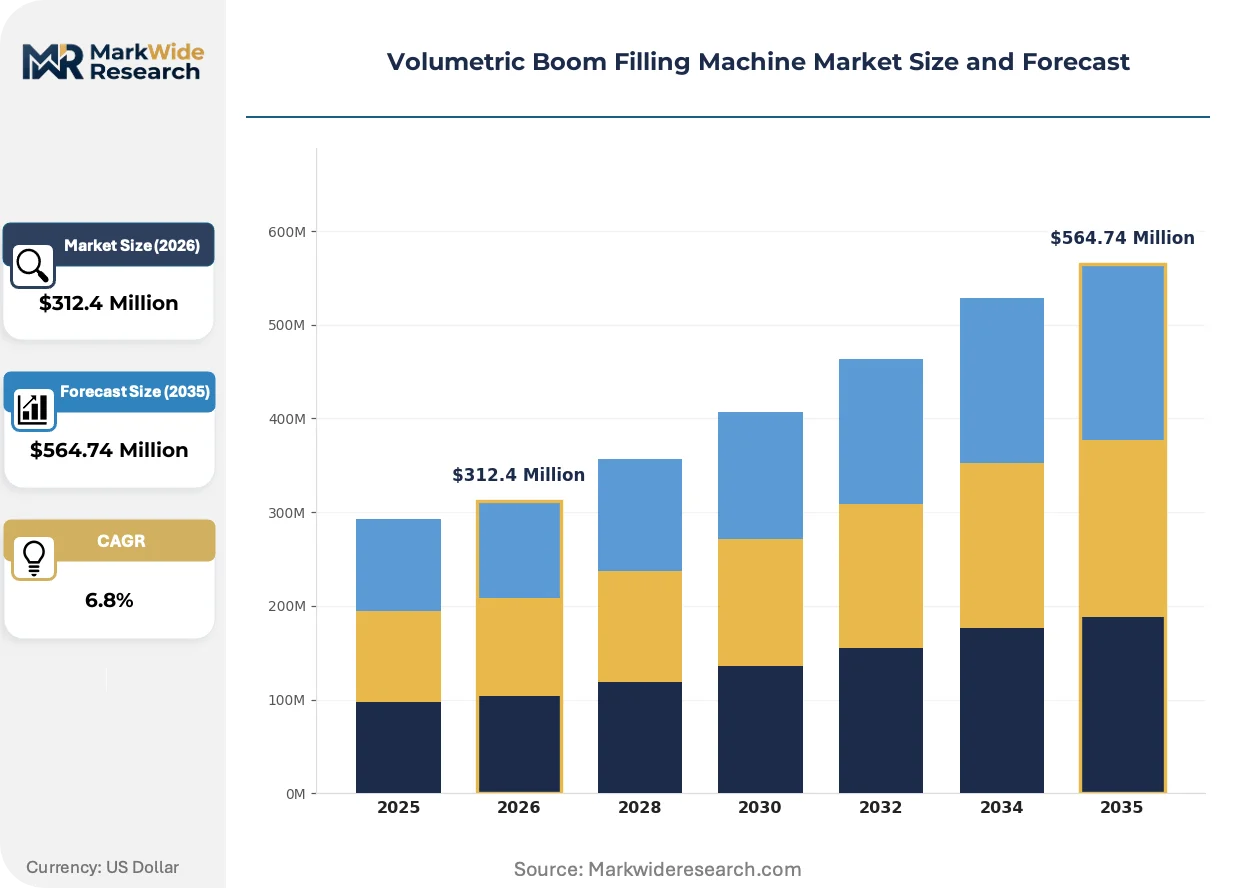
Market Dynamics
Electronic filling systems are displacing pneumatic architectures across pharmaceutical cleanrooms, forcing incumbent suppliers to reengineer control platforms around embedded audit trails and recipe management capabilities.
Growth Catalysts
- FDA cGMP digitization mandates:Pharmaceutical processors must retrofit lines with electronic batch recording, accelerating replacement cycles for legacy pneumatic equipment across US manufacturing corridors.
- EU MDR traceability requirements:Medical device liquid handlers now require material certificates and lineage documentation, favoring suppliers with integrated validation packages.
- Personal care SKU proliferation:Home care brands in Germany's Stuttgart-Karlsruhe industrial belt are scaling multi-head parallel processing to match fragmenting consumer demand without duplicating filling lines.
Market Restraints
- Stainless steel alloy volatility:316L pharmaceutical-grade tubing and piston assemblies face input cost swings tied to nickel supply concentration in Indonesian smelter networks.
- Validation timeline compression:REACH compliance documentation and FDA 21 CFR Part 11 software qualification extend commissioning cycles, freezing capital deployment.
- Aseptic blow-fill-seal substitution:Dairy and juice processors are bypassing standalone boom fillers in favor of integrated blow-mold-fill systems that eliminate secondary packaging steps.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDSCO's tightening GMP enforcement creates demand for isolator-integrated volumetric systems in Hyderabad and Ahmedabad clusters.
- Carbon accounting integration:EU CSRD scope 3 reporting requirements position filling equipment vendors to embed energy monitoring and solvent recovery modules as premium features.
- Service revenue unbundling:Predictive maintenance contracts using IoT vibration sensing on piston drives offer recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven electronic fillers require cross-trained automation engineers fluent in both pneumatic legacy systems and programmable motion control, a skill combination concentrated in southern German and Swiss industrial regions.
- Legacy line integration friction:Brownfield pharmaceutical sites struggle to synchronize electronic batch records from new volumetric booms with existing SCADA architectures dating to the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Boom Filling Machine Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Fillers, Horizontal Fillers, Multi-Head Fillers, Benchtop Fillers End User: Food and Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Mechanical, Electronic, Hybrid Installation: On-Premise, Modular, Mobile, Custom |
| Companies Covered | Krones AG, Sidel Group, Fogg Filler, Coesia, Tetra Pak, ProMach, Barry-Wehmiller Companies, JBT Corporation, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Boom Filling Machine Market Evolving Landscape
Digital validation protocols and servo-electric actuation are converging to compress changeover times and eliminate manual calibration drift, reshaping competitive differentiation around software-defined filling precision rather than mechanical tolerances alone.
Magnetic flow-metered dosing systems with Coriolis mass verification are displacing traditional piston-driven volumetric mechanisms in high-value pharmaceutical applications. Biologics contract manufacturers in Switzerland and Massachusetts are specifying these configurations to achieve plus-or-minus 0.1 percent fill accuracy for protein-based injectables. The technology is displacing incumbent pneumatic architectures by eliminating mechanical wear points and enabling real-time density compensation for temperature-variable biologic formulations.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cold-chain filling operations toward hydrocarbon-based cooling architectures or mechanical refrigeration alternatives. Aseptic dairy processors in Denmark and the Netherlands face retrofit deadlines that cascade into isolator system redesigns for temperature-controlled filling environments. Pharmaceutical exporters to the European Union are pre-emptively specifying equipment compliant with these thermal management constraints to avoid customs detention at Rotterdam and Hamburg.
Direct equipment procurement by beverage and pharmaceutical end-users is compressing distributor margins and fragmenting aftermarket service relationships. Contract packaging organizations in the United States are losing share as CPG brands internalize filling operations to capture batch traceability data required by FDA enforcement discretion letters. This disintermediation is most visible in California and Texas, where craft beverage producers are purchasing volumetric boom systems through manufacturer-direct sales channels rather than regional packaging equipment distributors.
Volumetric Boom Filling Machine Market Segmentation
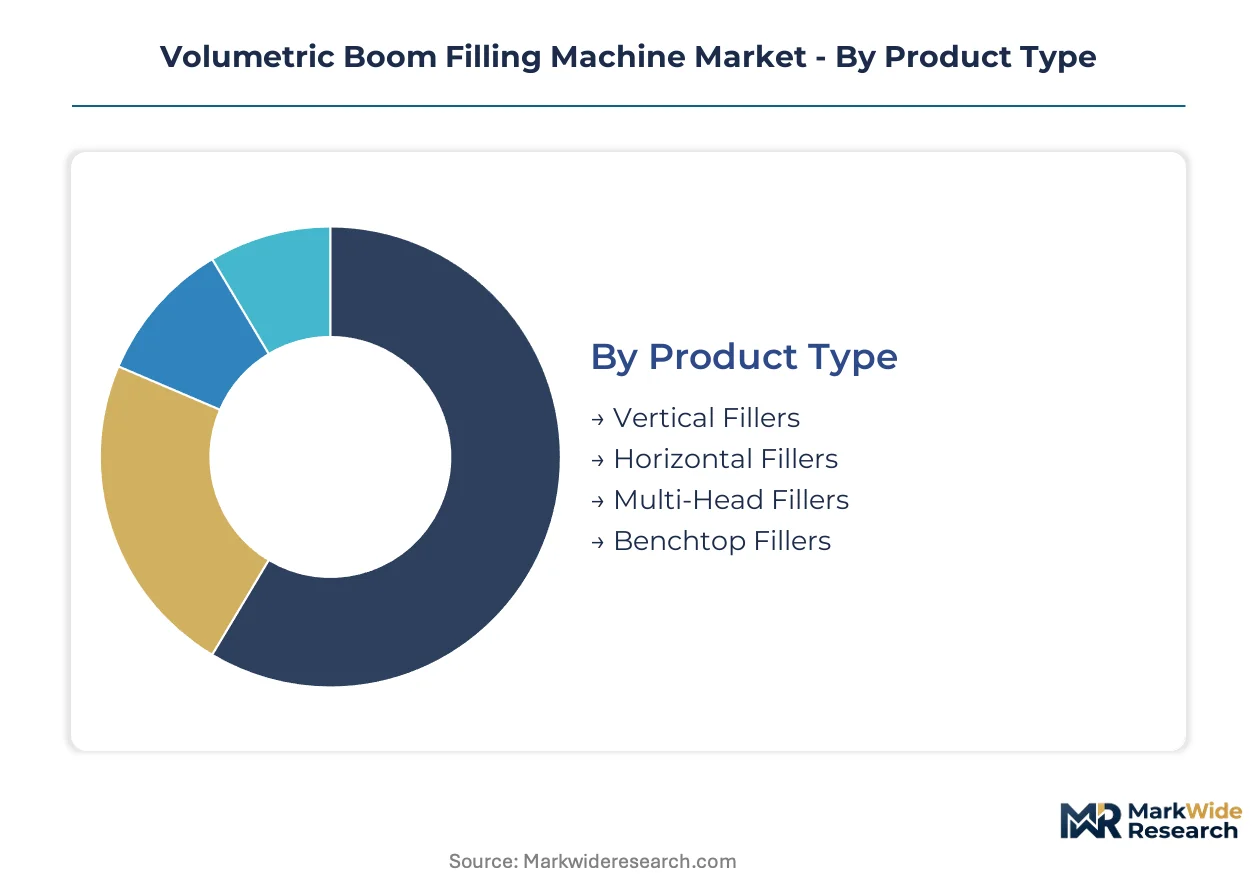
Volumetric boom filling machine segmentation reveals how regulatory complexity and application-specific precision requirements fragment procurement patterns. Each dimension—product architecture, end-use environment, control technology, and installation model—carries distinct compliance obligations that reshape supplier positioning.
Product Type:
REACH and FDA cGMP validation requirements diverge sharply across filling architectures, with stainless steel grade documentation and electronic batch recording capabilities becoming decisive procurement filters.
- Vertical Fillers:Gravity-assisted piston or pump-fed systems with bottom-up filling action minimize foam generation in carbonated beverages and volatile solvents. Beverage producers in Germany's Stuttgart-Karlsruhe corridor specify these for high-speed brewery lines where oxygen pickup control determines shelf stability.
- Multi-Head Fillers:Parallel boom assemblies enable simultaneous filling of multiple containers through synchronized flow-metered or piston-driven valves. Personal care brands scaling SKU proliferation without line duplication drive demand concentration in Germany's industrial belt.
- Horizontal Fillers:Side-entry boom configurations accommodate irregular container geometries and wide-mouth industrial pails. Chemical processors handling thousand-centipoise adhesives and sealants favor these for viscous product handling.
- Benchtop Fillers:Compact single-head units for laboratory-scale production and pilot batch validation. Contract manufacturers in Switzerland and Massachusetts deploy these for biologics process development before commercial scale-up.
Multi-head configurations handle the majority of throughput; benchtop units are climbing the fastest on share as pharmaceutical development pipelines expand.
End User:
Cost tier differentiation separates validation-intensive installations from standard industrial deployments, with audit trail capabilities commanding substantial price premiums.
- Pharmaceuticals:Isolator-integrated systems with embedded 21 CFR Part 11 software qualification and material certificates for 316L pharmaceutical-grade contact surfaces. FDA enforcement discretion letters and EU MDR traceability mandates compel electronic batch recording specifications.
- Chemicals:Hazardous liquid containment systems with EPA spill prevention compliance and OSHA lockout-tagout protocol integration. Processors specify corrosion-resistant alloys and secondary containment booms for aggressive solvents.
- Food and Beverage:Sanitary-design fillers with 3-A sanitary standards compliance and clean-in-place capability. Aseptic dairy processors in Denmark and Netherlands face EU F-Gas Regulation retrofit deadlines cascading into temperature-controlled filling environment redesigns.
- Cosmetics:Flexible format-change systems accommodating viscosity ranges from water-thin toners to high-cream emulsions. Home care brands prioritize rapid changeover without line duplication.
Pharmaceutical specifications absorb the highest capital allocation per installed base; food and beverage represents the steepest expansion trajectory as craft producers internalize filling operations.
Technology:
Control platform maturity determines integration friction with legacy SCADA architectures dating to the 1990s, particularly in brownfield pharmaceutical sites.
- Electronic:Servo-driven actuation with programmable recipe management, real-time density compensation, and direct sensor feedback. Biologics contract manufacturers specify magnetic flow-metered dosing with Coriolis mass verification for protein-based injectables.
- Hybrid:Pneumatic power sections with electronic sequencing and data logging bridges. Transitional architecture for sites modernizing incrementally without full line replacement.
- Pneumatic:Compressed-air-driven piston or diaphragm mechanisms with mechanical limit switches. Legacy installed base faces accelerated replacement cycles under FDA digitization mandates.
- Mechanical:Cam-driven volumetric mechanisms with fixed displacement and minimal electronics. Niche persistence in explosive atmosphere zones where electrical classification is prohibitive.
Electronic platforms dominate new capital deployment; hybrid systems gain share fastest among brownfield retrofit budgets.
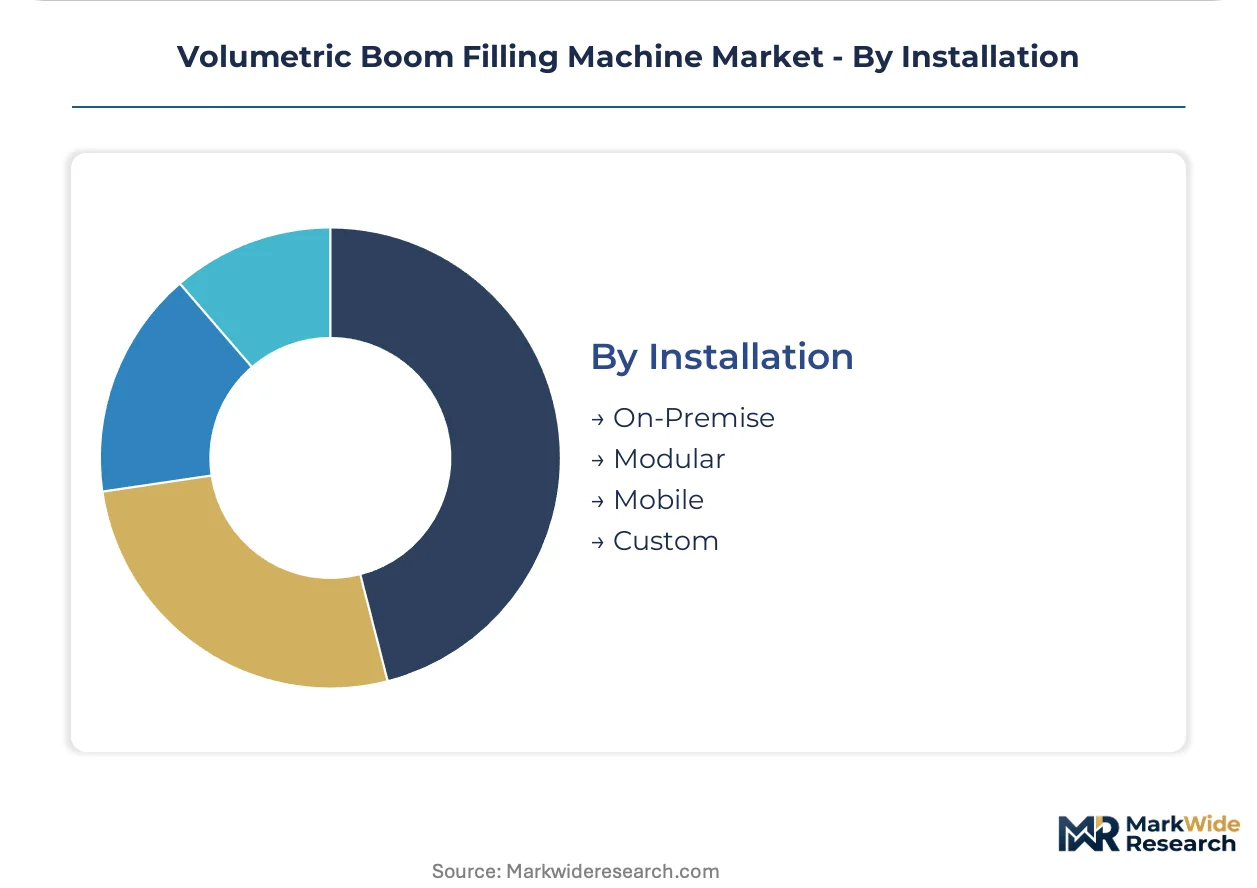
Installation:
Customer type segmentation separates integrated producers from contract packaging organizations, with direct procurement by end-users compressing traditional distributor channels.
- On-Premise:Permanently installed fixed-line systems with dedicated utility infrastructure and validated installation qualification protocols. Pharmaceutical commercial manufacturing sites require this architecture for regulatory submission consistency.
- Modular:Skid-mounted units with standardized utility connections enabling relocation and capacity reconfiguration. Contract manufacturers value redeployment flexibility across product lifecycle transitions.
- Custom:Engineered-to-order systems with isolator integration, specialized containment, or cleanroom-specific architectural features. CDSCO's tightening GMP enforcement in Hyderabad and Ahmedabad clusters drives specification.
- Mobile:Portable units on casters with quick-connect utilities for multi-product campaign manufacturing. Pilot-scale operations and R&D facilities prioritize this flexibility.
On-premise installations anchor the installed base; modular configurations are expanding most quickly as capacity planning emphasizes optionality over commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports volumetric filling systems to pharmaceutical processors across Switzerland and the United States, establishing the Stuttgart-Karlsruhe corridor as the primary trade-flow hub for precision liquid handling equipment.
United States
FDA cGMP digitization mandates and craft beverage producer consolidation drive equipment procurement. Enforcement discretion letters compel electronic batch recording retrofits across Massachusetts and California biologics clusters. Boston-area contract manufacturers specify isolator-integrated systems for protein-based injectables.
Germany
REACH compliance documentation and EU MDR traceability requirements tighten validation protocols for pharmaceutical-grade installations. The country's national chemical regulator enforces material certificate standards for 316L stainless steel contact surfaces. Stuttgart-Karlsruhe industrial belt manufacturers supply multi-head parallel processing systems to home care brands scaling SKU proliferation.
Switzerland
Swissmedic sterility standards and biologics manufacturing concentration elevate demand for magnetic flow-metered dosing configurations. The national pharmaceutical regulator mandates plus-or-minus 0.1 percent fill accuracy for temperature-variable protein formulations. Basel-region contract manufacturers anchor European demand for Coriolis mass verification systems.
India
CDSCO tightening of GMP enforcement creates replacement demand across pharmaceutical contract manufacturing clusters. The national pharmaceutical regulator's inspection intensity accelerates isolator-integrated system specifications. Hyderabad and Ahmedabad manufacturing hubs upgrade from pneumatic legacy equipment to electronic servo-driven platforms.
Denmark
EU F-Gas Regulation phase-down schedules force aseptic dairy processor retrofits toward hydrocarbon-based cooling architectures. The national environmental authority enforces refrigerant-dependent cold-chain filling deadlines. Aarhus-region dairy cooperatives redesign temperature-controlled filling environments to maintain Rotterdam and Hamburg customs clearance.
Volumetric Boom Filling Machine Market Competitive Landscape
Listed leaders compete with private specialists across validation-intensive pharmaceutical installations, creating a tiered structure where public company scale advantages meet family-owned flexibility in custom engineering. The market fragments across three strategic archetypes: rotary platform dominants anchoring brewery retrofits, aseptic blow-fill-seal integrators capturing dairy margin, and pharmaceutical-grade isolator specialists commanding sterility-critical premiums. Dominant competitive moves include backward integration into control software development and geographic expansion through distributor acquisition in emerging pharmaceutical manufacturing clusters.
Within the premium-tier isolator segment, GEA Group and Krones AG exemplify divergent specialization paths, while Sidel Group occupies a position bridging aseptic integration with beverage scale economics. GEA Group represents the pharmaceutical-grade archetype with isolator system dominance. Krones AG anchors rotary filling platform supply to European brewery retrofit cycles. Sidel Group sits within the blow-fill-seal integration tier serving dairy and juice applications where secondary packaging elimination sustains margin.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Fogg Filler |
| Coesia |
| Tetra Pak |
| ProMach |
| Barry-Wehmiller Companies |
| JBT Corporation |
| GEA Group |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German stainless steel fabricators lock in 316L pharmaceutical-grade tubing allocations while freezing input cost visibility for eighteen to twenty-four month windows. Equipment buyers in the Stuttgart-Karlsruhe corridor leverage these arrangements to buffer nickel price volatility originating from Indonesian smelter networks.
Pricing Analysis
Electronic-to-pneumatic generation gaps now span thirty to forty percent at list price, with servo-driven platforms commanding premiums for embedded 21 CFR Part 11 compliance and recipe management capabilities. Three-tier pricing structure across pharmaceutical-grade isolator, standard sanitary-design, and economy mechanical configurations reflects validation documentation intensity and material certification depth. Cost compression in the economy tier is intensifying because chemical processors are consolidating procurement around multi-head platforms with shared spare parts pools. Contract packaging organizations exhibit the highest price sensitivity as direct procurement by beverage and pharmaceutical end-users erodes their volume leverage.
Supply Chain Analysis
Inventory buffers for magnetic flow meters and Coriolis mass sensors now stretch sixteen to twenty weeks as biologics manufacturers in Switzerland and Massachusetts absorb available production slots. Component sourcing concentrates in Germany, Switzerland, and the United States for precision-machined piston assemblies and pharmaceutical-grade seal packages. Raw material dependencies rest on nickel-alloy feedstock, high-purity elastomers, and servo motor drives. Single-source vulnerability around Indonesian nickel refining creates exposure for 316L stainless steel cost bases. Distribution runs through manufacturer-direct channels for large pharmaceutical installations and regional equipment distributors for mid-scale chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts using IoT vibration sensing on piston drives are expanding faster than hardware replacement cycles, creating a service-attach layer that recurs annually rather than capitalizing every seven to ten years.
For Market Incumbents: Compound aftermarket revenue by unbundling predictive maintenance from original equipment sales and establishing captive spare parts distribution in India's Hyderabad and Ahmedabad clusters. Aseptic blow-fill-seal substitution threatens standalone boom filler margins in dairy and juice applications. Certification investment in CDSCO-compliant validation packages captures replacement demand as India's national pharmaceutical regulator tightens GMP enforcement. For New Entrants and Emerging Players: Anchor in India's pharmaceutical contract manufacturing clusters where pneumatic legacy equipment faces accelerated replacement cycles under tightening GMP enforcement. Benchtop fillers for biologics process development in Switzerland and Massachusetts represent the most penetrable segment given lower validation documentation barriers. A go-to-market angle emphasizing rapid electronic retrofit kits for brownfield pharmaceutical sites with 1990s-era SCADA architectures bypasses greenfield capital freezes. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among isolator-integrated system specialists with embedded software platforms and long-term validation support contracts. Long-term viability over a five-to-ten year window favors suppliers with pharmaceutical-grade certification depth and backward integration into control software development. Acquisition targets should display installed base density in FDA-regulated corridors paired with unbundled service revenue exceeding twenty percent of total sales. The signal to watch is CDSCO inspection intensity escalation driving emergency replacement demand in Indian pharmaceutical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Embedded 21 CFR Part 11 compliance eliminates third-party validation dependencies and captures FDA-mandated digitization spend. |
| Isolator System Certification Investment | Swissmedic sterility standards and EU MDR traceability requirements command premium positioning in Basel-region biologics manufacturing. |
| Predictive Maintenance Contract Unbundling | IoT vibration sensing on piston drives converts capital sales into recurring revenue independent of hardware replacement cycles. |
| Geographic Expansion through Distributor Acquisition | Direct procurement by craft beverage producers in California and Texas fragments traditional regional packaging equipment channels. |
| Carbon Accounting Module Integration | EU CSRD scope 3 reporting requirements position energy monitoring and solvent recovery as premium-feature differentiators. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers anchors the qualitative findings in operational reality. Secondary validation draws from FDA 483 observation databases, EMA GMP inspection reports, SEC equipment supplier filings, and customs trade flow records. Bottom-up installed base estimates triangulate against top-down capital expenditure projections from pharmaceutical and chemical processing trade associations.
Sensitivity analysis around nickel price volatility, REACH compliance timeline compression, and FDA enforcement discretion letter frequency tests projection robustness across the analysis window. Segmentation modeling spans product architecture, end-use environment, control technology generation, and installation flexibility. CAGRs derive from weighted average replacement cycle analysis and greenfield capacity addition tracking. Industry-specific forecast inputs include CDSCO inspection intensity indices and EU F-Gas Regulation phase-down schedules affecting temperature-controlled filling environment retrofits.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory digitization mandates and stable stainless steel alloy supply channels; material deviation in Indonesian nickel export policy or FDA enforcement discretion volume would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Oil Packing Machine Market