
 Sanitizer Filling Machine Market | 2026-2036
Sanitizer Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitizer Filling Machine Market Analytics
Automation engineering talent scarcity in Midwestern US manufacturing corridors is reorganizing how OEMs structure service networks and regional assembly. Krones AG sustains its European installed base through captive technical training academies. GEA Group competes by leveraging backward integration into servo-drive motion control systems. Bhagwati Pharma anchors South Asian demand with localized stainless-steel fabrication and shorter commissioning cycles.
Sanitizer filling machines are precision liquid handling systems built from 316L stainless steel contact surfaces, servo-driven volumetric pistons or mass-flow meters, and PLC-controlled conveyor indexing, designed to dispense antiseptic gels, foams, and sprays into primary containers at rates from 20 to 600 units per minute with fill accuracy within plus or minus 0.5 percent. Gravity filling technology dominates high-volume alcohol-based sanitizer lines where low-viscosity liquids permit passive head-pressure dispensing without mechanical shear. Fully automatic systems command the replacement cycle as pharmaceutical end users retire semi-automatic equipment to meet FDA 21 CFR Part 11 electronic record requirements. Contract packers represent the fastest-growing end-user category, absorbing overflow capacity from consumer brands that avoid capital deployment on dedicated lines.
FDA cGMP inspections, EU MDR technical documentation requirements, and EPA FIFRA registration protocols collectively determine machine design specifications, material certifications, and validation documentation burdens for cross-border equipment shipments. The EPA registers disinfectant formulations under FIFRA, which indirectly shapes filling line cleanability requirements and chemical compatibility testing. Stakeholders must monitor evolving EPA enforcement priorities around sanitizer efficacy claims and corresponding label verification protocols that filling equipment must support through vision inspection integration.
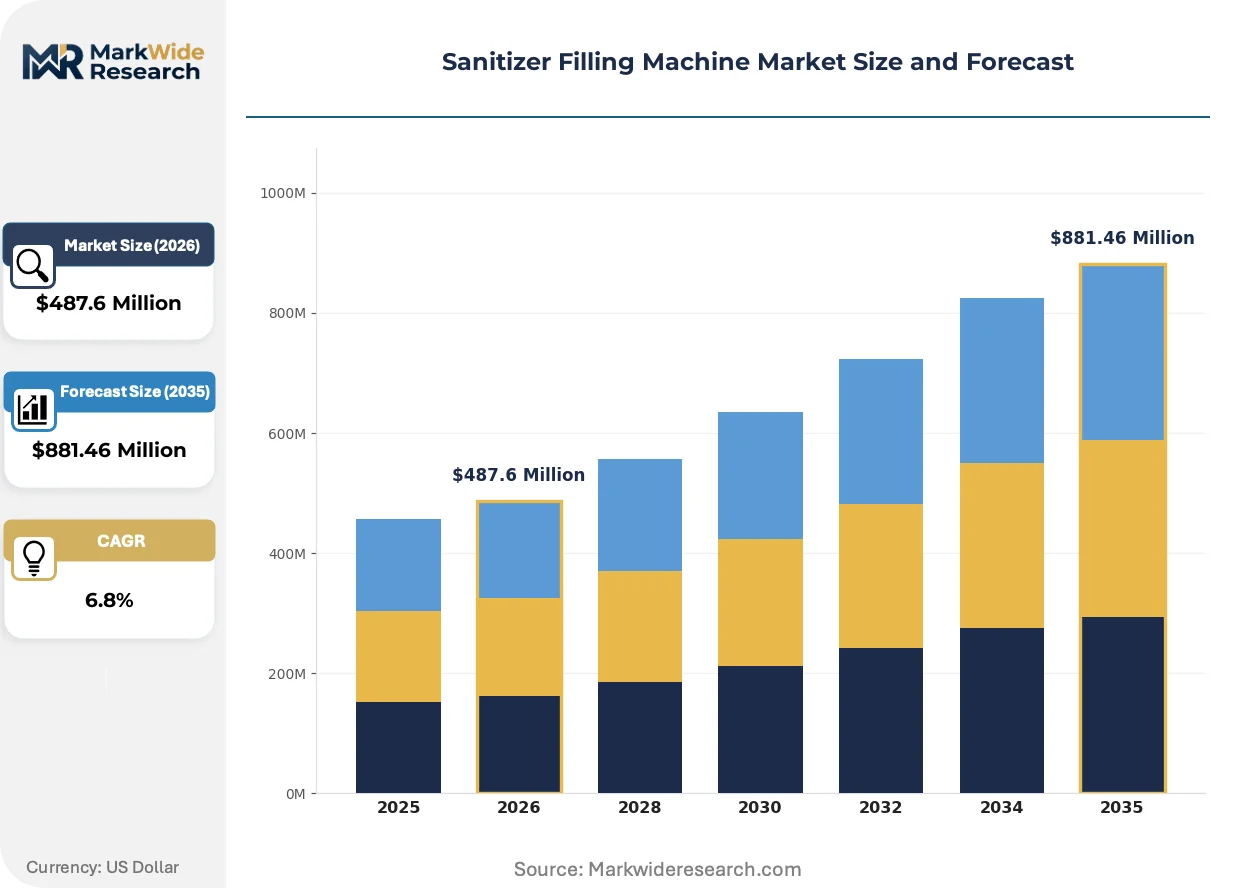
Market Dynamics
Pharmaceutical contract packers are consolidating bottling demand around fully automatic lines to satisfy FDA 21 CFR Part 11 electronic record mandates, compressing replacement cycles for semi-automatic equipment and reshaping how OEMs configure regional service networks.
Growth Catalysts
- FDA cGMP Inspections:Pharmaceutical end-users are retiring legacy semi-automatic equipment to meet validated clean-in-place protocol requirements, accelerating capital deployment toward servo-driven volumetric systems with integrated vision inspection.
- Germany:Contract packers in Baden-Württemberg and Bavaria are absorbing overflow capacity from consumer brands that avoid dedicated line investments, concentrating demand for high-speed alcohol-based sanitizer filling systems.
- 316L Stainless Steel Fabrication:Localized supply of certified contact surfaces in India and the United States is shortening commissioning cycles and reducing import dependency for critical machine components.
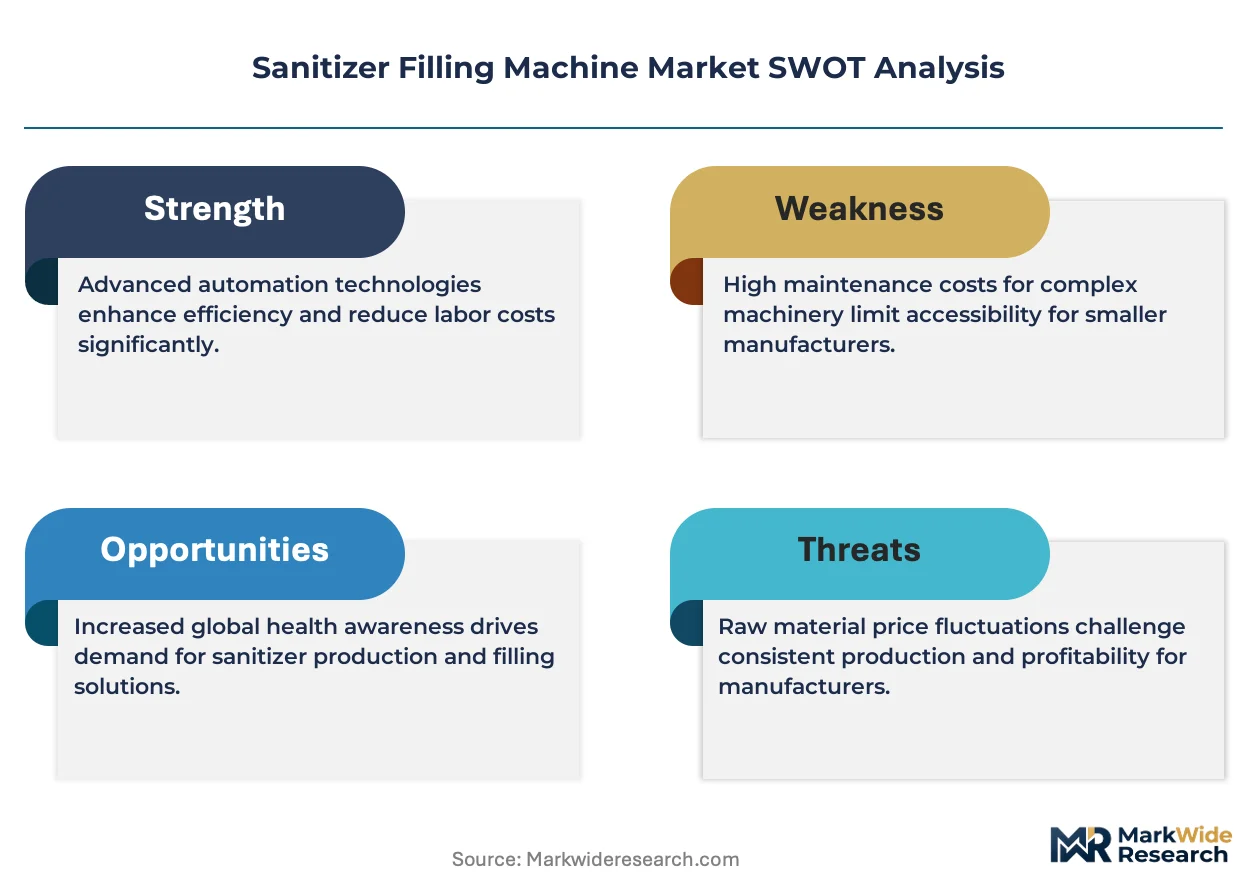
Market Restraints
- Servo-Drive Component Concentration:Motion control systems for precision volumetric pistons rely on concentrated supply from German and Japanese electromechanical suppliers, exposing lead time volatility.
- EU MDR Technical Documentation:Cross-border equipment shipments face escalating validation documentation burdens for material certifications and traceability protocols, extending sales cycles.
- Gravity Filling Limitation:Passive head-pressure dispensing technology cannot accommodate high-viscosity gel formulations above 5000 centipoise, restricting application range for premium foam and cream products.
Strategic Opportunities
- India:Domestic pharmaceutical manufacturing under the PLI scheme is expanding bottling capacity for alcohol-based formulations, creating demand for localized stainless-steel fabrication and shorter commissioning cycles.
- Mass-Flow Meter Convergence:Integration of Coriolis mass-flow measurement with PLC-controlled conveyor indexing is enabling real-time fill verification without mechanical shear, opening premium foam and spray segments.
- EPA FIFRA Registration Tailwind:Disinfectant formulation registrations are tightening label verification protocols, creating pull-through demand for vision inspection integration and automated rejection systems.
Industry Challenges
- Automation Engineering Talent Scarcity:Midwestern United States manufacturing corridors face acute shortages of PLC programming and servo-drive commissioning specialists, forcing OEMs to restructure technical training academies and captive service networks.
- Clean-In-Place Validation Timeline:FDA cGMP compliance requires documented protocol execution for 316L contact surface sterilization, extending factory acceptance testing and site qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitizer Filling Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Portable End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food Industry, Contract Packers Filling Technology: Gravity Filling, Positive Displacement, Pump Filling, Overflow Filling Container Type: Plastic Bottles, Glass Bottles, Pouches, Jars |
| Companies Covered | Krones AG, Tetra Pak, Syntegon Technology, GEA Group, Accutek Packaging Equipment Companies, Apacks, Bhagwati Pharma, Clearpack Group, Filling Equipment Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitizer Filling Machine Market Evolving Landscape
Precision liquid handling systems are converging with validated electronic record-keeping and real-time inspection technologies, compressing the functional gap between pharmaceutical-grade and consumer-packaged-goods equipment specifications.
Mass-flow meter technology using Coriolis measurement principles is displacing traditional volumetric piston systems in high-value foam and spray applications. Pharmaceutical contract packers in Germany and the United States are adopting these systems at accelerated pace to capture premium formulation contracts. This displacement is compressing price premiums for mechanical piston OEMs while expanding addressable market for meter-based suppliers.
EU MDR technical documentation requirements are mandating enhanced material traceability and risk management files for equipment with patient-contact implications. Machine builders must now supply complete 316L stainless steel certification chains and post-market surveillance protocols. Filling line manufacturers serving European pharmaceutical end-users are responding by embedding QR-coded component tracking and automated documentation generation into standard configurations.
After-sales service unbundling is fragmenting traditional OEM revenue models as contract packers in India and the United States negotiate standalone technical training and spare parts sourcing agreements. Third-party maintenance providers are capturing routine calibration and seal replacement work that previously anchored long-term service contracts. This shift is most visible among mid-volume pharmaceutical bottlers in Gujarat and Ohio seeking to reduce total cost of ownership through competitive service sourcing.
Sanitizer Filling Machine Market Segmentation
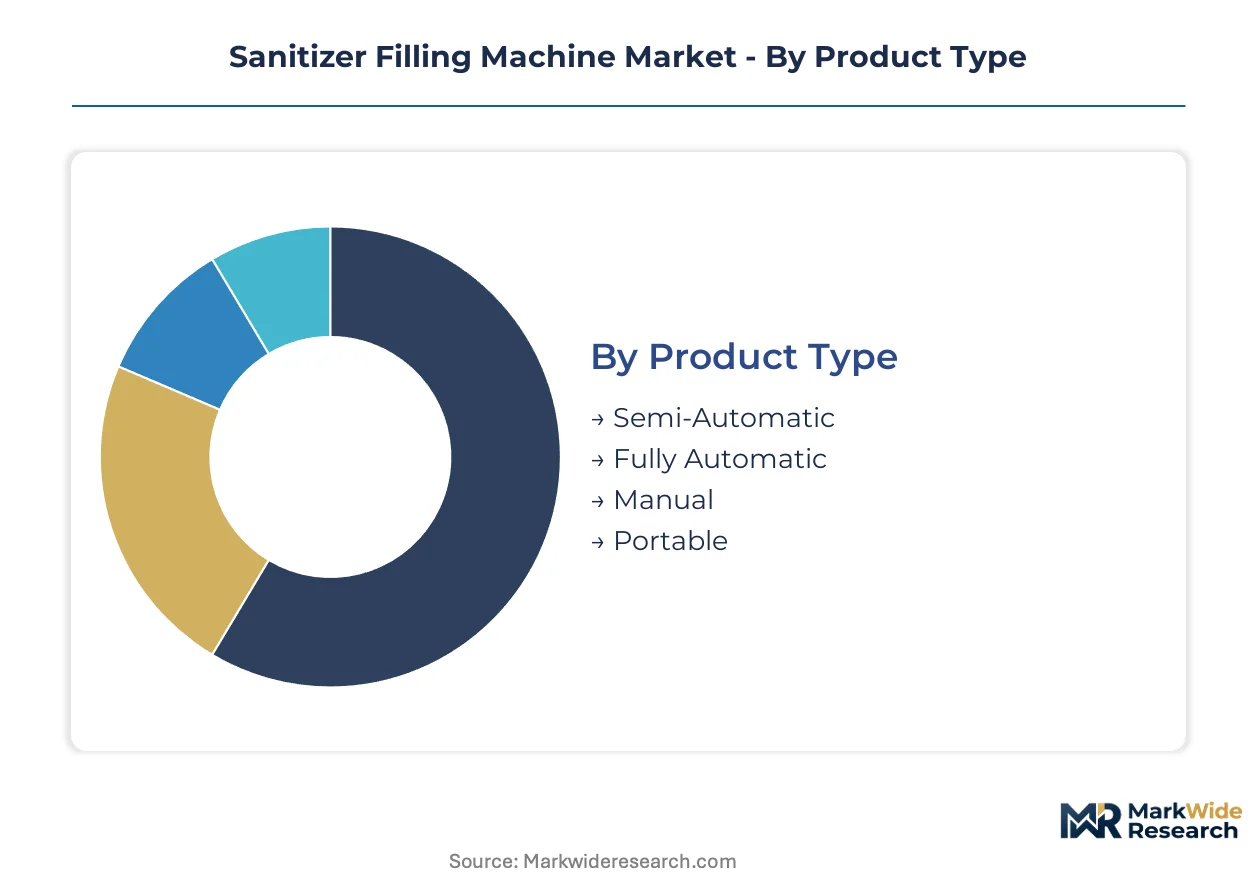
Machine configurations diverge sharply across regulatory compliance tiers, with FDA 21 CFR Part 11 mandates compressing equipment replacement cycles in pharmaceutical-grade segments while cost-sensitive consumer brands sustain demand for semi-automatic alternatives.
Product Type:
FDA cGMP and EU MDR validation requirements are splitting procurement patterns between validated automatic systems and legacy semi-automatic equipment.
- Fully Automatic:Servo-driven volumetric systems with integrated vision inspection and electronic batch records dominate pharmaceutical contract packing. German and US pharmaceutical end-users are retiring semi-automatic lines to satisfy FDA 21 CFR Part 11 mandates, accelerating capital deployment toward validated clean-in-place protocols.
- Semi-Automatic:Operator-assisted gravity filling stations serve mid-volume cosmetic manufacturers and regional sanitizer brands in India. PLI scheme beneficiaries in Gujarat are absorbing these systems for alcohol-based formulation bottling where throughput requirements fall below 100 units per minute.
- Manual:Bench-top piston fillers address micro-batch production and pilot-scale formulation testing.
- Portable:Mobile filling units support disaster relief deployment and temporary manufacturing surge capacity.
Fully automatic systems handle the majority of throughput; portable units are gaining share fastest among emergency response procurement channels.
End User:
Customer procurement authority concentrates with technical buyers who specify 316L certification chains and validation documentation depth.
- Contract Packers:Third-party bottlers in Baden-Württemberg, Bavaria, and Ohio absorb overflow capacity from consumer brands avoiding dedicated line investments. These operators prioritize rapid format changeover and multi-SKU flexibility to capture seasonal sanitizer demand surges.
- Pharmaceutical Companies:In-house bottling divisions at firms with EPA FIFRA-registered disinfectant portfolios require integrated vision inspection for label verification. FDA inspection intensity is forcing replacement of legacy equipment lacking electronic record capabilities.
- Cosmetic Manufacturers:Beauty brands with sanitizer line extensions source semi-automatic systems for gel and foam variants.
- Food Industry:Beverage and dairy processors repurpose filling lines for alcohol-based hand sanitizer during demand spikes.
Contract packers command the largest installed base; pharmaceutical companies are expanding most quickly as vertical integration resumes post-pandemic.
Filling Technology:
Viscosity tolerance and shear sensitivity determine technology selection across foam, gel, and spray formulation portfolios.
- Gravity Filling:Passive head-pressure dispensing dominates high-volume alcohol-based sanitizer lines where low-viscosity liquids permit flow without mechanical shear. German contract packers standardize on this technology for ethanol formulations below 5000 centipoise.
- Positive Displacement:Volumetric piston systems deliver fill accuracy within plus or minus 0.5 percent for high-viscosity gel and cream products. Indian pharmaceutical manufacturers specify servo-driven variants with 316L contact surfaces for domestic PLI scheme production.
- Pump Filling:Peristaltic and lobe pump configurations handle shear-sensitive foam formulations with integrated Coriolis mass-flow verification.
- Overflow Filling:Level-sensing technology ensures cosmetic visual fill height consistency for transparent container presentation.
Gravity filling handles the majority of throughput; positive displacement is climbing the fastest as gel formulation portfolios expand.
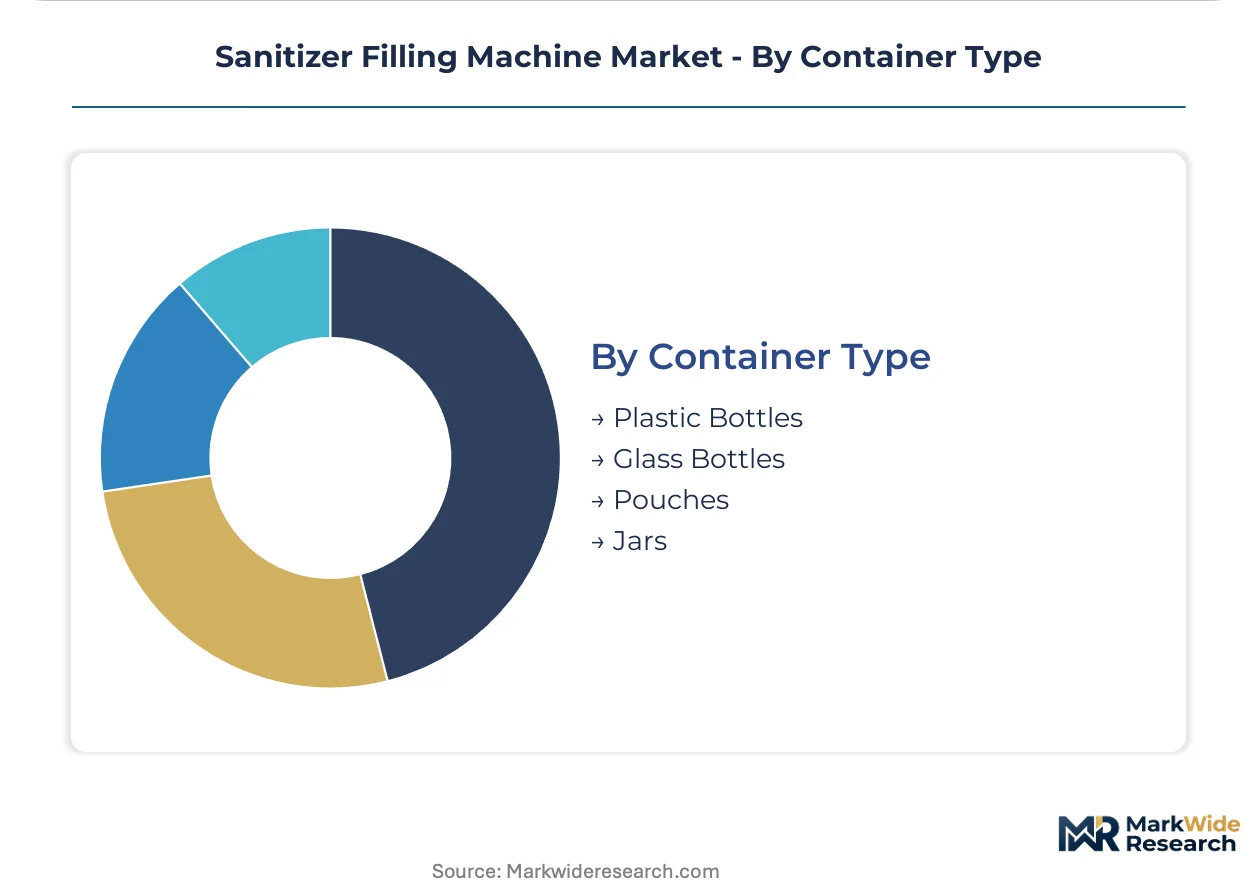
Container Type:
Material compatibility testing and capping torque specifications vary substantially across primary packaging formats.
- Plastic Bottles:HDPE and PET containers from 50ml to 1 liter dominate retail sanitizer distribution. US and Indian converters supply certified resin grades that withstand alcohol-based formulation chemical attack without stress cracking.
- Pouches:Flexible film sachets address single-use and travel-size segments with reduced shipping cube. Indian contract packers are adopting form-fill-seal integration for alcohol-based gel pouches under domestic manufacturing incentives.
- Glass Bottles:Premium cosmetic and pharmaceutical presentations specify borosilicate or amber glass for UV protection.
- Jars:Wide-mouth containers accommodate cream and lotion-style sanitizer formulations for institutional dispensing.
Plastic bottles handle the majority of throughput; pouches are expanding most quickly in emerging market single-use segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP enforcement intensity in the United States is compressing equipment replacement cycles and reshaping regional demand patterns across pharmaceutical manufacturing corridors worldwide.
United States
Contract packers in Ohio and Wisconsin absorb overflow capacity from consumer brands avoiding dedicated capital deployment. FDA 21 CFR Part 11 mandates force retirement of semi-automatic lines lacking electronic batch records. Midwestern automation engineering talent scarcity is pushing OEMs toward captive technical training academies.
Germany
Baden-Württemberg and Bavaria host concentrated contract packing operations serving pan-European sanitizer brands. EU MDR technical documentation requirements impose escalating validation burdens for cross-border equipment shipments. Krones AG sustains its installed base through regional service networks anchored in these southern industrial clusters.
India
Domestic pharmaceutical manufacturing under the PLI scheme expands bottling capacity for alcohol-based formulations. CDSCO compliance requirements and state-level manufacturing incentives in Gujarat and Maharashtra concentrate demand for localized 316L stainless steel fabrication. Bhagwati Pharma anchors South Asian supply with shorter commissioning cycles.
China
Yangtze River Delta pharmaceutical exporters face NMPA Good Manufacturing Practice alignment with FDA cGMP standards for equipment qualification. Domestic machine builders capture mid-volume contract packing demand through cost-competitive servo-drive integration. Shanghai and Jiangsu province clusters specialize in vision inspection module manufacturing.
Japan
PMDA pharmaceutical manufacturing inspections enforce validated clean-in-place protocols comparable to FDA intensity. METI industrial automation incentives support precision filling equipment upgrades in Osaka and Nagoya pharmaceutical corridors. Japanese electromechanical suppliers concentrate motion control component supply for regional OEMs.
Sanitizer Filling Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with European and Asian fabricators occupying distinct competitive positions based on regulatory compliance depth and regional service reach. The market structure rewards validated system documentation capabilities and captive technical training infrastructure. Two strategic archetypes dominate: integrated packaging line suppliers with backward control over motion control components, and regional stainless-steel fabricators with localized commissioning expertise. Competitive moves concentrate on geographic service network expansion and technology licensing partnerships for mass-flow meter integration.
Among Germany-based integrated suppliers, Krones AG and GEA Group exemplify the premium-tier archetype through captive supply of servo-drive systems and validated electronic record platforms. Bhagwati Pharma occupies a position within the regional fabricator tier, representing Indian specialists that compete through localized 316L contact surface production and compressed site qualification timelines.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Pak |
| Syntegon Technology |
| GEA Group |
| Accutek Packaging Equipment Companies |
| Apacks |
| Bhagwati Pharma |
| Clearpack Group |
| Filling Equipment Co. Inc. |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 11 validation requirements gate both supplier qualification and price differentiation simultaneously, forcing pharmaceutical end-users to pay premiums for documented electronic record capabilities while excluding uncertified fabricators from procurement shortlists. This regulatory filter compresses margin structures for mid-tier OEMs caught between validated system investments and price competition from regional stainless-steel specialists.
Pricing Analysis
German and US contract packers face 15-25 percent price spreads against Indian and Chinese suppliers for equivalent throughput specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation documentation depth and 316L certification chain completeness. Cost compression in the standard tier is intensifying because regional fabricators in Gujarat and Jiangsu are capturing mid-volume pharmaceutical contracts with shorter commissioning timelines. Cosmetic manufacturers and regional sanitizer brands exhibit highest price sensitivity; pharmaceutical companies with EPA FIFRA-registered portfolios show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Germany and Japan anchor precision servo-drive and motion control component fabrication for volumetric piston systems. India and China draw from localized 316L stainless steel foundries and CNC machining clusters to shorten lead times for contact surface production. Single-source vulnerability concentrates in German and Japanese electromechanical suppliers for precision filling heads. Distribution runs through OEM-direct channels for validated pharmaceutical systems and regional distributor networks for semi-automatic consumer-grade equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PLC programming and servo-drive commissioning expertise scarcity is restructuring competitive advantage toward captive technical training infrastructure and documented validation capabilities rather than hardware differentiation alone.
For Market Incumbents: Compound regional service network density through technical training academy investments in Midwestern US and Bavarian corridors to offset automation engineering talent scarcity. Deepen backward integration into Coriolis mass-flow meter technology to defend against meter-based suppliers displacing mechanical piston systems in premium foam applications. Prioritize EPA FIFRA registration alignment for vision inspection modules to capture disinfectant formulation label verification demand. For New Entrants and Emerging Players: After-sales service unbundling presents white-space opportunity where incumbents resist standalone spare parts and technical training contracts. Target mid-volume pharmaceutical bottlers in Gujarat and Ohio seeking competitive service sourcing to reduce total cost of ownership. Penetrate through third-party maintenance provider partnerships for routine calibration and seal replacement work. For Investors and Strategic Acquirers: EU MDR technical documentation requirements reshape the acquisition landscape toward machine builders with embedded QR-coded component tracking and automated documentation generation capabilities. Long-term viability centers on validated system documentation depth rather than production scale alone. Monitor CDSCO and NMPA Good Manufacturing Practice alignment intensity as signal for regional compliance investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Mass-Flow Meter Technology Licensing | Coriolis integration opens premium foam segments without mechanical shear limitations. |
| Captive Technical Training Academy Expansion | Krones AG sustains European installed base through regional specialist pipelines. |
| Localized 316L Stainless Steel Fabrication | Bhagwati Pharma compresses commissioning cycles through Indian supply chain control. |
| Vision Inspection Module Integration | EPA FIFRA label verification protocols pull through automated rejection system demand. |
| QR-Coded Component Tracking Implementation | EU MDR material traceability mandates require complete certification chain documentation. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical contract packing operations directors, FDA compliance officers at sanitizer manufacturers, servo-drive OEM procurement teams, and 316L stainless steel fabrication plant managers, then refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EPA FIFRA registration databases, EU MDR technical documentation requirements, and customs trade data for filling equipment imports. Bottom-up equipment shipment analysis and top-down pharmaceutical manufacturing capacity modeling were triangulated against regional regulatory filing patterns.
Variance decomposition across machine configuration, filling technology, end-user category, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand modeling incorporating pharmaceutical contract packer capacity expansion plans, PLI scheme beneficiary identification, and EPA enforcement priority shifts. Industry-specific inputs included validated clean-in-place protocol adoption timelines and Coriolis mass-flow meter penetration curves in foam formulation segments.
Forecasts assume regulatory continuity in FDA cGMP, EU MDR, and CDSCO enforcement regimes; material policy shifts around electronic record mandates or stainless steel certification requirements would require re-modeling. Specific risks include servo-drive component supply disruption from German and Japanese electromechanical suppliers and accelerating after-sales service unbundling compressing OEM recurring revenue streams. Recalibration cycles align with material shifts in FDA inspection intensity, PLI scheme expansion phases, and mass-flow meter technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Foil Embossing Machine Market