
 Flow Wrap Machines Market | 2026-2036
Flow Wrap Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Wrap Machines Market Analysis
Buyer concentration among multinational food processors is hardening as contract manufacturers consolidate purchasing decisions across regional networks. Syntegon leverages its R&D intensity to dominate servo-driven horizontal platforms for bakery applications. ULMA Packaging anchors its position through backward integration into film handling systems, giving it upstream control over line integration performance. Bosch Packaging Technology competes on manufacturing scale, sustaining output volumes that serve high-throughput frozen food facilities across multiple continents.
Flow wrap machines form, fill, and seal flexible film around products using continuous motion rotary jaw or box-motion sealing mechanisms, typically operating at 30 to 300 cycles per minute depending on product dimensions and film substrate. These systems serve primary commercial purposes in food, pharmaceutical, and consumer goods sectors where hermetic seals, extended shelf life, and retail-ready presentation are required. Horizontal flow wrap configurations occupy the largest installed base due to their versatility across bakery and confectionery formats, while automatic flow wrap lines represent the fastest-growing technology tier as labor costs reshape capital allocation in emerging manufacturing economies. Thermoforming technology leads technology segmentation in value terms, though ultrasound sealing is displacing conventional hot melt approaches in moisture-sensitive pharmaceutical applications where heat degradation poses formulation risks.
The FDA enforces 21 CFR Part 110 and FSMA preventive controls that dictate sanitary design standards for flow wrap equipment contacting food surfaces, while the EU Machinery Directive 2006/42/EC mandates CE conformity for automated packaging lines sold across member states. ECHA's REACH restrictions on certain plasticizers and film additives are forcing equipment suppliers to validate compatibility with reformulated sealant layers. Stakeholders must monitor how evolving extended producer responsibility frameworks in North America and Europe reshape total cost of ownership calculations for film-based packaging systems.
Market Dynamics
Food processors in Brazil and Mexico are consolidating purchasing decisions across regional contract manufacturing networks, hardening buyer concentration and forcing equipment suppliers to prove line integration performance at scale.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening material recovery requirements for flexible packaging equipment are accelerating capital replacement cycles in European food processing facilities.
- Bakery automation clusters:Germany's Bavaria industrial corridor has deepened capital deployment into horizontal flow wrap systems, creating concentrated demand pull for servo-driven platforms.
- Shelf-stable snack lines:Food processing plants across Latin America are expanding flow wrap adoption, driving equipment orders for hermetic sealing configurations.
Market Restraints
- Film substrate volatility:ECHA's REACH restrictions on certain plasticizers and sealant additives are forcing equipment suppliers to validate compatibility with reformulated layers, extending qualification timelines.
- Supplier concentration risk:Backward integration into film handling systems by dominant packaging OEMs limits third-party line integration options for mid-tier processors.
- Technical ceiling:Conventional hot melt sealing approaches face displacement limits in moisture-sensitive pharmaceutical applications where ultrasound sealing remains capital-intensive.
Strategic Opportunities
- Pharmaceutical convergence:Ultrasound sealing technology paired with thermoforming systems opens white space in moisture-sensitive drug packaging where heat degradation poses formulation risks.
- Extended producer responsibility frameworks:North American and European EPR schemes are reshaping total cost of ownership calculations, creating service-contract opportunities for film recovery integration.
- Emerging manufacturing economies:Labor cost pressures in Southeast Asian contract manufacturing hubs are accelerating automatic flow wrap line adoption.
Industry Challenges
- Sanitary design certification:FDA 21 CFR Part 110 and FSMA preventive controls mandate complex validation protocols for food-contact surfaces, compressing deployment timelines.
- Legacy system integration:Frozen food facilities running high-throughput lines face friction retrofitting servo-driven horizontal platforms into existing plant layouts without full line stoppage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Wrap Machines Market |
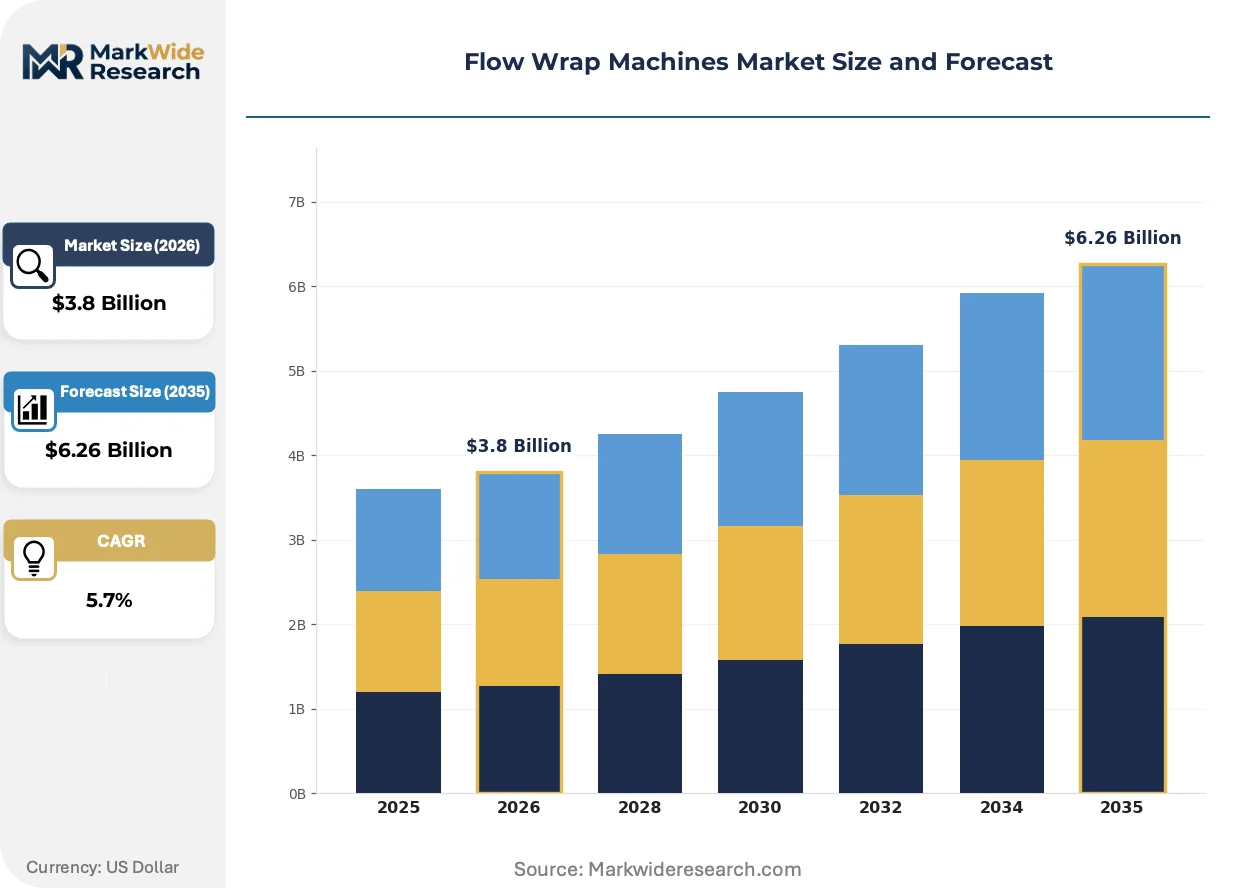
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Flow Wrap, Horizontal Flow Wrap, Automatic Flow Wrap, Manual Flow Wrap End User: Food Processing, Pharmaceuticals, Cosmetics, Electronics Technology: Thermoforming, Cold Seal, Hot Melt, Ultrasound Application: Snack Packaging, Bakery Products, Confectionery, Frozen Foods |
| Companies Covered | Bosch Packaging Technology, Syntegon, ULMA Packaging, IMA Group, PFM Packaging, Coesia Group, MULTIVAC, FUJI Machinery, Cavanna Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Wrap Machines Market Emerging Trajectories
Equipment architecture is pivoting toward modular servo configurations that decouple mechanical complexity from control intelligence, enabling faster format changeovers without full mechanical rebuilds.
Servo-driven motion control is consolidating market preference across bakery and confectionery applications. Mid-sized processors in Germany's industrial corridors are adopting these platforms at accelerated pace. This consolidation is compressing margins for mechanical cam-driven alternatives while rewarding suppliers with captive software ecosystems.
REACH restrictions on plasticizers and film additives are forcing reformulation of sealant chemistries across European supply chains. Equipment manufacturers must now validate jaw sealing temperatures and dwell times against narrower processing windows. Pharmaceutical packaging lines are responding fastest, prioritizing ultrasound sealing to bypass heat-dependent validation entirely.
Contract manufacturers are unbundling after-sales service from capital purchase decisions, treating maintenance and spare parts as separately negotiated cost centers. This shift is disrupting traditional OEM revenue models in high-throughput frozen food facilities. Brazil and Mexico show the clearest geographic expression, where regional networks centralize procurement across multiple plant locations.
Flow Wrap Machines Market Segmentation
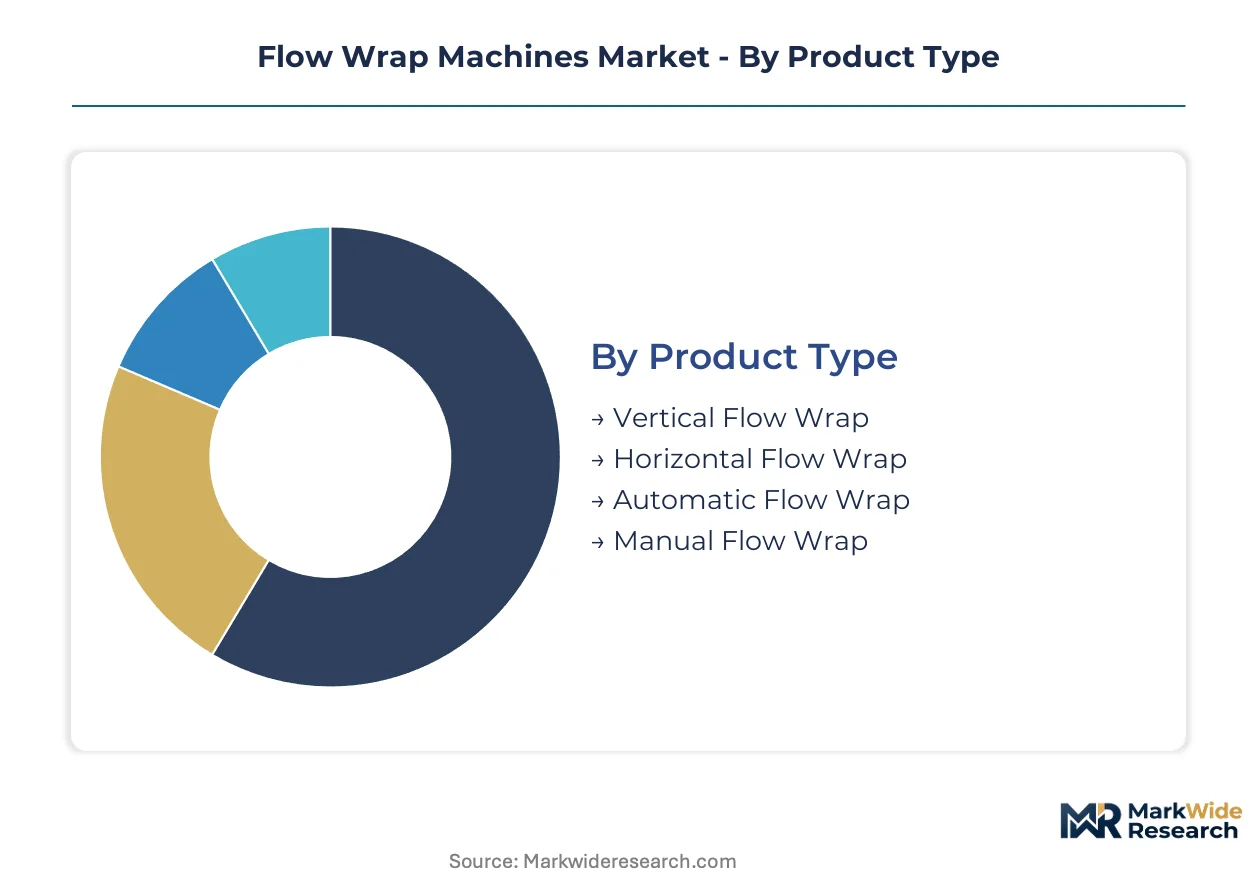
Flow wrap machine procurement decisions hinge on line integration depth, with standalone units serving regional bakeries and fully embedded systems dominating multinational frozen food networks. Equipment specification varies sharply across these deployment modes, reshaping supplier engagement models and service contract structures.
Product Type:
Standalone vertical configurations serve batch-oriented processors, while embedded horizontal systems anchor continuous-motion production lines in high-volume facilities.
- Horizontal Flow Wrap:Rotary jaw or box-motion sealing mechanisms operate at 30 to 300 cycles per minute, accommodating bakery and confectionery formats with minimal changeover downtime. Germany's Bavaria industrial corridor has concentrated capital deployment here, with servo-driven platforms capturing preference among automation clusters seeking format flexibility without mechanical rebuilds.
- Automatic Flow Wrap:Continuous-motion architectures integrate feeding, wrapping, and discharge modules under unified control systems. Southeast Asian contract manufacturing hubs are accelerating adoption as labor cost pressures reshape capital allocation toward unmanned operation.
- Vertical Flow Wrap:Gravity-fed product infeed suits irregular shapes and single-serve portions in mid-tier snack operations.
- Manual Flow Wrap:Foot-pedal or hand-crank actuation serves micro-producers and pilot-scale validation labs with sub-50 unit hourly throughput.
Horizontal configurations lead volumes today; automatic systems are gaining share fastest.
End User:
Margin structures diverge sharply between regulated pharmaceutical packaging and price-sensitive food processing procurement.
- Food Processing:Hermetic sealing requirements for shelf-stable snacks and frozen entrees drive specification of multi-zone temperature control and gas-flush compatibility. Brazil and Mexico are expanding regional contract manufacturing networks, hardening buyer concentration and forcing equipment suppliers to prove line integration performance at scale.
- Pharmaceuticals:FDA 21 CFR Part 110 and EMA GMP Annex 1 mandate sanitary design standards for all product-contact surfaces, compressing deployment timelines and elevating documentation burdens. Moisture-sensitive drug packaging is displacing conventional hot melt approaches with ultrasound sealing to bypass heat-dependent validation entirely.
- Cosmetics:Retail-ready presentation requirements prioritize film clarity and registration accuracy over sealing speed.
- Electronics:Anti-static film handling and ESD-controlled environments dominate specification sheets for semiconductor component packaging.
Food processing anchors installed base; pharmaceutical applications show steepest expansion trajectory.
Technology:
Capital intensity and operating cost trade-offs separate legacy thermal methods from emerging non-contact sealing approaches.
- Thermoforming:Vacuum-assisted cavity formation creates rigid trays from continuous film webs, dominating value terms across protein and dairy packaging. ECHA REACH restrictions on plasticizers are forcing equipment suppliers to validate jaw sealing temperatures against narrower processing windows.
- Ultrasound:High-frequency mechanical vibration generates localized heat at film interfaces without thermal mass, eliminating heat degradation risks in moisture-sensitive pharmaceutical applications. Paired with thermoforming systems, this opens white space in drug packaging where formulation stability is paramount.
- Hot Melt:Adhesive dispensing systems suit porous substrates and heavy-duty industrial wrapping with lower capital thresholds.
- Cold Seal:Pressure-activated cohesive coatings enable chocolate and heat-sensitive confectionery wrapping without thermal conditioning.
Thermoforming leads value capture; ultrasound sealing climbs the fastest.
Application:
Product fragility and barrier requirements dictate machine architecture selection across temperature-sensitive categories.
- Frozen Foods:High-throughput lines demand servo-driven horizontal platforms capable of maintaining seal integrity across -18°C to ambient thermal shock. Retrofitting these into existing plant layouts without full line stoppage creates friction for legacy facilities running mechanical cam-driven alternatives.
- Snack Packaging:Gas-flush and hermetic sealing configurations preserve crispness in shelf-stable formats. Latin American processing plants are expanding flow wrap adoption specifically for this application, driving equipment orders with modified atmosphere capability.
- Bakery Products:Crumb management and gentle product handling prioritize box-motion over rotary jaw mechanisms for delicate pastries.
- Confectionery:High-speed registration and precise film cutting accommodate seasonal volume spikes and promotional format changes.
Frozen foods command highest average selling prices; snack packaging shows strongest volume momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Bavaria industrial corridor has concentrated capital deployment into horizontal flow wrap systems, while Brazil's contract manufacturing networks are hardening buyer concentration across Latin American snack processing.
United States
Frozen food facilities in the Midwest and Southeast are retrofitting servo-driven horizontal platforms into existing plant layouts. FDA 21 CFR Part 110 and FSMA preventive controls mandate sanitary design standards that compress deployment timelines for food-contact surfaces. Chicago's industrial corridor anchors high-throughput line integration demand from multinational processors.
Germany
Bakery automation clusters in Bavaria and Baden-Württemberg have deepened capital deployment into servo-driven platforms seeking format flexibility. The EU Machinery Directive 2006/42/EC mandates CE conformity for automated packaging lines sold across member states. Stuttgart's machinery belt concentrates R&D intensity for thermoforming integration with ultrasound sealing.
Brazil
Food processing plants are expanding flow wrap adoption for shelf-stable snack lines across São Paulo and Minas Gerais states. ANVISA's pharmaceutical packaging regulations are elevating documentation burdens for equipment validation. Campinas' industrial corridor is consolidating purchasing decisions across regional contract manufacturing networks.
China
Labor cost pressures in Yangtze River Delta and Pearl River Delta manufacturing hubs are accelerating automatic flow wrap line adoption. SAMR's national standards for food machinery safety are tightening equipment certification requirements. Shenzhen's automation cluster is driving unmanned operation specifications for export-oriented contract manufacturers.
Mexico
Snack packaging demand in Nuevo León and Jalisco is driving equipment orders with modified atmosphere capability. The country's national food safety regulator enforces preventive control alignment with US FDA standards for cross-border supply chains. Monterrey's industrial corridor is centralizing procurement across multiple plant locations for multinational processors.
Flow Wrap Machines Market Vendor Landscape
German producers anchor one tier; Italian specialists hold positions in modular configurations for confectionery applications. The vendor base separates into consolidated multinational OEMs with captive film handling systems and mid-tier fabricators serving regional bakery networks. Two strategic archetypes dominate: backward-integrated packaging OEMs controlling upstream line integration performance, and servo-technology specialists decoupling mechanical complexity from control intelligence. Competitive moves center on M&A for film handling capabilities and geographic expansion into Southeast Asian contract manufacturing hubs.
Among Germany-based fabricators, Syntegon and Bosch Packaging Technology occupy positions at the scale-driven end of servo-driven horizontal platforms. Syntegon exemplifies R&D intensity concentration for bakery automation clusters, while Bosch Packaging Technology anchors manufacturing output volumes serving high-throughput frozen food facilities. ULMA Packaging represents backward integration into film handling systems, giving it upstream control over line integration performance. These three entities collectively illustrate how European OEMs are consolidating market preference through captive software ecosystems and format flexibility without mechanical rebuilds.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| Syntegon |
| ULMA Packaging |
| IMA Group |
| PFM Packaging |
| Coesia Group |
| MULTIVAC |
| FUJI Machinery |
| Cavanna Packaging |
| Others |
Supply Flow & Price Mechanics
Servo motor and precision bearing costs from Germany's industrial belt feed through three pricing tiers downstream, with Bavaria's automation clusters absorbing premium markups while Southeast Asian contract manufacturers negotiate standard-economy splits based on volume scale.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier horizontal platforms, compressing margins on mechanical cam-driven alternatives. Three-tier pricing structure across premium, standard, and economy levels separates servo-driven configurations with captive software ecosystems from basic pneumatic systems. Pricing pressure stems from REACH-driven reformulation costs passed through film handling subsystems. Food processors in Latin America show highest price sensitivity, while pharmaceutical packaging lines prioritize certification-grade premiums over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Campinas, and Shenzhen anchor hub-and-spoke patterns for spare parts and retrofit kits. Component manufacturing concentrates in Germany, Italy, and China, with servo drives and control systems drawing from Bavaria's machinery belt. Supply chain risk centers on single-source vulnerability for specialized rotary jaw assemblies. Distribution runs through OEM-direct channels for large frozen food facilities and regional fabricator networks for mid-tier bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Packaging and Packaging Waste Regulation tightening accelerates capital replacement cycles and service-contract bundling.
For Market Incumbents: Hedge against ultrasound sealing displacement by deepening backward integration into film handling systems. Prioritize captive software ecosystems that lock in format flexibility without mechanical rebuilds. Defend against emerging servo-technology specialists by accelerating R&D intensity in thermoforming integration.
For New Entrants and Emerging Players: Enter via pharmaceutical packaging white space where moisture-sensitive drug applications reward non-thermal sealing approaches. Target Southeast Asian contract manufacturing hubs where labor cost pressures accelerate automatic line adoption. Lead with modular servo configurations that decouple mechanical complexity from control intelligence.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators lack film handling capabilities and line integration performance validation. Five-to-ten year viability favors OEMs with captive upstream control and geographic presence in Brazil's regional networks. Watch EPR framework implementation velocity in North America as inflection indicator for service-contract revenue mix.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Handling | ULMA Packaging's upstream control over line integration performance validates this architecture's defensibility. |
| Servo-Driven Platform R&D Intensification | Syntegon's concentration in Bavaria automation clusters rewards format flexibility investments. |
| Pharmaceutical Ultrasound Sealing Partnership | Thermoforming paired with vibration sealing opens moisture-sensitive drug packaging white space. |
| Southeast Asian Hub Expansion | Shenzhen's automation cluster drives unmanned operation specifications for export-oriented contract manufacturers. |
| EPR-Aligned Service Contract Bundling | Extended producer responsibility frameworks in Europe reshape total cost of ownership calculations. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers grounded qualitative findings, cross-referenced with customs trade data, machinery belt production statistics, SEC equipment supplier filings, and ANVISA certification databases. Bottom-up and top-down triangulation validated segment-level assumptions across the analysis window.
Analytical lens combined unit shipment bottom-up builds with macroeconomic top-down constraints across the projection horizon. Segmentation dimensions modeled include machine configuration, end-use sector, sealing technology, and regional automation cluster adoption patterns. CAGRs derived from historical capital expenditure trajectories and replacement cycle compression, with inputs from servo motor cost curves and film substrate qualification timelines.
Inputs from FDA FSMA guidance documents and ECHA REACH restriction notices were available through the study window; gaps in real-time contract manufacturer procurement data introduce uncertainty bands around Latin American demand estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Food Packaging Machinery Market