
 Flow Wrapper Market | 2026-2036
Flow Wrapper Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Wrapper Market Analytics
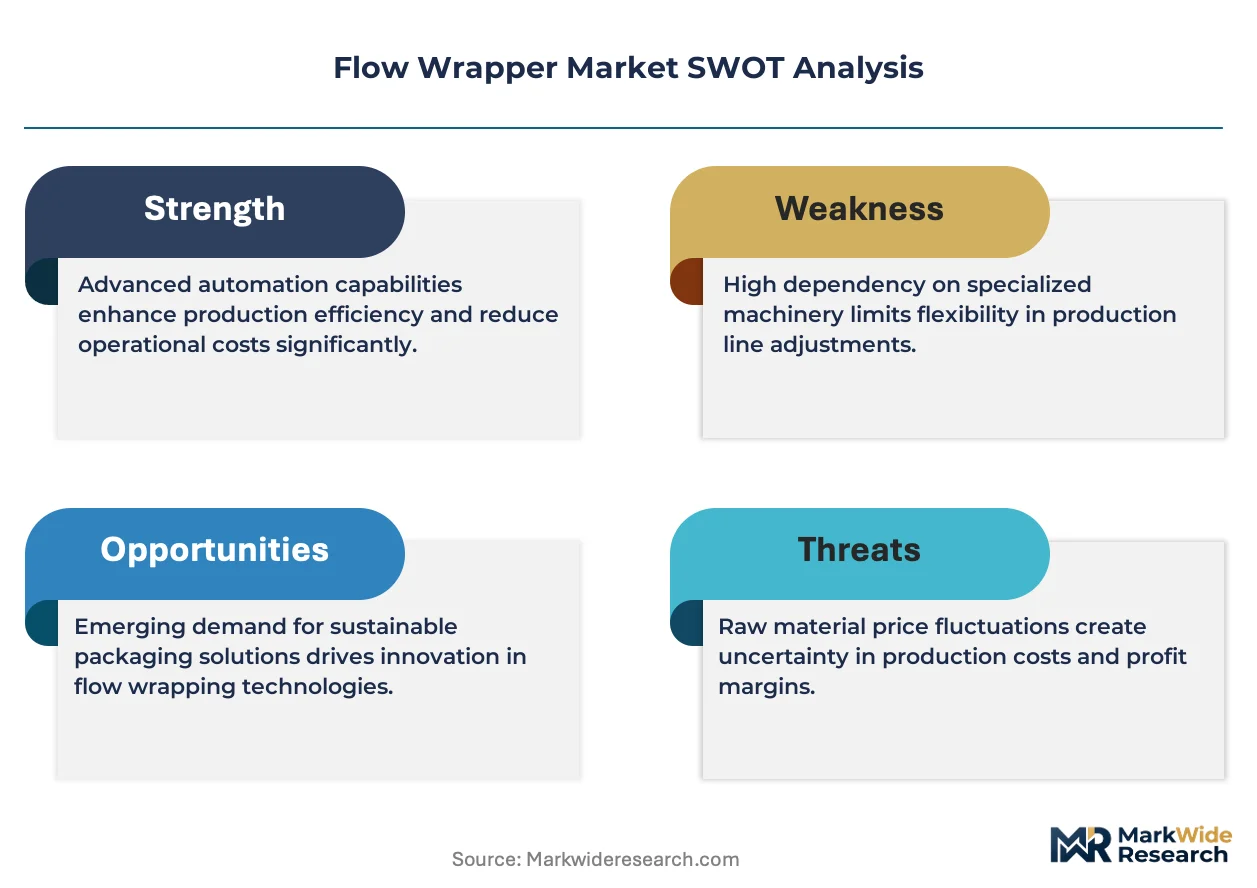
Equipment leasing and pay-per-output financing is rewriting competitive entry barriers for mid-sized food processors. Syntegon Technology leverages its global service network to sustain long-term contracts with multinational snack brands. Robert Bosch GmbH anchors premium positioning through precision servo-drive engineering and integrated quality inspection systems. ULMA Packaging competes aggressively on modular upgrade paths that let customers retrofit older horizontal flow wrapper frames with newer sealing technologies.
Flow wrappers are continuous-motion packaging machines that form, fill, and seal flexible film around individual or grouped products at speeds typically ranging from 50 to 1,200 packages per minute. These systems employ rotary or box-motion sealing jaws to create hermetic packages for perishable and non-perishable goods across food, pharmaceutical, and consumer goods sectors. Horizontal flow wrappers still command the largest installed base due to their versatility across bakery, confectionery, and frozen food applications, though vertical flow wrappers gain ground in single-serve and portion-controlled formats where gravity-fed product delivery improves line efficiency. Biodegradable materials represent the fastest-growing material segment as brand owners face retailer sustainability mandates, yet plastic films retain the deepest margin pools because of established supply chains and proven barrier performance.
FDA food contact material regulations and EU REACH chemical restrictions shape which film substrates and adhesive coatings gain market access in North America and Europe. BIS certification requirements in India and evolving GB standards in China add compliance layers for imported equipment and consumables alike. Stakeholders must monitor how fragmented national packaging waste laws converge or diverge, since this determines whether mono-material or compostable film investments pay off across their installed base.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is compressing converter timelines for mono-material film validation, forcing simultaneous retooling of sealing jaw geometries and heat-transfer algorithms across installed horizontal flow wrapper bases.
Growth Catalysts
- Quick-service restaurant chain expansion:Organized retail penetration in India sustains equipment orders for both domestic and imported flow wrapper systems serving frozen bakery and snack segments.
- FSSAI packaging safety mandates:India's food safety regulator tightens material traceability requirements, accelerating certified substrate adoption among processed food exporters.
- Servo-drive precision engineering:Advanced motion control systems enable hermetic sealing at higher line speeds without compromising package integrity for perishable goods.
Market Restraints
- Biodegradable film cost structure:Compostable substrate premiums remain elevated versus conventional plastic films due to limited resin supply scale and nascent extrusion infrastructure.
- Sealing technology supplier concentration:Critical rotary jaw and ultrasonic welding component sourcing clusters in Germany and Japan, exposing buyers to extended lead times during capacity constraints.
- REACH chemical restriction complexity:ECHA substance authorization processes delay adhesive coating approvals for multi-layer film constructions targeting European food contact applications.
Strategic Opportunities
- Modular retrofit pathways:ULMA Packaging's upgrade architecture allows processors to refresh sealing technologies on legacy horizontal frames without full line replacement.
- Equipment leasing proliferation:Pay-per-output financing models lower capital barriers for mid-sized food processors in Southeast Asia seeking automated wrapping capacity.
- Single-serve format pivot:Vertical flow wrapper configurations capture gravity-fed portion-control applications in confectionery and nutraceutical verticals where line efficiency gains justify format switching costs.
Industry Challenges
- Heat-seal technician scarcity:Specialized knowledge of jaw pressure calibration and temperature profiling for novel mono-material substrates outpaces vocational training program output.
- Legacy MES integration friction:New flow wrapper installations face protocol mismatches with existing manufacturing execution systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Wrapper Market |
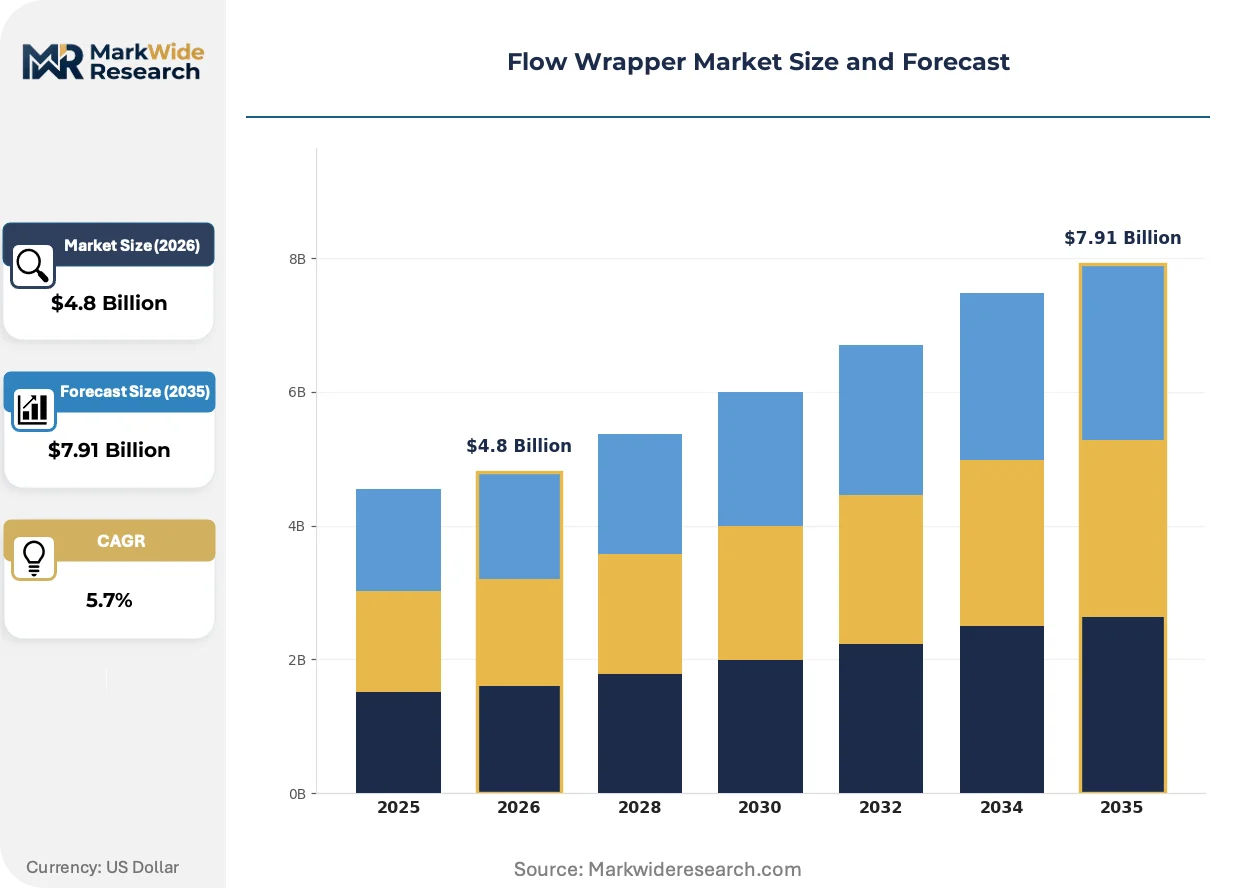
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Flow Wrappers, Automatic Flow Wrappers, Semi-Automatic Flow Wrappers, Vertical Flow Wrappers End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Material: Plastic Films, Paper, Aluminum Foil, Biodegradable Materials Application: Packaged Food, Snacks, Confectionery, Industrial Products |
| Companies Covered | Syntegon Technology, Robert Bosch GmbH, FUJI MACHINERY, IMA Group, Coesia Group, MULTIVAC Group, ULMA Packaging, PFM Packaging Machinery, Ilapak International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Wrapper Market Evolving Landscape
Active migration toward sustainable substrate portfolios is rewriting converter R&D priorities and equipment specification criteria simultaneously.
Mono-material polyolefin films are migrating from niche organic brand applications to mainstream private-label bakery and frozen food packaging. European retailers with Scope 3 emissions targets now mandate recyclable substrate compatibility in equipment tenders. This shift compresses the viable technology window for legacy multi-layer barrier constructions that cannot achieve mechanical recycling stream qualification.
EU Green Deal packaging waste reduction targets are accelerating EPR scheme harmonization across member states. Brand owners face consolidated reporting obligations for post-consumer collection and recycling rates. Food and beverage multinationals respond by centralizing film specification authority at corporate sustainability functions rather than delegating to regional procurement teams.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts. Snack and confectionery processors in North America now source spare parts through third-party distributors and deploy independent technicians for preventive maintenance. Equipment manufacturers counter by embedding predictive diagnostics and remote monitoring capabilities to retain recurring revenue attachment.
Flow Wrapper Market Segmentation
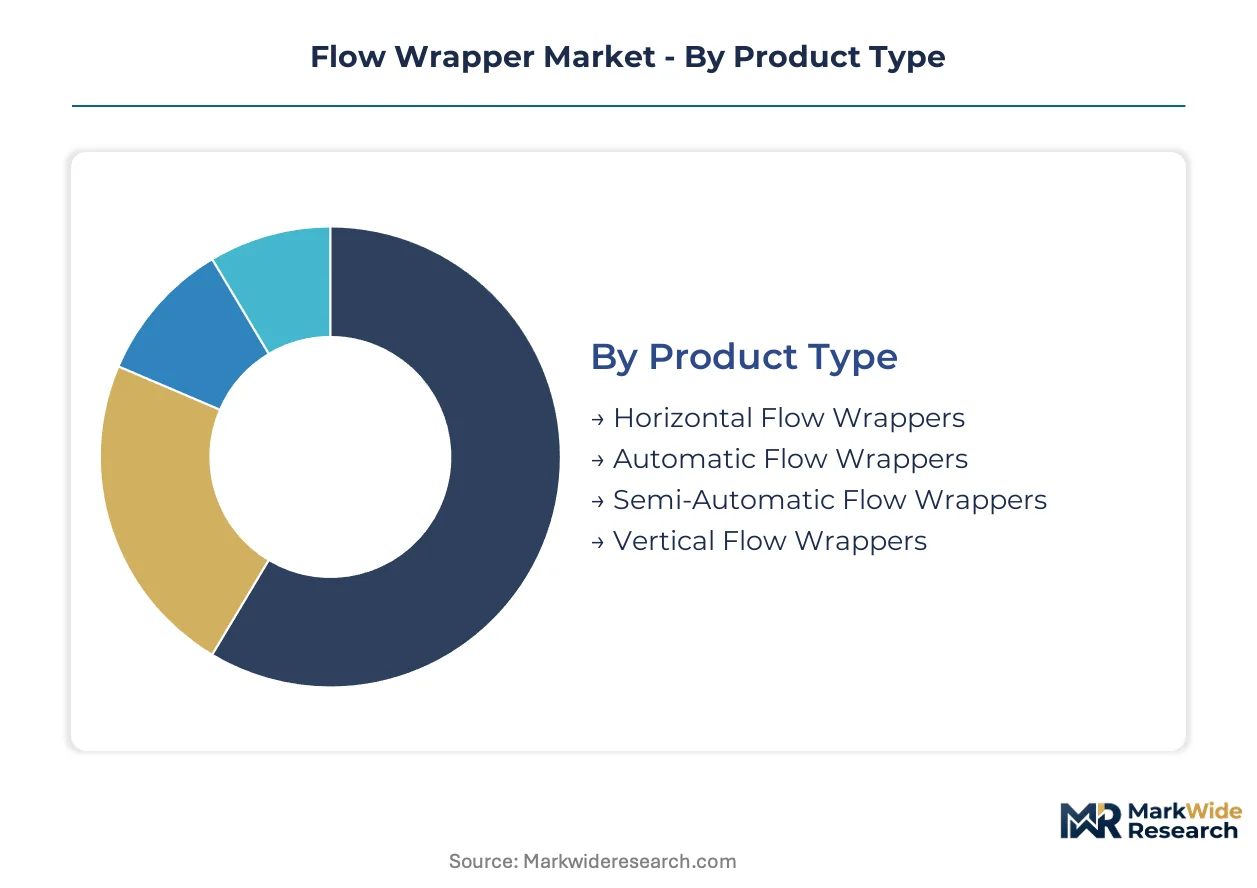
Flow wrapper procurement decisions hinge on line speed requirements, substrate compatibility, and regulatory compliance across divergent end-use environments. Equipment specification varies sharply between high-volume bakery operations and precision pharmaceutical packaging, driving distinct vendor specialization patterns.
Product Type:
Mature horizontal architectures dominate installed capacity while emerging vertical configurations capture gravity-fed format opportunities.
- Horizontal Flow Wrappers:Continuous-motion machines with rotary or box-motion sealing jaws achieve 50-1,200 packages per minute across bakery, confectionery, and frozen food applications. Demand concentrates in India where quick-service restaurant chain expansion sustains equipment orders for both domestic and imported systems.
- Automatic Flow Wrappers:Fully integrated servo-drive systems enable hermetic sealing at elevated speeds without compromising package integrity for perishable goods. European retailers with Scope 3 emissions targets now mandate recyclable substrate compatibility in equipment tenders for these lines.
- Semi-Automatic Flow Wrappers:Lower-capital units serve mid-sized processors in Southeast Asia seeking automated wrapping capacity through pay-per-output financing models.
- Vertical Flow Wrappers:Gravity-fed configurations gain traction in single-serve and portion-controlled formats where line efficiency improvements justify format switching costs in confectionery and nutraceutical verticals.
Horizontal Flow Wrappers retain volume leadership; Vertical Flow Wrappers hold the steepest expansion curve.
End User:
Application-driven margin structures separate commodity food packaging from regulated pharmaceutical environments.
- Food & Beverage:The largest demand concentration spans packaged food, snacks, and confectionery segments where FSSAI packaging safety mandates in India accelerate certified substrate adoption among processed food exporters. Mono-material polyolefin films are migrating from niche organic brands to mainstream private-label bakery and frozen food packaging in this vertical.
- Personal Care:Moderate-speed lines accommodate irregular product geometries and premium presentation requirements with modified atmosphere capabilities.
- Pharmaceuticals:FDA food contact material regulations and EU REACH chemical restrictions shape film substrate and adhesive coating selections for medical device and drug packaging applications requiring validated sealing processes.
- Electronics:Anti-static film specifications and precision length control distinguish this segment, though order volumes remain fragmented across contract manufacturers.
Food & Beverage commands absolute volume; Pharmaceuticals maintains the premium pricing tier.
Material:
Cost-performance tradeoffs and regulatory compliance layers determine substrate selection across geographic markets.
- Plastic Films:Deep margin pools persist due to established supply chains and proven barrier performance, though EU Packaging and Packaging Waste Regulation enforcement is compressing converter timelines for mono-material validation. Multi-layer barrier constructions face narrowing technology windows as mechanical recycling stream qualification becomes mandatory.
- Biodegradable Materials:Compostable substrate premiums remain elevated versus conventional plastics due to limited resin supply scale and nascent extrusion infrastructure. European retailers now mandate recyclable substrate compatibility, accelerating R&D priority shifts.
- Paper:Fiber-based substrates with barrier coatings serve organic and premium brand positioning where consumer perception favors non-plastic packaging.
- Aluminum Foil:High-barrier applications in pharmaceutical and specialty food segments sustain demand despite energy-intensive production profiles.
Plastic Films retain installed base dominance; Biodegradable Materials are climbing the fastest.
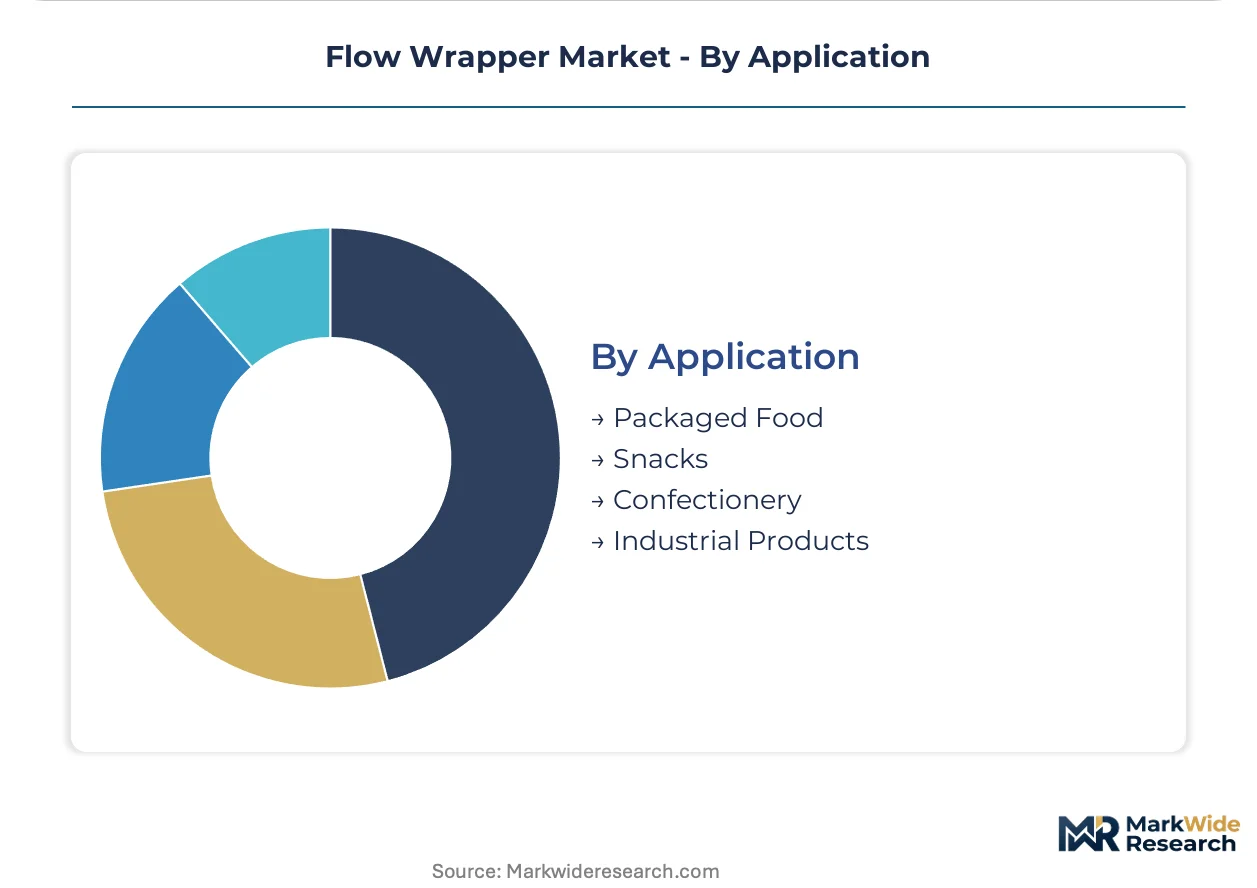
Application:
Packaging format requirements and shelf-stability demands create distinct equipment specification profiles.
- Packaged Food:Horizontal flow wrappers serve frozen bakery and ready-meal segments with extended shelf-life requirements through modified atmosphere packaging capabilities.
- Snacks:High-speed lines with ultrasonic welding and rotary jaw technologies address nitrogen-flush requirements for chip and extruded snack categories.
- Confectionery:Precision temperature profiling and jaw pressure calibration for heat-sensitive products concentrate demand in European and North American processing facilities.
- Industrial Products:Heavy-gauge film specifications and reinforced sealing patterns accommodate hardware and automotive component packaging with lower speed tolerances.
Packaged Food anchors equipment demand; Snacks demonstrates the most aggressive capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation enforcement is compressing converter timelines for mono-material film validation, forcing simultaneous retooling of sealing jaw geometries across installed horizontal flow wrapper bases in multiple jurisdictions.
United States
Quick-service restaurant chain expansion sustains equipment orders for frozen bakery and snack segments. FDA food contact material regulations shape film substrate selections for medical device and drug packaging applications. Chicago and Dallas processing clusters drive demand for high-speed horizontal wrapping lines serving national snack brands.
Germany
Precision servo-drive engineering from domestic equipment manufacturers anchors premium positioning in pharmaceutical and confectionery verticals. ECHA REACH chemical restrictions delay adhesive coating approvals for multi-layer film constructions. Stuttgart and Munich industrial corridors concentrate retrofit demand for legacy horizontal frames with newer sealing technologies.
India
Organized retail penetration and quick-service restaurant chain expansion create sustained equipment orders for both domestic and imported flow wrapper systems. FSSAI packaging safety mandates accelerate certified substrate adoption among processed food exporters. Maharashtra and Gujarat processing hubs dominate frozen bakery equipment procurement.
China
GB standards evolution adds compliance layers for imported equipment and consumables in food and beverage applications. Dual carbon goals push converters toward mono-material films and certified recyclable substrates. Yangtze River Delta manufacturing clusters drive domestic equipment fabrication for Southeast Asian export markets.
Japan
Rotary jaw and ultrasonic welding component sourcing concentrates capacity constraints for international buyers. METI industrial policy supports precision motion control system development for hermetic sealing applications. Nagoya and Osaka equipment fabricators supply high-speed lines for confectionery and nutraceutical portion-control formats.
Flow Wrapper Market Competitive Landscape
On the supply side, the industry is consolidating around precision engineering capabilities and global service network scale. Equipment manufacturers cluster into three strategic archetypes: full-line integrators with multinational service footprints, modular retrofit specialists, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include portfolio diversification into predictive diagnostics and geographic expansion through equipment leasing proliferation.
Among Germany-based precision engineering groups, Robert Bosch GmbH and Syntegon Technology exemplify the full-line integrator archetype through established multinational footprints. ULMA Packaging occupies a position within the modular retrofit specialist tier, serving processors seeking sealing technology refresh without full line replacement. Japanese fabricator FUJI MACHINERY anchors the high-speed precision segment alongside European competitors.
| Leading Market Players |
|---|
| Syntegon Technology |
| Robert Bosch GmbH |
| FUJI MACHINERY |
| IMA Group |
| Coesia Group |
| MULTIVAC Group |
| ULMA Packaging |
| PFM Packaging Machinery |
| Ilapak International |
| Others |
Value Network & Pricing Analysis
Stuttgart and Munich industrial corridors anchor European precision servo-drive component fabrication, where concentrated German engineering capacity translates into pricing power for horizontal flow wrapper systems serving pharmaceutical and confectionery verticals. Equipment manufacturers leverage this geographic concentration to maintain premium positioning through integrated quality inspection architectures, while buyers in Southeast Asia face extended procurement cycles when sourcing from these clusters.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium and economy-tier flow wrapper systems. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and predictive diagnostic capabilities as secondary differentiators. Cost compression in the standard tier intensifies because mid-sized food processors in India and Southeast Asia prioritize capital efficiency over precision specifications. Quick-service restaurant chain procurement teams demonstrate highest price sensitivity, while pharmaceutical packaging operations accept premium positioning for validated sealing process documentation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese rotary jaw component suppliers help multinational snack brands manage working capital through equipment commissioning periods. Critical sealing technology sourcing concentrates in Germany and Japan, with ultrasonic welding component fabrication drawing from precision motion control supply chains in Nagoya and Osaka. Single-source vulnerability around servo-drive engineering exposes buyers to capacity constraints during order surges. Distribution runs through OEM direct sales for premium pharmaceutical lines and third-party equipment distributors serving mid-cap food processors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flow wrapper market is reshaping around mono-material film compliance mandates, with EU Packaging and Packaging Waste Regulation enforcement compressing converter validation timelines and forcing simultaneous equipment retooling decisions.
For Market Incumbents: Insulate installed base relationships by embedding predictive diagnostics and remote monitoring capabilities that counter third-party aftermarket service fragmentation. Accelerate modular retrofit architecture deployment to capture legacy frame upgrade demand in European bakery and frozen food processing clusters. Vertical integration into certified recyclable substrate supply partnerships defends margin position against emerging leasing-model competitors. For New Entrants and Emerging Players: Maharashtra and Gujarat processing hubs present underpenetrated demand for pay-per-output financed semi-automatic systems serving domestic quick-service restaurant supply chains. Target certified substrate compatibility as the entry wedge, since FSSAI packaging safety mandates accelerate compliance investment among processed food exporters. Equipment-as-a-service bundling with preventive maintenance contracts lowers capital barriers for mid-sized processors seeking automated wrapping capacity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular retrofit specialists with established sealing technology upgrade architectures over full-line integrators facing aftermarket service unbundling pressure. Long-term viability hinges on corporate sustainability function centralization of film specification authority, creating consolidation rationale around substrate-equipment integration capabilities. Watch for EPR scheme harmonization across EU member states as the signal indicating accelerated mono-material investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Architecture Deployment | ULMA Packaging's upgrade paths capture legacy frame refresh demand without full line replacement capital burden. |
| Predictive Diagnostics Integration | Embedded remote monitoring capabilities retain recurring revenue attachment against third-party aftermarket fragmentation. |
| Certified Recyclable Substrate Partnership | Corporate sustainability function centralization creates substrate-equipment bundling opportunities for integrated suppliers. |
| Pay-per-Output Financing Proliferation | Equipment leasing models lower entry barriers for mid-sized Southeast Asian food processors seeking automation. |
| Vertical Flow Wrapper Format Expansion | Gravity-fed configurations capture single-serve confectionery and nutraceutical portion-control applications. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this flow wrapper market assessment. Primary field engagement with horizontal and vertical system operators across bakery, confectionery, and pharmaceutical packaging facilities combined with secondary validation through SEC equipment manufacturer filings, EU EPR scheme documentation, and FSSAI regulatory circulars. Bottom-up equipment shipment analysis and top-down end-use demand modeling provided triangulation across the projection horizon.
Scenario-bracketing around mono-material film adoption timelines and servo-drive component supply constraints shaped the analytical framework. Segmentation dimensions modeled include product architecture (horizontal versus vertical), automation level (automatic versus semi-automatic), end-use vertical (food and beverage, pharmaceuticals, personal care), material substrate type, and geographic regulatory cluster. CAGRs derived from equipment order backlogs, substrate conversion rates, and installed base refresh cycles across the analysis window. Industry-specific forecast inputs incorporated FSSAI packaging safety mandate enforcement schedules and EU Green Deal packaging waste reduction target trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular retrofit specialists or equipment-leasing platform entrants would shift outcomes beyond modeled parameters. Macroeconomic deviation in emerging market food processing investment, regulatory acceleration or delay in EPR harmonization, or breakthrough sealing technology for biodegradable substrates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Volumetric Boom Filling Machine Market