
 Global Filling Machines Market | 2026-2036
Global Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Filling Machines Market Foresight
Multi-source procurement for servo-driven filling systems is shifting toward consolidated vendor relationships among large beverage and pharmaceutical buyers. Krones AG leverages its integrated bottling-line architecture to anchor European demand for high-speed rotary fillers. GEA Group competes through hygienic design specialization in dairy and pharmaceutical applications. Tetra Pak sustains its aseptic carton-filling dominance via captive technology ecosystems and long-term customer financing structures.
A filling machine is an industrial packaging device that dispenses measured quantities of liquid, powder, paste, or granular product into containers, bottles, pouches, or cartons at speeds ranging from 20 to 1,200 units per minute depending on configuration and product viscosity. Its primary commercial purpose is to ensure dose accuracy, minimize product giveaway, and maintain sanitary conditions across food, pharmaceutical, and chemical processing environments. Volumetric technology occupies the largest installed base due to lower capital requirements and compatibility with thin liquids, while gravimetric systems command premium positioning where fill-precision tolerances below 0.5% are mandatory. Automatic and servo-driven automation levels represent the fastest-expanding configuration tier as labor-cost inflation and batch-traceability mandates push mid-sized processors toward programmable logic controller-based operations.
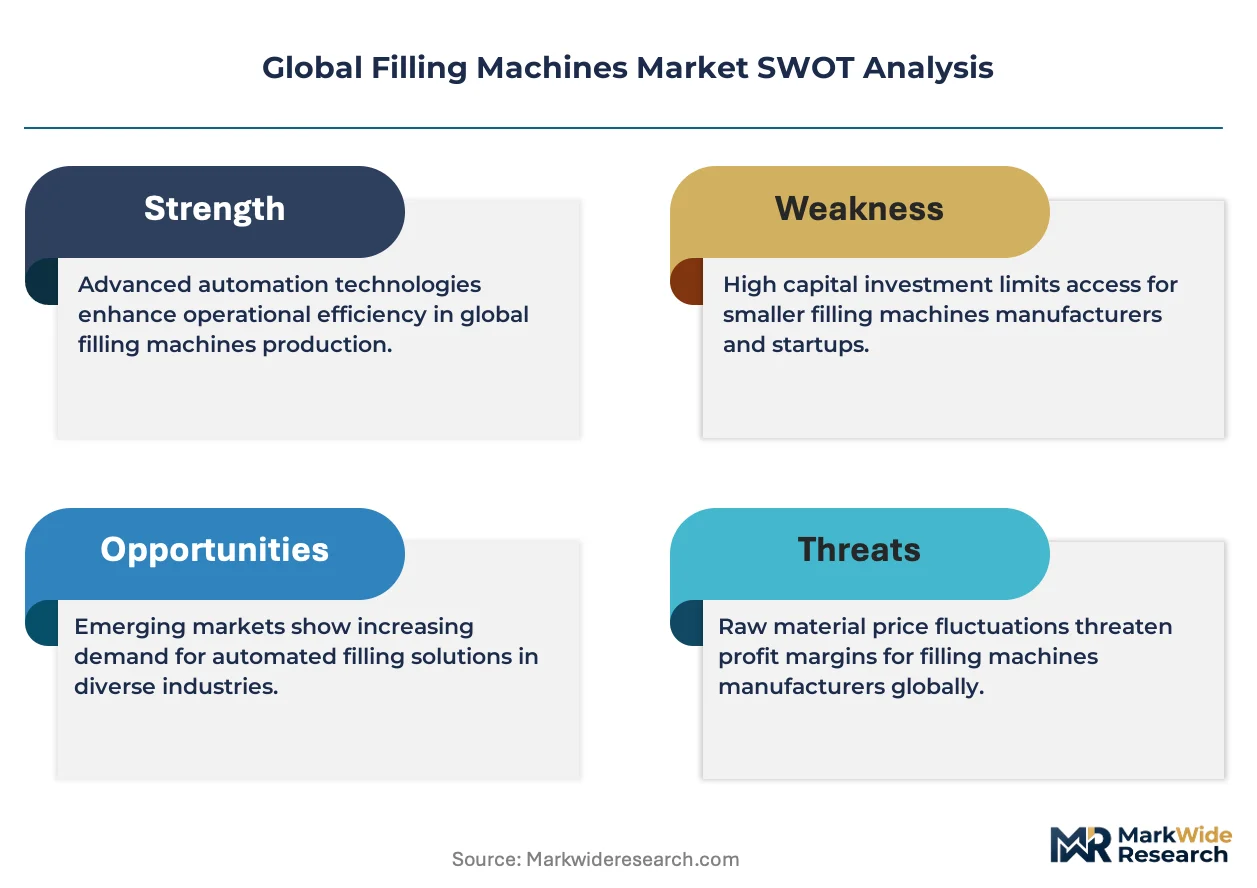
FDA cGMP guidelines and the EU's MDR framework impose validated clean-in-place protocols and material-contact surface standards that directly shape R&D priorities for pharmaceutical-facing equipment suppliers. EMA inspections and REACH substance restrictions further constrain seal-elastomer and lubricant selections, raising compliance costs for manufacturers serving dual food-pharma customer bases. Stakeholders must monitor evolving PFAS limitations under ECHA proposals and state-level chemical disclosure laws in the US, as these will redefine barrier-coating specifications for liquid-contact machine components within the next regulatory cycle.
Market Dynamics
Consolidated vendor relationships among large beverage and pharmaceutical buyers are compressing procurement cycles and reshaping competitive positioning across the filling machinery sector. This structural concentration favors integrated line suppliers over component specialists.
Growth Catalysts
- Aseptic filling technology:Beverage producers in Germany and Thailand are expanding adoption of aseptic filling lines to meet extended shelf-life requirements for ambient-distributed products. This technology eliminates preservatives while maintaining microbiological safety.
- EU F-Gas Regulation:The regulatory mandate is accelerating transitions to low-global-warming-potential refrigerant systems in cold-chain packaging equipment, forcing equipment upgrades across European dairy and pharmaceutical processing facilities.
- Servo-driven automation:Labor-cost inflation in Poland and Mexico is pushing mid-sized processors toward programmable logic controller-based operations with batch-traceability capabilities.
Market Restraints
- Stainless steel price volatility:Input cost fluctuations for 316L and 304 grades directly compress margins for hygienic equipment manufacturers serving dual food-pharma customer bases.
- German machinery cluster concentration:Supply risk concentrates around Stuttgart and Munich export hubs, creating vulnerability to regional logistics disruptions affecting Middle East and Southeast Asian delivery schedules.
- REACH substance restrictions:ECHA constraints on seal-elastomer and lubricant selections raise compliance costs and extend material qualification timelines for pharmaceutical-facing equipment.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO regulatory alignment with EU MDR standards is opening contract manufacturing opportunities for aseptic filling equipment in injectables and biologics production.
- Digital twin integration:Convergence of virtual commissioning tools with physical filling lines enables remote validation and reduces on-site installation time for rotary filler deployments.
- US state-level PFAS disclosure laws:Emerging barrier-coating mandates are creating replacement demand for liquid-contact machine components ahead of federal restrictions.
Industry Challenges
- Validated clean-in-place protocol engineering:FDA cGMP guidelines require specialized automation programming expertise that outstrips current talent pools in Midwest US manufacturing regions.
- EMA inspection preparation timelines:Pharmaceutical equipment suppliers face 18-24 month certification cycles that delay revenue recognition and strain working capital.
- Legacy gravimetric system integration:Retrofitting 0.1% precision fill-control modules into existing volumetric lines demands custom mechanical engineering that extends project delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Filling Machines Market |
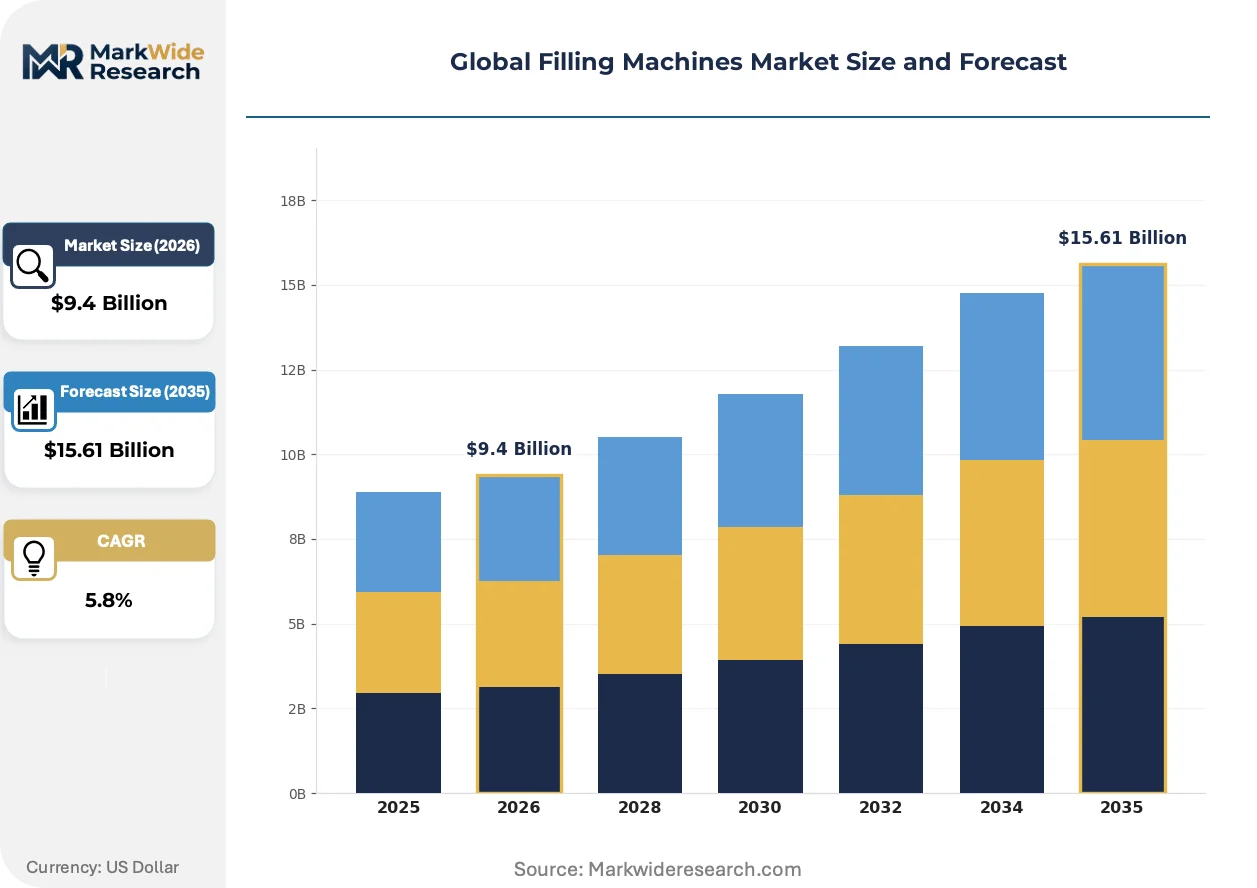
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filling Technology: Volumetric, Gravimetric, Piston, Auger, Vacuum, Overflow Product Type: Liquid, Powder, Granular, Paste, Aerosol, Tablets End User: Pharmaceutical Manufacturers, Beverage Producers, Personal Care Brands, Chemical Processors, Food & Confectionery Plants Automation Level: Manual, Semi-Automatic, Automatic, Fully Automated, Servo-Driven |
| Companies Covered | GEA Group, Coesia Group, Krones AG, ProMach, KHS Group, Tetra Pak, IMA Group, FULUKE, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Filling Machines Market Shifts & Advancements
Digitalization of filling line validation and remote service architectures is compressing commissioning timelines and redefing aftermarket revenue models. Equipment suppliers are embedding connectivity as a standard feature rather than premium option.
Magnetic flow meter technology is converging with servo-driven pump control to enable real-time fill-volume correction without mechanical recalibration. Pharmaceutical bottling operations in Switzerland and Singapore are adopting these systems for high-value liquid formulations. This convergence is displacing traditional piston-filler architectures in applications requiring frequent product changeovers.
Japan's PMDA has tightened data integrity requirements for computerized systems used in aseptic processing, mandating audit trails that capture every parameter adjustment. Equipment manufacturers must now embed tamper-evident logging capabilities into human-machine interfaces. Pharmaceutical exporters to Japan are retrofitting existing lines or specifying compliant architectures for greenfield investments.
Service contract unbundling is fragmenting traditional maintenance relationships as large beverage groups bring predictive analytics in-house. Third-party vibration monitoring and thermal imaging specialists are displacing OEM service teams for routine inspections. This pattern is most visible in Brazil and South Africa where multinational bottlers operate centralized engineering centers.
Global Filling Machines Market Segmentation
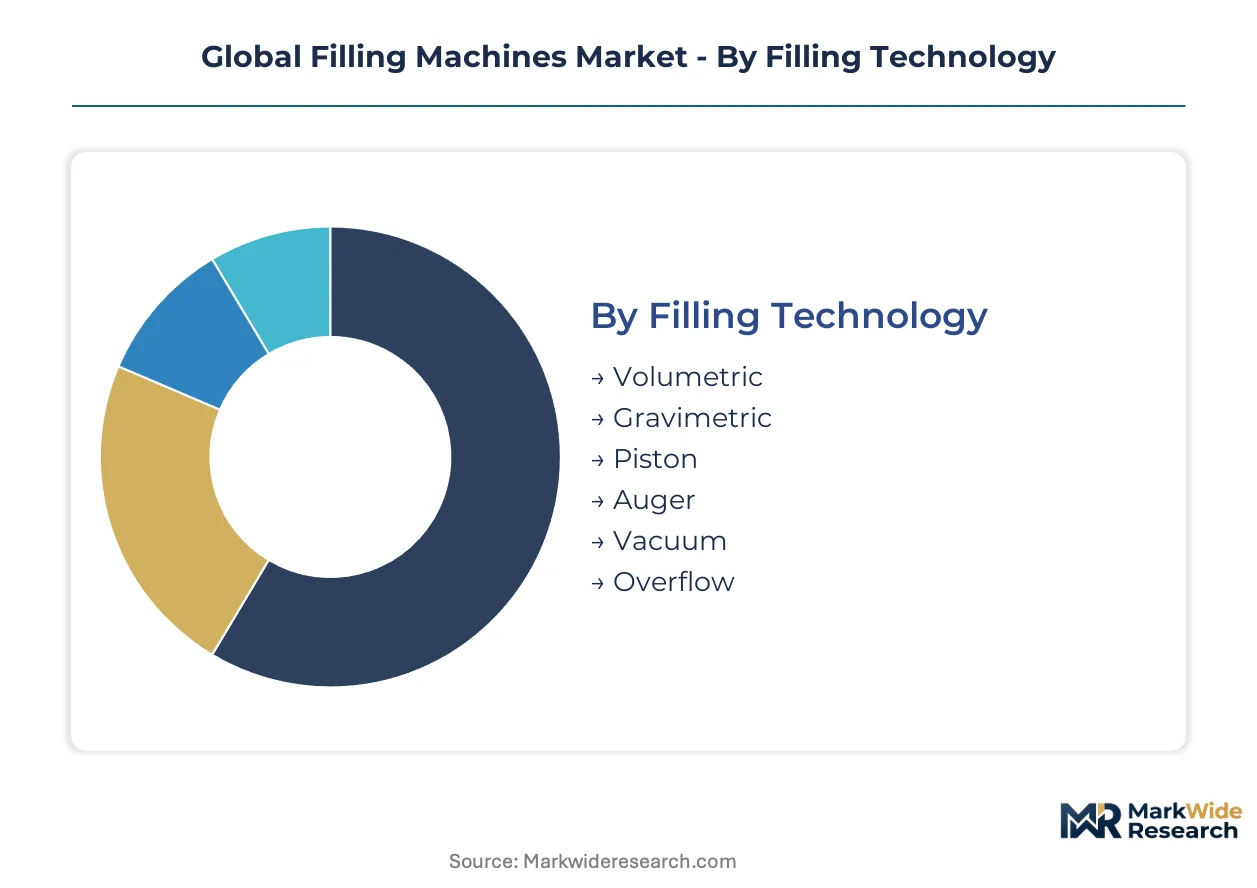
Filling machine procurement hinges on precise alignment between product rheology, regulatory environment, and throughput requirements. Segment selection determines capital allocation, compliance burden, and operational flexibility across processing environments.
Filling Technology:
Precision tolerance and product viscosity dictate technology selection, with capital intensity separating commodity from premium tiers.
- Volumetric:Displacement-based measurement using fixed-cavity pumps or flow meters suits thin liquids with moderate accuracy requirements. Beverage bottlers in Thailand deploy these systems for high-speed water and juice filling where ±1% tolerance satisfies commercial standards.
- Gravimetric:Load-cell-based weighing achieves ±0.1% fill precision for high-value pharmaceutical and chemical formulations. Swiss injectables manufacturers specify these systems where product cost exceeds equipment capital by orders of magnitude.
- Piston:Positive-displacement cylinders handle viscous creams and sauces with minimal shear.
- Auger:Screw-feed mechanisms meter free-flowing powders and granules into rigid containers.
- Vacuum:Negative-pressure filling prevents foam generation in carbonated and volatile liquids.
- Overflow:Level-sensing nozzles ensure cosmetic bottle consistency regardless of container volume variation.
Volume sits with Volumetric; growth tilts toward Gravimetric as pharmaceutical precision mandates tighten.
Product Type:
Physical state determines sealing technology, contact materials, and cleanability protocols.
- Liquid:Thin to viscous fluids ranging from water to syrups constitute the largest installed base across beverage and pharmaceutical sectors. Aseptic processing requirements in Germany are accelerating stainless-steel upgrade cycles for dairy and functional drink lines.
- Powder:Free-flowing to cohesive particulates demand dust-containment and explosion-protection engineering. Indian pharmaceutical contract manufacturers are expanding capacity for generic active pharmaceutical ingredient packaging under CDSCO oversight.
- Granular:Discrete solid particles require vibratory feed systems and check-weigh integration.
- Paste:Non-Newtonian fluids need heated hoppers and positive-displacement pumping.
- Aerosol:Pressurized propellant systems mandate specialized valve crimping and pressure testing.
- Tablets:Solid-dose counting and bottle filling serve pharmaceutical dispensing operations.
Liquid dominates installed value; paste and aerosol applications are climbing fastest on personal care demand.
End User:
Regulatory stringency and batch-traceability requirements create distinct procurement profiles.
- Pharmaceutical Manufacturers:FDA cGMP and EMA validation protocols mandate documented clean-in-place cycles and material certificates. German injectables specialists near Frankfurt specify fully isolator-integrated lines for cytotoxic drug filling.
- Beverage Producers:Shelf-life extension drives aseptic investment without preservatives. Thai and Indonesian bottlers are adopting hydrogen peroxide vapor sterilization for ambient-distributed coconut water and ready-to-drink tea.
- Personal Care Brands:Viscous emulsions and fragrances require gentle handling and aromatic containment.
- Chemical Processors:Corrosive and flammable formulations dictate specialized metallurgy and explosion-proofing.
- Food & Confectionery Plants:Hygienic design balances washdown accessibility with production speed.
Pharmaceutical buyers concentrate premium spending; beverage producers are expanding fastest on emerging market capacity.
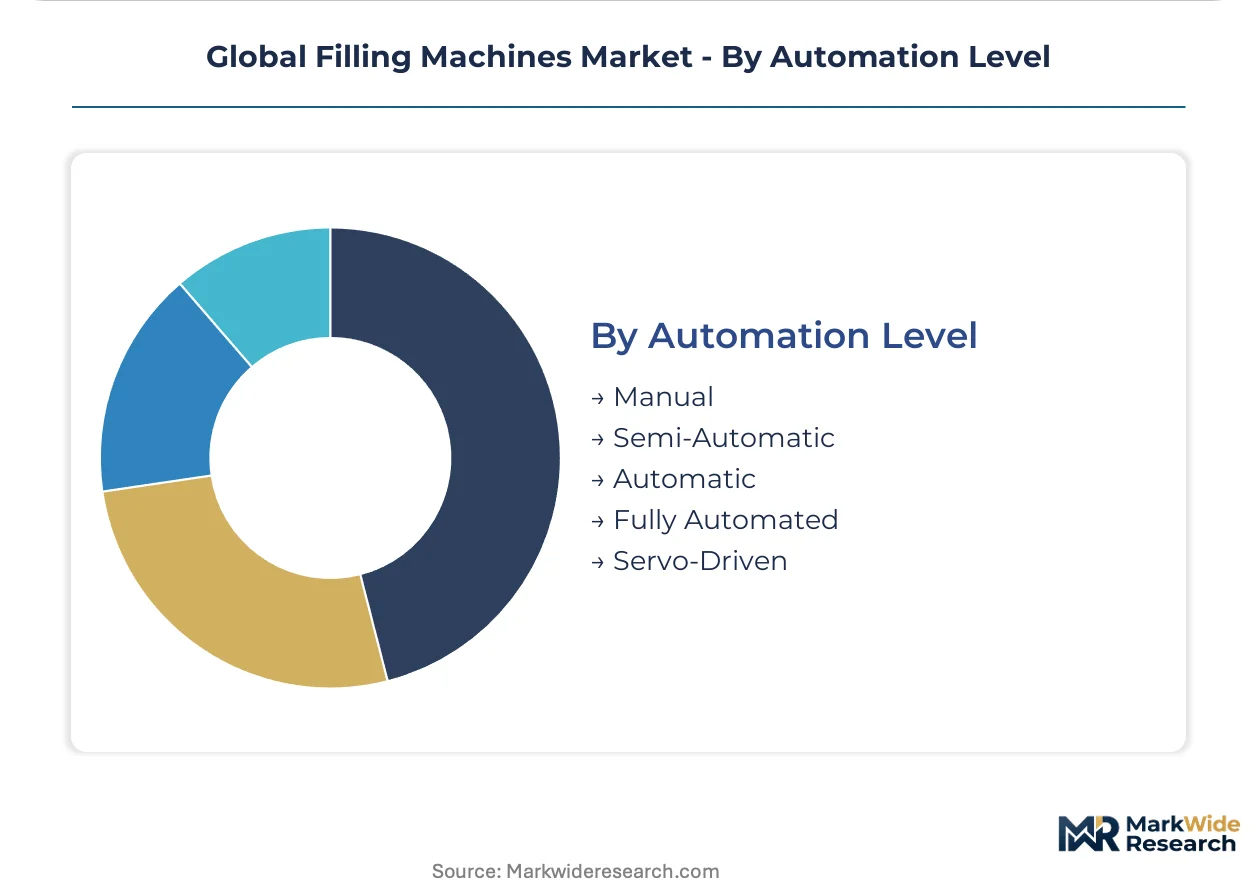
Automation Level:
Labor economics and batch complexity determine the human-machine boundary.
- Servo-Driven:Individual motor control on each filling station enables recipe-driven changeovers without mechanical adjustment. Mexican food processors are adopting these architectures to offset wage inflation while maintaining SKU flexibility.
- Automatic:Programmable logic controller-coordinated operations with integrated feeding and capping dominate mid-scale installations.
- Fully Automated:Robotic loading, inspection, and palletizing complete unmanned lines for high-volume single-SKU production.
- Semi-Automatic:Operator-assisted loading with machine-controlled filling suits pilot-scale and seasonal operations.
- Manual:Hand-operated systems serve artisanal producers and regulatory-exempt niches.
Automatic systems anchor current volume; servo-driven configurations are gaining share fastest on flexibility premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for filling machinery concentrates in Germany, the United States, and China, with machinery clusters in each country anchoring export supply to Southeast Asia, Latin America, and the Middle East.
Germany
Aseptic dairy and pharmaceutical filling lines drive capital expenditure near Stuttgart and Munich. The EU's F-Gas Regulation accelerates refrigerant system upgrades across cold-chain packaging equipment. Machinery manufacturers in Baden-Württemberg export rotary fillers to Thai and Indonesian beverage bottlers expanding ambient-distributed product portfolios.
United States
Pharmaceutical contract manufacturers in New Jersey and North Carolina invest in isolator-integrated filling lines for cytotoxic drug production. FDA cGMP guidelines mandate validated clean-in-place protocols that extend equipment qualification timelines. Midwest dairy processors in Wisconsin specify servo-driven systems to offset labor-cost inflation while maintaining SKU flexibility.
China
Domestic beverage brands in Guangdong and Zhejiang provinces scale aseptic carton capacity for shelf-stable juices and plant-based drinks. NMPA alignment with international pharmaceutical standards opens import substitution opportunities for local filling equipment suppliers. Yangtze River Delta machinery fabricators compete on cost for volumetric systems serving Southeast Asian contract manufacturers.
India
CDSCO regulatory harmonization with EU MDR standards enables contract manufacturing growth in injectables and biologics. Pharmaceutical clusters in Maharashtra and Gujarat import gravimetric filling systems for high-value API packaging. Domestic equipment makers in Ahmedabad and Pune target mid-tier pharmaceutical and food processors with automatic PLC-based configurations.
Japan
PMDA data integrity requirements for computerized aseptic processing systems mandate tamper-evident audit trails in human-machine interfaces. Pharmaceutical exporters in Osaka and Tokyo retrofit existing lines or specify compliant architectures for greenfield investments. Precision equipment specialists in Nagoya supply magnetic flow meter integration for real-time fill-volume correction in high-value liquid formulations.
Global Filling Machines Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated line suppliers extend fabrication footprints to reduce delivery lead times. The vendor base organizes around three tiers: multinational turnkey system providers, regional hygienic design specialists, and component-focused automation houses. Consolidation pressure favors suppliers offering bundled line architecture over standalone filling module vendors. Geographic expansion and technology licensing represent the primary competitive moves, with European fabricators establishing service hubs in Southeast Asia and Mexican food processing corridors.
Among Germany-based industrial groups, Krones AG and GEA Group exemplify the integrated-system archetype, anchoring premium-tier positioning through captive technology ecosystems and long-term customer financing structures. Tetra Pak occupies a distinct position within aseptic carton-filling, sustaining dominance via specialized barrier-coating expertise and beverage industry partnerships. These three entities represent the consolidation trajectory reshaping procurement patterns among large-scale beverage and pharmaceutical buyers.
| Leading Market Players |
|---|
| GEA Group |
| Coesia Group |
| Krones AG |
| ProMach |
| KHS Group |
| Tetra Pak |
| IMA Group |
| FULUKE |
| Syntegon Technology |
| Others |
Supply & Pricing Matrix
Large beverage and pharmaceutical buyers with consolidated procurement functions command project-based pricing with extended warranty bundling, while mid-tier processors face transactional per-unit structures without service integration. This buyer-tier bifurcation concentrates pricing power among integrated line suppliers who anchor long-term financing relationships.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from component specialists, with Krones AG and GEA Group embedding multi-year maintenance contracts into rotary filler sales while regional fabricators unbundle these elements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and automation complexity, with FDA-validated pharmaceutical systems commanding substantial premiums over beverage-grade volumetric units. Pricing pressure stems from stainless steel input volatility compressing margins on hygienic equipment. Beverage producers in Southeast Asia exhibit highest price sensitivity, while German pharmaceutical contract manufacturers prioritize precision specifications over capital outlay.
Supply Chain Analysis
Refurbishment flows for servo motors and PLC modules concentrate in Germany and Japan, with Nagoya and Stuttgart facilities remanufacturing control systems for redeployment across Southeast Asian bottling operations. Production gravity centers on Germany, China, and Italy, with Baden-Württemberg and Yangtze River Delta fabricators drawing from 316L stainless steel suppliers in Sweden and Japan. Single-source vulnerability concentrates in precision load-cell manufacturing anchored in Swiss and German component houses. Distribution runs through machinery export hubs in Hamburg and Shanghai serving Middle Eastern dairy processors and Latin American beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with equipment suppliers pursuing captive control over servo-drive manufacturing to secure margin position against automation component vendors.
For Market Incumbents: Lock in long-term stainless steel supply agreements with Swedish and Japanese metallurgical suppliers before REACH substance restrictions tighten further. Consolidate service contract portfolios through predictive analytics platforms to counter in-house engineering centers at multinational beverage groups. The threat of third-party vibration monitoring specialists displacing OEM service teams demands channel control investment. For New Entrants and Emerging Players: Magnetic flow meter integration with real-time fill correction offers technology-first wedge into Swiss and Singapore pharmaceutical bottling operations where precision mandates outstrip incumbent refresh cycles. Target Indian pharmaceutical contract manufacturers under CDSCO regulatory alignment as the most penetrable geography. Pursue digital twin commissioning tools as go-to-market differentiator against legacy rotary filler architectures. For Investors and Strategic Acquirers: The window for entry favors mid-cap hygienic design specialists with isolator-integrated line capabilities serving cytotoxic drug manufacturing. Long-term viability hinges on regulatory certification depth rather than volume scale. Watch ECHA PFAS limitation timelines as inflection indicator for barrier-coating replacement demand across liquid-contact components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Drive Manufacturing | Captive motor production insulates margin from automation vendor pricing power in German machinery clusters. |
| Digital Twin Platform Development | Virtual commissioning tools compress installation timelines for rotary filler deployments in Thai beverage plants. |
| Southeast Asian Service Hub Establishment | Regional maintenance presence counters logistics vulnerability from Stuttgart and Munich export concentration. |
| Isolator-Integrated Line Certification | EMA-compliant architectures access German injectables manufacturers near Frankfurt expanding cytotoxic capacity. |
| PFAS-Free Barrier Coating R&D | Anticipatory material qualification positions suppliers ahead of ECHA restrictions on liquid-contact components. |
Research Methodology
Independent corroboration across plant engineers at beverage bottlers, procurement leads at pharmaceutical contract manufacturers, and aftermarket service heads at OEMs underwrites the qualitative findings. Primary interviews with maintenance directors and OEM procurement teams combined with secondary validation from SEC filings, customs trade data, and EMA inspection databases. Bottom-up triangulation across filling technology configurations and top-down reconciliation against regional machinery production statistics anchored volume estimates.
Comparable-period anchoring to historical installation data across the projection horizon enabled CAGR derivation through segmented growth rate blending. The analytical framework modeled filling technology, product type, end-user regulatory cluster, and automation level as core dimensions. Industry-specific inputs incorporated EU F-Gas Regulation compliance timelines and CDSCO harmonization progress for Indian pharmaceutical equipment demand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden stainless steel price spikes or accelerated PFAS restriction implementation. Practitioners should monitor ECHA regulatory proposals and German machinery cluster logistics disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Induction Sealing Machine Market