
 Automatic Paper Cutter Market | 2026-2036
Automatic Paper Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Paper Cutter Market Outlook
Carbon steel blade substrates are pivoting toward tungsten carbide and ceramic composites in high-volume cutter lines, extending service intervals and reducing downtime costs. Polar Mohr leverages in-house grinding technology to anchor premium positioning in European commercial printing. Baumann Maschinenbau Solms specializes in modular feed systems that integrate with existing bindery workflows. Challenge Machinery dominates the North American educational and institutional channel through distributor relationships.
An automatic paper cutter is a motorized shearing machine that employs a hardened blade driven through a paper stack by hydraulic, electric, or mechanical power, typically achieving cutting tolerances within ±0.1 millimetre and cycle speeds exceeding forty cuts per minute; its primary purpose is to convert large parent sheets or rolls into precise finished formats for downstream binding, printing, or packaging operations. Programmable cutters command the strongest margin pools because software-controlled backgauge positioning and automated jogger systems eliminate manual setup labour. Digital control technology is displacing manual feed configurations in mid-market printing houses where operator availability constrains throughput. Laser cutting remains confined to specialty crafting and prototyping applications where heat-sealed edges prevent fibre fraying in synthetic stocks.
The EU Machinery Directive and CE marking framework mandate two-hand operation, light curtain guarding, and emergency stop redundancy on all cutters sold in member states, elevating engineering costs for non-compliant imports. The US OSHA lockout/tagout standards and NHTSA-influenced workplace safety audits drive replacement demand in aging American binderies. China's GB standards and SAMR certification requirements create separate compliance pathways for equipment entering Asian manufacturing zones. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape energy efficiency benchmarks for motorized cutter platforms.
Market Dynamics
Programmable backgauge systems and automated jogger mechanisms are compressing setup labor to near-zero, forcing mid-market binderies to replace manual feed configurations or exit commercial printing entirely.
Growth Catalysts
- EU Machinery Directive safety mandates:Two-hand operation and light curtain guarding requirements accelerate replacement cycles in German and French commercial printing houses.
- Tungsten carbide blade substrates:Extended service intervals reduce downtime costs in high-volume lines, pulling demand from carbon steel legacy systems.
- Educational institutional procurement:North American school districts and university print shops standardize on automated cutters to offset operator availability constraints.
Market Restraints
- CE marking engineering costs:Non-compliant imports face elevated redesign expenses to satisfy emergency stop redundancy and guarding specifications.
- Hydraulic system maintenance:Fluid replacement and seal degradation create recurring operational burdens absent in fully electric alternatives.
- Laser cutting substitution ceiling:Heat-sealed edge technology remains confined to synthetic stock prototyping, limiting addressable market expansion.
Strategic Opportunities
- Modular retrofit kits:Binderies in aging industrial zones upgrade existing cutter frames with programmable controllers rather than full replacement.
- Digital control platform convergence:Integration of safety interlocks with production workflow software opens premium positioning for systems architects.
- China GB standards pathway:SAMR certification requirements create separate compliance tracks for equipment targeting Asian manufacturing zones.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and PLC troubleshooting skills lag deployment of digital control platforms in regional print markets.
- Legacy mechanical integration:Pneumatic jogger systems from 1990s cutter lines resist interface with modern backgauge positioning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Paper Cutter Market |
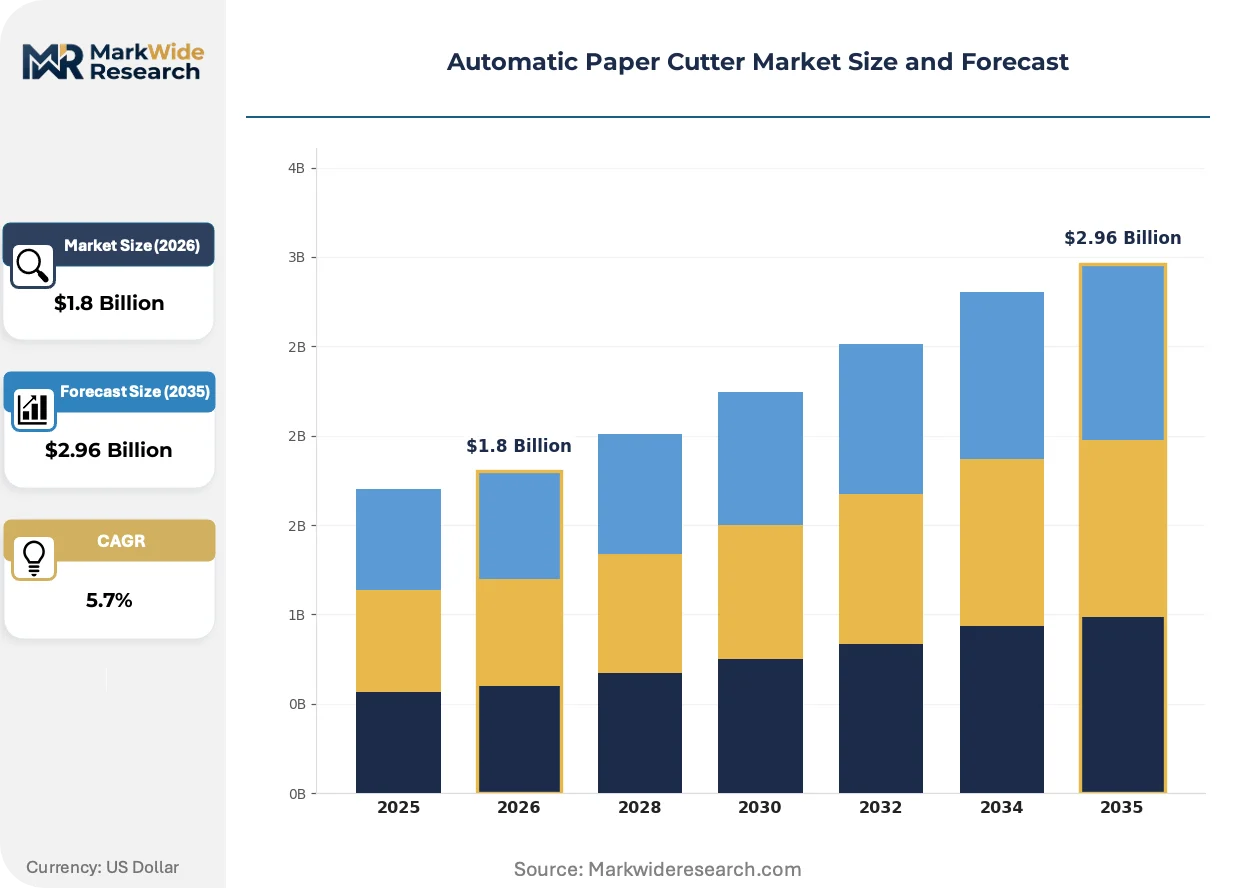
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Cutters, Rotary Cutters, Guillotine Cutters, Programmable Cutters End User: Printing Houses, Educational Institutions, Office Supplies, Craft Shops Technology: Manual Feed, Automatic Feed, Digital Control, Laser Cutting Application: Commercial Printing, Crafting, Packaging, Office Use |
| Companies Covered | Perfecta Cutting Systems, Standard Horizon, Polar Mohr, Colter & Peterson, MBM Corporation, Challenge Machinery, Ideal Krug & Priester, Baumann Maschinenbau Solms, Duplo International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Paper Cutter Market Strategic Shifts
Software-defined cutting workflows are absorbing functions previously executed by skilled operators, compressing the boundary between prepress automation and finishing equipment.
Ceramic composite blade substrates are absorbing abrasive wear from coated and recycled stocks that degrade conventional steel edges. Commercial printers in high-volume book manufacturing are adopting these materials to extend grind intervals from weekly to monthly cycles. This absorption of wear-related downtime is compressing total cost of ownership calculations and reshaping maintenance contract structures.
REACH substance restrictions and RoHS substance limitations are forcing reformulation of hydraulic fluids and electrical insulation in cutter platforms sold into EU member states. Manufacturers must certify alternative chemistries through ECHA notification pathways before placing equipment on the market. German precision engineering clusters around Solms and Ludwigsburg are responding fastest, leveraging in-house testing capacity to maintain shipment velocity.
Service unbundling is fragmenting traditional cutter procurement into capital purchase, software subscription, and per-cut maintenance tiers. Educational and institutional buyers increasingly separate equipment acquisition from training and spare parts provisioning. This pattern is most pronounced in North American distributor channels, where Challenge Machinery's network structure accommodates modular contracting.
Automatic Paper Cutter Market Segmentation
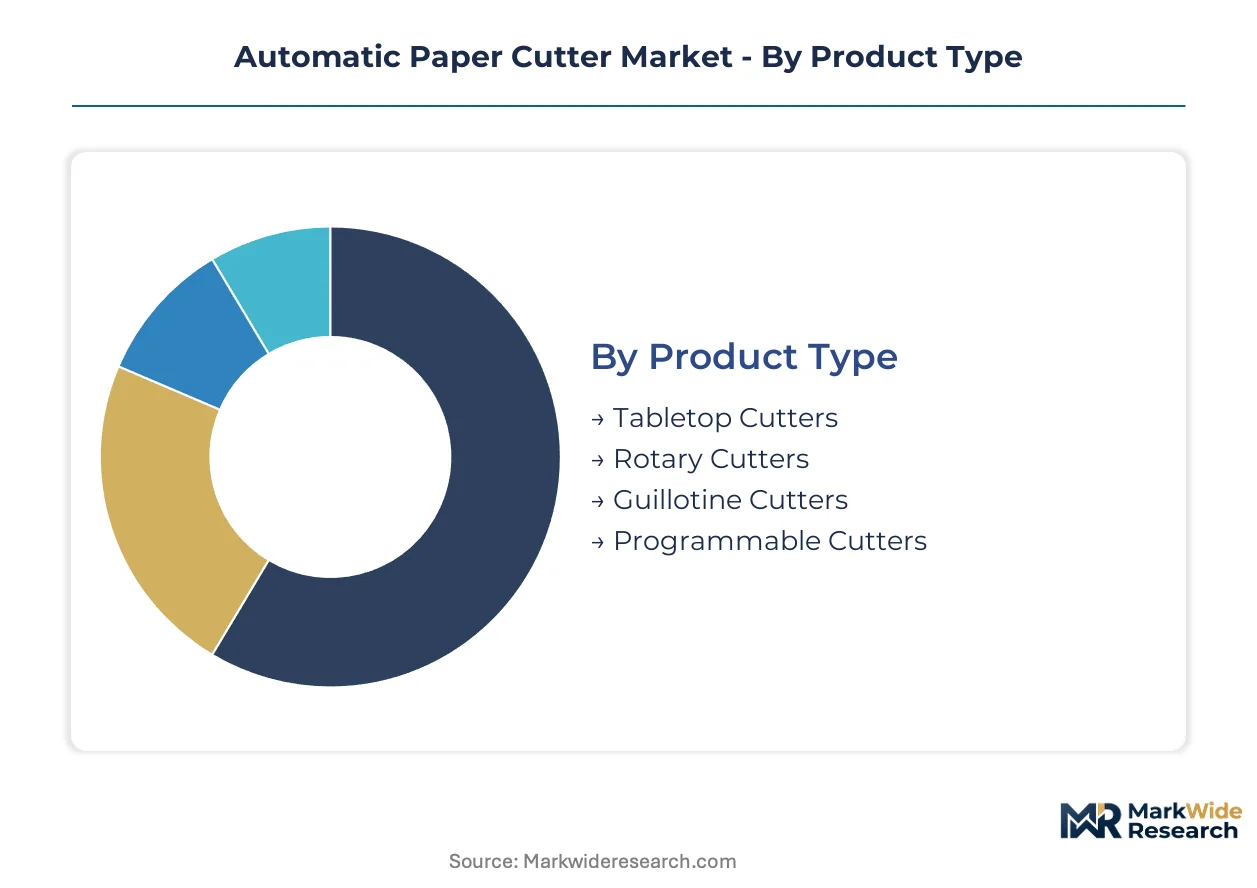
Segmentation in the automatic paper cutter market reveals how buyer priorities diverge across precision requirements, throughput demands, and compliance burdens. Equipment specifications cluster around blade substrate durability, control system sophistication, and integration depth with upstream prepress workflows.
Product Type:
Capital deployment scale and cutting tolerance requirements drive product selection across commercial binderies and institutional buyers.
- Programmable Cutters:These systems employ servo-driven backgauge positioning and automated jogger mechanisms to achieve ±0.1 millimetre tolerances at cycle speeds exceeding forty cuts per minute. German commercial printing houses around Solms and Ludwigsburg anchor demand, pulled by EU Machinery Directive safety mandates that accelerate replacement of manual configurations. Margin pools concentrate here due to software-controlled setup elimination.
- Guillotine Cutters:Hydraulic or electric power drives hardened blades through paper stacks in high-volume shearing operations. North American educational procurement channels standardize on these units to offset operator availability constraints in school district print shops. Extended service intervals from tungsten carbide blade substrates are compressing total cost of ownership calculations.
- Tabletop Cutters:Compact motorized units serve low-volume office environments and small craft operations with limited floor space.
- Rotary Cutters:Continuous-feed drum mechanisms process roll stock into sheet formats for packaging and label manufacturing workflows.
Programmable cutters lead on scale; guillotine cutters lead on momentum across institutional replacement cycles.
End User:
Operational sophistication and maintenance capability determine equipment tier selection across buyer categories.
- Printing Houses:High-volume commercial binderies demand programmable cutting systems with integrated safety interlocks and digital control platforms. These buyers prioritize tungsten carbide and ceramic composite blade substrates that extend grind intervals from weekly to monthly cycles. REACH substance restrictions and RoHS limitations force hydraulic fluid reformulation compliance through ECHA notification pathways.
- Educational Institutions:North American school districts and university print shops drive standardized procurement through distributor relationships. Modular retrofit kits allow aging cutter frame upgrades rather than full replacement, accommodating constrained capital budgets.
- Office Supplies:Corporate mailroom and administrative operations select tabletop and entry-level automatic feed configurations for intermittent use patterns.
- Craft Shops:Specialty retailers and hobbyist channels concentrate demand for laser cutting systems where heat-sealed edges prevent synthetic stock fibre fraying.
Printing houses dominate absolute unit volume; educational institutions are expanding most quickly through distributor channel penetration.
Technology:
Control system architecture separates legacy mechanical platforms from software-defined cutting workflows.
- Digital Control:PLC-based platforms with integrated safety interlocks and production workflow software are displacing manual feed configurations in mid-market binderies. EU Machinery Directive two-hand operation and light curtain guarding requirements elevate engineering costs for non-compliant imports. German precision engineering clusters leverage in-house testing capacity to maintain shipment velocity under CE marking frameworks.
- Automatic Feed:Motorized jogger and backgauge systems eliminate manual stack positioning labor in high-throughput environments.
- Manual Feed:Operator-dependent configurations persist in aging industrial zones where mechatronics technician scarcity constrains digital platform deployment.
- Laser Cutting:Heat-based edge sealing technology remains confined to specialty crafting and prototyping applications with limited addressable market expansion.
Digital control commands premium positioning; automatic feed configurations gain share fastest as mid-market buyers upgrade legacy mechanical systems.
Application:
Downstream process integration requirements shape blade specification and control system selection.
- Commercial Printing:Book manufacturing and general commercial binderies demand ceramic composite blade substrates to absorb abrasive wear from coated and recycled stocks. Service unbundling fragments procurement into capital purchase, software subscription, and per-cut maintenance tiers.
- Packaging:Corrugated and label production lines require continuous-feed rotary mechanisms with hardened blade edges for synthetic substrate processing.
- Crafting:Prototyping and specialty material work concentrates laser cutting demand where edge quality specifications exceed mechanical shear capabilities.
- Office Use:Intermittent cutting of standard paper stocks drives tabletop and light-duty automatic feed selection with minimal setup complexity.
Commercial printing anchors revenue concentration; packaging applications show steepest expansion trajectory as e-commerce fulfillment demands precision cutting integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solms and Ludwigsburg precision engineering clusters anchor European supply chain development for programmable cutting systems, while regulatory divergence across major economies fragments compliance pathways and shapes procurement decisions.
Germany
Commercial printing houses in Hesse and Baden-Württemberg drive replacement demand for servo-driven backgauge systems. EU Machinery Directive two-hand operation and light curtain guarding requirements accelerate upgrade cycles. Solms precision engineering cluster specializes in modular feed systems that integrate with existing bindery workflows.
United States
Educational institutional procurement channels standardize on automated cutters to offset operator availability constraints in school district print shops. OSHA lockout/tagout standards and NHTSA-influenced workplace safety audits drive replacement demand in aging American binderies. Midwest industrial zones concentrate distributor relationships for mid-market equipment.
China
Manufacturing zones in Guangdong and Jiangsu provinces absorb high-volume cutting lines for packaging and label production workflows. GB standards and SAMR certification requirements create separate compliance pathways distinct from CE marking frameworks. Dual carbon goals in Beijing reshape energy efficiency benchmarks for motorized cutter platforms.
Japan
Commercial binderies in Kanto and Kansai regions prioritize ceramic composite blade substrates for abrasive wear resistance in coated stock processing. METI industrial efficiency guidelines encourage automation adoption to address technician scarcity. Nagoya precision manufacturing corridor supplies control system components to regional equipment assemblers.
India
Educational and commercial printing sectors in Maharashtra and Karnataka expand automated cutter procurement as bindery modernization accelerates. BIS certification requirements and state-level industrial policy incentives shape equipment import decisions. Mumbai-Pune manufacturing belt concentrates distributor networks for mid-range programmable systems.
Automatic Paper Cutter Market Competitive Environment
Strategic partnerships dominate the current landscape as equipment manufacturers align with software providers and distributor networks to capture mid-market upgrade cycles. The vendor base separates into three distinct tiers: precision engineering specialists with in-house grinding technology, modular system integrators serving retrofit demand, and volume-oriented fabricators targeting institutional procurement channels. Geographic concentration in German engineering clusters and North American distributor networks creates natural segmentation. Competitive moves center on technology licensing agreements and geographic expansion through regional distributor relationships.
Among German precision engineering specialists, Polar Mohr and Baumann Maschinenbau Solms exemplify the premium-tier positioning built around in-house component manufacturing and regional cluster proximity. Ideal Krug & Priester occupies a position within the same archetype, leveraging proximity to Ludwigsburg engineering infrastructure. Challenge Machinery represents the North American institutional channel approach, anchoring distributor-dependent market access for educational and mid-market commercial buyers. These three company structures illustrate how geographic origin and organizational form shape competitive positioning without requiring vertical integration into upstream supply chains.
| Leading Market Players |
|---|
| Perfecta Cutting Systems |
| Standard Horizon |
| Polar Mohr |
| Colter & Peterson |
| MBM Corporation |
| Challenge Machinery |
| Ideal Krug & Priester |
| Baumann Maschinenbau Solms |
| Duplo International |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions and RoHS limitations gate qualified supply for EU-bound automatic paper cutters, forcing hydraulic fluid and electrical insulation reformulation through ECHA notification pathways. This regulatory filter concentrates premium-tier pricing access among German precision engineering clusters with in-house testing capacity, while non-compliant imports absorb elevated redesign expenses or exit the market entirely.
Pricing Analysis
Input-cost pass-through from tungsten carbide and ceramic composite blade substrates compresses margins for mid-tier fabricators unable to absorb material premiums. Three-tier pricing structure across premium, standard, and economy levels separates programmable systems with servo-driven backgauge positioning from basic guillotine configurations. Price differentiation hinges on CE marking compliance depth and after-sales service bundling. Cost compression in economy-tier manual feed units is intensifying because educational procurement channels prioritize capital expenditure minimization over performance specifications.
Supply Chain Analysis
Dual-sourcing requirements for hardened blade substrates and servo motor assemblies push commercial binderies to qualify suppliers across Germany, Japan, and China. Raw material dependencies center on tungsten carbide powders, high-grade carbon steel forgings, and precision-machined castings for backgauge mechanisms. Single-source vulnerability concentrates in ceramic composite substrate formulations where Japanese suppliers anchor specialized production. Distribution runs through regional distributor networks in North America and direct OEM relationships in European precision engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic paper cutter market reads as a late-cycle quality story, with commercial printing houses shifting procurement toward programmable systems that eliminate manual setup labor and compress cutting tolerances.
For Market Incumbents: Acquire digital control platform capabilities to defend against software-defined workflow providers encroaching on finishing equipment margins. Deepen backward integration into ceramic composite blade grinding technology to capture service interval extension value. Prioritize certification investment for SAMR pathways targeting Asian manufacturing zones. For New Entrants and Emerging Players: Cloud-connected predictive maintenance algorithms offer a technology-first wedge into mid-market binderies constrained by mechatronics technician scarcity. Modular retrofit kits for aging cutter frames represent the most penetrable segment, accommodating capital budget limitations in North American educational procurement. Lead with subscription-based software tiers rather than capital equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for precision engineering specialists with captive blade grinding capacity because maintenance contract structures are fragmenting toward per-cut pricing. Target acquisition archetypes include regional distributors with embedded relationships in institutional channels. Watch for inflection when ceramic composite grind intervals compress industry-wide maintenance revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Substrate Production | German clusters capture grind interval extension value through in-house ceramic composite capacity. |
| Modular Retrofit Kit Development | Aging binderies upgrade legacy frames without full replacement, accommodating constrained capital budgets. |
| SAMR Certification Pathway Investment | Separate compliance tracks open Asian manufacturing zones distinct from CE marking frameworks. |
| Cloud-Connected Predictive Maintenance Platform | Software subscriptions displace capital sales in educational and institutional procurement channels. |
| Regional Distributor Network Expansion | Mid-market access in North America depends on embedded relationships with school district print shops. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial printing house operations directors, bindery maintenance technicians, OEM procurement managers, and educational institutional purchasing coordinators with secondary validation against EU Machinery Directive compliance databases, ECHA substance restriction filings, and regional trade association shipment statistics. Bottom-up equipment deployment estimates triangulated against top-down market value reconstruction across the analysis window.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns in German commercial printing and North American educational procurement. Segmentation modeling spanned product type sophistication, control system architecture, blade substrate material grade, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to equipment unit economics and service revenue pools, incorporating inputs from technician labor availability constraints and safety mandate compliance timelines.
The model holds under stable regulatory enforcement intensity; deviation in REACH substance restriction expansion or dual carbon goal acceleration in Beijing would shift replacement demand timing and regional supply concentration. Forecasts reflect documented assumptions about blade substrate technology adoption curves and distributor channel consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Tissue Paper Unwinding Machine Market