
 Stretch Blow Molding Machines Market | 2026-2036
Stretch Blow Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Blow Molding Machines Market Analytics
Specialty beverage bottlers is reorganizing procurement priorities toward high-speed linear systems. Sidel leverages integrated aseptic blow-fill-seal platforms to anchor European premium water contracts. Krones AG competes through modular retrofit architectures that extend machine lifecycles without full replacement. Nissei ASB specializes in single-stage precision molding for pharmaceutical-grade containers, occupying a defensible niche against larger line builders.
Stretch blow molding machines inject and stretch preforms biaxially within blow molds, achieving PET wall thickness below 0.25 mm at outputs exceeding 2,000 bottles per cavity per hour. This process serves primarily carbonated beverage, bottled water, and edible oil packaging where barrier consistency and lightweighting determine shelf performance. Single-stage systems command margin pools in pharmaceutical and cosmetic applications requiring dimensional tolerances under 0.1 mm, while multiple-stage rotary architectures dominate high-volume beverage lines above 50,000 bottles per hour. PET material demand outpaces HDPE and PVC alternatives as recyclability mandates from EUs Packaging and Packaging Waste Regulation reshape converter specifications.
FDA 21 CFR food-contact substance notifications and EUs REACH restrictions on antimony catalyst residues constrain preform composition and machine thermal management protocols. Chinas GB standards for food packaging plastics and SAMR quality inspections create parallel compliance layers for equipment exporters. The countrys national standards body continues tightening volatile organic compound emission thresholds during preform heating cycles. Stakeholders must monitor how deposit-return schemes in Germany, France, and Italy alter bottle lightweighting targets and corresponding machine clamp-force requirements.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing bottle lightweighting targets and forcing recalibration of clamp-force specifications across installed machine bases. This regulatory compression is reshaping procurement criteria faster than typical replacement cycles.
Growth Catalysts
- Deposit-return schemes:Germany, France, and Italy have operationalized bottle-to-bottle recycling loops. These systems demand higher-throughput rotary architectures to process returned flake into food-grade preforms.
- Pharmaceutical-grade PET:Single-stage precision molding systems achieve dimensional tolerances under 0.1 mm. This capability opens dedicated contract manufacturing for injectable and ophthalmic packaging.
- Carbonated soft drink clusters:Production concentration in China, Brazil, and Germany anchors machine procurement cycles. Bottlers in these markets prioritize line integration over standalone equipment purchases.
Market Restraints
- Antimony catalyst residue limits:EUs REACH restrictions and FDA 21 CFR notifications constrain preform thermal management protocols. Compliance requires upgraded heating tunnel configurations that extend delivery timelines.
- Preform supply concentration:Asia-based resin converters control upstream PET pellet flows. Equipment buyers face input cost volatility when crude-derived paraxylene prices fluctuate.
- Rotary system footprint constraints:High-output multiple-stage architectures exceed floor space availability at legacy beverage facilities in mature European markets. Site retrofit costs rival new equipment expenditure.
Strategic Opportunities
- Modular retrofit architectures:Krones AG and competing line builders can extend machine lifecycles without full replacement. This service layer captures margin from installed base maintenance deferrals.
- Aseptic blow-fill-seal convergence:Premium water and sensitive beverage segments demand integrated platforms. Sidel leverages this technology to anchor European contract manufacturing relationships.
- India packaged beverage expansion:FSSAI food-contact regulations are tightening parallel to EU standards. Domestic bottlers require compliant equipment upgrades as per-capita bottled water consumption climbs.
Industry Challenges
- Multi-jurisdictional certification timelines:FDA 21 CFR notifications, EU REACH compliance documentation, and Chinas GB standards for food packaging plastics create parallel approval tracks. Equipment exporters face 14-18 month validation cycles.
- Heating cycle VOC emission thresholds:Chinas national standards body continues tightening volatile organic compound limits during preform conditioning. Retrofitting existing ovens to meet evolving thresholds strains technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Blow Molding Machines Market |
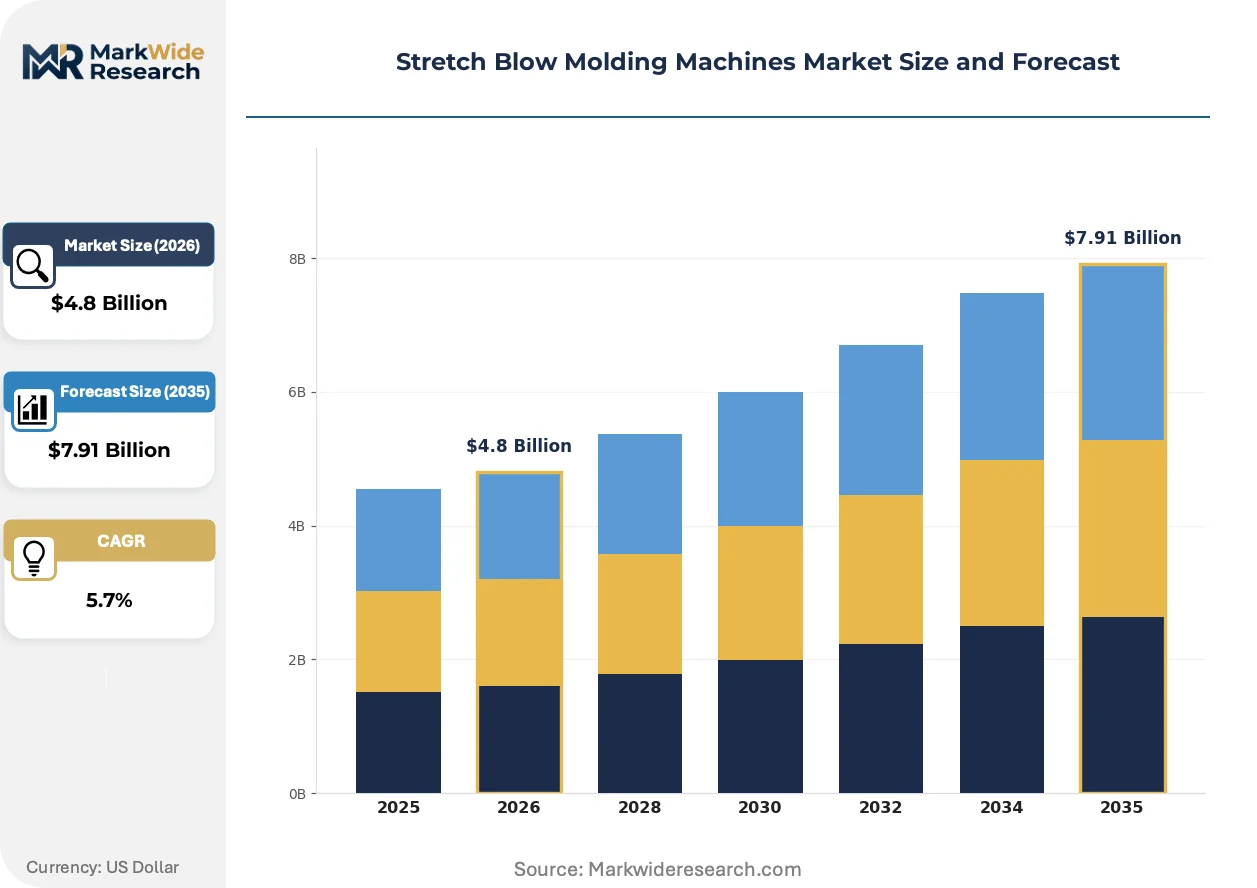
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multiple Stage, Continuous, Semi-Continuous Material: PET, HDPE, PVC, Others End User: Food & Beverage, Healthcare, Personal Care, Consumer Goods Capacity: Low Capacity, Medium Capacity, High Capacity, Very High Capacity |
| Companies Covered | Sidel, Krones AG, KHS Group, Nissei ASB, Aoki Technical Laboratory, SIPA, SMI Group, Tech-Long, Chumpower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Blow Molding Machines Market Evolving Landscape
Machine architecture is bifurcating between compact linear systems for specialty applications and massive rotary platforms for commodity beverage volume. This divergence is compressing mid-tier equipment viability and reshaping R&D allocation across manufacturers.
Electrical servo-driven stretch rods are miniaturizing hydraulic actuation out of precision molding cells. Pharmaceutical and cosmetic converters in Switzerland and Japan adopt these systems for batch-size flexibility below 5,000 units. The technology is miniaturizing cleanroom footprints and reducing changeover downtime from four hours to under forty minutes.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon and CO2-based blowing agent adoption. Equipment suppliers must redesign heating and mold temperature control circuits to handle flammable refrigerant loops. Blow molding lines for edible oil and sensitive beverages face the steepest retrofit obligations under the 2024-2030 reduction pathway.
Beverage bottlers now unbundle after-sales service from initial equipment procurement. Third-party technical service networks in Brazil and Mexico are capturing maintenance contracts from original manufacturers. This channel fragmentation is visible most acutely in carbonated soft drink operations where line utilization rates exceed 85 percent and downtime penalties escalate contract values.
Stretch Blow Molding Machines Market Segmentation
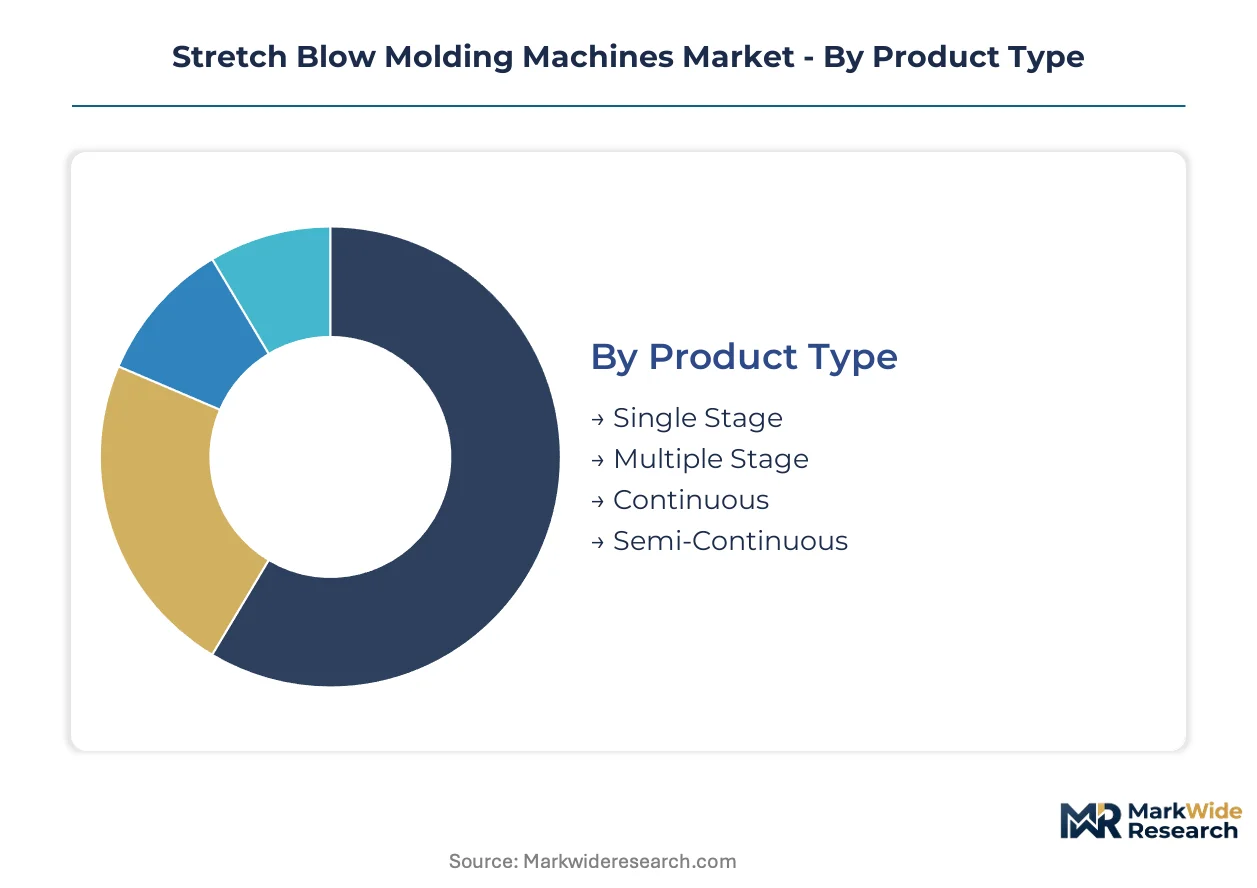
Machine architecture and material specifications determine procurement economics across beverage, pharmaceutical, and cosmetic packaging lines. Segment boundaries are hardening as regulatory compliance requirements diverge between food-contact and medical-grade applications.
Product Type:
Margin pools concentrate in precision-controlled single-stage systems where pharmaceutical contracts command premium pricing over commodity beverage lines.
- Single Stage:Injection and blow molding occur within one machine cycle, achieving dimensional tolerances under 0.1 mm for pharmaceutical-grade containers. Swiss and Japanese cosmetic converters adopt these systems for batch-size flexibility below 5,000 units, miniaturizing cleanroom footprints and reducing changeover downtime from four hours to under forty minutes.
- Multiple Stage:Preform injection and blow molding execute across separate machines, enabling rotary architectures that exceed 50,000 bottles per hour. Carbonated soft drink production clusters in Germany, China, and Brazil anchor procurement cycles for these high-throughput systems where line integration outweighs standalone equipment purchases.
- Continuous:Non-interrupted production flow suits edible oil and bottled water applications with stable demand profiles and minimal SKU variation.
- Semi-Continuous:Intermittent indexing allows format changeovers without full line shutdown, serving contract packagers with diverse portfolio requirements.
Multiple Stage holds installed capacity. Single Stage is rotating up the share rankings.
Material:
Recyclability mandates from the EU's Packaging and Packaging Waste Regulation are compressing specification sheets toward mono-material solutions.
- PET:Dominates barrier-sensitive applications with wall thickness below 0.25 mm achievable at outputs exceeding 2,000 bottles per cavity per hour. EUs REACH restrictions on antimony catalyst residues and FDA 21 CFR food-contact substance notifications constrain preform composition and thermal management protocols, forcing upgraded heating tunnel configurations.
- HDPE:Serves dairy and chemical packaging where moisture resistance outweighs oxygen barrier requirements. Chinas GB standards for food packaging plastics and SAMR quality inspections create parallel compliance layers for equipment exporters targeting this material segment.
- PVC:Retains niche presence in industrial and non-food applications despite regulatory pressure on plasticizer migration.
- Others:Bio-based and recycled-content polymers are gaining trial deployments in premium water segments seeking differentiation through sustainability claims.
PET commands the dominant installed base. Recycled-content grades are climbing the specification ladder fastest.
End User:
Application-specific compliance requirements split procurement criteria between aseptic beverage lines and cleanroom pharmaceutical systems.
- Food & Beverage:Carbonated soft drink and bottled water production clusters anchor machine procurement cycles in Germany, China, and Brazil. Sidel leverages integrated aseptic blow-fill-seal platforms to anchor European premium water contracts, while Krones AG competes through modular retrofit architectures.
- Healthcare:Injectable and ophthalmic packaging demand single-stage precision molding with dimensional tolerances under 0.1 mm. Nissei ASB occupies this defensible niche against larger line builders.
- Personal Care:Cosmetic converters prioritize batch-size flexibility and rapid changeover capability over maximum throughput.
- Consumer Goods:Household chemical packaging tolerates wider tolerance bands, favoring cost-optimized multiple-stage configurations.
Food & Beverage holds installed capacity. Healthcare is rotating up the share rankings.
Capacity:
Floor space constraints at legacy European facilities are compressing mid-tier equipment viability while favoring either compact linear systems or massive rotary platforms.
- Low Capacity:Output below 10,000 bottles per hour serves specialty beverage bottlers and pharmaceutical contract manufacturers. Electrical servo-driven stretch rods are miniaturizing hydraulic actuation out of these precision molding cells.
- Medium Capacity:10,000-30,000 bottles per hour range faces margin compression as architecture bifurcation accelerates.
- High Capacity:30,000-50,000 bottles per hour dominates mainstream carbonated soft drink operations where line utilization rates exceed 85 percent.
- Very High Capacity:Exceeding 50,000 bottles per hour requires rotary architectures with footprint demands that rival new equipment expenditure at constrained European sites. Deposit-return schemes in Germany, France, and Italy demand these throughputs to process returned flake into food-grade preforms.
High Capacity holds installed capacity. Very High Capacity is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export rotary blow molding systems to beverage bottlers across Brazil and China, while Asian preform converters supply resin-dependent machine operators in North America and Europe.
Germany
Carbonated soft drink production clusters in Bavaria and North Rhine-Westphalia anchor procurement cycles for high-throughput rotary architectures. Deposit-return schemes operationalized under national packaging law demand bottle-to-bottle recycling loops with food-grade preform processing capability. Krones AG leverages modular retrofit architectures from its Neutraubling headquarters to extend machine lifecycles across European installed bases.
China
Bottled water production concentration in Guangdong and Zhejiang provinces drives demand for very high capacity systems exceeding 50,000 bottles per hour. GB standards for food packaging plastics and SAMR quality inspections create compliance layers for equipment exporters targeting this market. Tech-Long and Chumpower anchor domestic supply chains from manufacturing clusters in the Pearl River Delta.
Brazil
Carbonated beverage bottlers in São Paulo and Minas Gerais prioritize line integration over standalone equipment purchases. ANVISA pharmaceutical regulations open contract manufacturing opportunities for single-stage precision molding in injectable packaging. Sidel captures premium water contracts through integrated aseptic platforms deployed at production facilities in the Southeast region.
United States
Specialty beverage bottlers in California and Texas reorganize procurement priorities toward high-speed linear systems for craft and functional drink segments. FDA 21 CFR food-contact substance notifications constrain preform thermal management protocols for equipment entering the market. Third-party technical service networks in Mexico capture maintenance contracts from original manufacturers serving cross-border operations.
India
Packaged beverage expansion in Maharashtra and Gujarat accelerates as FSSAI food-contact regulations tighten parallel to EU standards. Per-capita bottled water consumption climbs in urban centers, requiring compliant equipment upgrades from domestic and imported suppliers. SIPA and SMI Group position rotary architectures to serve contract packagers with diverse portfolio requirements in the Western region.
Stretch Blow Molding Machines Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic reach. The vendor base separates into three tiers: integrated line builders with full beverage system portfolios, precision molding specialists serving pharmaceutical niches, and regional fabricators capturing aftermarket service contracts. Consolidation pressures concentrate among mid-scale rotary system providers as architecture bifurcation accelerates between compact linear and massive platform designs. Dominant competitive moves include modular retrofit service layering and aseptic blow-fill-seal technology licensing.
Within the integrated line builder tier, Sidel and Krones AG exemplify European-listed entities with beverage system portfolios spanning blow molding through filling and labeling. Nissei ASB occupies a defensible position among Japanese precision specialists, representing the single-stage pharmaceutical-grade segment where dimensional tolerances under 0.1 mm command premium pricing. These three anchors illustrate how competitive positioning stratifies across commodity volume, precision medical, and retrofit service archetypes rather than converging on uniform technology platforms.
| Leading Market Players |
|---|
| Sidel |
| Krones AG |
| KHS Group |
| Nissei ASB |
| Aoki Technical Laboratory |
| SIPA |
| SMI Group |
| Tech-Long |
| Chumpower |
| Others |
Value Network & Pricing Analysis
Electrical servo-driven stretch rods displacing hydraulic actuation simultaneously concentrate component supply in Switzerland and Japan while compressing maintenance pricing premiums for legacy pneumatic systems. This substitution dynamic redraws procurement geography toward precision-motor fabricators and forces beverage bottlers to recalibrate total-cost-of-ownership models across extended depreciation horizons.
Pricing Analysis
Technology-generation pricing gaps separate current-gen aseptic blow-fill-seal platforms from prior-gen standalone blow molders and next-gen integrated cleanroom systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in mid-tier rotary architectures intensifies because European deposit-return schemes demand rapid retrofit compliance. Contract packagers with diverse SKU portfolios exhibit highest price sensitivity, while pharmaceutical-grade single-stage buyers prioritize dimensional tolerance guarantees over capital expenditure minimization.
Supply Chain Analysis
Inventory lead times for precision heating tunnel components now stretch eighteen to twenty-four months at German and Italian subsystem suppliers. Machine assembly draws from China for PET preform injection units, Germany for clamp-force mechanisms, and Japan for servo-drive controls. Single-source vulnerability concentrates in high-wattage infrared oven elements sourced from limited European foundries. Distribution runs through OEM-direct channels for greenfield beverage lines and third-party technical service networks for aftermarket retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of technicians certified for multi-jurisdictional FDA-EU-China compliance documentation constrains how quickly equipment exporters can scale validation throughput. This capability gap determines which line builders capture premium pricing for rapid market entry.
For Market Incumbents: Shield installed-base relationships by layering modular retrofit architectures that extend machine lifecycles without full replacement. Krones AG demonstrates this defensive posture through Neutraubling-based technical service teams. Certification investment in China's evolving GB standards for VOC emission thresholds provides channel control against emerging domestic competitors. For New Entrants and Emerging Players: Anchor in India's packaged beverage expansion where FSSAI regulations tighten parallel to EU standards but local fabrication capacity lags demand. Western region contract packagers with diverse portfolio requirements represent the most penetrable buyer archetype. Go-to-market execution should emphasize rapid spare parts availability through Mumbai-based distribution partnerships rather than equipment-only positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision molding specialists serving pharmaceutical niches with dimensional tolerances under 0.1 mm. Five-to-ten year viability hinges on whether deposit-return schemes in Germany, France, and Italy sustain demand for very high capacity rotary architectures. Watch for inflection when China's SAMR quality inspection protocols extend to cover recycled-content PET pellet flows.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Architecture Deployment | Krones AG extends machine lifecycles across European installed bases without requiring full replacement capital. |
| Aseptic Blow-Fill-Seal Platform Integration | Sidel anchors premium water contracts through European contract manufacturing relationships demanding sterile packaging. |
| Pharmaceutical-Grade Precision Molding Specialization | Nissei ASB occupies defensible niche against larger line builders with dimensional tolerances under 0.1 mm. |
| Electrical Servo-Driven Stretch Rod Adoption | Swiss and Japanese cosmetic converters achieve batch-size flexibility below 5,000 units with reduced changeover downtime. |
| Hydrocarbon Blowing Agent Circuit Redesign | Equipment suppliers handle flammable refrigerant loops under EU F-Gas Regulation phase-down schedules for edible oil lines. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interview data combined with secondary validation from customs records, SEC filings of listed equipment manufacturers, and SAMR quality inspection protocols. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness across machine architecture bifurcation scenarios and regulatory compliance timeline variations. Segmentation dimensions included product type, material specification, end-use application, and regional production cluster. CAGRs derived from installed base replacement cycles and greenfield capacity announcements throughout the forecast period. Specific inputs captured deposit-return scheme operationalization rates and pharmaceutical packaging contract award velocity.
Material uncertainties — antimony catalyst residue limit revisions, paraxylene price volatility, and VOC emission threshold tightening — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and resin supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market