
 Sack Filling Machine Market | 2026-2036
Sack Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sack Filling Machine Market Analytics
After-sales service contracts is expanding as a revenue layer in the sack filling machine sector, shifting vendor economics from pure equipment sales toward lifecycle value capture. Premier Tech Ltd. leverages its North American installed base to secure multi-year maintenance agreements. CONCETTI S.P.A anchors its Italian manufacturing footprint with rapid-response technical teams across Mediterranean markets. PAYPER S.A differentiates through software-integrated remote diagnostics that reduce unplanned downtime for chemical processors.
A sack filling machine is an industrial packaging system designed to dispense dry bulk solids or powders into woven polypropylene, paper, or laminated sacks at rates typically ranging from 200 to 2,000 bags per hour, with primary application in automated production lines for cement, flour, fertilizer, and petrochemical feedstocks. Automatic product type configurations command the widest deployment in high-throughput food and chemical plants where labor scarcity elevates total cost of ownership calculations. Electronic technology segments are gaining share as servo-driven net-weigh systems displace legacy pneumatic controls in precision-critical applications.
CE marking under the EU Machinery Directive and FDA food-contact surface regulations govern material selection and hygienic design standards for machines serving regulated industries. OSHA lockout/tagout requirements in the United States further shape guard interlock and access-panel specifications. Stakeholders must monitor how evolving ESG disclosure rules, including the EU CSRD, extend carbon-accounting obligations upstream to packaging equipment suppliers and their component sourcing decisions.
Market Dynamics
Food processors across Europe and North America are consolidating bulk packaging lines around single-source automation vendors to compress commissioning timelines and unify compliance documentation under tightening FDA and EFSA material-contact rules.
Growth Catalysts
- REACH substance restrictions:European chemical registrants must validate machine surface coatings for SVHC content, creating replacement demand for legacy equipment that cannot meet ECHA documentation thresholds.
- Cement sector automation:Dust-exposure regulations in Germany and Poland are forcing manual bagging operations toward enclosed automatic systems with integrated dust-collection interfaces.
- Servo-driven net-weigh systems:These configurations achieve fill accuracies within 0.1% for high-value chemical powders, justifying capital outlays against pneumatic alternatives in Swiss and Dutch specialty chemical plants.
Market Restraints
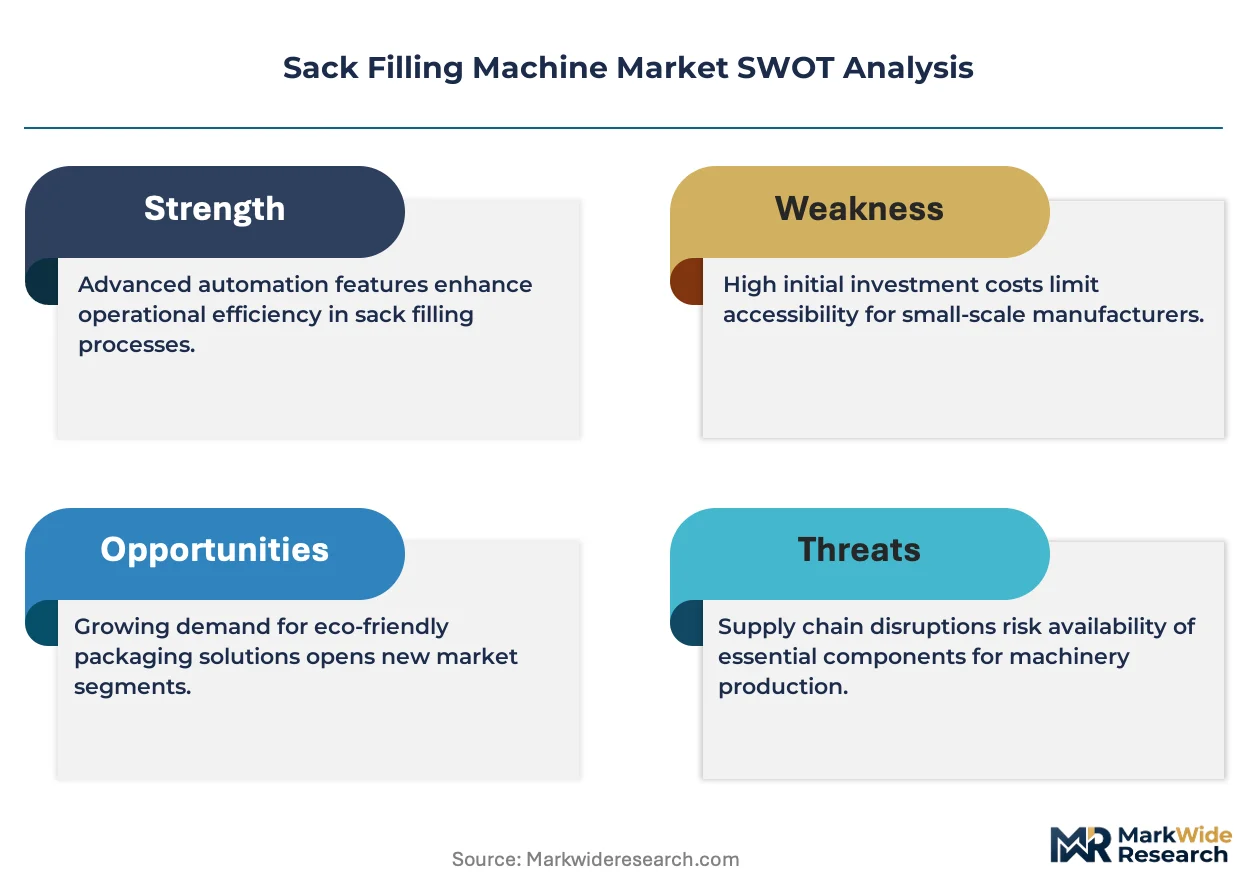
- Stainless steel price volatility:Grade 304 and 316 sheet metal constitute 35-45% of machine variable costs, with Turkish and Chinese mill pricing subject to anti-dumping duty adjustments that compress vendor margins.
- Control system supplier concentration:Siemens, Rockwell, and Schneider Electric dominate servo drive and PLC supply, creating single-source vulnerability for mid-tier machine builders in Italy and Spain.
- Bag material incompatibility:Recyclable mono-material woven sacks lack the dimensional stability of multi-layer laminates, limiting throughput speeds on legacy form-fill-seal configurations without mechanical retrofits.
Strategic Opportunities
- Indian food processing corridors:FSSAI-mandated hygienic design standards for flour and spice packaging are accelerating demand for stainless-steel contact surfaces in Gujarat and Maharashtra processing clusters.
- Remote diagnostics convergence:Integration of edge computing with vibration sensors enables predictive maintenance contracts that extend vendor revenue streams beyond equipment sale.
- Brazilian fertilizer distribution:ANVISA traceability requirements for agrochemical packaging are creating specification premiums for machines with integrated barcode verification and weight-data logging.
Industry Challenges
- Servo commissioning expertise:Shortage of technicians capable of tuning multi-axis motion profiles delays installation acceptance and extends project timelines for chemical sector deployments.
- CE-MDR documentation burden:Extended technical file preparation for EU Machinery Directive conformity assessment stretches engineering resources at mid-cap Italian and German builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sack Filling Machine Market |
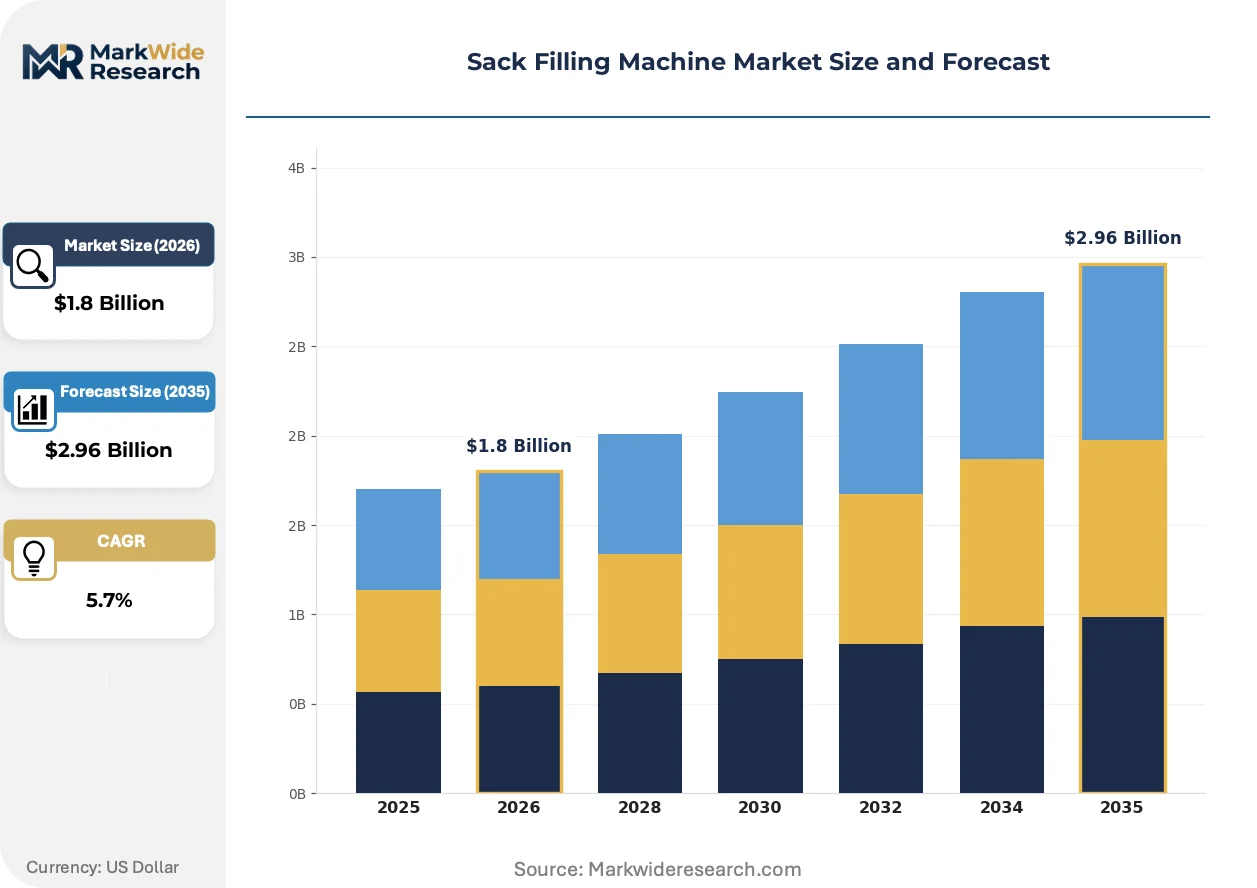
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Bulk Technology: Pneumatic, Mechanical, Electronic, Hydraulic End User: Food Industry, Chemical Industry, Construction, Agriculture Filling Method: Weighing, Volumetric, Gravity, Vacuum |
| Companies Covered | Premier Tech Ltd., CONCETTI S.P.A, PAYPER S.A, Industria Macchine Automatiche SpA, Bossar Packaging S.A, Tinsley Equipment Company LLC, Choice Bagging Equipment, Votech, PLÜMAT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sack Filling Machine Market Evolving Landscape
Electrification of mechanical functions and software-defined control architectures are compressing the performance gap between premium and mid-tier equipment categories, redistributing buyer value capture toward lifecycle service contracts.
Servo-driven net-weigh filling systems is overtaking pneumatic gross-weigh configurations in high-precision chemical and food applications. Specialty chemical processors in the Netherlands and Belgium are specifying these systems for pigment and additive packaging where 50-gram fill tolerances determine batch acceptance. The technology is overtaking legacy pneumatic controls by eliminating compressed air infrastructure and enabling closed-loop feedback that reduces overfill giveaway.
EU CSRD carbon-accounting disclosure rules are extending upstream to packaging equipment suppliers, mandating Scope 3 emissions documentation for steel sourcing and component logistics. Machine builders serving multinational food and chemical accounts must now validate supplier carbon intensities or risk exclusion from approved vendor lists. German and French engineering firms are responding by regionalizing fabrication to shorten transport emissions and satisfy auditor traceability requirements.
Buyers are unbundling after-sales service from initial equipment procurement, negotiating multi-year maintenance agreements through competitive tender rather than accepting OEM-captive service packages. Chemical processors in the US Gulf Coast and Rotterdam-Antwerp corridor are leading this shift, using third-party industrial service contractors with cross-brand technician certifications. The practice is most visible in continuous-process fertilizer and petrochemical plants where unplanned downtime costs exceed service contract premiums by an order of magnitude.
Sack Filling Machine Market Segmentation
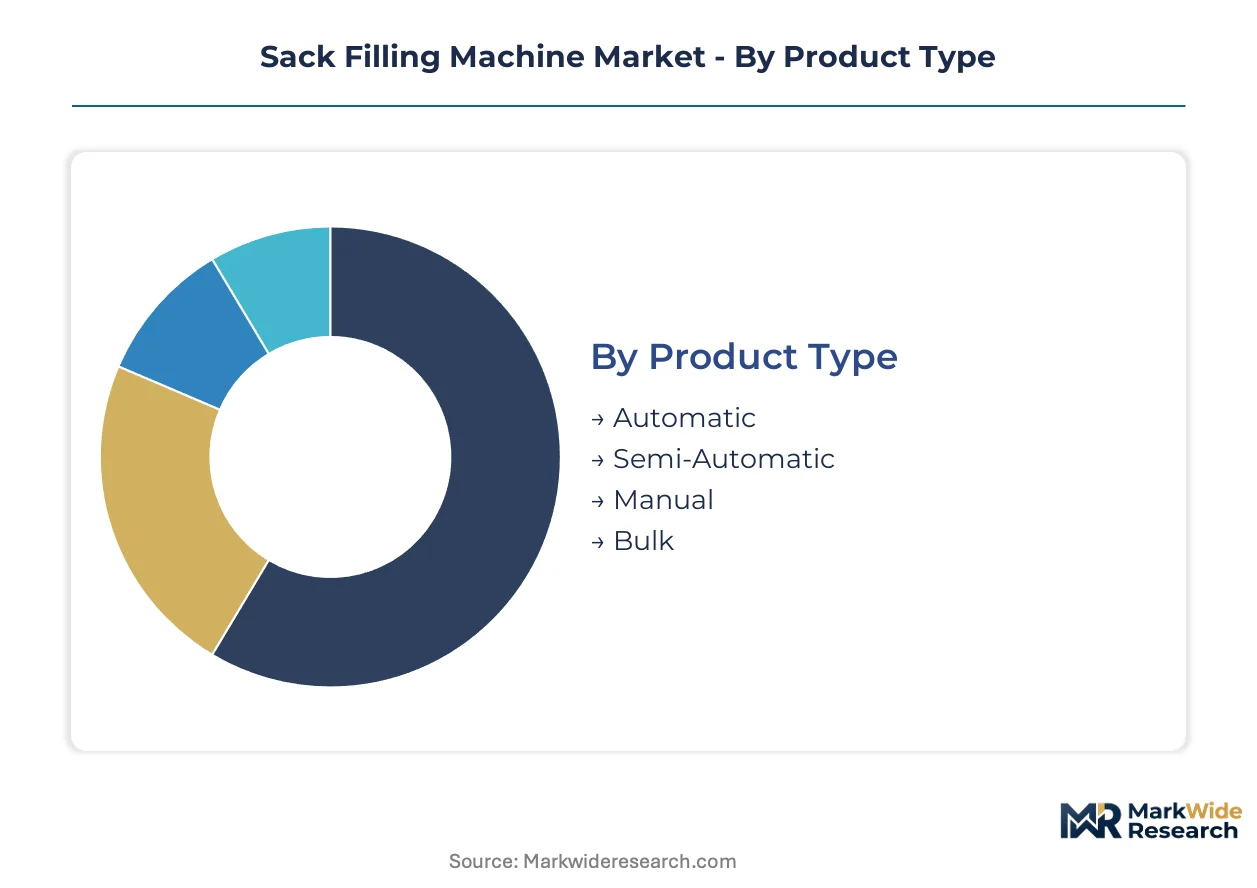
Segmentation in the sack filling machine market reveals how packaging automation priorities diverge across capital intensity, precision requirements, and regulatory exposure. Buyers select configurations based on throughput demands, labor economics, and material-handling constraints rather than uniform technology preferences.
Product Type:
Buyers differentiate primarily by labor substitution economics and line integration complexity, with capital availability determining the threshold for full automation.
- Automatic:Servo-driven systems achieve 1,000-2,000 bags per hour with integrated palletizing and stretch-wrapping. High-throughput flour mills in Germany and cement plants in Poland deploy these configurations to satisfy dust-exposure regulations and compress staffing levels. Automatic configurations lead volumes today; Bulk systems are gaining share fastest.
- Semi-Automatic:Operator-assisted bag placement with automated filling and weighing cycles bridges manual and fully automatic economics. Mid-scale spice processors in Gujarat and regional fertilizer blenders in Brazil favor this tier for flexibility across multiple stock-keeping units without full line reconfiguration.
- Manual:Pedal- or lever-actuated filling stations persist in artisanal food production and small-batch chemical compounding where throughput falls below 200 bags per hour and capital constraints preclude automation.
- Bulk:Containerized and big-bag filling systems handle 500-2,000 kilogram loads for petrochemical feedstocks and construction aggregates, bypassing individual sack handling entirely.
Automatic configurations dominate revenue concentration; Bulk systems are expanding most quickly in chemical export corridors.
Technology:
Control architecture selection determines precision capability, energy intensity, and maintenance staffing requirements across installed bases.
- Electronic:Servo-driven net-weigh systems with closed-loop feedback achieve 0.1% fill accuracy for high-value pigment and additive packaging. Specialty chemical processors in the Netherlands and Belgium specify these to eliminate overfill giveaway and compressed air infrastructure. Electronic systems lead volumes today; Pneumatic retains share only in legacy cement installations.
- Pneumatic:Compressed-air actuation dominates legacy cement and construction material installations where fill tolerance of 0.5% suffices and maintenance technician familiarity reduces commissioning risk.
- Mechanical:Cam-driven and linkage-based systems persist in developing market flour milling where electrical supply reliability varies and mechanical simplicity supports local fabrication and repair.
- Hydraulic:High-force actuation for dense, abrasive materials in mining and heavy construction applications where pneumatic or electronic drives lack sufficient torque density.
Electronic systems command the steepest expansion trajectory; Hydraulic maintains niche position in extractive industries.
End User:
Industry-specific material properties and regulatory exposure shape machine specification priorities more than throughput scale alone.
- Food Industry:Stainless-steel contact surfaces with FDA and EFSA-compliant finishes for flour, sugar, and spice handling. FSSAI-mandated hygienic design standards in Maharashtra and Gujarat processing clusters are accelerating specification premiums for 316-grade construction and clean-in-place capability.
- Chemical Industry:Explosion-proof enclosures and dust-collection integration for pigment, fertilizer, and petrochemical powder handling. ANVISA traceability requirements in Brazil and REACH SVHC documentation obligations in Europe drive specification complexity.
- Construction:Heavy-duty framing and abrasion-resistant contact surfaces for cement, lime, and gypsum packaging. German and Polish dust-exposure regulations are forcing manual operations toward enclosed automatic systems.
- Agriculture:Corrosion-resistant construction for fertilizer, seed, and animal feed handling with seasonal utilization patterns that favor equipment mobility and rapid format changeover.
Food Industry leads installed base concentration; Chemical Industry is climbing the fastest on specialty powder automation demand.
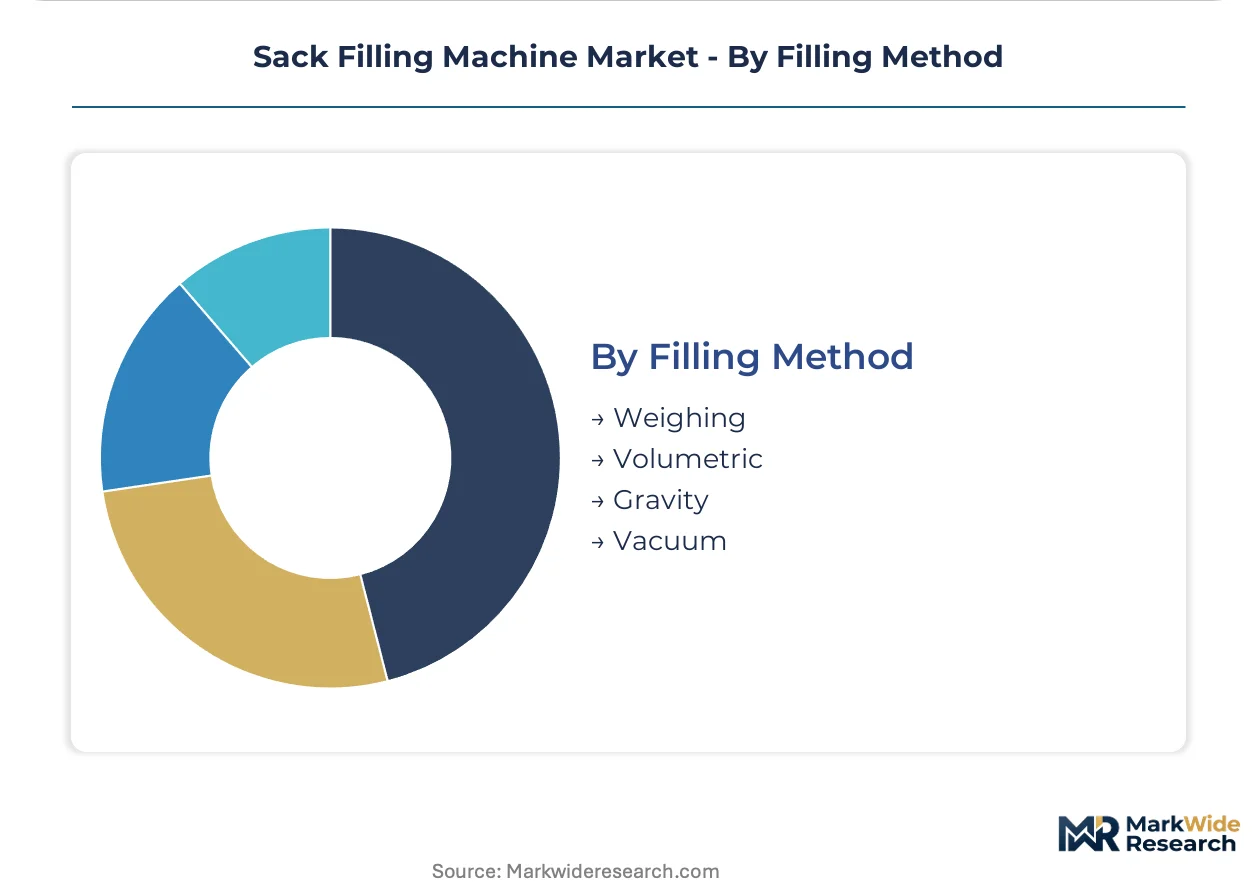
Filling Method:
Measurement principle selection balances accuracy requirements against product characteristics including flowability, bulk density variation, and value density.
- Weighing:Net-weigh and gross-weigh configurations with load cell feedback achieve highest precision for high-value chemical additives and pharmaceutical intermediates. Servo-driven implementations are displacing pneumatic controls in Swiss and Dutch specialty chemical plants.
- Volumetric:Auger, cup, and belt-feed systems for free-flowing granules and pellets where bulk density remains consistent and speed outweighs absolute accuracy. Dominates fertilizer and seed packaging.
- Gravity:Simple chute-fed systems for large-particle, free-flowing materials in construction aggregates and coarse agricultural products with minimal value density.
- Vacuum:Pneumatic conveying with vacuum-assisted densification for fine, aerated powders that resist gravity flow, including carbon black and fumed silica in specialty chemical applications.
Weighing systems lead revenue contribution today; Vacuum methods are expanding most quickly in fine powder handling segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering-intensive manufacturers export across Central and Eastern Europe, while Indian food processing clusters in Gujarat and Maharashtra drive specification premiums for hygienic stainless-steel construction under tightening FSSAI mandates.
Germany
Dust-exposure regulations from the Federal Ministry of Labour and Social Affairs accelerate cement sector automation toward enclosed systems with integrated dust-collection interfaces. REACH SVHC documentation obligations under ECHA force chemical registrants to validate machine surface coatings, generating replacement demand for legacy equipment. Engineering firms in North Rhine-Westphalia regionalize fabrication to satisfy EU CSRD carbon-accounting traceability requirements.
United States
OSHA lockout/tagout requirements shape guard interlock specifications for chemical processors along the Gulf Coast. FDA food-contact surface regulations govern stainless-steel finish standards for flour and spice packaging automation. Third-party industrial service contractors with cross-brand certifications capture maintenance agreements from OEM-captive packages in continuous-process fertilizer plants.
India
FSSAI-mandated hygienic design standards for flour and spice packaging accelerate demand for 316-grade stainless-steel contact surfaces. The country's national food safety regulator enforces clean-in-place capability specifications that elevate capital outlays versus legacy carbon-steel alternatives. Processing clusters in Gujarat and Maharashtra concentrate specification activity for automatic configurations serving bulk commodity exporters.
Brazil
ANVISA traceability requirements for agrochemical packaging create specification premiums for machines with integrated barcode verification and weight-data logging. The national health surveillance agency mandates documentation chains that favor vendors with software-integrated control architectures. Fertilizer distribution networks in São Paulo and Minas Gerais states concentrate demand for high-throughput automatic systems with seasonal utilization flexibility.
Netherlands
Specialty chemical processors in Rotterdam-Antwerp corridor specify servo-driven net-weigh systems achieving 0.1% fill accuracy for pigment and additive packaging. ECHA REACH compliance documentation extends to machine surface coatings, favoring vendors with validated supplier chains. Belgian and Dutch plants eliminate compressed air infrastructure through closed-loop electronic controls that reduce overfill giveaway.
Sack Filling Machine Market Competitive Landscape
Top-tier vendors anchor premium engineering-intensive segments, while mid-cap fabricators compete on regional service density and commissioning speed. The vendor base stratifies across three archetypes: German and Italian engineering houses with export-focused manufacturing footprints, North American service-integrated providers leveraging installed base capture, and Asian fabricators scaling standard configurations for price-sensitive developing markets. Dominant competitive moves include geographic expansion through distributor partnerships and technology licensing agreements that accelerate servo-control adoption without captive R&D investment.
Among Italian manufacturing specialists, CONCETTI S.P.A exemplifies the Mediterranean rapid-response service archetype, while Industria Macchine Automatiche SpA occupies a position within the engineering-intensive tier serving regulated food and chemical accounts. Premier Tech Ltd. represents the North American service-integrated model, leveraging multi-year maintenance agreements to extend lifecycle revenue capture beyond initial equipment procurement. These three entities illustrate how vendor economics shift from pure equipment sales toward recurring service contract structures.
| Leading Market Players |
|---|
| Premier Tech Ltd. |
| CONCETTI S.P.A |
| PAYPER S.A |
| Industria Macchine Automatiche SpA |
| Bossar Packaging S.A |
| Tinsley Equipment Company LLC |
| Choice Bagging Equipment |
| Votech |
| PLÜMAT |
| Others |
Value Network & Pricing Analysis
Servo-driven net-weigh technology adoption simultaneously compresses production cost curves and concentrates supply among German and Italian engineering houses with captive drive programming expertise. This shift elevates price premiums for closed-loop electronic configurations while eroding margins on legacy pneumatic alternatives.
Pricing Analysis
Capacity additions in China and Turkey are reshaping price floors for Grade 304 and 316 stainless-steel contact surfaces, the dominant variable cost component. Three-tier pricing structure across premium servo-electric, standard pneumatic, and economy mechanical tiers separates vendors by fill accuracy certification and after-sales bundling. Cost compression in mid-tier pneumatic systems is intensifying because Turkish mill pricing volatility forces margin absorption at Italian and Spanish fabricators. Regional fertilizer blenders in Brazil exhibit highest price sensitivity; Swiss specialty chemical processors demonstrate least.
Supply Chain Analysis
Dual-sourcing requirements from multinational food and chemical processors mandate multi-supplier qualification for servo drives and load cell assemblies, fragmenting procurement leverage. Component fabrication concentrates in Germany, Italy, and China, with steel sourcing anchored in Turkish and Chinese mills. Machine builders draw from Siemens, Rockwell, and Schneider Electric for control systems, creating single-source vulnerability for mid-tier European fabricators. Tariff exposure on Chinese steel imports compresses vendor margins. Distribution runs through engineering-intensive OEMs with regional service subsidiaries and third-party industrial contractors with cross-brand certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-electric technology penetration creates margin-expansion headroom as buyers absorb premiums for 0.1% fill accuracy and compressed air elimination. After-sales service unbundling shifts value capture toward lifecycle contracts.
For Market Incumbents: Anchor premium positioning through regionalized fabrication footprints that satisfy EU CSRD carbon-accounting traceability requirements. Defend against third-party service contractors by embedding predictive diagnostics into standard equipment configurations. Vertical integration into servo commissioning training programs addresses technician scarcity that delays installation acceptance. For New Entrants and Emerging Players: Mid-scale spice processors in Gujarat and Maharashtra represent an underserved buyer archetype requiring 316-grade stainless construction without full line integration complexity. White-space exists in seasonal fertilizer distribution networks seeking rapid format changeover capability. Pursue software-integrated remote diagnostics as primary go-to-market wedge against established OEM service packages. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Italian fabricators with Mediterranean service density but limited servo-control R&D. Long-term viability centers on vendors with validated REACH SVHC documentation chains and software-defined control architectures. Watch technician training program expansion rates as inflection indicator for installation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Programming | German engineering houses reduce PLC supplier dependence and accelerate commissioning timelines. |
| Regional Fabrication Footprint Expansion | Proximity to Indian food processing clusters in Gujarat shortens delivery cycles and satisfies FSSAI audit requirements. |
| Predictive Maintenance Platform Launch | Edge-computing integration with vibration sensors extends vendor revenue streams beyond equipment sale. |
| REACH SVHC Documentation Investment | Validated supplier chains secure approved vendor status with ECHA-registrant chemical processors. |
| Cross-Brand Technician Certification Program | Third-party industrial contractors capture maintenance agreements from OEM-captive packages in US Gulf Coast plants. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at flour mills, cement plants, and specialty chemical processors grounded qualitative findings. Secondary validation drew from ECHA REACH registration databases, EU Machinery Directive technical files, SEC 10-K disclosures from listed automation vendors, and customs trade data for stainless-steel mill imports. Bottom-up equipment shipment tallies triangulated against top-down end-use industry capital expenditure patterns.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between technology substitution rates, regulatory compliance deadlines, and regional food processing investment cycles. Segmentation dimensions included product type, control architecture, end-use industry, filling method, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating REACH SVHC documentation phase-in schedules and FSSAI hygienic design mandate enforcement timelines. Servo drive cost curves and stainless-steel price volatility informed variable cost assumptions.
Underlying measurement precision varies by segment; electronic technology and food industry applications carry tighter precision than mechanical configurations and construction end-uses due to disclosure density. Forecasts reflect documented assumptions regarding ECHA enforcement intensity and Indian food safety regulator inspection frequency. Deviation in EU CSRD carbon-accounting auditor stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Global Paper Napkin Making Machine Market