
 Twist Tie Machines Market | 2026-2036
Twist Tie Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Tie Machines Market Analytics
Automation in twist tie machine design is narrowing the performance gap between semi-automatic and fully automatic systems. Kunshan Yuanhan Electronic Equipment leverages its Jiangsu manufacturing base to serve export markets across Southeast Asia. Tach-It sustains North American demand through specialized tabletop and portable units for low-volume operations. Plas-Ties, Co. anchors the supply of complementary tying materials, extending its influence beyond equipment into consumables.
Twist tie machines are electromechanical devices that twist, cut, and secure flexible binding materials around bag necks or bundled items, typically operating at speeds of 30-120 ties per minute depending on configuration. These systems serve primary industrial purposes in food packaging closure, agricultural produce bundling, and wire harness management. Fully automatic units command the largest installed base among machine types due to labor-cost pressures in high-volume food processing. Food packaging applications generate the dominant share of demand, while agricultural product handling represents the fastest-expanding application segment as fresh-produce distribution chains mechanize post-harvest operations. Plastic and composite materials lead material preferences for moisture-sensitive applications, though metal ties retain share in heavy-duty electrical wiring uses.
FDA regulations governing food-contact surfaces and OSHA machine-guarding standards shape equipment specifications for US-installed systems, while China's SAMR enforces GB machinery safety and food-contact compliance for domestic production and export certification. The EU Machinery Directive and REACH chemical restrictions further constrain material choices for equipment sold into European markets. Stakeholders must monitor evolving food-safety audit requirements and energy-efficiency mandates as these frameworks tighten compliance thresholds for new machine deployments.
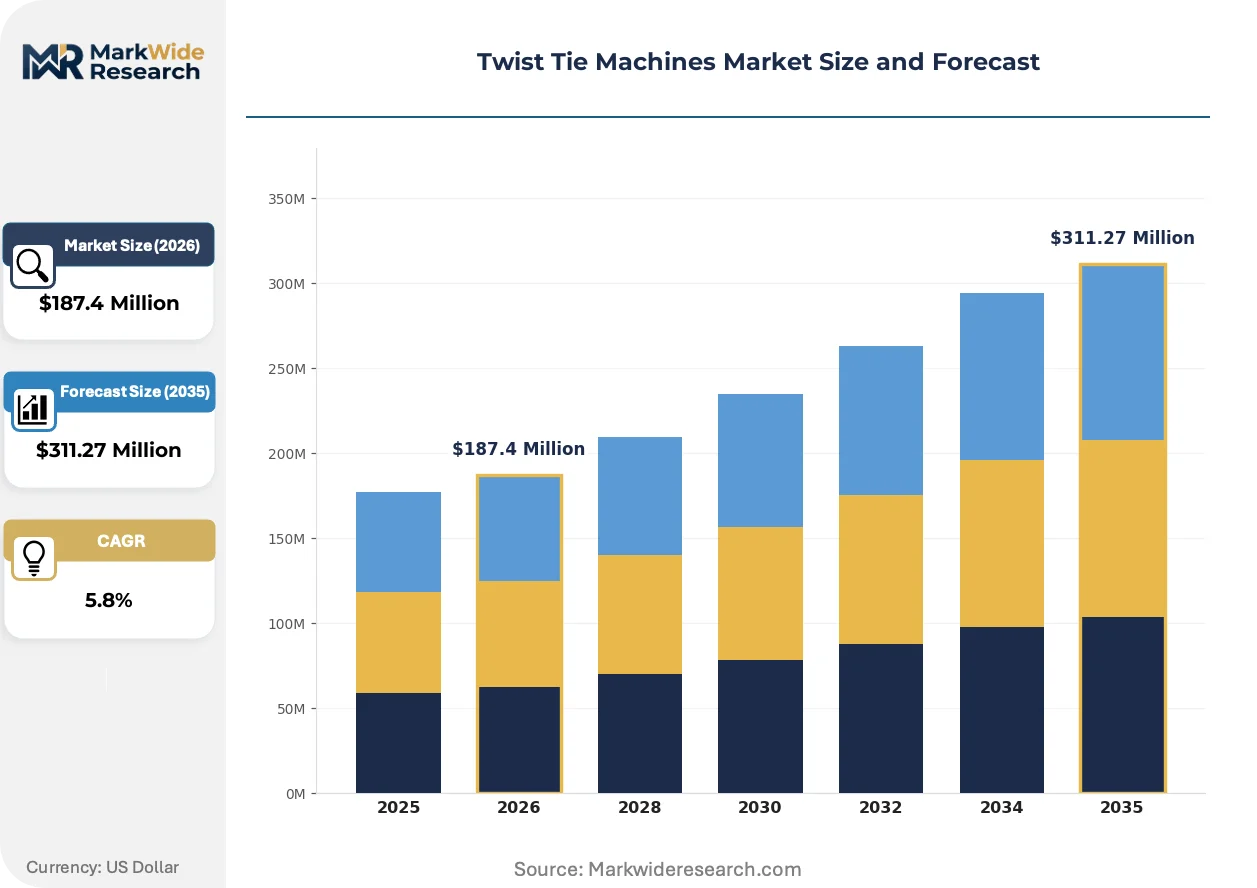
Market Dynamics
Food processors in Jiangsu province are consolidating procurement around certified fully automatic systems as China's SAMR tightens GB machinery safety enforcement and export buyers demand traceable compliance documentation.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of GB machinery safety and food-contact material rules compels domestic food processors to replace legacy equipment with certified twist tie systems.
- Fresh Produce Mechanization:Agricultural cooperatives in Southeast Asia are automating post-harvest bundling operations to reduce labor dependency and improve throughput consistency.
- OSHA Machine Guarding:US food packaging facilities face inspection-driven upgrades to interlocked guarding and emergency stop systems on bag-closing lines.
Market Restraints
- Stainless Steel Price Volatility:Food-grade 304 stainless steel input costs fluctuate with nickel futures, compressing margin on hygienic machine builds.
- Jiangsu Supply Concentration:Machine-building clusters around Kunshan and Zhenjiang create single-province dependency for export-capable equipment.
- Adhesive Tape Substitution:Pressure-sensitive bag-sealing tapes compete for low-speed bakery applications where moisture resistance is secondary.
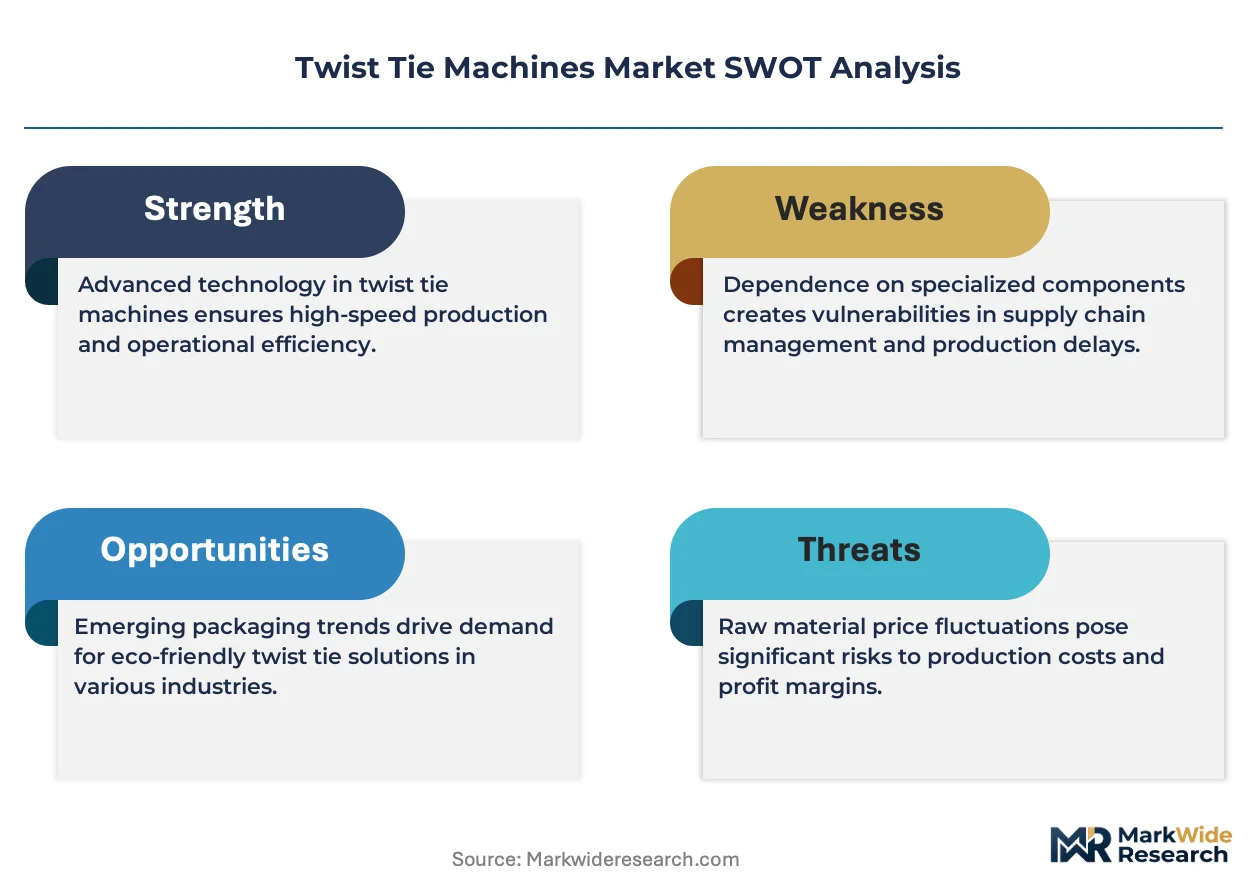
Strategic Opportunities
- India Food Processing:FSSAI licensing expansion and cold chain investment under PLI schemes create first-mover potential in untapped regional markets.
- Biodegradable Tie Materials:EU REACH chemical restrictions and single-use plastic directives drive equipment adaptation for cellulose-based binding strips.
- Remote Diagnostics Integration:IoT-enabled predictive maintenance contracts allow OEMs to capture recurring revenue from distributed installed bases.
Industry Challenges
- Mechatronics Talent Scarcity:Programming servo-driven twisting mechanisms requires hybrid electrical-mechanical skills that vocational pipelines undersupply.
- FDA Validation Timelines:Food-contact surface certification for new polymer tie materials extends product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Tie Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Manual, Semi-Automatic, Fully Automatic, Electric Application: Food Packaging, Agricultural Products, Textile, Electrical Wiring End User: Manufacturers, Distributors, Retailers, Food Processors Material: Plastic, Metal, Paper, Composite |
| Companies Covered | Kunshan Yuanhan Electronic Equipment, Tach-It, Chengdu Huitong Packing Machine, Hughes Enterprises, Paxiom, International Plastics Inc, Plas-Ties, Co., Zhenjiang Hongda Commodity, IPS Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Tie Machines Market Evolving Landscape
Electromechanical control architectures are converging with food-safety traceability systems, compressing the gap between operational efficiency and regulatory audit readiness across packaging lines.
Vision-guided tie positioning systems are digitizing quality assurance in high-speed bakery applications. Mid-size processors in Germany and the Netherlands are retrofitting existing lines with camera-based verification modules. This convergence is digitizing defect detection from post-batch sampling to real-time rejection, reducing material waste and audit failure risk.
REACH chemical restrictions on phthalate plasticizers are forcing material transitions in tie coatings sold into European markets. Equipment manufacturers must validate compatibility with bio-based alternatives or risk market exclusion. Bakery and confectionery packaging lines in France and Italy are prioritizing suppliers with pre-certified REACH-compliant material portfolios.
Service unbundling is fragmenting traditional equipment-plus-consumables bundling. Large food processors in the US are separating machine procurement from tie material supply, forcing OEMs to compete on pure equipment performance metrics. This disintermediation is most pronounced among private-label snack manufacturers seeking multi-source flexibility for commodity inputs.
Twist Tie Machines Market Segmentation
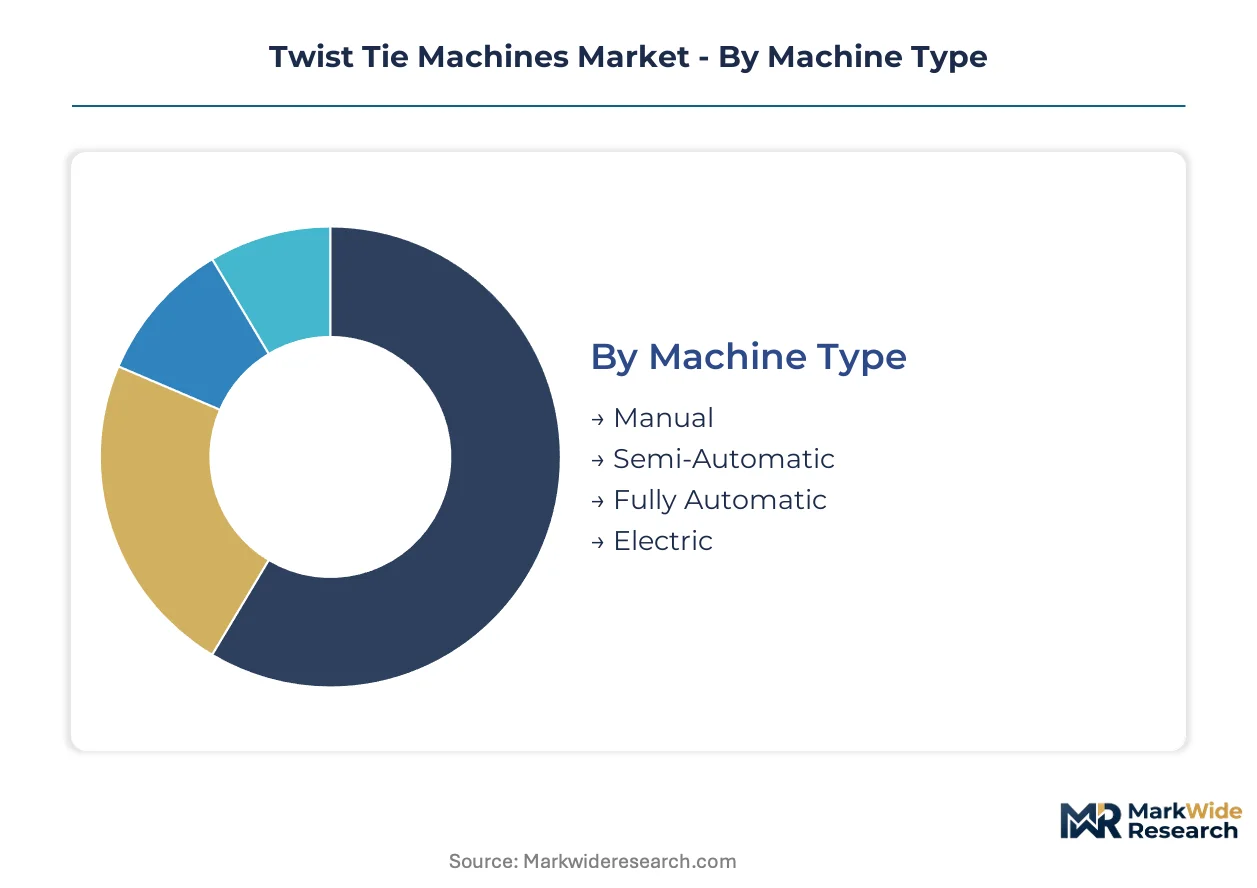
Segmentation in twist tie machines reflects divergent automation thresholds across end-use industries. Food processors prioritize throughput velocity while agricultural cooperatives balance capital constraints against seasonal volume spikes.
Machine Type:
Mature electromechanical platforms dominate installed bases, yet emerging servo-driven architectures are compressing price-performance ratios.
- Fully Automatic:Servo-controlled twisting heads achieve 80-120 ties per minute with programmable tension settings. Jiangsu province food processors deploy these systems to meet SAMR GB machinery safety certification for export-bound production lines.
- Semi-Automatic:Operator-fed designs bridge manual and automated workflows at 30-60 ties per minute. Southeast Asian agricultural cooperatives favor this tier for post-harvest bundling operations where labor costs remain below full automation thresholds.
- Manual:Hand-cranked or foot-pedal units serve micro-bakeries and specialty food producers with volumes below 500 bags daily.
- Electric:Motor-assisted tabletop systems target low-volume retailers requiring consistent twist quality without pneumatic infrastructure.
Fully Automatic handles the majority of throughput; Semi-Automatic is expanding most quickly among capital-constrained agricultural operators.
Application:
Application demand clusters around moisture-sensitive packaging requirements versus mechanical durability specifications.
- Food Packaging:Bakery and confectionery lines drive specifications for stainless steel contact surfaces and FDA-compliant polymer ties. German and Dutch mid-size processors retrofit vision-guided positioning modules to existing twist tie stations.
- Agricultural Products:Post-harvest bundling of fresh produce demands weather-resistant tying materials and portable machine configurations. Vietnamese and Thai cooperatives mechanize banana and asparagus packing to reduce harvest-to-cold-chain time.
- Textile:Fabric roll bundling and garment bag closure utilize lighter-gauge tying mechanisms with adjustable loop diameters.
- Electrical Wiring:Heavy-duty metal ties secure cable harnesses in automotive and industrial equipment manufacturing, prioritizing tensile strength over speed.
Food Packaging commands the dominant equipment spend; Agricultural Products shows the steepest expansion trajectory as fresh-produce distribution chains mechanize.
End User:
Procurement authority concentrates with volume-scale operators, though distributor networks shape regional equipment availability.
- Food Processors:Integrated bakery and snack manufacturers specify fully automatic lines with traceability documentation for retailer audit compliance. Private-label producers unbundle equipment from consumable supply to enable multi-source flexibility.
- Manufacturers:OEMs and tier suppliers deploy twist tie systems for in-house packaging of components and subassemblies, often integrating with existing conveyor infrastructure.
- Distributors:Agricultural supply cooperatives purchase semi-automatic fleets for seasonal rental to member farms during harvest windows.
- Retailers:In-store bakery operations and produce departments utilize compact electric units for same-day packaging of perishable goods.
Food Processors drive premium equipment specifications; Distributors are gaining procurement influence through cooperative purchasing structures.
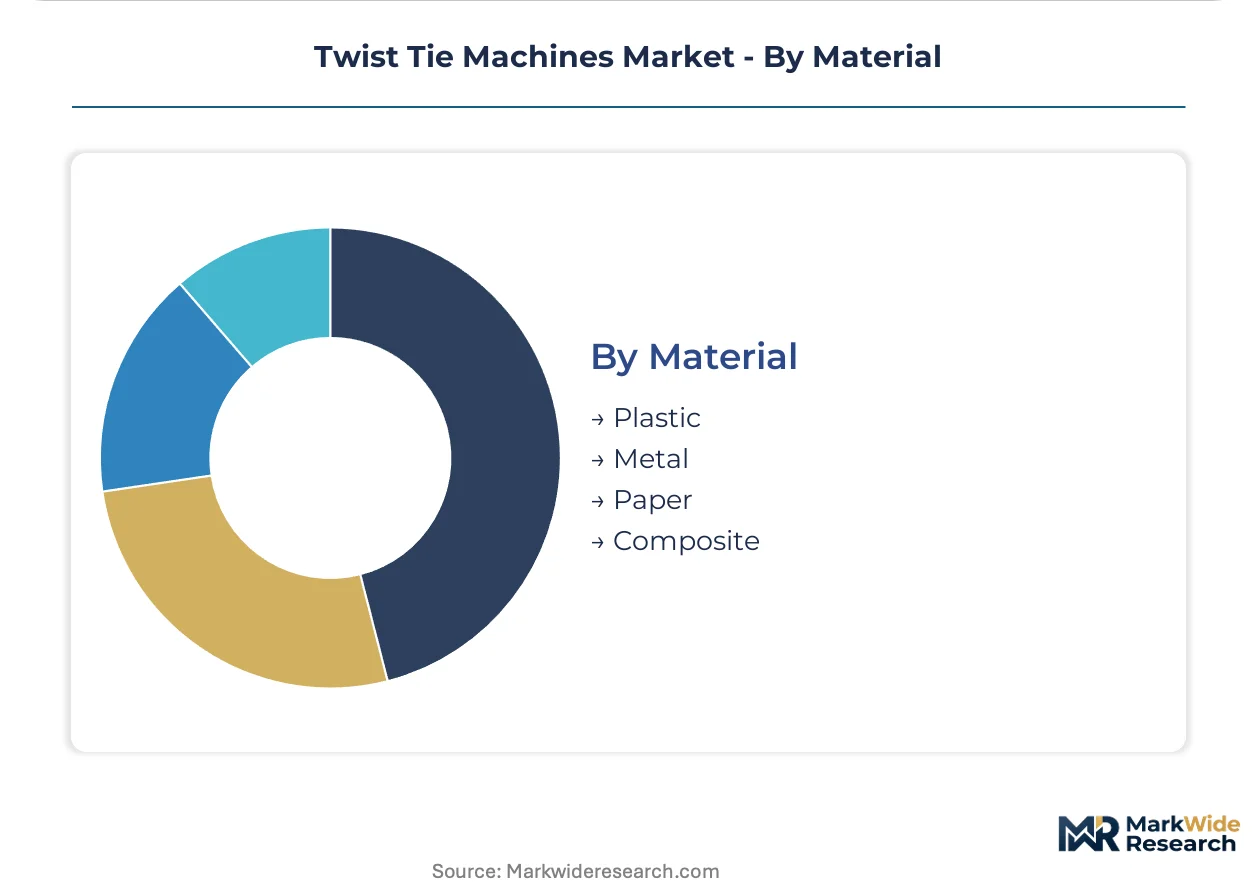
Material:
Material selection hinges on regulatory compliance timelines and end-of-life disposal requirements.
- Plastic:Polyethylene and polypropylene ties dominate moisture-barrier applications in frozen food packaging. REACH phthalate restrictions are forcing European bakery lines to validate bio-based coating alternatives.
- Metal:Galvanized steel and aluminum ties retain electrical wiring and heavy-duty agricultural bundling applications where tensile load exceeds polymer limits.
- Paper:Kraft and cellulose-based strips serve compostable packaging mandates in EU single-use plastic directive jurisdictions.
- Composite:Metal-core plastic-coated hybrids balance flexibility with strength for premium gift and specialty food presentations.
Plastic ties handle the majority of unit volume; Paper materials are climbing the fastest on regulatory-driven substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province exports fully automatic twist tie systems to Southeast Asian food processors, while German mid-size bakeries retrofit vision-guided modules to existing lines.
China
Food processors in Kunshan and Zhenjiang consolidate procurement around GB-certified equipment as SAMR tightens machinery safety enforcement. Export buyers demand traceable compliance documentation for bakery and confectionery lines. The Yangtze River Delta cluster anchors machine-building capacity serving Vietnam and Thailand.
Germany
Mid-size processors retrofit vision-guided tie positioning systems to compress defect detection from post-batch sampling to real-time rejection. REACH chemical restrictions on phthalate plasticizers force validation of bio-based tie coatings. The Baden-Württemberg region concentrates equipment retrofitting activity for French and Italian bakery supply chains.
United States
Private-label snack manufacturers unbundle machine procurement from tie material supply to enable multi-source flexibility. OSHA inspection-driven upgrades compel interlocked guarding and emergency stop installations on bag-closing lines. Wisconsin and Illinois food packaging facilities dominate retrofit demand for compliant systems.
Vietnam
Agricultural cooperatives mechanize banana and asparagus post-harvest bundling to reduce harvest-to-cold-chain time. FDI in cold chain infrastructure accelerates semi-automatic fleet purchases for seasonal volume spikes. The Mekong Delta region concentrates produce packing operations adopting Jiangsu-sourced equipment.
India
FSSAI licensing expansion and PLI scheme investments in food processing create first-mover potential in untapped regional markets. Cold chain infrastructure gaps currently constrain fully automatic deployment. Maharashtra and Gujarat food processors pilot semi-automatic units for snack and bakery applications.
Twist Tie Machines Market Competitive Landscape
On the supply side, the industry is bifurcated between Jiangsu-based export-capable fabricators and regional specialists serving protected domestic markets. Equipment-plus-consumables bundling fragments as large processors separate machine procurement from tie material supply. Two strategic archetypes dominate: stainless steel hygienic-build specialists and portable semi-automatic fabricators for agricultural cooperatives. Capacity expansion in Jiangsu and strategic partnerships for biodegradable material compatibility represent the dominant competitive vectors.
Within the Jiangsu export-capable tier, Kunshan Yuanhan Electronic Equipment and Zhenjiang Hongda Commodity occupy positions anchored to the province's dense machine-building cluster. Tach-It represents the North American specialist archetype, serving low-volume operations through tabletop and portable configurations. These three exemplify the geographic and functional segmentation shaping procurement patterns across food processing and agricultural end uses.
| Leading Market Players |
|---|
| Kunshan Yuanhan Electronic Equipment |
| Tach-It |
| Chengdu Huitong Packing Machine |
| Hughes Enterprises |
| Paxiom |
| International Plastics Inc |
| Plas-Ties, Co. |
| Zhenjiang Hongda Commodity |
| IPS Packaging |
| Others |
Value Network & Pricing Analysis
Overcapacity in Jiangsu province's machine-building cluster is compressing pricing power for export-capable fabricators while driving consolidation toward certified equipment tiers. Food processors exploit this slack by demanding GB-compliant documentation without premium markups, forcing suppliers to absorb certification costs into base pricing.
Pricing Analysis
Servo-driven next-generation systems command 40-60% premiums over electromechanical prior-generation platforms, while legacy pneumatic units trade at distressed clearance levels. Three-tier pricing structure across premium, standard, and economy levels reflects GB certification status, stainless steel grade, and after-sales bundling intensity. Cost compression in standard-tier equipment is intensifying because nickel price volatility squeezes 304 stainless steel input costs. Agricultural cooperatives in Southeast Asia exhibit highest price sensitivity, while integrated North American snack manufacturers prioritize traceability documentation over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Jiangsu fabricators serving Vietnamese and Thai agricultural cooperatives, straining working capital buffers. Production concentrates in China, Germany, and the United States, with component sourcing drawn from Japanese servo motor suppliers and Taiwanese control system vendors. Single-source vulnerability around Jiangsu's machine-building cluster creates geographic concentration risk for export-dependent buyers. Distribution runs through agricultural supply cooperatives in Southeast Asia and integrated food processor procurement departments in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Twist tie machine demand is accelerating as China's SAMR enforcement of GB machinery safety standards forces replacement cycles across export-oriented food processing lines. This regulatory inflection compresses equipment lifecycles and redirects procurement toward certified fabricators.
For Market Incumbents: Entrench position by deepening backward integration into stainless steel fabrication and servo motor assembly within Jiangsu province. Secure GB certification moats ahead of SAMR inspection waves. Channel control through exclusive distributor arrangements in Vietnam and Thailand defends against emerging portable-equipment specialists.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat food processing corridors represent the most penetrable entry point, where FSSAI licensing expansion outpaces domestic equipment supply. Semi-automatic configurations for snack and bakery applications avoid head-to-head competition with Jiangsu's fully automatic dominance. Partner with cold chain infrastructure investors to bundle equipment-procurement with logistics development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-driven equipment tiers as R&D cycles compress and certification timelines extend. Targets with pre-validated REACH-compliant material portfolios and established SAMR documentation workflows offer acquisition premiums. Monitor FDA validation timelines for bio-based tie materials as inflection indicator for equipment refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Pre-Investment | SAMR enforcement timelines reward early-certified equipment portfolios with procurement preference. |
| Biodegradable Tie Material Validation | REACH chemical restrictions force equipment adaptation for cellulose-based binding strips. |
| Remote Diagnostics Integration | IoT-enabled predictive maintenance contracts capture recurring revenue from distributed installed bases. |
| India Market Entry Partnership | FSSAI licensing expansion and PLI scheme investments create first-mover positioning in untapped regional markets. |
| Servo Architecture Migration | Electromechanical platforms face displacement as servo-driven systems compress price-performance ratios. |
Research Methodology
Initial hypotheses were tested against primary input from food processing plant engineers, agricultural cooperative procurement managers, OEM equipment sales directors, and aftermarket service technicians, then refined through secondary validation. Primary fieldwork encompassed Jiangsu province machine-building clusters, Vietnamese Mekong Delta packing operations, and German Baden-Württemberg retrofitting activity. Secondary sources included SAMR GB standards documentation, FDA food-contact surface regulations, REACH chemical restriction filings, and trade flow data from China Customs. Bottom-up equipment shipment tallies were triangulated against top-down food processing capital expenditure estimates.
Demand-supply balance modeling across the projection horizon incorporated machine type segmentation by automation tier, application segmentation by moisture-sensitivity requirements, and material segmentation by regulatory compliance timelines. CAGRs were derived from installed base replacement cycles, greenfield food processing capacity additions, and agricultural mechanization penetration curves. Industry-specific forecast inputs included nickel futures price trajectories affecting stainless steel equipment costs and FSSAI licensing velocity in Indian states.
Practitioners should monitor SAMR inspection enforcement intensity, nickel price volatility, and FDA validation timelines for bio-based materials as early signals for forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market