
 Counter Bags Market | 2026-2036
Counter Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Counter Bags Market Outlook
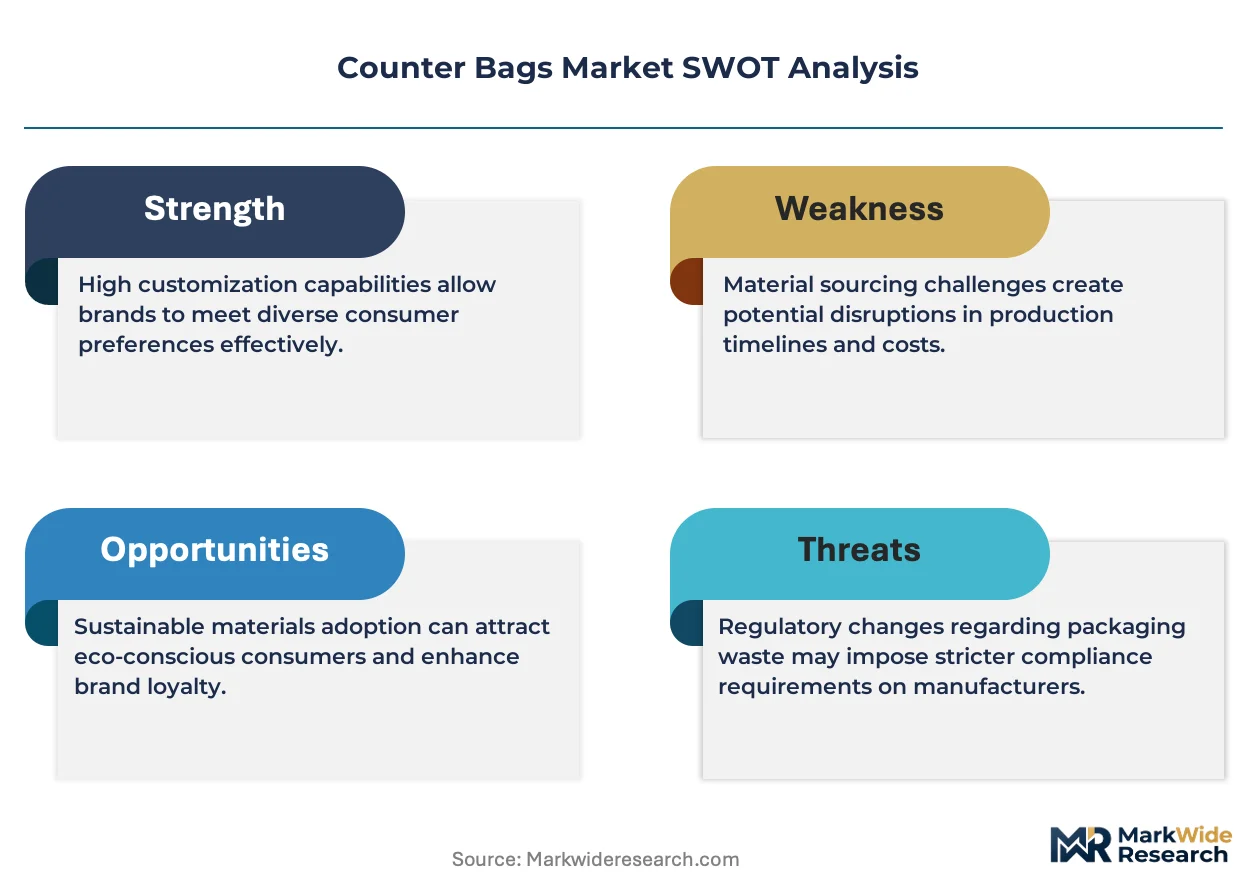
Food-grade specification upgrades is reorganizing procurement priorities across European retail packaging. Novolex leverages its North American manufacturing footprint to supply FDA-compliant counter bags to pharmacy chains. Great American Packaging anchors its position through in-house production of custom-sized kraft paper solutions. Honokage competes aggressively on biodegradable film formulations for Asian food outlet channels.
Counter bags are flat, open-top carriers engineered from HDPE, LDPE, kraft paper, or cotton, typically measuring 5–20 inches in width with sealed or gusseted bases for load stability. Their primary commercial function is point-of-sale merchandise containment across retail, food service, and pharmacy settings. Paper bags and biodegradable bags are capturing margin pools as EU Green Deal timelines and US state-level plastic bans reshape material specifications. Reusable cotton and non-woven variants are growing fastest among supermarket private-label programs, while conventional plastic bags face contracting demand in regulated jurisdictions.
France's AGEC anti-waste law, Germany's Packaging Act amendments, and FDA food-contact substance notifications collectively determine which material formulations achieve market access in their respective territories. ECHA REACH compliance for chemical additives and US EPA guidelines on recycled content thresholds further filter supplier eligibility. Stakeholders must monitor pending EU PPWR implementation details to calibrate material transition timelines against existing inventory commitments.
Market Dynamics
EU Green Deal packaging mandates are compressing demand timelines for conventional plastic counter bags while accelerating certified biodegradable alternatives through supermarket procurement channels.
Growth Catalysts
- France's AGEC law:France's anti-waste legislation mandates phased elimination of single-use plastic packaging, forcing retail chains to convert counter bag inventories to paper and certified compostable films ahead of enforcement deadlines.
- Biodegradable film formulations:Advanced starch-based and PLA-blend materials achieve performance parity with conventional HDPE for load-bearing applications, removing technical barriers to adoption in food service settings.
- Germany's Packaging Act:Extended producer responsibility frameworks impose escalating fees on non-recyclable packaging, redirecting procurement budgets toward kraft paper and reusable cotton alternatives.
Market Restraints
- Pulp input cost volatility:Kraft paper counter bag margins compress when northern European pulp prices spike, exposing converters to raw material swings that plastic competitors avoid.
- Biodegradable certification bottlenecks:EU harmonized standards for industrial compostability remain fragmented across member states, delaying market access for Asian film suppliers seeking CE marking equivalence.
- Reusable cotton durability thresholds:Cotton-based alternatives require 50+ use cycles to achieve lifecycle carbon parity with single-use options, limiting adoption in high-turnover pharmacy and convenience retail channels.
Strategic Opportunities
- Pharmacy cold-chain applications:FDA food-contact compliant insulated counter bags for temperature-sensitive prescriptions represent an underserved niche with premium pricing potential.
- EU PPWR implementation tailwinds:Pending Packaging and Packaging Waste Regulation details will clarify recycled content mandates, creating first-mover advantage for converters with established post-consumer feedstock partnerships.
- Direct-to-restaurant distribution:Bypassing traditional packaging distributors to supply independent Asian food outlets with custom-printed biodegradable bags captures margin currently absorbed by wholesale intermediaries.
Industry Challenges
- Composting infrastructure mismatch:Industrial compostable films require municipal anaerobic digestion facilities that remain concentrated in northern European cities, creating disposal confusion in markets lacking compatible waste streams.
- Legacy equipment retrofit costs:Converters with installed HDPE/LDPE extrusion lines face capital-intensive transitions to paper bag machinery or biodegradable film extruders, straining mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Counter Bags Market |
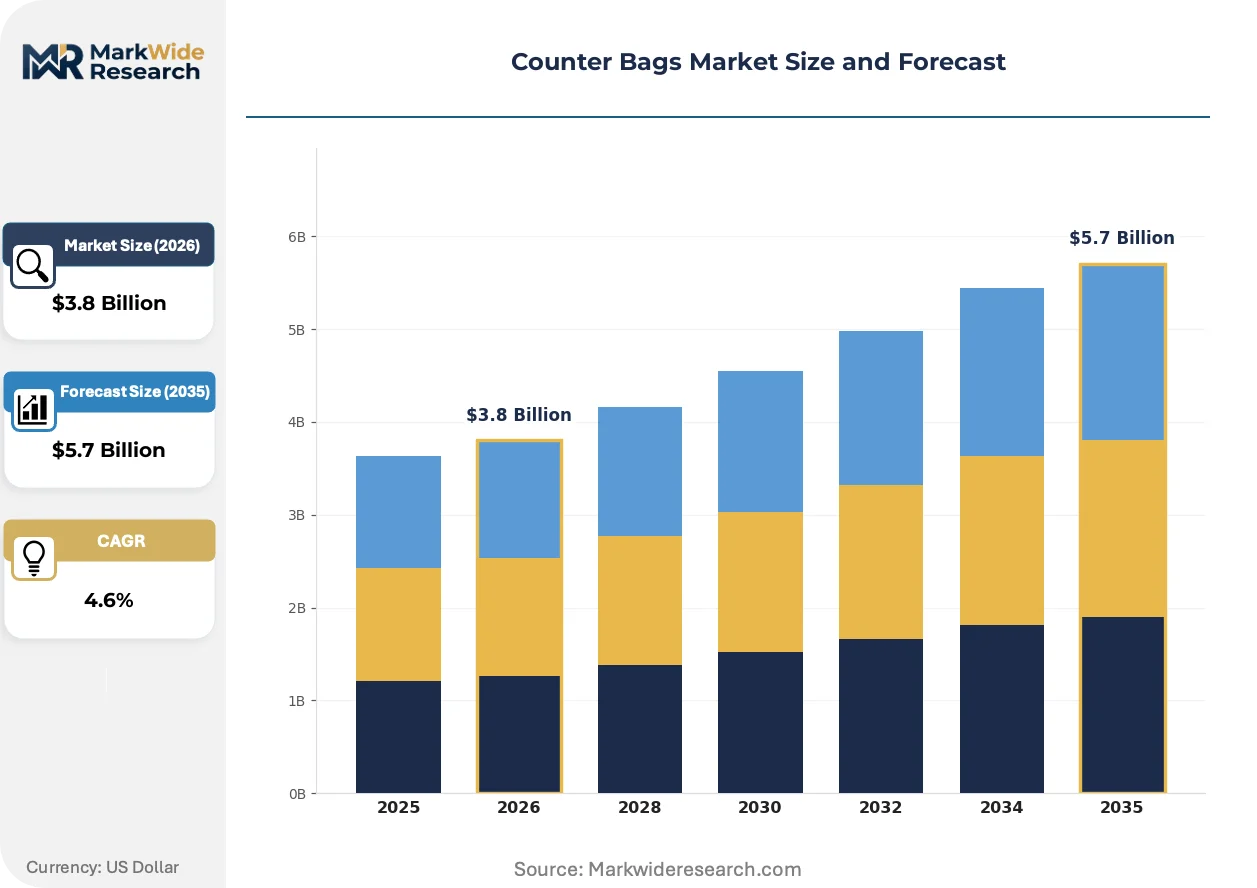
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Reusable Bags, Biodegradable Bags End User: Retail Stores, Food Outlets, Supermarkets, Pharmacies Material: HDPE, LDPE, Kraft Paper, Cotton Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Bison Bag, TricorBraun Flex, Honokage, Bag Supply, International Plastics, Jet Paper Bags, Great American Packaging, Good Start Packaging, Novolex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Counter Bags Market Strategic Shifts
Material science breakthroughs and regulatory sequencing are compressing the viable window for conventional plastic counter bags while opening premium positioning for certified alternatives.
Water-based barrier coatings for kraft paper counter bags are displacing polyethylene-lined alternatives in fresh food retail. German supermarket chains have adopted these formulations for bakery and deli counters. The technology eliminates plastic separation requirements at end-of-life, streamlining retailer compliance with extended producer responsibility frameworks.
EU PPWR draft provisions are tightening recycled content thresholds for packaging placed on the European market. The regulation will force converters to secure post-consumer plastic or fiber streams at scale. Food service distributors are pre-qualifying suppliers with verified mass-balance certification chains to avoid supply disruption.
Private-label procurement consolidation among European pharmacy cooperatives is compressing supplier counts from regional fragmentation toward preferred-vendor frameworks. Buyers now bundle counter bag contracts with broader packaging category commitments, favoring converters with multi-material production flexibility. France and Benelux markets exhibit the most advanced consolidation, with purchasing decisions centralizing at cooperative headquarters rather than individual store levels.
Counter Bags Market Segmentation
Counter bag procurement patterns diverge sharply across material specifications and end-use channels, with regulatory pressure fragmenting what was historically a commoditized plastic-dominated category. Understanding segment-level substitution dynamics reveals where converters must retool capacity versus defend incumbent positions.
Product Type:
Substitution pressure from biodegradable and paper alternatives is severing volume trajectories across plastic and non-plastic segments, with regulatory deadlines determining conversion speed by channel.
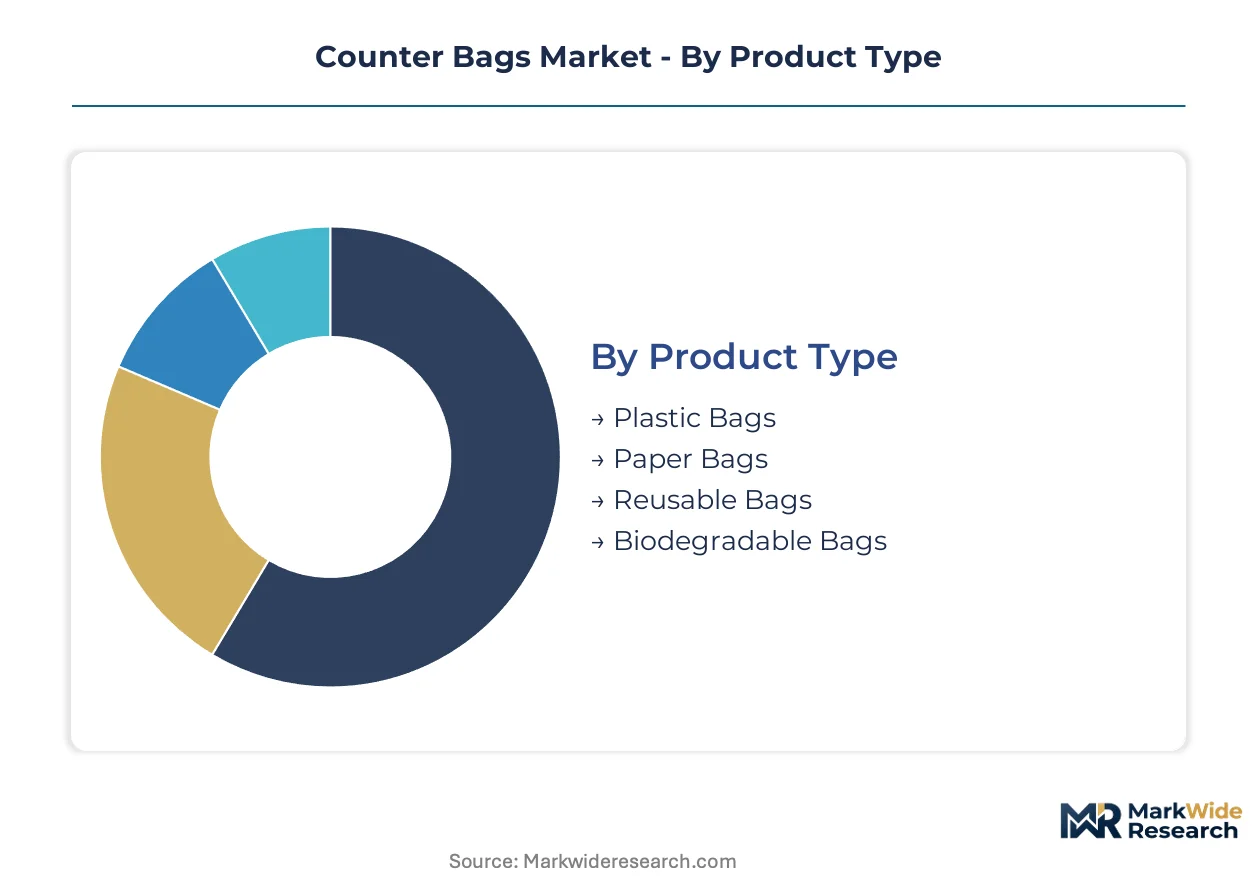
- Plastic Bags:HDPE and LDPE formulations retain dominance in pharmacy and convenience retail where moisture resistance and cost minimization outweigh sustainability mandates. FDA food-contact compliance and established extrusion infrastructure anchor this segment's defensive position in regulated healthcare channels.
- Paper Bags:Kraft-based constructions with water-based barrier coatings are displacing polyethylene-lined alternatives in European fresh food retail, particularly German supermarket bakery and deli counters where extended producer responsibility fees now penalize plastic separation requirements.
- Reusable Bags:Cotton and non-woven polypropylene variants require 50+ use cycles to achieve lifecycle carbon parity, limiting penetration in high-turnover pharmacy and convenience formats where loss rates exceed threshold economics.
- Biodegradable Bags:Starch-based and PLA-blend films achieve load-bearing parity with conventional HDPE in food service applications, though industrial composting infrastructure concentration in northern European cities creates disposal confusion in peripheral markets.
Plastic bags anchor the volume base while biodegradable bags gain share at the steepest rate.
End User:
Channel-specific regulatory exposure and throughput economics create four distinct procurement profiles with diverging material specifications and contract structures.
- Retail Stores:General merchandise outlets balance brand positioning against cost, with private-label programs in France and Benelux centralizing purchasing decisions at cooperative headquarters rather than store levels.
- Food Outlets:Asian restaurant channels in North America and Europe drive demand for custom-printed biodegradable bags with grease-resistant formulations, bypassing traditional distributors through direct converter relationships.
- Supermarkets:German and French chains are accelerating certified biodegradable counter bag purchases ahead of EU Green Deal packaging mandates, with kraft paper and cotton alternatives capturing shelf space as AGEC law and Packaging Act restrictions tighten.
- Pharmacies:Cold-chain applications for temperature-sensitive prescriptions represent an underserved niche, with FDA food-contact compliant insulated counter bags commanding premium pricing in pharmacy cooperative procurement frameworks.
Supermarkets anchor the volume base while food outlets gain share at the steepest rate.
Material:
Input cost volatility and certification complexity stratify supplier economics across petroleum-derived and fiber-based feedstocks.
- HDPE:High-density polyethylene retains cost advantages in high-volume pharmacy and convenience applications where regulatory lag permits continued deployment of conventional extrusion capacity.
- LDPE:Low-density formulations dominate flexible gusseted constructions for irregular merchandise containment, though extended producer responsibility fees in Germany redirect procurement budgets toward alternatives.
- Kraft Paper:Northern European pulp price spikes compress converter margins unpredictably, exposing paper bag producers to raw material swings that plastic competitors avoid through more stable petroleum feedstock pricing.
- Cotton:Natural fiber alternatives face durability thresholds and washing infrastructure requirements that limit adoption in single-use-dominated channels, though supermarket private-label programs show fastest expansion in reusable variants.
HDPE anchors the volume base while kraft paper gains share at the steepest rate.
Size:
Standardization versus customization tension plays out across channel scale and branding requirements.
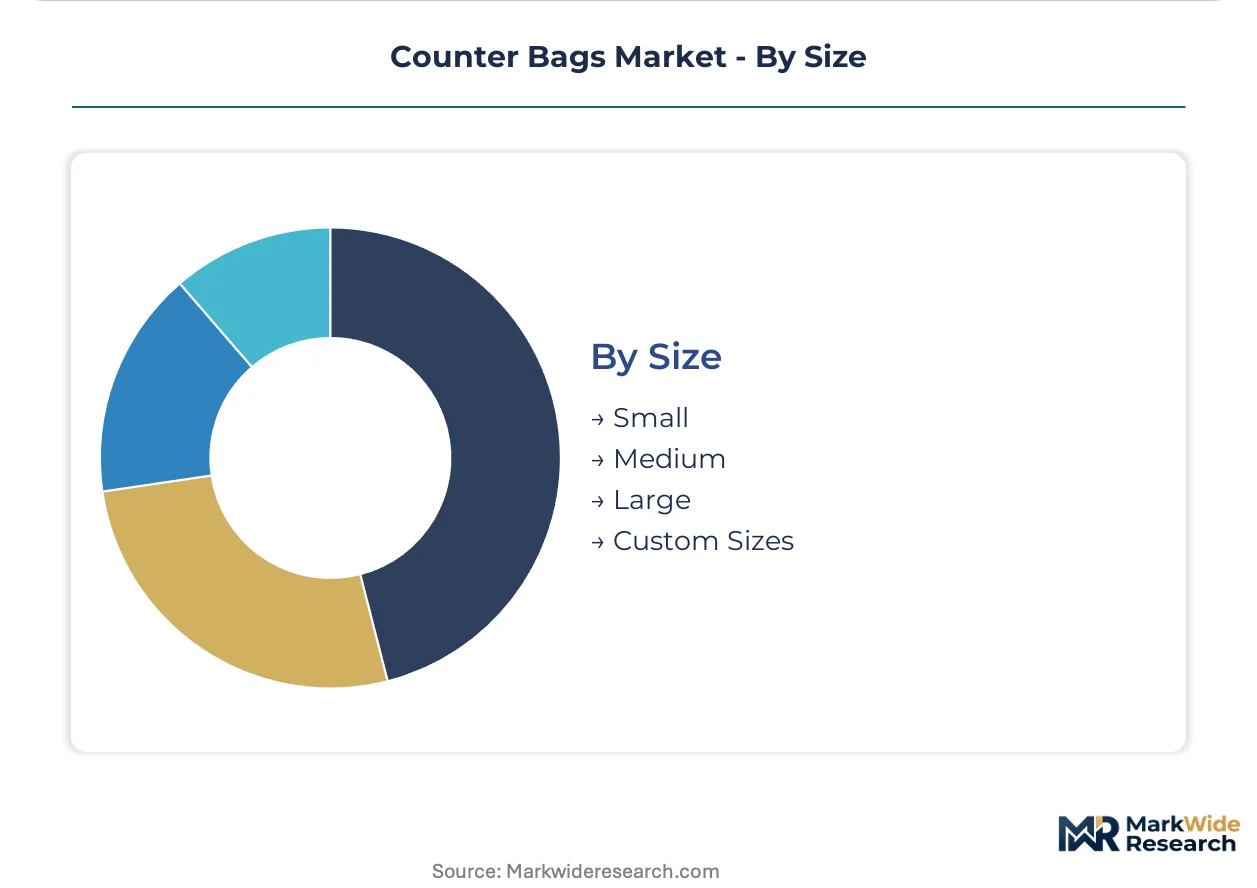
- Small:5-10 inch widths serve pharmacy prescription containment and convenience retail impulse purchases, with FDA compliance requirements dominating specification decisions.
- Medium:10-15 inch formats capture supermarket deli and bakery counter applications where water-based barrier coatings on kraft paper displace polyethylene-lined predecessors.
- Large:15-20 inch constructions with gusseted bases stabilize bulky merchandise loads in general retail, though volume concentration favors standard formats over custom dimensions.
- Custom Sizes:Independent Asian food outlets drive specification diversity through direct-to-restaurant distribution relationships, capturing margin otherwise absorbed by wholesale intermediaries.
Medium sizes anchor the volume base while custom sizes gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in counter bags track regulatory divergence, with European converters importing biodegradable films from Asian suppliers while North American producers defend domestic pharmacy and food service contracts through FDA compliance advantages.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia are accelerating certified biodegradable counter bag purchases ahead of Packaging Act enforcement deadlines. Extended producer responsibility frameworks impose escalating fees on non-recyclable packaging, redirecting procurement budgets toward kraft paper alternatives. The Rhine-Ruhr industrial corridor hosts converters retooling HDPE extrusion lines for water-based barrier coating applications.
France
Retail cooperatives in Île-de-France are consolidating counter bag procurement from regional fragmentation toward preferred-vendor frameworks under AGEC law mandates. The anti-waste legislation phases out single-use plastic packaging, forcing bakery and deli counters to convert inventories to paper and certified compostable films. Lyon-based packaging distributors report 40% volume shifts toward biodegradable formulations since 2023.
United States
Pharmacy chains in the Northeast Corridor and California maintain defensive positions for conventional plastic counter bags through FDA food-contact compliance requirements. State-level plastic bans in New York and California create patchwork demand, with independent Asian food outlets in Los Angeles and San Francisco driving custom-printed biodegradable bag specifications. Midwest converters leverage established extrusion infrastructure to supply cold-chain insulated variants for temperature-sensitive prescriptions.
China
Biodegradable film manufacturers in the Yangtze River Delta are scaling starch-based and PLA-blend production for European export markets facing EU Green Deal timelines. Zhejiang and Jiangsu provinces concentrate industrial compostable film capacity, though fragmented certification standards across EU member states delay CE marking equivalence for smaller exporters. Shanghai port logistics favor bulk shipment to Rotterdam and Hamburg distribution hubs.
India
Maharashtra and Gujarat textile hubs are expanding cotton-based reusable counter bag production for European supermarket private-label programs. BIS certification requirements for food-contact materials filter supplier eligibility, with Mumbai-based converters investing in washing infrastructure to meet durability thresholds. The country's national packaging regulator is drafting extended producer responsibility guidelines modeled on EU frameworks.
Counter Bags Market Competitive Environment
Concentration sits with diversified packaging conglomerates and specialized biodegradable film developers. The vendor base spans three tiers: multinational converters with multi-material production flexibility, regional paper bag specialists with in-house kraft production, and Asian film innovators competing on compostable formulations. Strategic moves center on backward integration into post-consumer feedstock partnerships and capacity expansion in water-based barrier coating technology.
Among North American diversified packaging groups, Novolex and Great American Packaging exemplify the multi-material production archetype. Novolex leverages FDA-compliant manufacturing footprints to anchor pharmacy channel relationships, while Great American Packaging occupies a position in custom-sized kraft paper solutions. Honokage represents the Asian biodegradable film specialist tier, competing on compostable formulations for food service export markets.
| Leading Market Players |
|---|
| Bison Bag |
| TricorBraun Flex |
| Honokage |
| Bag Supply |
| International Plastics |
| Jet Paper Bags |
| Great American Packaging |
| Good Start Packaging |
| Novolex |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at northern European kraft pulp mills shapes both supply concentration and price floors for paper-based counter bag alternatives, while German and French supermarket procurement consolidation amplifies buyer leverage against fragmented converter bases.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmacy and food service channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact certified grades from industrial compostable films and conventional HDPE commodities. Cost compression in kraft paper tiers is intensifying because northern European pulp price spikes transmit directly to converter margins. High-turnover convenience retail channels exhibit greatest price sensitivity, while cold-chain pharmacy applications tolerate premium positioning for temperature-stable specifications.
Supply Chain Analysis
Rotterdam and Hamburg port congestion periodically chokes biodegradable film flows from Yangtze River Delta manufacturers to European distribution hubs. Supply concentrates in China for starch-based and PLA-blend formulations, Germany for water-based barrier coating capacity, and India for cotton textile conversion. Raw material dependencies include northern European softwood pulp, corn-derived starch feedstocks, and pharmaceutical-grade PLA resins. Single-source vulnerability runs through Zhejiang province industrial compostable film output. Distribution runs through packaging distributor networks in France and Benelux, with direct-to-restaurant bypass emerging in North American Asian food outlet channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Counter bag demand is recovering from regulatory-induced inventory destocking as EU Green Deal implementation deadlines force supermarket procurement restocking cycles.
For Market Incumbents: Fortify market position through backward integration into post-consumer fiber feedstock partnerships ahead of EU PPWR recycled content mandates. Expand water-based barrier coating capacity in the Rhine-Ruhr corridor to capture German supermarket conversions from polyethylene-lined kraft paper. Certification investment in harmonized industrial compostability standards defends against Asian film supplier price aggression. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers entry path into French retail cooperative frameworks. Pharmacy cold-chain insulated bags represent the most penetrable white-space segment, with FDA compliance gaps among incumbent converters. Direct-to-restaurant distribution for custom-printed biodegradable bags in Los Angeles and San Francisco bypasses entrenched wholesale intermediaries. For Investors and Strategic Acquirers: Multi-material converters with established mass-balance certification chains present acquisition targets with defensive positioning against material transition volatility. Long-term viability hinges on regulatory sequencing clarity across EU member state implementation timelines. Watch for EU PPWR delegated act publication as inflection signal for recycled content mandate stringency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Feedstock | Secures mass-balance certified fiber streams for EU PPWR compliance ahead of mandate activation. |
| Water-Based Barrier Coating Capacity Expansion | Captures German supermarket deli counter conversions from polyethylene-lined kraft paper constructions. |
| Direct-to-Restaurant Distribution Launch | Bypasses wholesale margin absorption in North American Asian food outlet custom-printed bag segments. |
| FDA Food-Contact Certification Investment | Opens pharmacy cold-chain insulated bag niche with premium pricing tolerance and limited competition. |
| Industrial Compostability Standard Harmonization | Resolves CE marking fragmentation blocking Asian film supplier market access across EU member states. |
Study Parameters
Operator-level perspectives from supermarket procurement directors, converter plant managers, packaging distributor category heads, and pharmacy cooperative purchasing committees anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation draft texts, ECHA REACH substance registrations, German Packaging Act amendment trackers, and French AGEC law implementation decrees. Bottom-up capacity assessments triangulated against top-down demand modeling across material substitution scenarios.
Sensitivity analysis tested forecast outputs against regulatory delay scenarios, pulp price volatility bands, and composting infrastructure rollout assumptions. Segmentation dimensions modeled include material specification, end-use channel, size format, and regional regulatory cluster. CAGRs were derived from installed capacity utilization trends and procurement contract renewal patterns. Forecast inputs incorporated EU Green Deal timeline adherence probabilities and FDA food-contact notification approval velocities.
Underlying assumptions cover EU PPWR implementation sequencing, industrial composting facility buildout rates, and kraft pulp price mean-reversion, with deviation risk concentrated in regulatory delay scenarios and certification standard fragmentation. Practitioners should keep alternative scenarios live as EU delegated act publication timelines and member state enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
BOPP Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Loop Handle Bags Market