
 Binding & Lamination Machines Market | 2026-2036
Binding & Lamination Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Binding & Lamination Machines Market Insights
ISO 9001 quality management certification is unwinding the competitive landscape for mid-tier equipment suppliers seeking entry into institutional procurement channels. BOBST Group leverages its Swiss manufacturing heritage to dominate high-speed rotary die-cutting and laminating lines for packaging converters. FRIMO Group anchors its position through specialized polyurethane processing machinery that integrates lamination stages for automotive interior applications. Nordson Corporation extends its adhesive dispensing technology into binding systems, controlling critical subsystems that OEMs specify for hot-melt perfect binding operations.
Binding and lamination machines encompass mechanical systems that apply protective films or secure printed sheets through thermal fusion, pressure adhesion, or ultraviolet curing, typically operating at temperatures between 100°C and 160°C for thermal lamination and pressures from 50 to 300 psi for binding applications, serving primarily to enhance document durability and presentation quality in commercial and educational environments. Thermal laminators lead the product type category due to entrenched demand from commercial printing operations requiring glossy, rigid output for marketing materials. Automatic feed technology captures expanding share among print service providers facing labor constraints, while UV coating systems command premium positioning in graphic arts studios seeking chemical-resistant finishes without film substrate costs.
CE marking requirements under the EU Machinery Directive and RoHS substance restrictions govern equipment importation and electrical component sourcing across European markets, compelling manufacturers to redesign heating elements and control systems. The EPA's National Emission Standards for Hazardous Air Pollutants affects thermal lamination equipment sold in the United States by regulating solvent-based adhesive formulations and dryer exhaust configurations. Stakeholders must monitor evolving Ecodesign regulations from the European Commission that will likely mandate energy consumption disclosures and recyclability thresholds for lamination films and binding covers.
Market Dynamics
Commercial print finishing operations face intensifying pressure to automate binding and lamination workflows as labor availability tightens across North American and European print service centers, forcing equipment replacement cycles to compress from seven-year intervals toward four-to-five-year horizons.
Growth Catalysts
- EPA National Emission Standards for Hazardous Air Pollutants:Regulatory pressure on solvent-based adhesive formulations in the United States is accelerating capital redeployment toward thermal and UV-curing binding systems that eliminate volatile organic compound exposure.
- Educational publishing consolidation:K-12 and higher education textbook publishers in India are centralizing pre-press and finishing operations, creating concentrated demand for high-throughput perfect binding lines with integrated three-knife trimming.
- Polyurethane film lamination:Automotive interior suppliers are specifying TPU-based protective films for dashboard and door panel components, requiring specialized heated-roller systems with precision temperature control across 120°C to 150°C operating windows.
Market Restraints
- Silicon carbide heating element supply:Thermal lamination equipment manufacturers depend on Chinese suppliers for 70% of high-purity SiC components, exposing production schedules to export quota volatility and shipping cost spikes.
- CE marking compliance costs:EU Machinery Directive conformity assessment for new binding machine introductions requires third-party notified body involvement, adding eighteen-to-twenty-four month certification timelines that delay revenue recognition.
- Digital document substitution:Corporate training departments and legal firms are migrating technical manuals and contract repositories to cloud-based distribution, eliminating annual print runs that previously sustained mid-volume binding equipment utilization rates.
Strategic Opportunities
- India's Production-Linked Incentive scheme for specialty chemicals:Domestic adhesive formulation capacity expansion creates backward integration opportunities for binding equipment OEMs seeking captive supply of hot-melt EVA and PUR adhesives.
- On-demand packaging print finishing:E-commerce corrugated box converters require inline lamination for moisture-resistant exterior graphics, opening equipment sales channels outside traditional commercial print verticals.
- EU Ecodesign regulation preparatory studies:Anticipated energy consumption disclosure mandates for industrial laminators will favor early movers with verified efficiency testing protocols, creating first-mover certification advantages.
Industry Challenges
- Mechatronics technician scarcity:Servo-controlled binding lines require maintenance personnel fluent in both mechanical adjustment and PLC programming, a skill intersection that vocational training programs in Germany and the United States have failed to replenish at replacement rates.
- ISO 9001 certification timeline:Mid-tier suppliers seeking entry into institutional procurement channels face twelve-to-eighteen month quality management system implementation periods that delay competitive bidding eligibility.
- Legacy equipment integration:Print service providers with amortized perfect binders from the 2010s cannot justify full line replacement, forcing OEMs to engineer retrofit control packages that bridge analog sensors with Industry 4.0 data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binding & Lamination Machines Market |
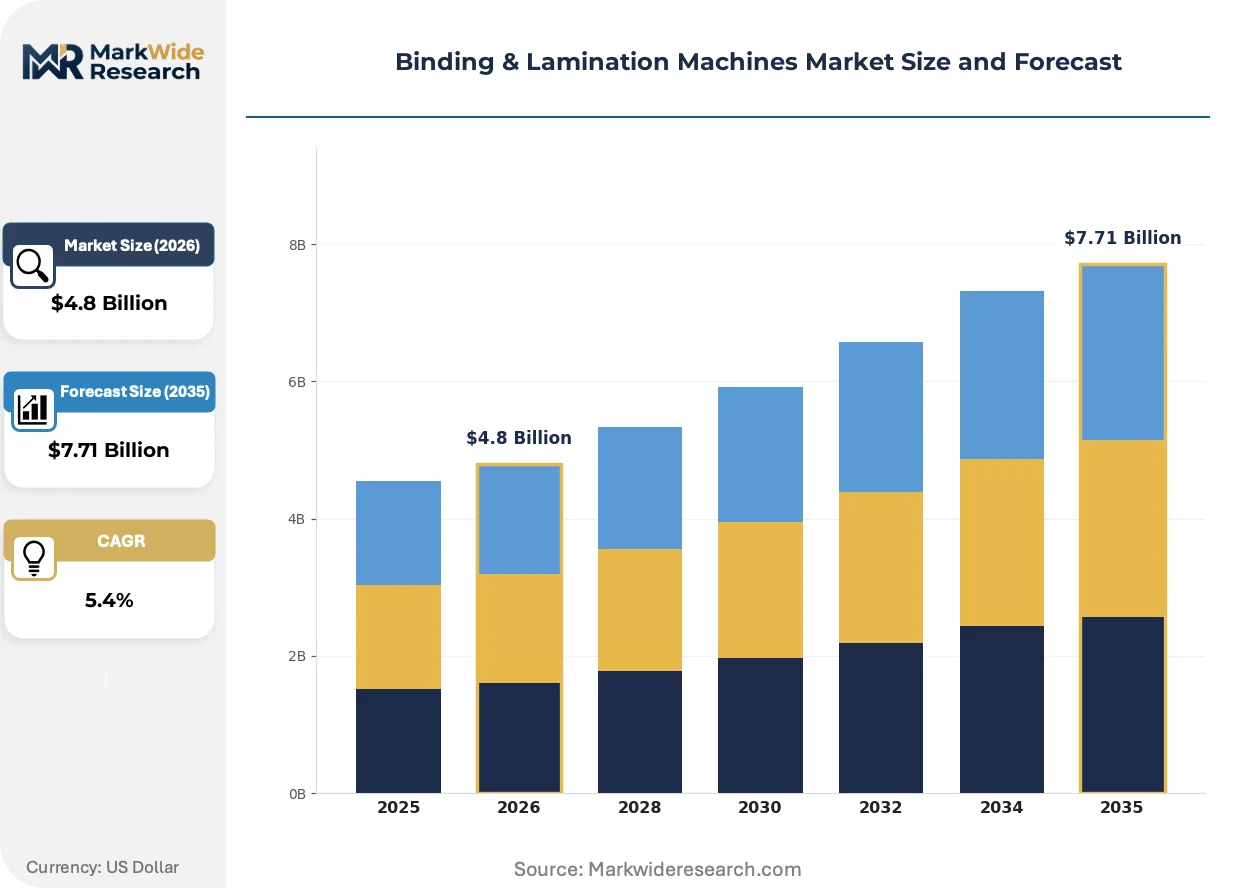
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Laminators, Cold Laminators, Binding Machines, Roll Laminators, Pouch Laminators Technology: Heat Activation, Pressure Sensitivity, UV Coating, Roll-to-Roll, Automatic Feed Application: Commercial Printing, Educational Institutions, Corporate Offices, Packaging, Advertising Agencies End User: Print Service Providers, Graphic Arts Studios, Document Management Firms, Publishing Houses |
| Companies Covered | Nordson Corporation, FRIMO Group, Akiles Products, HMT Manufacturing, KENMEC Mechanical Engineering, GBC, BOBST Group, Uteco Converting, Ledco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binding & Lamination Machines Market Trends and Innovations
Binding and lamination equipment architecture is diverging along two parallel development tracks: high-speed automated lines for volume print consolidation centers versus compact modular systems enabling distributed micro-factories near urban consumption clusters.
Water-based UV coating technology is fragmenting the protective finishing segment by eliminating thermal film substrate costs while delivering comparable chemical resistance and surface hardness. Mid-volume commercial printers in France and the Netherlands are retrofitting existing sheetfed offset presses with inline UV coating towers, compressing demand for standalone thermal laminators in the 50-100 sheets-per-minute category. Equipment financing structures are adapting to accommodate shorter depreciation schedules as buyers prioritize flexibility over fifteen-year asset longevity.
REACH substance restrictions on per- and polyfluoroalkyl substances are compelling European laminator manufacturers to reformulate release coatings on heated rollers and redesign exhaust filtration for fluoropolymer-containing legacy films. The regulation's downstream impact falls most heavily on food packaging converters who must validate new film-to-substrate adhesion protocols before Q4 certification deadlines. German OEMs are accelerating substitution testing programs to maintain CE marking validity across their installed base.
Print service providers are unbundling after-sales service contracts from initial equipment purchases, treating maintenance and spare parts as separately negotiated spend categories. This procurement pattern shift pressures OEM margin structures in the United States where multi-year service agreements historically contributed 35-40% of lifetime customer value. Independent technical service firms in Texas and California are capturing share by offering third-party preventive maintenance at 60% of manufacturer rates.
Binding & Lamination Machines Market Segmentation
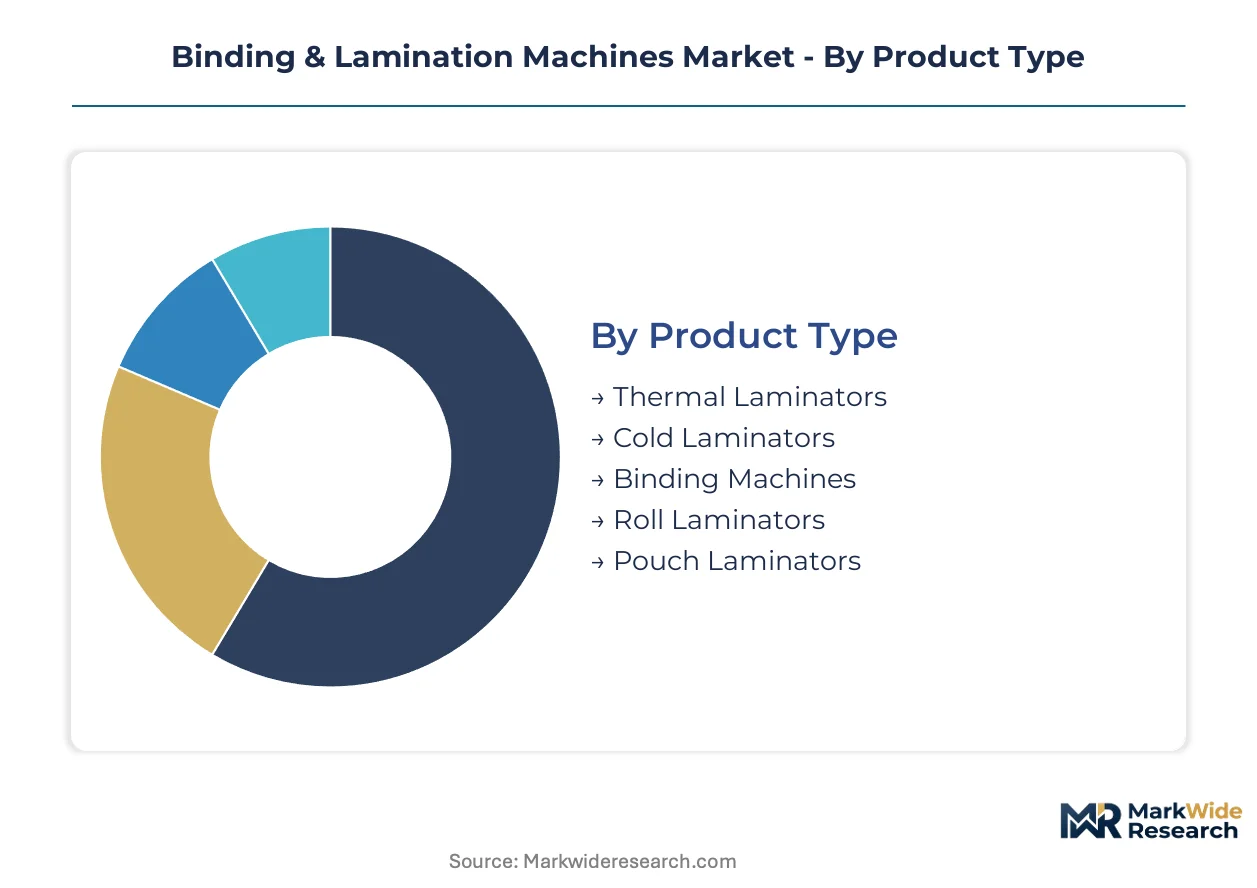
Binding and lamination equipment purchasing decisions diverge sharply by operational scale and output requirements. Print service providers evaluate throughput specifications and integration complexity against labor availability, while corporate and educational buyers prioritize footprint constraints and operator training thresholds.
Product Type:
Equipment flows through three distinct channel structures: direct OEM sales for high-capacity lines, dealer networks for mid-tier systems, and e-commerce platforms for entry-level desktop units.
- Thermal Laminators:These systems apply heat-activated adhesive films at 100°C to 160°C operating temperatures, utilizing heated rollers or plates to bond protective layers to printed substrates. Commercial printing operations in Germany's precision engineering corridor specify these for high-gloss marketing collateral, though REACH compliance on heated roller coatings adds reformulation costs for European suppliers.
- Binding Machines:Mechanical systems secure printed sheets through thermal fusion, pressure adhesion, or wire comb insertion, operating at pressures from 50 to 300 psi for perfect binding applications. Educational publishers in India are centralizing procurement of high-throughput perfect binding lines with integrated three-knife trimming as textbook production consolidates.
- Cold Laminators:Pressure-sensitive adhesive systems eliminate thermal components, reducing energy consumption and fire safety requirements for smaller operations.
- Roll Laminators:Continuous-feed systems process wide-format graphics and signage through heated roller pairs, common in advertising agency production departments.
- Pouch Laminators:Desktop units encapsulate documents in pre-formed adhesive pouches, dominating corporate office procurement through office supply distributors.
Thermal laminators dominate installed base. Binding machines are where expansion concentrates.
Technology:
Technology selection correlates directly with energy cost exposure and regulatory compliance burden across operating geographies.
- Heat Activation:Thermal adhesive melting remains the dominant binding mechanism for commercial print finishing, though EPA National Emission Standards for Hazardous Air Pollutants are accelerating capital redeployment toward systems that eliminate volatile organic compound exposure.
- Automatic Feed:Servo-controlled paper handling reduces labor intensity in high-volume operations, capturing expanding share among North American print service providers facing technician scarcity.
- UV Coating:Ultraviolet curing delivers chemical-resistant finishes without film substrate costs, gaining traction in French and Dutch commercial print markets where water-based formulations are displacing thermal lamination.
- Pressure Sensitivity:Cold adhesive bonding serves temperature-sensitive substrates and energy-constrained environments.
- Roll-to-Roll:Continuous web processing enables inline integration with flexographic and digital print engines for packaging converters.
Heat activation retains the largest installed base. Automatic feed is climbing the fastest as labor constraints intensify.
Application:
Application segmentation reveals diverging growth trajectories between document-centric verticals and emerging packaging opportunities.
- Commercial Printing:Print service providers automate finishing workflows to compress replacement cycles from seven-year intervals toward four-to-five-year horizons, driving demand for integrated binding and trimming lines.
- Packaging:E-commerce corrugated box converters require inline lamination for moisture-resistant exterior graphics, opening equipment sales channels outside traditional commercial print verticals with specialized heated-roller specifications.
- Educational Institutions:K-12 and higher education facilities prioritize desktop pouch laminators for in-house document protection, procuring through educational supply cooperatives.
- Corporate Offices:Document management departments specify compact binding systems for proposal and training material production.
- Advertising Agencies:Creative production studios demand wide-format roll laminators for point-of-sale and exhibition graphics.
Commercial printing anchors equipment revenue. Packaging is gaining share fastest as corrugated converters expand finishing capabilities.
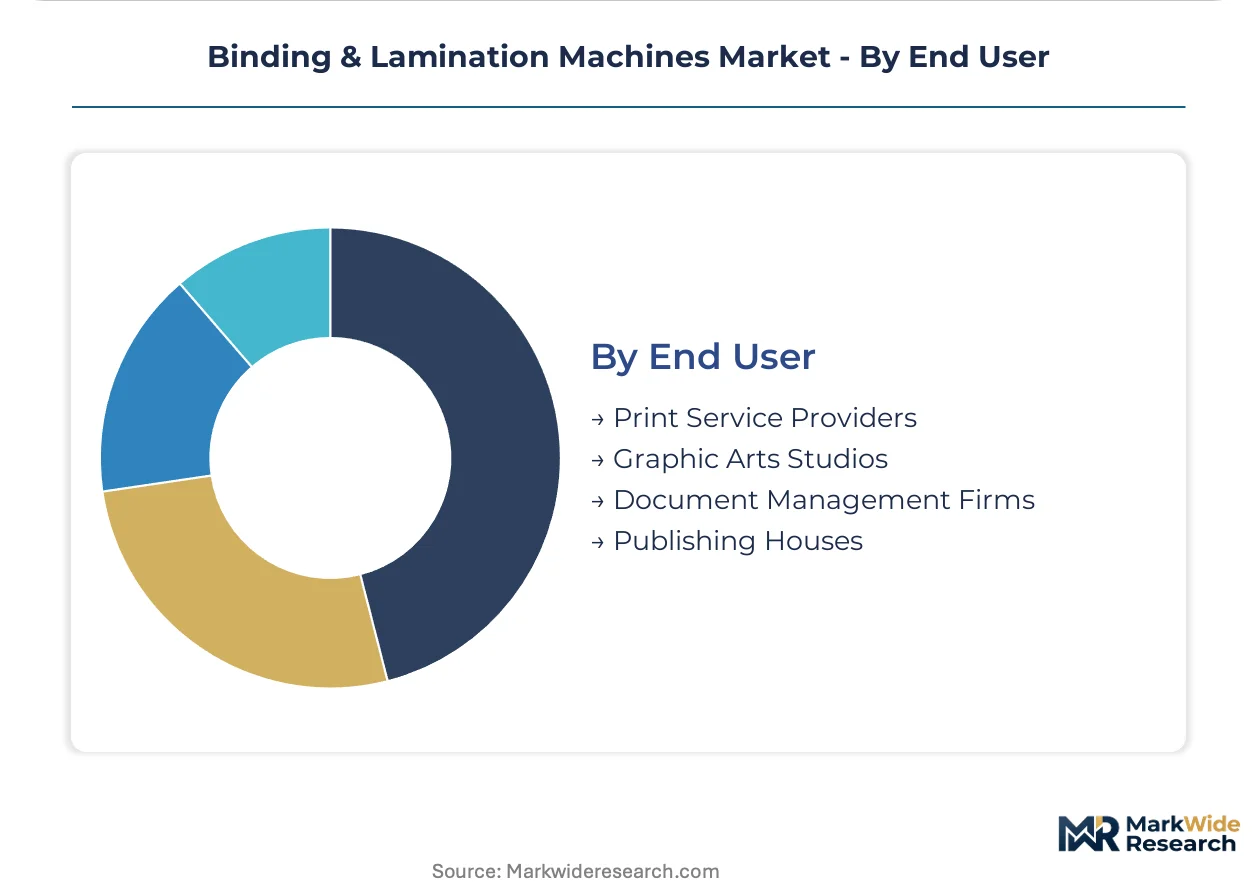
End User:
End-user procurement patterns are unbundling after-sales service from initial equipment purchases, treating maintenance as separately negotiated spend categories.
- Print Service Providers:These high-volume operators prioritize throughput reliability and preventive maintenance availability, though independent technical service firms in Texas and California are capturing share by offering third-party maintenance at reduced rates.
- Publishing Houses:Educational and trade publishers centralize pre-press and finishing operations, creating concentrated demand for high-throughput perfect binding lines as India's Production-Linked Incentive scheme expands domestic adhesive capacity.
- Graphic Arts Studios:Boutique creative operations specify UV coating systems for premium chemical-resistant finishes without thermal film costs.
- Document Management Firms:Corporate outsourcing providers procure mid-tier binding equipment for litigation support and records processing contracts.
Print service providers command the largest equipment installed base. Publishing houses are where procurement concentration is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Print service providers and packaging converters concentrate equipment procurement in manufacturing corridors with established precision engineering ecosystems and favorable regulatory treatment of automated finishing workflows.
Germany
Commercial print consolidation drives replacement of legacy binding systems with servo-controlled perfect binding lines in Baden-Württemberg's precision engineering corridor. REACH compliance mandates from ECHA compel heated roller coating reformulations that add certification costs for domestic OEMs. Stuttgart-based equipment fabricators supply high-throughput laminating systems across EMEA packaging markets.
United States
EPA National Emission Standards for Hazardous Air Pollutants accelerate capital redeployment from solvent-based adhesive systems toward thermal and UV-curing binding equipment. Labor scarcity in Texas and California print service centers compresses replacement cycles toward four-to-five-year intervals. Independent technical service firms in these states capture aftermarket maintenance contracts at rates below manufacturer service agreements.
India
Educational textbook publishers centralize pre-press and finishing operations, creating concentrated demand for high-throughput perfect binding lines with integrated three-knife trimming. The Production-Linked Incentive scheme for specialty chemicals expands domestic hot-melt adhesive capacity, enabling backward integration opportunities for binding equipment OEMs. Gujarat and Maharashtra host emerging manufacturing clusters serving South Asian print markets.
China
Silicon carbide heating element supply concentration exposes thermal lamination equipment manufacturers to export quota volatility and shipping cost spikes from domestic suppliers. MIIT industrial upgrading programs incentivize automation adoption in packaging converter operations. Yangtze River Delta manufacturing hubs produce mid-tier binding systems for export to Southeast Asian markets.
France
Water-based UV coating technology displaces thermal lamination demand among mid-volume commercial printers in the Île-de-France region. ANSM and CNIL regulatory frameworks intersect with REACH substance restrictions on per- and polyfluoroalkyl substances in food packaging applications. Paris-area graphic arts studios retrofit existing offset presses with inline UV coating towers to eliminate film substrate costs.
Binding & Lamination Machines Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with adhesive technology or converting machinery heritage alongside specialized equipment fabricators serving regional print markets. Strategic archetypes include precision engineering specialists leveraging ISO 9001 certification for institutional procurement access, and adhesive subsystem suppliers controlling critical components that OEMs specify for hot-melt operations. Competitive moves concentrate on vertical integration into captive adhesive supply and geographic expansion through dealer network establishment in emerging print markets.
Within the diversified industrial tier, Nordson Corporation and BOBST Group exemplify contrasting approaches to market positioning. Nordson extends adhesive dispensing technology into binding system subsystems, occupying a position as a critical component supplier rather than complete equipment fabricator. BOBST Group leverages Swiss manufacturing heritage to anchor high-speed rotary die-cutting and laminating lines for packaging converters. FRIMO Group sits within the specialized processing machinery segment, representing polyurethane lamination integration for automotive interior applications. These three entities illustrate how competitive positioning diverges between subsystem control, complete line integration, and vertical specialization.
| Leading Market Players |
|---|
| Nordson Corporation |
| FRIMO Group |
| Akiles Products |
| HMT Manufacturing |
| KENMEC Mechanical Engineering |
| GBC |
| BOBST Group |
| Uteco Converting |
| Ledco |
| Others |
Pricing and Supply Chain Analysis
Water-based UV coating substitution for thermal lamination films is redrawing procurement geography toward French and Dutch equipment retrofits while compressing pricing premiums previously commanded by heated-roller systems. This input shift simultaneously fragments supplier power across adhesive subsystem vendors and collapses film substrate cost pass-through structures.
Pricing Analysis
Cost-plus contracts with silicon carbide indexation govern thermal lamination equipment sales, exposing OEM margins to Chinese export quota volatility. Three-tier pricing structure across premium servo-controlled lines, standard pneumatic systems, and economy manual units differentiates on CE certification grade and after-sales bundling. Pricing pressure stems from independent Texas and California service firms undercutting manufacturer maintenance rates by forty percent. Corporate training departments migrating to digital document repositories exhibit highest price sensitivity, while packaging converters prioritizing moisture-resistant inline lamination show lowest.
Supply Chain Analysis
China supplies seventy percent of high-purity silicon carbide heating elements for thermal lamination equipment, with Germany and Japan fabricating precision servo-controlled binding lines. Raw material flows draw from Shanxi province SiC foundries, BASF adhesive resin formulations, and Swedish steel roller blanks. Single-source vulnerability concentrates in Chinese heating element export quotas, with logistics chokepoints at Shanghai and Ningbo ports. Distribution runs through direct OEM sales for high-capacity lines, authorized dealer networks for mid-tier systems, and Amazon Business for desktop pouch units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling from equipment purchases is expanding third-party maintenance revenue faster than hardware sales, creating attach-rate opportunities for predictive maintenance software and spare parts subscription programs.
For Market Incumbents: Shield installed base retention by embedding proprietary adhesive dispensing subsystems that lock in consumables revenue, while accelerating ISO 9001 certification for institutional procurement eligibility. Water-based UV coating retrofit kits threaten thermal laminator replacement demand; counter by offering control system upgrades that bridge 2010s analog sensors with Industry 4.0 data architectures. Backward integration into captive hot-melt adhesive supply secures margin defense against PLI-subsidized Indian competitors. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations unlocks eighteen-month compressed certification timelines versus standard twenty-four-month pathways. White-space concentrates in India's Gujarat and Maharashtra manufacturing clusters, where educational publisher consolidation demands high-throughput perfect binding lines with integrated three-knife trimming. Target e-commerce corrugated box converters in the Yangtze River Delta through equipment-as-a-service financing structures that align with shorter depreciation preferences. For Investors and Strategic Acquirers: EPA National Emission Standards for Hazardous Air Pollutants enforcement reshapes the acquisition landscape toward thermal and UV-curing equipment portfolios with solvent-free compliance. Long-term viability favors adhesive subsystem suppliers controlling critical hot-melt dispensing technology over complete equipment fabricators exposed to hardware commoditization. Monitor Ecodesign regulation preparatory studies from the European Commission as the signal for energy consumption disclosure mandates that will favor early movers with verified efficiency testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Supply | Captive hot-melt EVA and PUR production insulates margins from PLI-subsidized Indian capacity expansion. |
| Equipment-as-a-Service Financing | Subscription models align with print service provider preference for four-to-five-year replacement cycles over fifteen-year ownership. |
| CE Marking Fast-Track Certification | Pre-submission consultations with TÜV Rheinland or SGS compress eighteen-month notified body timelines for institutional market access. |
| Retrofit Control Package Development | Analog-to-digital bridge solutions capture revenue from amortized 2010s perfect binders resistant to full line replacement. |
| Third-Party Maintenance Network Buildout | Independent Texas and California service firms demonstrate sixty percent rate undercutting validates unbundled aftermarket capture. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at print service centers, OEM procurement teams, aftermarket service heads, and plant engineers at packaging converters, then refined through secondary validation. Trade data from Eurostat and U.S. Census Bureau machinery imports, SEC 10-K filings from diversified industrial conglomerates, and VDMA industry association production statistics anchored quantitative sizing. Bottom-up equipment shipment tallies and top-down print industry capital expenditure surveys were triangulated to converge on market estimates.
Variance decomposition across product type, technology, application, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from logistic adoption curves fitted to automation penetration rates in commercial print finishing, with inputs including labor cost indices for mechatronics technicians and REACH substance restriction implementation timelines. Energy cost exposure and compliance burden by operating geography informed technology segment trajectory assumptions across the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of sustained educational publisher consolidation and stable silicon carbide export quota administration; material deviation in either driver would warrant model refresh. Specific risk factors include accelerated digital document substitution in corporate legal sectors and MIIT industrial upgrading program modifications affecting Chinese packaging converter automation incentives. Recalibration cycles align with material shifts in EPA enforcement intensity and Ecodesign regulation finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Bubble Wrap Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Vacuum Sealing Machine Market