
 Multi Attachment Loaders Market | 2026-2036
Multi Attachment Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Attachment Loaders Market Foresight
Modular attachment bundling is pivoting buyer procurement from standalone machines to configurable loader platforms that accept multiple work tools. Deere & Company leverages its agricultural distribution network to cross-sell compact loader systems into farm operations. JCB Ltd. anchors its position through proprietary quick-hitch interfaces that reduce attachment swap time. Bobcat Company differentiates via compact footprint designs that dominate landscaping and tight-access construction segments.
Multi attachment loaders are self-propelled wheeled or tracked machines engineered with universal coupling interfaces, typically rated from 1,500 to 3,500 pounds operating capacity, designed to switch between buckets, forks, augers, and grapples within minutes for diverse material handling and earthmoving tasks. Skid steer loaders and compact track loaders together constitute the core product volume, with compact track variants gaining share on soft-ground performance advantages in site preparation and snow removal. Hydraulic systems technology remains the dominant architecture, though electric power variants are emerging fastest in municipalities pursuing fleet decarbonization targets.
EPA Tier 4 Final and OSHA equipment safety standards shape product certification requirements and operator protection mandates in the United States, while CE marking under EU machinery directives governs market access across European member states. China's GB standards and MEE emissions protocols add compliance layers for manufacturers serving infrastructure-heavy provincial markets. Stakeholders must monitor powertrain electrification timelines and attachment interoperability standards as these forces determine platform obsolescence risk and residual value trajectories.
Market Dynamics
Modular platform architecture is compressing replacement cycles as contractors prioritize attachment interoperability over dedicated single-purpose machines, forcing manufacturers to standardize coupling interfaces across product lines.
Growth Catalysts
- EPA Tier 4 Final compliance:Emissions mandates in the United States accelerate fleet turnover toward cleaner diesel and emerging electric powertrains, creating replacement demand in municipal contracting.
- Urban infrastructure densification:Compact loader footprints dominate site preparation in constrained metropolitan job sites across Germany and China where maneuverability commands premium positioning.
- Attachment ecosystem expansion:Hydraulic quick-coupler standardization enables contractors to deploy augers, grapples, and snow pushers on shared platforms, reducing capital deployment per work function.
Market Restraints
- Hydraulic component supply concentration:Precision valve and pump sourcing clusters in German and Japanese industrial centers, exposing OEMs to extended lead times during capacity constraints.
- Steel alloy input volatility:High-strength chassis materials fluctuate with commodity indexes, compressing margin visibility for manufacturers with fixed-price municipal contracts.
- Electric powertrain range limitations:Battery energy density constraints restrict continuous operation duration on large-scale earthmoving sites, delaying full electrification in heavy-cycle applications.
Strategic Opportunities
- China provincial infrastructure stimulus:GB standards alignment and MEE emissions protocols create compliant product pathways for equipment serving high-speed rail and highway expansion clusters.
- Telematics-attachment integration:IoT-enabled couplers that log utilization patterns and predict maintenance intervals enable subscription-based fleet management revenue streams.
- Landscaping service unbundling:Seasonal snow removal and grounds maintenance contractors in the United States adopt rental-to-own models for compact track variants, expanding addressable customer base.
Industry Challenges
- Certification timeline compression:CE marking under EU machinery directives and OSHA equipment safety standards require parallel testing protocols, straining engineering bandwidth for multi-market launches.
- Hydraulic technician scarcity:Specialized troubleshooting skills for high-pressure systems lag workforce development curves, extending downtime costs for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Attachment Loaders Market |
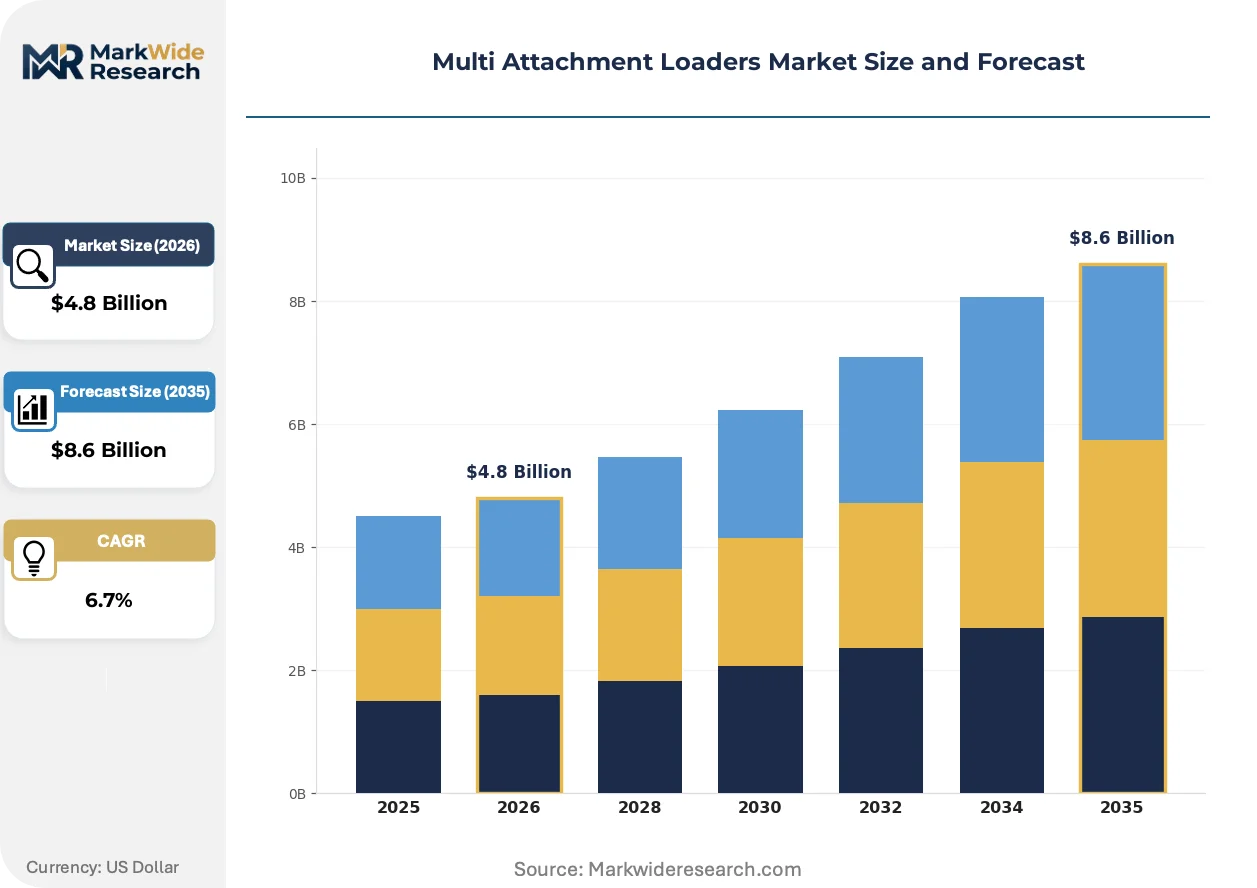
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid Steer Loaders, Compact Track Loaders, Wheel Loaders, All Terrain Forklifts End User: Agriculture, Construction, Landscaping, Municipalities Application: Earthmoving, Material Handling, Site Preparation, Snow Removal Technology: Hydraulic Systems, Electric Power, Mechanized Controls, Intelligent Operations |
| Companies Covered | Deere & Company, JCB Ltd., Volvo Construction Equipment, Bobcat Company, CNH Industrial N.V., Doosan Infracore Co., Ltd., Komatsu America, Hitachi Construction Machinery Co., Ltd., Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Attachment Loaders Market Shifts & Advancements
Powertrain electrification and digital integration are restructuring competitive differentiation, shifting value capture from mechanical reliability to software-enabled performance optimization and energy management.
Electro-hydraulic actuation systems are overtaking conventional mechanical linkages in premium loader segments. Municipal fleet managers in California and Nordic urban centers specify electric-hydraulic hybrids to meet decarbonization targets without sacrificing breakout force. This architecture is overtaking pure diesel configurations in sub-75-horseweight classes where duty cycles accommodate battery charging intervals.
EU Stage V emissions frameworks are tightening particulate matter and nitrogen oxide thresholds for non-road mobile machinery. Manufacturers serving European markets must integrate diesel particulate filters and selective catalytic reduction hardware, adding cost and packaging complexity. Compact track loader variants face the steepest compliance burden as their enclosed undercarriages limit thermal management space.
Rental channel consolidation is compressing OEM-direct sales ratios. United Rentals and Ashtead Group volume commitments now dictate specification priorities for mid-tier loader platforms, shifting design influence from end-user operators to fleet procurement analytics. Equipment utilization data shared through telematics partnerships shapes attachment bundling decisions and residual value forecasting.
Multi Attachment Loaders Market Segmentation
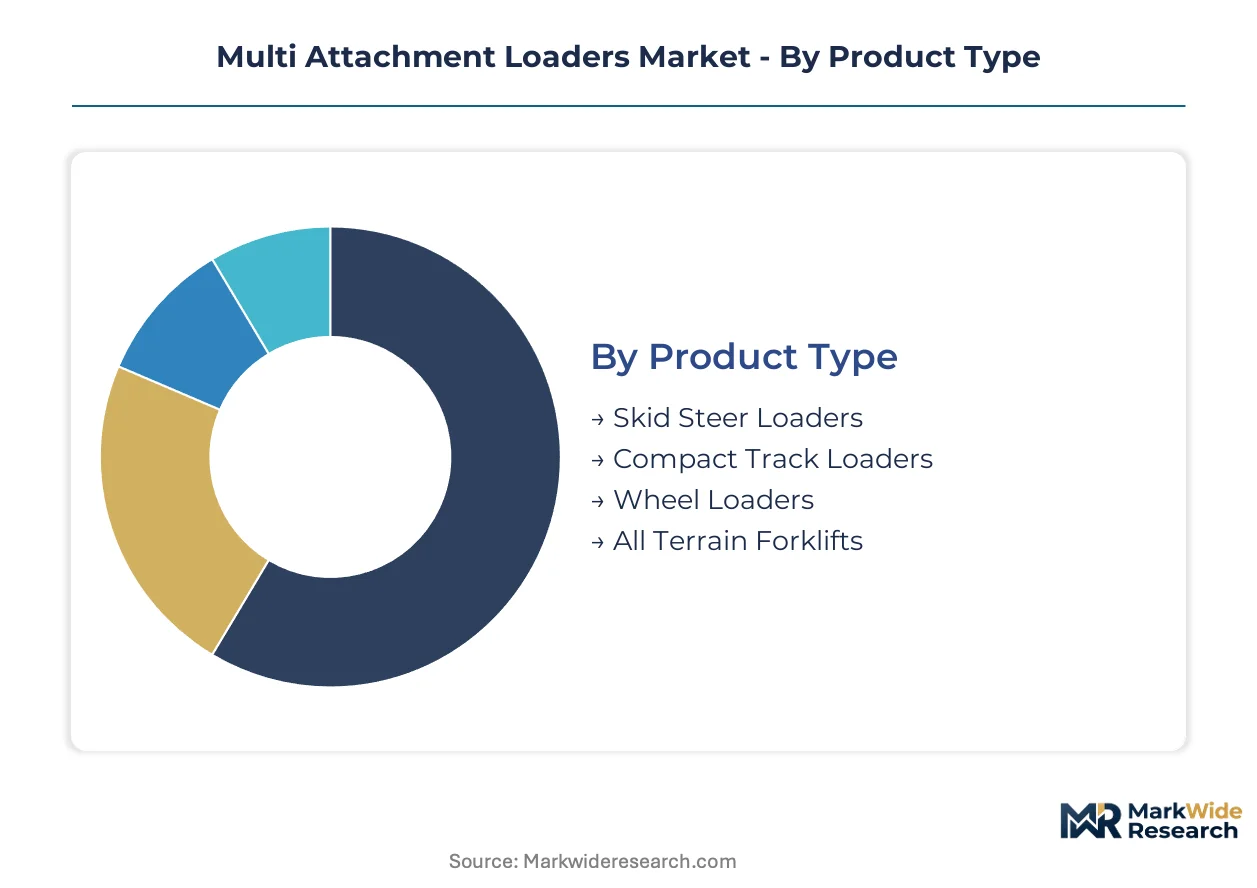
Multi attachment loader procurement patterns diverge sharply across operating environments, with contractors prioritizing footprint constraints, ground conditions, and attachment interchangeability rather than horsepower ratings alone. Equipment specification decisions cascade from site access limitations and seasonal utilization patterns, creating distinct buyer clusters that manufacturers must address through platform modularity.
Product Type:
Buyers in this category differentiate primarily by ground surface conditions and maneuverability requirements rather than lift capacity specifications.
- Skid Steer Loaders:Wheeled platforms with rigid-frame steering and rated operating capacities from 1,500 to 3,500 pounds dominate hard-surface construction sites. Demand concentrates in United States landscaping and urban demolition contractors where tight turning radius and low ground pressure on finished surfaces command premium positioning.
- Compact Track Loaders:Rubber-track undercarriages distribute weight across broader footprints, enabling soft-ground operation without site damage. Municipalities in Germany and snow removal contractors across the northern United States specify these variants for year-round deployment on sensitive turf and unpaved surfaces.
- Wheel Loaders:Articulated steering and higher lift arms serve aggregate handling and loading operations in quarry and mining feeder applications.
- All Terrain Forklifts:Rough-terrain masts and telescoping booms address material placement on uneven grades in remote construction and agricultural settings.
Volume sits with skid steer configurations; growth tilts toward compact track variants as site preservation mandates expand.
End User:
Capital deployment intensity and fleet utilization seasonality separate procurement behaviors across customer types.
- Construction:General contractors and specialty trades deploy loaders across demolition, concrete forming, and utility installation phases. Earthmoving contractors in China prioritize quick-coupler standardization to switch between buckets and grapples within single job cycles.
- Agriculture:Livestock operations and dairy farms specify compact loaders for feed handling and barn cleaning. Deere & Company's agricultural distribution network drives cross-selling into farm operations with bundled attachment packages.
- Landscaping:Seasonal revenue patterns push contractors toward rental-to-own financing for compact track units serving grounds maintenance and snow removal contracts.
- Municipalities:Public works departments specify electric-hydraulic hybrids in California and Nordic urban centers to meet decarbonization targets without sacrificing breakout force.
Construction commands the largest installed base; municipalities are climbing the fastest as fleet electrification timelines accelerate.
Application:
Cycle intensity and attachment dwell time determine platform durability specifications and hydraulic system sizing.
- Earthmoving:Continuous digging and grading operations subject loaders to high-impact duty cycles requiring reinforced quick-couplers and heavy-duty bucket configurations. Site preparation contractors in Germany specify compact track variants for residential foundation work on variable soils.
- Material Handling:Pallet fork and grapple applications emphasize lift capacity and load stability over breakout force. Distribution yards and recycling facilities in the United States prioritize hydraulic flow rates for simultaneous lift and auxiliary functions.
- Site Preparation:Land clearing and rough grading demand brush cutters and soil conditioner attachments with high-torque hydraulic demands.
- Snow Removal:Pusher and blower attachments require front-mounted quick-couplers with integrated electrical connections for hydraulic angling controls.
Earthmoving absorbs the highest equipment hours; snow removal is expanding most quickly as municipal outsourcing unbundles seasonal services.
Technology:
Powertrain architecture and control system sophistication segment buyers along regulatory compliance timelines and total cost of ownership horizons.
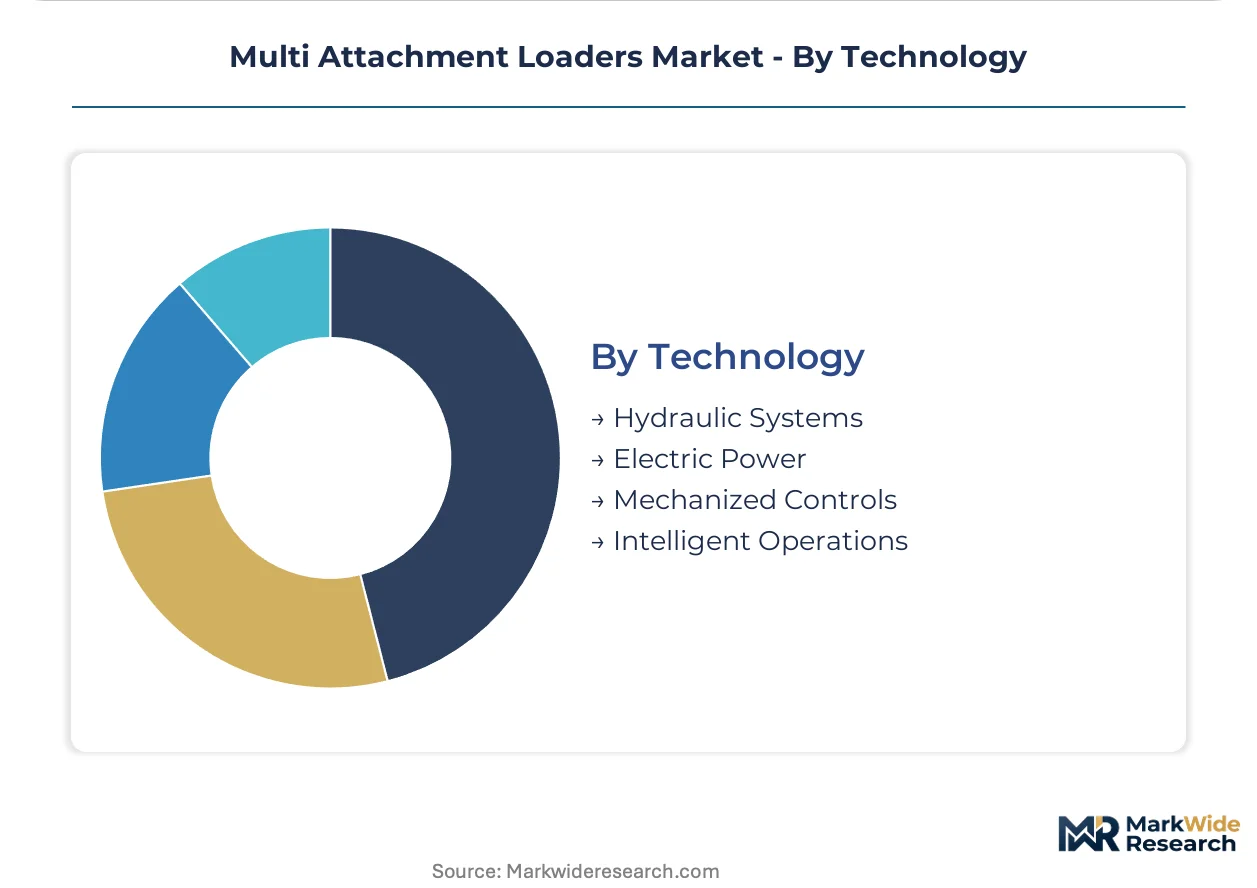
- Hydraulic Systems:Conventional diesel-hydraulic architectures remain dominant across heavy-cycle earthmoving and continuous operation environments. EPA Tier 4 Final compliance costs have compressed margins for manufacturers serving municipal contracting segments with fixed-price bid structures.
- Electric Power:Battery-electric and tethered electric variants address indoor demolition, food processing facilities, and zero-emission zones. California Air Resources Board mandates and EU Green Deal alignment are accelerating specification in urban fleet procurement.
- Mechanized Controls:Pilot-operated hydraulic joysticks and single-lever controls reduce operator fatigue in high-hour rental applications.
- Intelligent Operations:Telematics-enabled couplers and payload weighing systems support subscription-based fleet management and utilization-based billing models.
Hydraulic systems retain volume leadership; intelligent operations are gaining share fastest as rental channel consolidation shifts purchasing influence toward fleet analytics platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shanghai and Shenzhen concentrate assembly capacity for export-oriented loader platforms serving municipal fleets across North America and Europe.
United States
Municipal infrastructure stimulus and rental channel consolidation drive procurement of compact track loaders for snow removal and site preparation. EPA Tier 4 Final emissions standards mandate diesel particulate filters and selective catalytic reduction hardware on new equipment. Equipment clusters concentrate around Chicago, Dallas-Fort Worth, and Los Angeles metropolitan areas where United Rentals and Ashtead Group maintain dense depot networks.
Germany
Site preservation mandates on residential construction projects favor compact track variants with low ground pressure ratings for foundation work. EU Stage V emissions frameworks impose stringent particulate matter and nitrogen oxide thresholds on non-road mobile machinery. Manufacturing activity concentrates in Baden-Württemberg and Bavaria where Bosch Rexroth and Linde Hydraulics supply precision valve and pump components to OEM assembly lines.
China
Provincial infrastructure stimulus for high-speed rail and highway expansion generates demand for quick-coupler standardized platforms. GB standards and MEE emissions protocols establish compliance pathways for domestic and export-bound equipment. Production gravity sits in Shandong Province and the Yangtze River Delta where Sany Heavy Industry and XCMG operate integrated manufacturing campuses.
Japan
Compact loader demand from precision agriculture and urban demolition contractors emphasizes hydraulic efficiency and operator ergonomics. METI energy efficiency standards and JIS certification requirements shape product development timelines for domestic and Southeast Asian export markets. Industrial clusters concentrate in Aichi Prefecture and Osaka-Kobe manufacturing corridors where Komatsu and Kubota maintain captive component supply chains.
India
Rural road construction under the Pradhan Mantri Gram Sadak Yojana and urban smart city initiatives expand addressable demand for skid steer configurations. BIS certification and CEA emissions notifications add compliance layers for equipment serving infrastructure-heavy state markets. Assembly and distribution networks concentrate in Maharashtra and Gujarat where JCB India and Mahindra Construction Equipment operate regional manufacturing facilities.
Multi Attachment Loaders Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans agricultural equipment conglomerates, dedicated construction machinery manufacturers, and regional fabrication specialists serving price-sensitive municipal segments. Three archetypes dominate: diversified industrial groups with captive distribution networks, construction equipment pure-plays with proprietary attachment interfaces, and regional assemblers leveraging component import strategies. Consolidation pressures intensify through rental channel volume commitments and telematics partnership requirements.
Among diversified industrial groups, Deere & Company and CNH Industrial N.V. occupy positions anchored by agricultural equipment distribution networks that cross-sell compact loader platforms into farm operations. JCB Ltd. and Bobcat Company exemplify construction equipment specialists competing through proprietary quick-hitch interfaces and compact footprint designs. Komatsu America and Doosan Infracore Co., Ltd. represent scale-driven manufacturers with integrated hydraulic component sourcing and dense dealer service networks.
| Leading Market Players |
|---|
| Deere & Company |
| JCB Ltd. |
| Volvo Construction Equipment |
| Bobcat Company |
| CNH Industrial N.V. |
| Doosan Infracore Co., Ltd. |
| Komatsu America |
| Hitachi Construction Machinery Co., Ltd. |
| Kubota Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EPA Tier 4 Final and basic utility-tier loaders splits both pricing power and component sourcing strategies across the market. Premium platforms commanding municipal fleet contracts in California and Germany carry 40-60% hydraulic system cost premiums tied to selective catalytic reduction hardware and Bosch Rexroth valve sourcing, while price-sensitive agricultural buyers in India and China drive procurement toward Shandong-assembled configurations with standardized quick-couplers.
Pricing Analysis
Expedited lead-time premiums dominate contract structures, with municipal procurement officers paying 12-18% markups for German-manufactured compact track loaders delivering within 90 days versus 180-day standard cycles. Three-tier pricing structure across premium, standard, and economy levels tracks attachment bundling complexity and telematics integration depth. Cost compression in economy-tier skid steer configurations intensifies as Chinese OEMs expand export capacity through Yangtze River Delta free trade zones. Agricultural contractors exhibit highest price elasticity, while snow removal municipalities locked into seasonal contracting windows show least sensitivity to freight-adjusted delivered pricing.
Supply Chain Analysis
Regional distribution centers in Chicago, Dallas-Fort Worth, and Los Angeles anchor hub-and-spoke fulfillment patterns for United Rentals and Ashtead Group volume commitments. Manufacturing gravity centers on Germany, China, and Japan, with precision hydraulic components drawing from Baden-Württemberg and Aichi Prefecture industrial corridors. High-strength steel alloys, rubber track assemblies, and diesel particulate filters constitute critical input dependencies. Single-source vulnerability concentrates in Bosch Rexroth and Linde Hydraulics valve production, exposing OEMs to extended lead times during capacity constraints. Distribution runs through rental channel consolidation, with depot-level inventory positioning dictating specification priorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi attachment loader manufacturing is consolidating around telematics-enabled fleet management capabilities, with rental channel volume commitments forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Hedge platform obsolescence risk by accelerating electric-hydraulic hybrid R&D investment to meet California Air Resources Board mandates and EU Green Deal alignment timelines. Secure captive supply of precision hydraulic valves through backward integration or long-term offtake agreements with Bosch Rexroth and Linde Hydraulics, insulating margin structures from German industrial center capacity constraints. For New Entrants and Emerging Players: Begin with landscaping service contractor segments in the United States where rental-to-own financing models lower capital barriers and seasonal utilization patterns favor compact track variants over dedicated single-purpose machines. Target snow removal outsourcing contracts across northern state municipalities, leveraging attachment interoperability standards to displace legacy skid steer fleets through total cost of ownership positioning. For Investors and Strategic Acquirers: Re-rating potential sits with telematics-integrated pure-play specialists given IoT-enabled coupler adoption acceleration across rental channel consolidation. Five-to-ten year viability favors manufacturers with proprietary quick-hitch interfaces and software-enabled utilization analytics. Monitor attachment ecosystem expansion rates as inflection signal for platform standardization winners.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Attachment Integration | IoT-enabled couplers unlock subscription revenue streams for fleet management platforms. |
| Electric Powertrain Transition | California Air Resources Board mandates accelerate hybrid specification in municipal procurement. |
| Quick-Coupler Standardization | Hydraulic interoperability reduces capital deployment per work function for contractors. |
| Rental Channel Partnership | United Rentals volume commitments dictate specification priorities for mid-tier platforms. |
| Provincial Infrastructure Alignment | GB standards compliance opens high-speed rail equipment pathways in Shandong Province. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across equipment procurement managers at municipal public works departments, fleet operations directors at rental companies, maintenance directors at construction contractors, and aftermarket service heads at regional dealerships. EPA certification databases, EU machinery directive compliance registries, China customs export statistics, and SEC 10-K equipment segment disclosures provided validation layers. Bottom-up attachment shipment analysis and top-down fleet replacement modeling were triangulated against OEM production disclosures.
Data-stream reconciliation across shipment volumes, rental fleet utilization metrics, and provincial infrastructure budget allocations shaped projection outputs across the analysis window. Segmentation modeling captured product type, end-user vertical, application intensity, and powertrain architecture dimensions. CAGRs were derived from replacement cycle compression rates and electrification adoption curves, with municipal decarbonization timelines and attachment ecosystem expansion rates serving as key forecast inputs.
Underlying measurement precision varies by segment; electric power and intelligent operations categories carry tighter precision than conventional hydraulic configurations given regulatory visibility. Forecasts reflect documented assumptions around emissions compliance timelines and infrastructure stimulus execution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Earthmover Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Cold Planers Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Winch Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Snow Removal Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market