
 Radial Drilling Machine Market | 2026-2036
Radial Drilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Drilling Machine Market Analytics
Job shop and maintenance-repair-overhaul buyers is collapsing as a share of radial drilling machine procurement, while aerospace tier-1 suppliers and heavy machinery OEMs capture growing allocation. KAAST Machine Tools leverages its North American distribution infrastructure to anchor defense and energy sector contracts. Vandana Industries competes on cost-engineered floor and bench models for India's domestic metal fabrication segment. Shandong Luzhong Machine Tool dominates hydraulic technology variants through captive casting and machining capacity in Shandong Province.
A radial drilling machine positions a drill head on an arm that extends from and rotates around a vertical column, typically accommodating spindle speeds from 20 to 2,000 RPM and drill capacities up to 75 mm in steel; its primary industrial purpose is precision hole-making in large or awkwardly shaped workpieces that cannot be maneuvered under a fixed-spindle drill press. Heavy-duty product types lead absolute volume due to infrastructure and energy sector replacement cycles, while electric technology variants represent the fastest-growing configuration as factory electrification mandates tighten across multiple jurisdictions. Metal fabrication applications sustain the broadest installed base, though prototype development commands premium pricing through quick-change tooling and CNC retrofit compatibility.
OSHA machine guarding standards in the United States, CE marking and Machinery Directive compliance in Europe, and China's GB/T safety standards collectively shape product design, export eligibility, and liability exposure for radial drilling machine manufacturers. EPA and MEE emissions frameworks indirectly pressure foundry and heat-treatment suppliers upstream, transmitting cost and compliance requirements into finished machine pricing. Stakeholders must monitor how ISO 16090 machining center safety standards evolve to encompass retrofitted legacy radial drills in mixed-fleet environments.
Market Dynamics
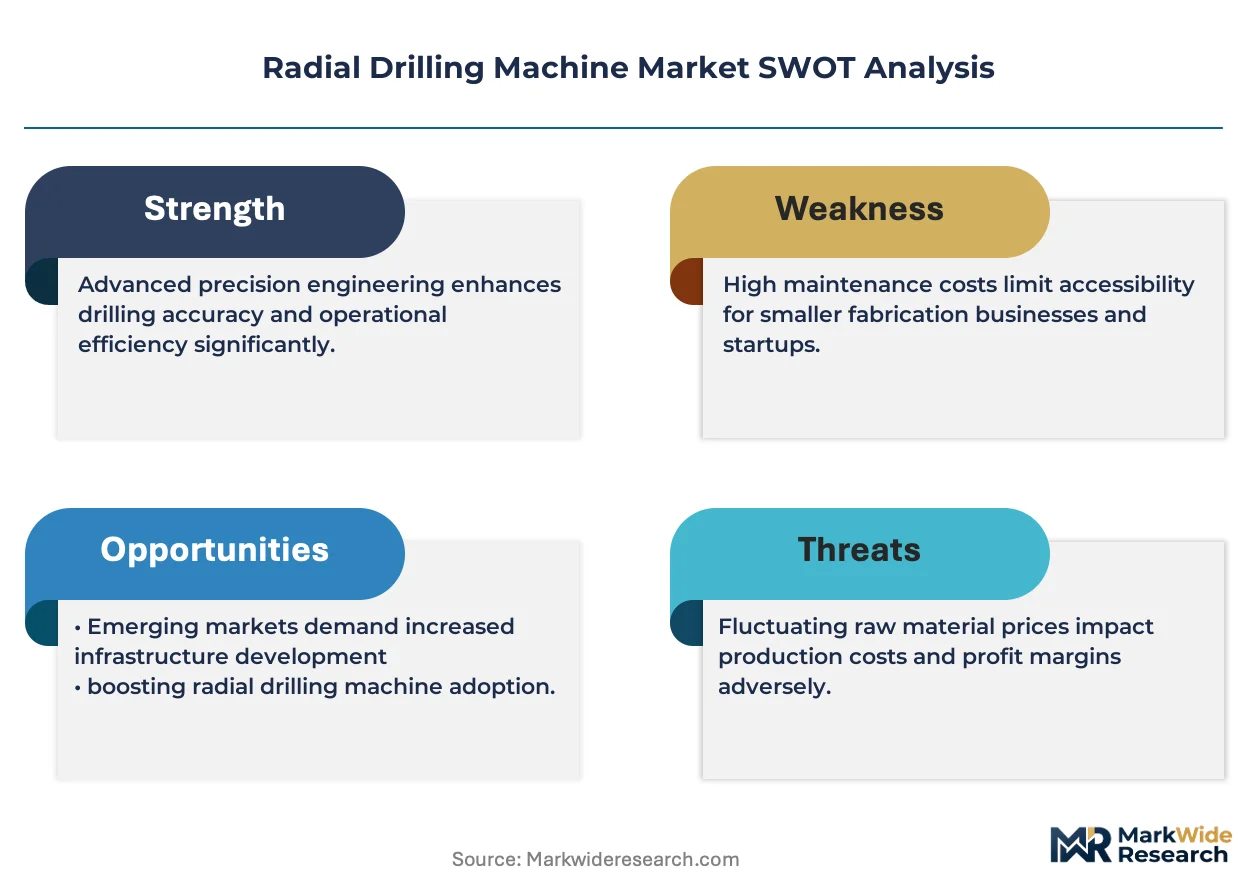
Factory electrification mandates across multiple jurisdictions are compressing replacement cycles for hydraulic radial drills while elevating electric spindle configurations to default specification status in new procurement tenders.
Growth Catalysts
- China's dual carbon goals:Energy-efficiency requirements under GB standards are accelerating retirement of legacy hydraulic machines and redirecting import demand toward electric technology variants.
- Aerospace tier-1 suppliers:Airframe assembly programs are expanding heavy-duty radial drill procurement for precision hole-making in large aluminum and titanium structural components.
- Baden-Württemberg precision engineering cluster:Dense automotive supplier networks in this German region sustain concentrated demand for high-accuracy drilling systems with quick-change tooling.
Market Restraints
- Foundry energy costs:EPA and MEE emissions frameworks are transmitting cost pressure through cast iron and steel casting supply chains into finished machine pricing.
- Control system import dependency:CNC retrofit compatibility requirements create structural reliance on proprietary spindle drive and motion control architectures from limited supplier bases.
- Manual machine substitution:Entry-level bench drills and portable magnetic drilling units capture low-precision applications that once absorbed basic radial drill volume.
Strategic Opportunities
- India's domestic metal fabrication segment:Cost-engineered floor and bench models face limited indigenous competition and absorb growing infrastructure investment.
- CNC retrofit compatibility:Quick-change tooling and open-architecture control interfaces enable premium positioning in prototype development workflows.
- Defense and energy sector contracts:North American distribution infrastructure anchors long-term service agreements with capital-intensive end-users seeking localized spare parts availability.
Industry Challenges
- ISO 16090 safety standard evolution:Machining center safety protocols are expanding to encompass retrofitted legacy radial drills in mixed-fleet environments, compressing compliance timelines for rebuild specialists.
- Multi-jurisdiction certification burden:Simultaneous OSHA machine guarding, CE marking Machinery Directive, and GB/T safety standard compliance extends product development cycles and fragments testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Drilling Machine Market |
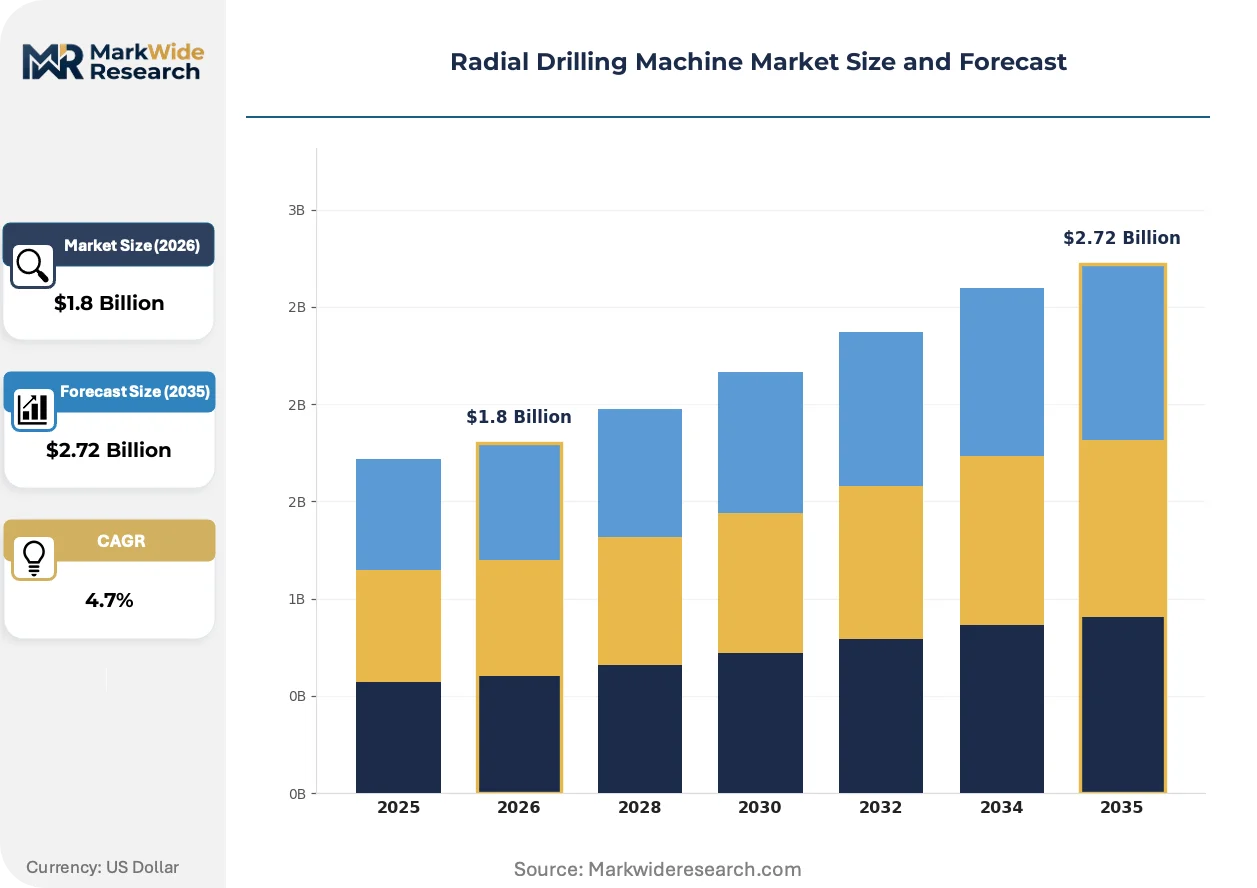
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench, Floor, Column, Heavy-Duty End User: Aerospace, Automotive Manufacturing, Heavy Machinery, Construction Technology: Electric, Pneumatic, Hydraulic, Mechanical Application: Metal Fabrication, Woodworking, Prototype Development, Maintenance |
| Companies Covered | KAAST Machine Tools, Vandana Industries, ANTISHICNC, Shandong Luzhong Machine Tool, Gurmeet Machinery Corporation, KNUTH Machine Tools USA, Shandong Tsinfa CNC Equipment, Shandong Matsumoto Machine Tool, Kent Industrial USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Drilling Machine Market Evolving Landscape
Electrification and digital integration are redefining radial drill architecture while regulatory safety harmonization attempts to bridge decades of legacy machine deployment with modern factory automation requirements.
Servo-electric spindle drives are fragmenting the traditional hydraulic power transmission segment by eliminating fluid maintenance cycles and enabling programmable torque curves. Aerospace manufacturers in Germany and the United States are specifying these configurations for repeatable hole quality in heat-resistant alloys. The technology is fragmenting aftermarket service revenue streams away from hydraulic seal and pump replacements toward encoder calibration and drive parameter optimization.
EU Machinery Directive updates and China's GB/T safety standard revisions are tightening interlock and emergency-stop requirements for semi-automatic drilling cycles. Machine builders must redesign column-mounted control enclosures and radial arm traverse limits to satisfy divergent regional test protocols. European metal fabrication job shops face the steepest compliance cost increases as they operate mixed fleets spanning thirty-year equipment age ranges.
Service contract unbundling is separating preventive maintenance from parts supply in capital equipment relationships. Energy sector buyers in North America now procure spindle bearing replacement kits through independent distributors rather than OEM service divisions. This pattern is most visible in maintenance-repair-overhaul procurement where total cost of ownership calculations favor component-level sourcing over bundled annual agreements.
Radial Drilling Machine Market Segmentation
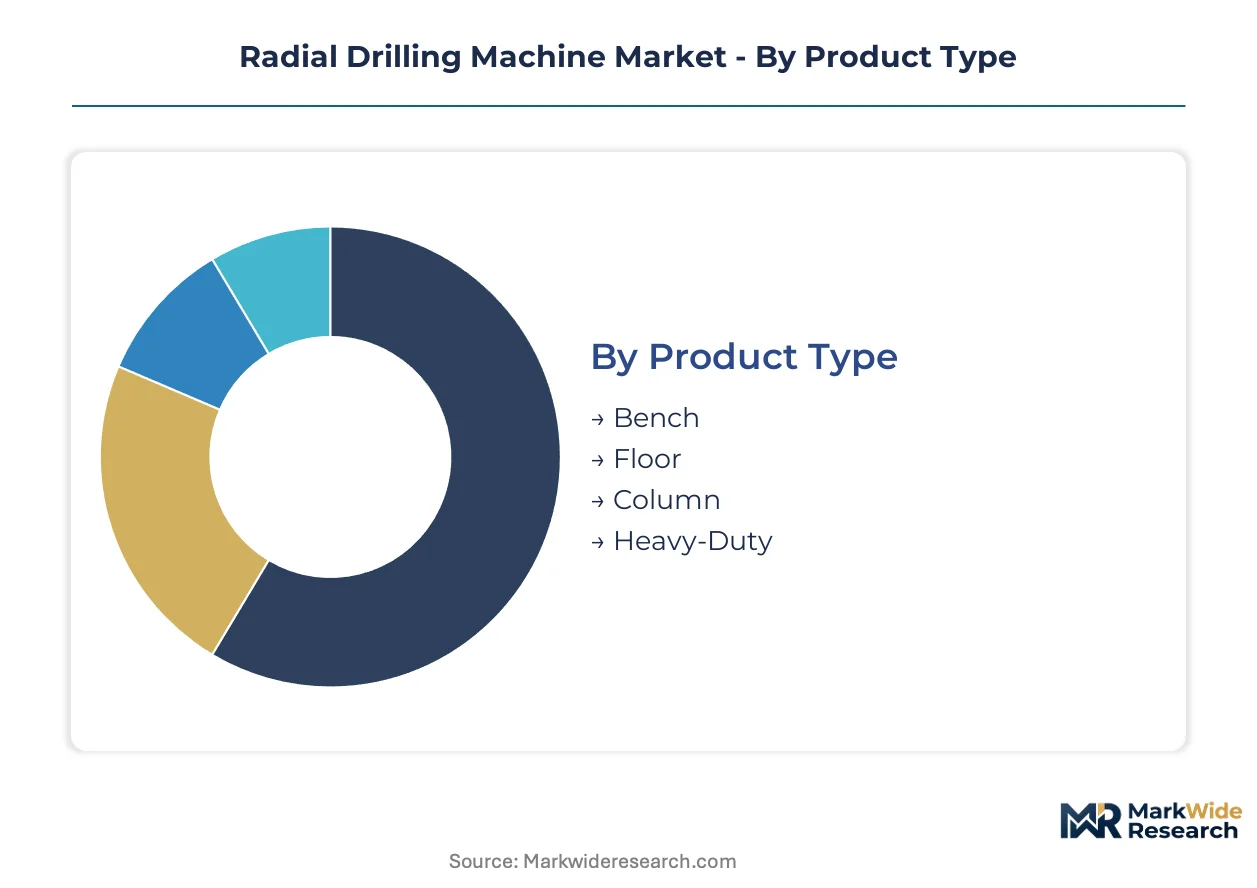
Radial drilling machine procurement patterns diverge sharply across product configurations, end-use sectors, and power transmission technologies. Regulatory mandates on energy efficiency and factory automation compatibility reshape specification priorities within each segment boundary.
Product Type:
OSHA machine guarding standards in the United States, CE marking Machinery Directive in Europe, and China's GB/T safety standards impose divergent physical enclosure and interlock requirements that favor heavier column and floor-mounted designs over compact bench units in cross-border trade.
- Heavy-Duty:These machines accommodate spindle drives exceeding 7.5 kW and drill capacities up to 75 mm in steel, serving infrastructure replacement cycles and energy sector capital programs. Demand concentrates among aerospace tier-1 suppliers in Germany and the United States for precision hole-making in large aluminum and titanium structural components, though foundry energy costs transmit pricing pressure through cast iron casting supply chains.
- Floor:Freestanding units with adjustable column heights dominate metal fabrication job shops requiring workpiece mobility. India's domestic infrastructure investment absorbs cost-engineered variants from Shandong Province foundries, while Baden-Württemberg automotive suppliers specify quick-change tooling compatibility for dense supplier network integration.
- Bench:Compact units for light-duty drilling face substitution pressure from portable magnetic drills in low-precision applications.
- Column:Fixed-base designs with rotating arms occupy the mid-market for general machining operations with moderate spindle speed requirements.
Established volume favors Heavy-Duty; emerging adoption favors Floor.
End User:
Customer procurement authority and total cost of ownership calculation methods fragment sharply between capital-intensive OEMs with in-house maintenance capabilities and job shops reliant on OEM service divisions.
- Aerospace:Airframe assembly programs demand repeatable hole quality in heat-resistant alloys, specifying servo-electric spindle drives with programmable torque curves. German and United States manufacturers lead procurement, with factory electrification mandates compressing replacement cycles for legacy hydraulic configurations.
- Heavy Machinery:OEMs producing mining and construction equipment require radial drills for large cast iron and steel workpieces that cannot maneuver under fixed-spindle presses. China's dual carbon goals accelerate retirement of energy-intensive hydraulic machines in favor of electric technology variants.
- Automotive Manufacturing:Tier-1 and tier-2 suppliers in precision engineering clusters prioritize quick-change tooling and CNC retrofit compatibility for prototype development workflows.
- Construction:Equipment manufacturers and on-site maintenance operations absorb mid-duty floor models with limited automation requirements.
Procurement value concentrates in Aerospace; installation breadth extends across Heavy Machinery.
Technology:
Power transmission architecture determines maintenance cost structures, energy efficiency compliance, and aftermarket revenue streams for component suppliers.
- Electric:Servo-electric spindle drives eliminate fluid maintenance cycles and enable programmable motion profiles. Factory electrification mandates across multiple jurisdictions elevate these configurations to default specification status in new procurement tenders, fragmenting aftermarket revenue toward encoder calibration services.
- Hydraulic:Traditional power transmission dominates installed base volume but faces accelerated retirement under China's GB standards and EPA emissions frameworks affecting foundry suppliers.
- Pneumatic:Compressed-air drives occupy niche applications in explosive environments and facilities with existing compressor infrastructure.
- Mechanical:Belt and gear-driven spindles persist in legacy installations and cost-sensitive markets with limited automation requirements.
Installed base dominance remains with Hydraulic; specification momentum shifts toward Electric.
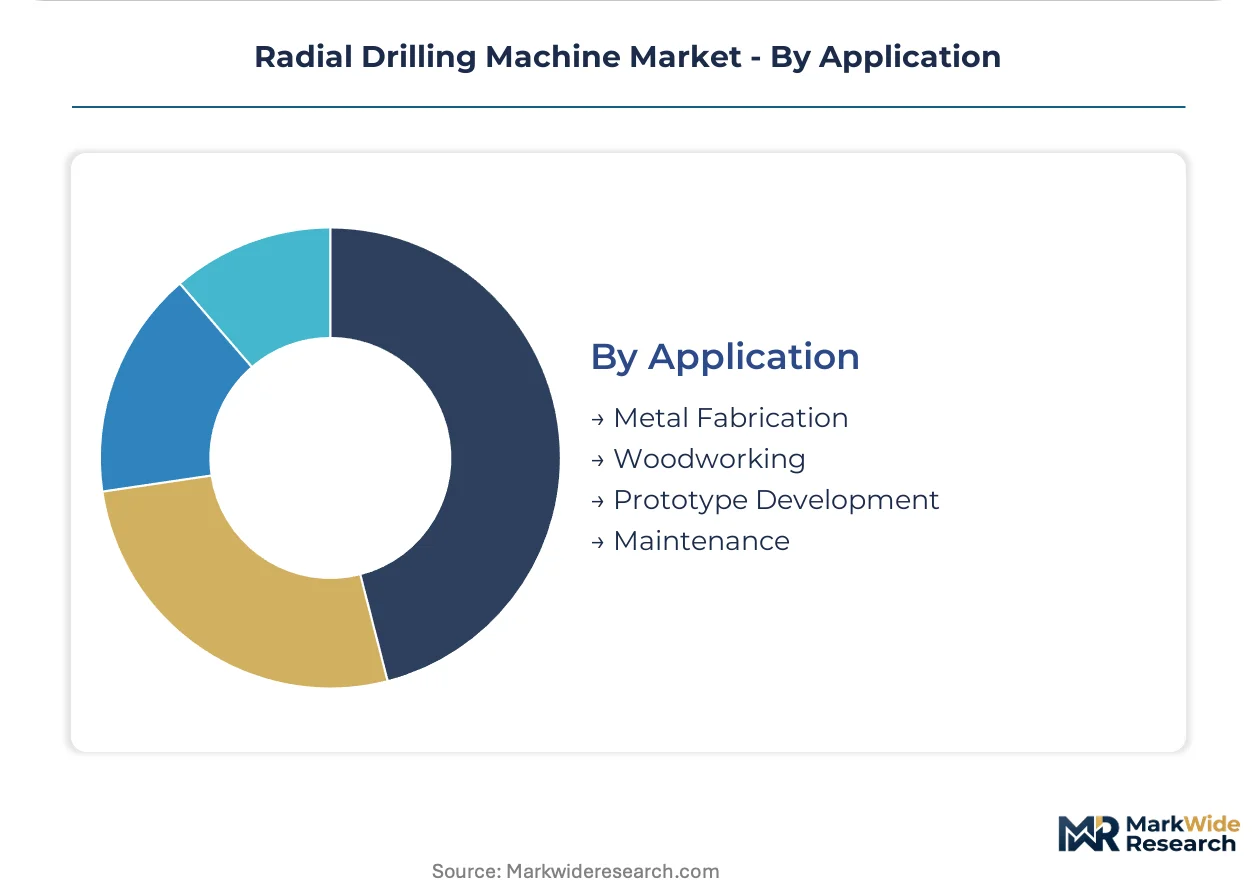
Application:
Workpiece material characteristics and production batch sizes determine tooling change frequency, spindle speed range requirements, and control system complexity.
- Metal Fabrication:Broadest installed base spanning steel, aluminum, and alloy drilling with varying chip load requirements. India's domestic segment absorbs cost-engineered floor and bench models with limited indigenous competition.
- Prototype Development:Quick-turn workflows command premium pricing through CNC retrofit compatibility and open-architecture control interfaces. Aerospace and automotive R&D facilities in Germany and the United States specify these configurations for design validation cycles.
- Maintenance:Repair and overhaul operations favor component-level sourcing over bundled service agreements, unbundling preventive maintenance from parts supply in capital equipment relationships.
- Woodworking:Lower spindle speed requirements and reduced cutting forces permit lighter-duty bench and column configurations with basic guarding compliance.
Volume concentration sits with Metal Fabrication; margin expansion tracks Prototype Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered radial drilling systems to aerospace manufacturers in the United States and automotive suppliers across Central Europe, establishing the dominant trade-flow corridor in high-accuracy machine tools.
United States
Aerospace tier-1 suppliers in Seattle and Wichita expand procurement of heavy-duty radial drills for airframe assembly programs. OSHA machine guarding standards enforce interlock requirements on column-mounted control enclosures. Defense sector buyers in Texas anchor long-term service agreements through North American distribution infrastructure.
Germany
Baden-Württemberg's precision engineering cluster sustains concentrated demand from automotive supplier networks requiring quick-change tooling compatibility. CE marking and Machinery Directive compliance shape product design for cross-border export eligibility. Stuttgart-based fabricators supply CNC-retrofit-compatible systems to prototype development facilities.
China
Domestic infrastructure investment absorbs cost-engineered floor models while GB standards accelerate retirement of legacy hydraulic machines. MEE emissions frameworks transmit cost pressure through Shandong Province foundries. Dual carbon goals redirect import specifications toward electric spindle configurations.
India
Metal fabrication job shops in Maharashtra and Gujarat drive volume for bench and floor models with limited indigenous competition. BIS certification requirements influence safety enclosure specifications for imported equipment. Domestic infrastructure programs absorb cost-engineered variants from regional distributors.
Japan
Automotive and precision machinery OEMs in Aichi Prefecture specify servo-electric spindle drives for repeatable hole quality. METI industrial efficiency guidelines favor programmable torque curves over hydraulic power transmission. Nagoya-based manufacturers export high-accuracy systems to Southeast Asian fabrication networks.
Radial Drilling Machine Market Competitive Landscape
Player mix skews toward regional specialists with captive foundry capacity and mid-scale fabricators dependent on imported control systems. Market structure fragments across three tiers: integrated manufacturers with backward casting operations, assembly-focused distributors serving defense and energy contracts, and cost-engineered exporters targeting price-sensitive domestic fabrication. Strategic moves center on CNC retrofit compatibility partnerships and geographic expansion through localized spare parts warehousing.
Within the integrated-manufacturer tier, Shandong Luzhong Machine Tool and Shandong Matsumoto Machine Tool occupy positions anchored by captive machining capacity in Shandong Province. KAAST Machine Tools represents the distribution-anchored archetype, exemplifying North American infrastructure deployment for defense and energy sector relationships. These three company structures illustrate how competitive positioning separates foundry-integrated Chinese producers from service-network-dependent Western distributors.
| Leading Market Players |
|---|
| KAAST Machine Tools |
| Vandana Industries |
| ANTISHICNC |
| Shandong Luzhong Machine Tool |
| Gurmeet Machinery Corporation |
| KNUTH Machine Tools USA |
| Shandong Tsinfa CNC Equipment |
| Shandong Matsumoto Machine Tool |
| Kent Industrial USA |
| Others |
Value Network & Pricing Analysis
Captive casting capacity in Shandong Province anchors cost floors for Chinese manufacturers while compressing margin headroom for Western assemblers dependent on outsourced foundry supply. Scale advantages at integrated producers transmit directly into specification flexibility on electric spindle configurations, forcing distributors to compete through service bundling rather than hardware pricing.
Pricing Analysis
Electric-hydraulic-mechanical technology generations stratify across premium, standard, and economy tiers with widening gaps as factory electrification mandates accelerate. Servo-electric spindle drives command premium positioning through programmable torque curves and reduced maintenance cycles, while legacy hydraulic configurations face price erosion from regulatory retirement pressure in China and Europe. Aerospace tier-1 suppliers in Germany and the United States exhibit lowest price sensitivity due to total cost of ownership calculations favoring precision and uptime, whereas India's domestic metal fabrication segment drives volume absorption of cost-engineered floor models where specification flexibility trumps brand premium.
Supply Chain Analysis
Strategic stockpiling of cast iron and steel castings characterizes procurement behavior among integrated manufacturers, while distributors operate on lean inventory models vulnerable to Shandong Province foundry output fluctuations. Supply concentration in China, Germany, and India shapes component availability timelines, with CNC control systems drawing from limited Japanese and German motion architecture suppliers. Single-source vulnerability in spindle drive electronics creates structural risk for retrofit specialists, while distribution runs through regional service networks anchored by localized spare parts warehousing in North American defense and energy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encoder calibration and drive parameter optimization services are expanding faster than hardware shipments as electric spindle configurations fragment aftermarket revenue streams away from traditional hydraulic maintenance.
For Market Incumbents: Consolidate captive foundry relationships in Shandong Province to defend cost position against emerging Chinese exporters, while accelerating CNC retrofit compatibility partnerships to offset substitution pressure from portable magnetic drilling units. Certification investment in GB/T safety standard compliance opens sustained access to China's domestic infrastructure procurement channels. For New Entrants and Emerging Players: Anchor in India's domestic metal fabrication segment where BIS certification requirements create defensible positioning against unorganized regional competition, targeting cost-engineered floor models for Maharashtra and Gujarat job shops. Component-level sourcing relationships with independent distributors bypass entrenched OEM service networks in North American maintenance-repair-overhaul procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with backward casting operations over assembly-dependent distributors as electrification mandates compress replacement cycles. Five-to-ten year viability hinges on control system import diversification, with encoder supply security serving as the critical inflection signal for premium positioning in aerospace and automotive prototype development workflows.| Strategic Initiative | Industry Significance |
|---|---|
| CNC Retrofit Compatibility Program | Open-architecture control interfaces capture premium positioning in German and United States prototype development facilities. |
| Captive Foundry Capacity Expansion | Shandong Province casting integration insulates cost structures from EPA and MEE emissions framework pressure. |
| Localized Spare Parts Warehousing | Regional inventory positioning secures long-term service agreements with Texas defense sector buyers. |
| Electric Spindle Drive Partnership | Servo-electric technology alliances enable programmable torque curves for aerospace heat-resistant alloy applications. |
| GB/T Safety Certification Investment | Chinese standard compliance redirects import specifications toward electric configurations under dual carbon goals. |
Research Methodology
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview cycles, validated against customs trade data, SEC filings from listed machine tool manufacturers, foundry energy cost disclosures, and aerospace tier-1 supplier capital expenditure reports. Bottom-up installation base modeling triangulated with top-down trade flow analysis across Germany, China, India, and the United States.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product type, power transmission technology, end-use sector, and regional regulatory cluster. CAGRs derived from replacement cycle analysis, electrification mandate compliance timelines, and infrastructure investment absorption rates in named precision engineering clusters.
Material uncertainties — foundry energy cost volatility, CNC control system supply disruptions, and ISO 16090 safety standard evolution timelines — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation pace and technology substitution thresholds. Revision becomes warranted when electric spindle configuration penetration crosses critical mass in aerospace procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Earthmover Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Smart Crane Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Robotic Total Stations (RTS) Market