
 Earthmoving Equipment Market | 2026-2036
Earthmoving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Earthmoving Equipment Market Analysis
The EU Green Deal's construction sector decarbonization targets are expanding demand for lower-emission earthmoving fleets across European public works tenders. Caterpillar Inc. leverages its global dealer network to sustain aftermarket parts revenue in mature North American markets. Komatsu Ltd. anchors its position through autonomous haulage integration that reduces labor intensity in Australian iron ore pits. SANY Group competes aggressively on cost-engineered hydraulic excavators for Southeast Asian contractors.
Earthmoving equipment comprises heavy machinery engineered to displace, transport, and grade soil, rock, and aggregate materials using hydraulic actuation systems typically generating breakout forces exceeding 150 kN. These machines serve as primary production tools in civil engineering, mineral extraction, and land modification operations where mechanical advantage replaces manual labor at scale. Excavators command the largest installed base across product categories due to versatility in trenching, loading, and demolition cycles. Electric technology segments are gaining fastest traction in urban construction zones where noise ordinances and indoor air quality rules restrict diesel operation. Site preparation applications absorb the greatest equipment hours because every subsequent construction phase depends on precisely graded and compacted substrate conditions.
The US EPA enforces Tier 4 Final particulate and NOx limits that compel engine manufacturers to integrate selective catalytic reduction and diesel particulate filters, raising powertrain costs but creating aftermarket retrofit opportunities. China's MEE implements dual carbon goals that push domestic OEMs toward battery-electric prototypes for municipal projects in Beijing and Shanghai. Stakeholders must monitor how emission compliance timelines in the European Union, United States, and China diverge, as asynchronous regulatory phase-ins will fragment equipment specification requirements and complicate multinational fleet standardization decisions.
Market Dynamics
Diesel-electric hybrid powertrains are forcing a fundamental equipment specification rewrite as EPA Tier 4 Final and EU Stage V emission ceilings harden, compelling fleet operators to retire legacy machines ahead of depreciation schedules or absorb costly aftertreatment retrofits.
Growth Catalysts
- Australian and Chilean mining expansion:Copper and lithium output targets are absorbing new excavator and haul truck deliveries. Pit operators require larger fleets to meet battery supply chain mineral commitments.
- EU Green Deal construction decarbonization:Public works tenders now embed lower-emission fleet requirements. Municipal procurement rules across Germany, France, and the Netherlands favor machines meeting Stage V standards with documented carbon footprints.
- Hydraulic system efficiency gains:Variable displacement pumps and regenerative circuits are cutting fuel consumption per cubic meter moved. Contractors in India's infrastructure corridor projects specify these configurations for 24-hour earthmoving cycles.
Market Restraints
- High-alloy steel input volatility:Boom and arm fabrication depends on specialized plate grades subject to scrap metal price swings. OEM margin compression intensifies when nickel and molybdenum spot markets spike.
- Engine supply concentration:Selective catalytic reduction and diesel particulate filter subsystems source from a narrow tier of certified suppliers in Germany and Japan. Disruption ripples through final assembly schedules.
- Battery energy density limitations:Electric excavators above 20-ton operating weight face runtime constraints in continuous loading applications. Quarry operators defer full electrification until cell chemistry improves.
Strategic Opportunities
- Autonomous haulage integration:Sensor fusion and machine learning convergence enables unmanned truck fleets in Australian iron ore pits. Labor cost arbitrage and safety incident reduction drive adoption curves.
- Southeast Asian contractor cost optimization:Cost-engineered hydraulic excavators address price-sensitive infrastructure builds in Indonesia, Vietnam, and the Philippines. Local assembly partnerships reduce import duty exposure.
- China MEE dual carbon municipal mandates:Battery-electric prototypes gain trial deployment in Beijing and Shanghai urban demolition zones. Night work permits hinge on noise and zero-tailpipe compliance.
Industry Challenges
- Autonomous systems technician scarcity:Fleet maintenance departments lack personnel trained in LiDAR calibration and predictive algorithm diagnostics. Vocational pipelines have not scaled to match deployment timelines.
- Retrofit certification complexity:EPA and EU Stage V compliance timelines diverge, fragmenting equipment specification requirements. Multinational operators face fleet standardization paralysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthmoving Equipment Market |
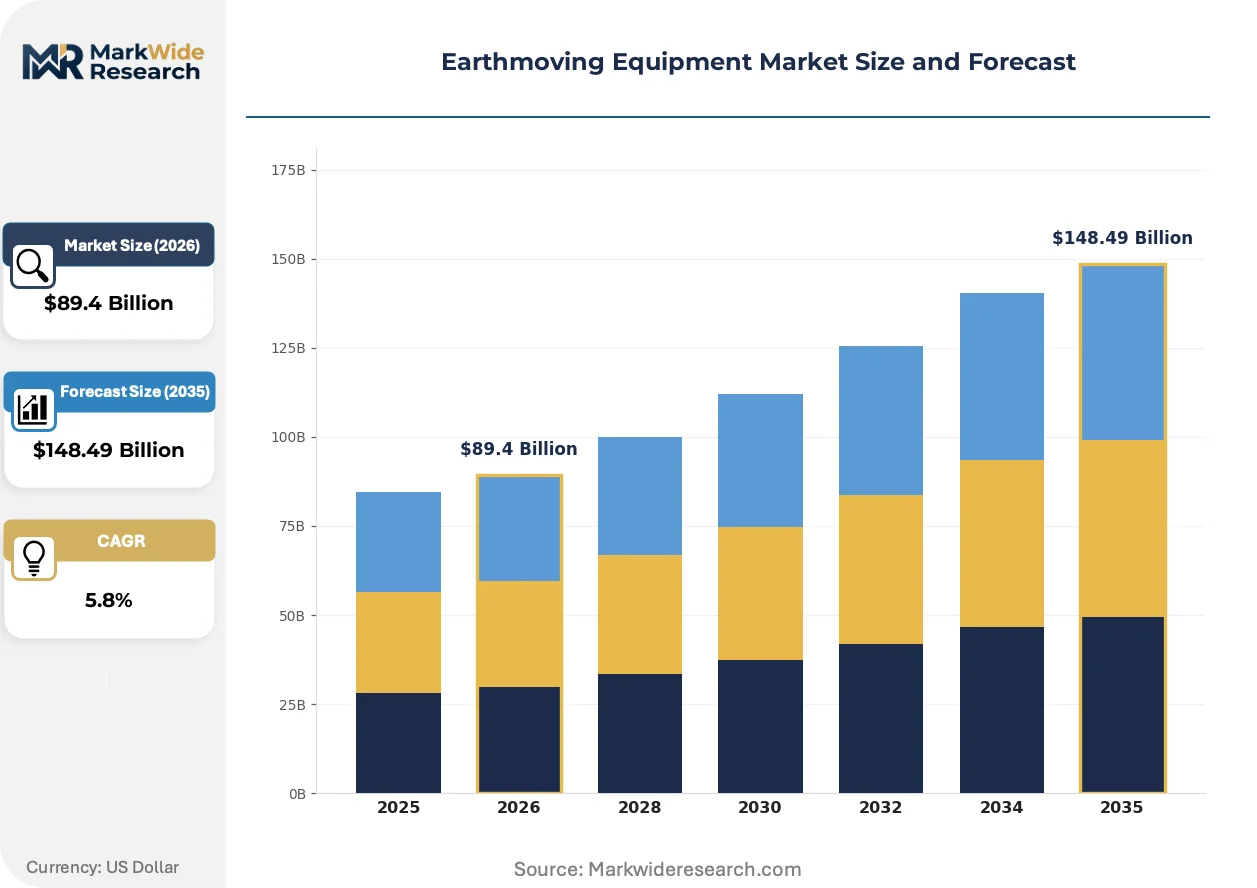
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $148.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Loaders, Backhoes Technology: Hydraulic, Electric, Mechanical, Pneumatic End User: Construction, Mining, Agriculture, Landscaping Application: Site Preparation, Trenching, Demolition, Road Construction |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co. Ltd., Liebherr Group, AB Volvo, J.C. Bamford Excavators Limited, SANY Group, Doosan Infracore Co. Ltd., XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthmoving Equipment Market Emerging Trajectories
Powertrain electrification and automation are compressing traditional equipment lifecycle economics while reshaping how contractors evaluate total cost of ownership across fuel, labor, and downtime variables.
Telematics-integrated predictive maintenance is consolidating aftermarket service relationships around data-rich platforms that anticipate hydraulic pump failures and track undercarriage wear in real time. Large mining contractors in Australia and Chile now specify OEM-native connectivity as a procurement prerequisite. Equipment-as-a-service contracts bundle hardware, maintenance, and uptime guarantees into single-line operating expenditures that displace capital-heavy ownership models.
EU Stage V and EPA Tier 4 Final emission standards are tightening particulate and NOx enforcement across public works tenders. Engine manufacturers must integrate selective catalytic reduction and diesel particulate filters, raising powertrain costs but creating certified retrofit pathways for aging fleets. European municipal contractors face the steepest compliance cliffs as Green Deal procurement rules harden through 2027.
Rental and short-term leasing channels are capturing growing equipment-hour share from traditional ownership models. Southeast Asian contractors facing project-to-project cash flow variability prefer operational flexibility over balance-sheet asset concentration. India's infrastructure corridor builders increasingly source machines through dealer rental pools that absorb residual value risk and maintenance burden.
Earthmoving Equipment Market Segmentation
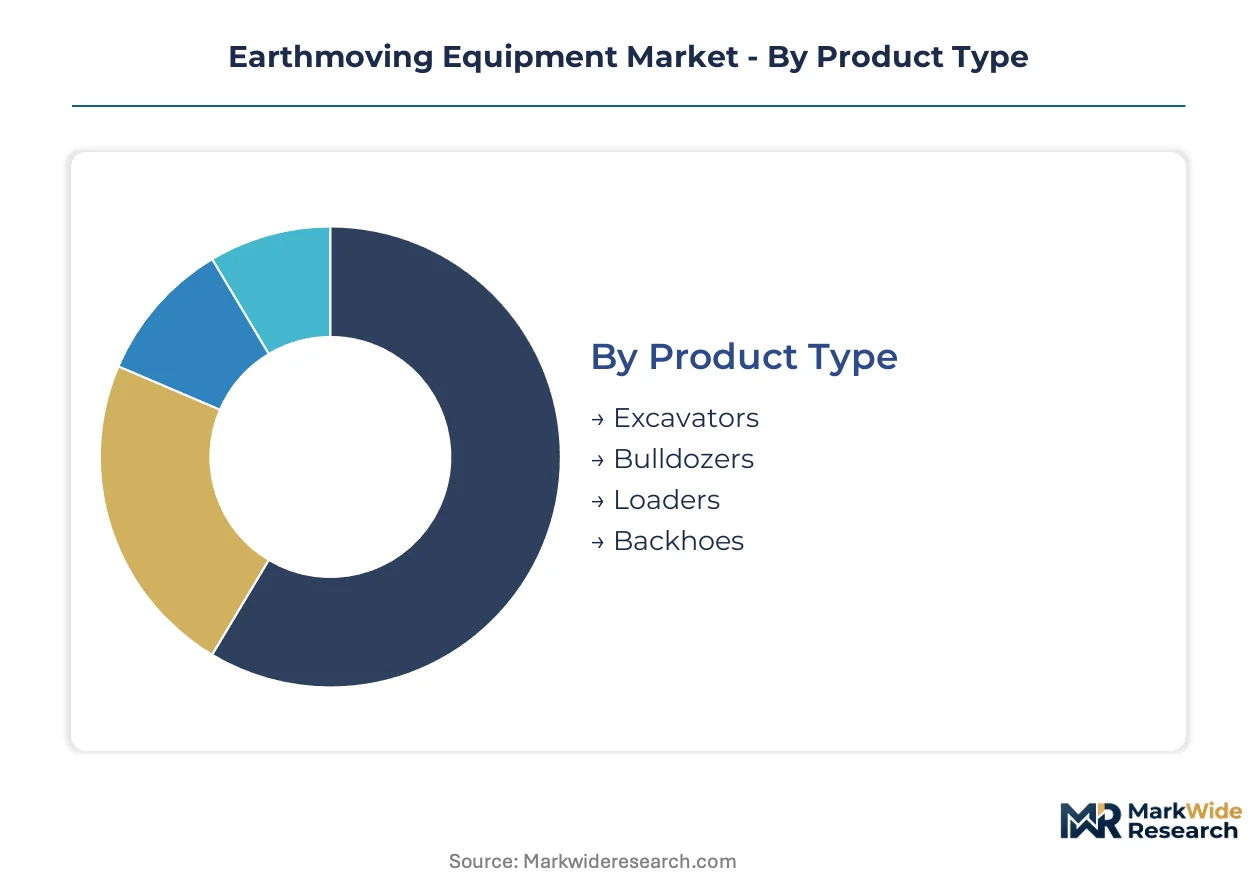
Equipment segmentation reveals how capital deployment patterns diverge across powertrain technologies and end-use intensities. Fleet managers calibrate specifications against duty cycles, emission zones, and terrain demands that vary sharply by project type.
Product Type:
Replacement cycles accelerate where hydraulic system wear and undercarriage fatigue accumulate fastest in high-shift operations.
- Excavators:These machines deploy boom-arm-bucket kinematics with breakout forces exceeding 150 kN for trenching and loading cycles. Australian iron ore pits and Chilean copper operations absorb the heaviest crawler-mounted units as pit depths extend. Fleet operators face 8,000-hour rebuild decisions on major hydraulic components.
- Loaders:Articulated chassis designs with hydrostatic transmissions dominate material rehandling at crushing plants and stockpile yards. India's infrastructure corridor projects specify these for aggregate loading where cycle frequency exceeds 40 loads per hour. Z-bar linkage geometry determines bucket penetration force and spillage rates.
- Bulldozers:Track-type tractors with power-shift or hydrostatic drivelines deliver drawbar pull for cut-and-fill earthworks. Ripper-equipped configurations penetrate fractured rock in mining overburden removal.
- Backhoes:Loader-excavator combinations serve utility trenching and light construction with sub-100-horsepower engines. Municipal contractors in European cities favor compact models for streetscape work.
Volume placements concentrate in Excavators; the faster expansion belongs to Loaders.
Technology:
Powertrain cost tiers stratify sharply between mature diesel-hydraulic platforms and emerging electric architectures.
- Hydraulic:Variable displacement piston pumps with load-sensing circuits optimize fuel efficiency across 20-50 ton operating weights. EPA Tier 4 Final aftertreatment adds $15,000-$25,000 per machine but preserves operational range in remote mining locations.
- Electric:Battery-electric prototypes with 300-500 kWh packs enable zero-tailpipe operation in urban demolition zones. Beijing and Shanghai municipal projects trial these where night work permits hinge on noise compliance.
- Mechanical:Direct mechanical linkages persist in emerging market cost-optimized equipment where simplicity outweighs efficiency gains. Southeast Asian contractors accept higher fuel consumption for lower acquisition cost.
- Pneumatic:Compressed air systems serve specialized underground mining applications where spark suppression mandates exclude internal combustion. Narrow vein operations in select jurisdictions specify these for ventilation-constrained headings.
Cost-sensitive procurement favors Mechanical systems; the steepest expansion trajectory belongs to Electric powertrains.
End User:
Customer margin profiles and equipment utilization rates create distinct specification demands across sector boundaries.
- Construction:General contractors deploy mixed fleets across civil engineering, commercial building, and infrastructure phases. EU Green Deal procurement rules in Germany and France now embed Stage V compliance and carbon footprint documentation as tender prerequisites.
- Mining:Pit operators in Australia and Chile run 24-hour continuous cycles with autonomous haulage integration. Labor cost arbitrage and safety incident reduction drive sensor-fusion deployments in iron ore operations.
- Agriculture:Land improvement contractors specify lower-horsepower units for drainage ditching and field leveling. Seasonal utilization patterns favor rental over ownership in volatile commodity price environments.
- Landscaping:Compact equipment with rubber tracks or tires minimizes ground pressure on finished surfaces. Urban parks departments in the Netherlands prioritize low-noise configurations for residential adjacency.
Equipment-hour concentration sits with Mining; the fastest share gains belong to Construction decarbonization mandates.
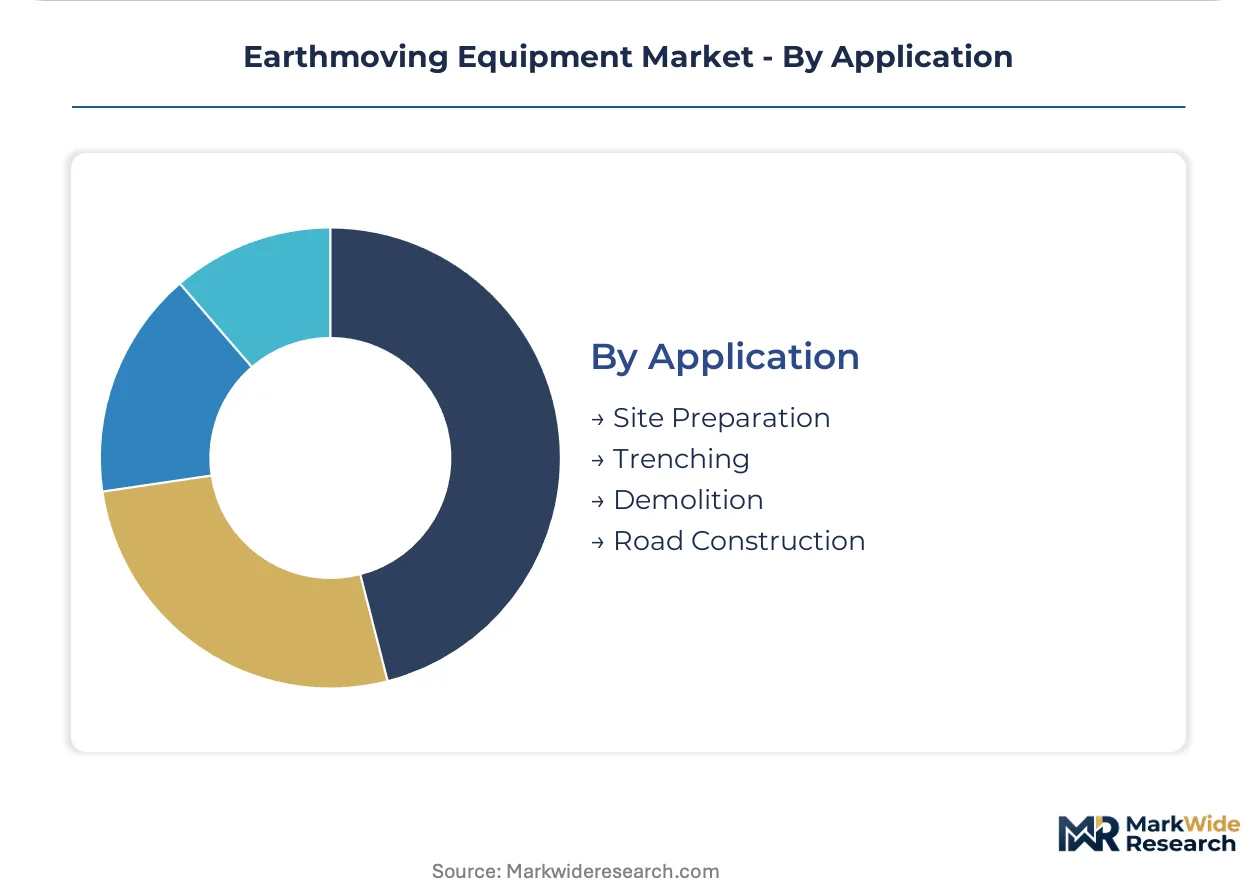
Application:
Site sequence dependencies make certain applications non-discretionary while others respond to cyclical investment timing.
- Site Preparation:Cut-and-fill grading with dozers and motor scrapers establishes substrate conditions for all subsequent construction. Every vertical development phase depends on precisely compacted bearing capacity.
- Trenching:Utility installation demands excavators with specialized boom configurations for pipe laying and backfilling. India's infrastructure corridors absorb continuous trenching cycles for water, power, and fiber networks.
- Demolition:High-reach excavators with hydraulic pulverizer attachments dismantle urban structures. Battery-electric prototypes gain trial deployment in Beijing and Shanghai where dust and noise ordinances restrict diesel operation.
- Road Construction:Grader and compactor fleets establish longitudinal grade and density specifications. Federal highway programs in select jurisdictions sustain equipment demand through multi-year appropriation cycles.
Equipment-hour dominance belongs to Site Preparation; the most rapid demand shift appears in Demolition electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara mining clusters in Western Australia absorb the heaviest crawler-mounted excavator deployments as pit depths extend and copper output targets harden. Fleet operators across four additional national markets face distinct regulatory and demand configurations.
United States
Infrastructure appropriations through federal highway programs sustain multi-year demand for graders and compactors across the Midwest and Southeast corridors. EPA Tier 4 Final enforcement compels selective catalytic retrofits on legacy fleets in California and Texas construction zones. Houston-Galveston petrochemical expansion absorbs specialized earthmoving hours for site preparation at downstream facilities.
China
Western region mining belts in Xinjiang and Inner Mongolia drive haul truck and excavator replacement cycles as lithium extraction scales. MEE dual carbon mandates push battery-electric prototypes into Beijing and Shanghai municipal demolition tenders. Yangtze River Delta contractors trial zero-tailpipe configurations where night work permits hinge on noise compliance.
Germany
EU Green Deal procurement rules embed Stage V compliance and carbon footprint documentation in federal transport infrastructure tenders. Autonomous haulage integration trials concentrate in Lower Saxony quarry operations seeking labor cost arbitrage. Bavarian construction consortia specify lower-emission fleets for Autobahn expansion phases through 2027.
India
National infrastructure corridor projects across Delhi-Mumbai and Chennai-Bengaluru industrial belts specify fuel-efficient hydraulic configurations for 24-hour earthmoving cycles. BIS emission alignment pressures OEMs to localize aftertreatment assembly. Gujarat port expansion and Maharashtra metro construction absorb continuous excavator and loader deployments.
Chile
Atacama Desert lithium extraction operations require expanded haul truck fleets to meet battery supply chain mineral commitments. Antofagasta and Calama mining clusters absorb the heaviest unit deployments as pit operators extend extraction depths. Copper output targets in the central zone drive excavator replacement ahead of standard depreciation schedules.
Earthmoving Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration and aftermarket service intensity. The vendor base stratifies into three tiers: full-line OEMs with autonomous system portfolios, regional specialists in cost-engineered hydraulics, and rental fleet operators consolidating used equipment channels. Strategic moves concentrate on telematics platform integration and equipment-as-a-service contract expansion that displace capital-heavy ownership models.
Within the full-line OEM tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by global dealer network density and autonomous haulage system deployment. SANY Group anchors the cost-optimization archetype through localized assembly partnerships that reduce import duty exposure in Southeast Asian markets. These three entities exemplify how scale, geographic origin, and technology positioning stratify competitive access to mining and infrastructure procurement channels.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co. Ltd. |
| Liebherr Group |
| AB Volvo |
| J.C. Bamford Excavators Limited |
| SANY Group |
| Doosan Infracore Co. Ltd. |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
EU Stage V emission ceilings gate qualified supply for premium-tier earthmoving equipment, restricting certified engine and aftertreatment subsystem availability to OEMs with established compliance pathways. Fleet operators in Germany and France face procurement premiums for machines meeting documented carbon footprint thresholds, while contractors in price-sensitive Southeast Asian markets absorb higher fuel consumption to access lower acquisition cost mechanical-hydraulic alternatives.
Pricing Analysis
Outcome-based contracts anchored to uptime guarantees and fuel efficiency per cubic meter moved are displacing traditional capital-heavy ownership models. Price differentiation hinges on Stage V certification tier and autonomous system integration depth, with Australian mining contractors absorbing premiums for sensor-fusion haulage configurations. Cost compression in the mechanical-hydraulic tier is intensifying because Chinese OEMs localize assembly partnerships. Municipal procurement teams in European cities exhibit the least price sensitivity, while Southeast Asian infrastructure contractors prioritize lowest acquisition cost over lifecycle operating expenditure.
Supply Chain Analysis
Dual-sourcing mandates from Australian and Chilean mining operators require engine manufacturers to qualify SCR and DPF subsystems from multiple certified suppliers in Germany and Japan. High-alloy steel plate fabrication draws from Japanese and South Korean mill capacity, with nickel and molybdenum spot volatility feeding through to boom and arm cost structures. Single-source vulnerability concentrates in selective catalytic reduction subsystem supply. Distribution runs through OEM-native dealer networks and emerging equipment-as-a-service platforms that consolidate aftermarket service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified aftertreatment subsystem supply constraints prop equipment pricing, as Tier 4 Final and Stage V compliance timelines harden faster than supplier qualification expands.
For Market Incumbents: Cement autonomous haulage system deployment in Australian iron ore pits to lock in labor cost arbitrage gains before sensor-fusion technology commoditizes. Deepen backward integration into telematics platform development to capture recurring service revenue streams and defend against emerging data-native entrants. For New Entrants and Emerging Players: Capture battery-electric prototype trial deployments in Beijing and Shanghai municipal demolition zones where night work permits hinge on zero-tailpipe compliance. Position through local assembly partnerships in Indonesia and Vietnam to reduce import duty exposure and access price-sensitive infrastructure corridor projects. For Investors and Strategic Acquirers: EPA-EU Stage V regulatory divergence is the leading indicator that multinational fleet standardization paralysis will create acquisition opportunities for retrofit certification specialists. Target mid-cap OEMs with established Stage V compliance pathways and underutilized autonomous system development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage System Deployment | Australian iron ore operators reduce labor intensity and safety incidents through sensor-fusion integration. |
| Battery-Electric Prototype Trials | Beijing and Shanghai municipal projects test zero-tailpipe configurations for night work permit eligibility. |
| Local Assembly Partnerships | Southeast Asian contractors access cost-engineered hydraulics with reduced import duty exposure. |
| Telematics Platform Integration | Predictive maintenance contracts consolidate aftermarket service relationships around data-rich uptime guarantees. |
| Stage V Certification Investment | European OEMs secure procurement eligibility under EU Green Deal public works tender requirements. |
Methodological Framework
Independent corroboration across maintenance directors at Australian mining operations, OEM procurement teams in Germany and Japan, and aftermarket service heads in North America underwrites the qualitative findings. Primary fieldwork combined structured interviews with fleet operators in Chile's Atacama Desert and India's infrastructure corridor builders with secondary validation from EPA enforcement bulletins, EU procurement directive databases, and customs trade records. Bottom-up equipment shipment tallies and top-down mineral extraction output projections triangulate market sizing.
Comparable-period anchoring to historical fleet replacement cycles and emission compliance phase-in timelines structured the projection horizon. Segmentation modeling spanned powertrain technology, operating weight class, end-use intensity, and regional regulatory cluster. CAGRs derived from equipment-hour demand elasticities tied to copper and lithium output targets, infrastructure appropriation cycles, and autonomous system adoption curves.
The model holds under steady emission compliance enforcement and stable mining commodity demand; deviation in battery energy density breakthroughs or synchronous global recession would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Earthmover Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Hydraulic Intensifiers Market