
 Snow Removal Market | 2026-2036
Snow Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Removal Market Intelligence
A divergence in capital intensity between large-scale equipment ownership and asset-light service contracting is reorganizing competitive dynamics. Integrated facility management firms like KBS Services leverage their scale to offer bundled solutions across multiple geographies. In contrast, specialized providers such as Tovar Snow Professionals and Semmer Landscape compete on operational depth and rapid deployment capabilities within specific regional markets.
Snow removal encompasses the mechanical and chemical clearing of snow and ice to maintain surface accessibility and safety. Mechanical methods utilize equipment like snow plows and multi-stage blowers, while chemical methods involve applying de-icing agents such as calcium chloride. Service contracts for commercial parking lots and critical roadways constitute the largest application segments. While municipal agencies remain a foundational end-user base, demand from facility management contractors is expanding significantly.
Regulatory frameworks increasingly influence operational choices and material selection. In the United States, the EPA provides guidance on chloride usage to mitigate environmental runoff, while in Canada, road salts are assessed under the Canadian Environmental Protection Act. European municipal authorities, particularly in Nordic countries, enforce strict rules on snow disposal and anti-icing chemical composition. Service providers must now balance investments in eco-friendly de-icing agents against the acquisition of more efficient mechanical clearing equipment.
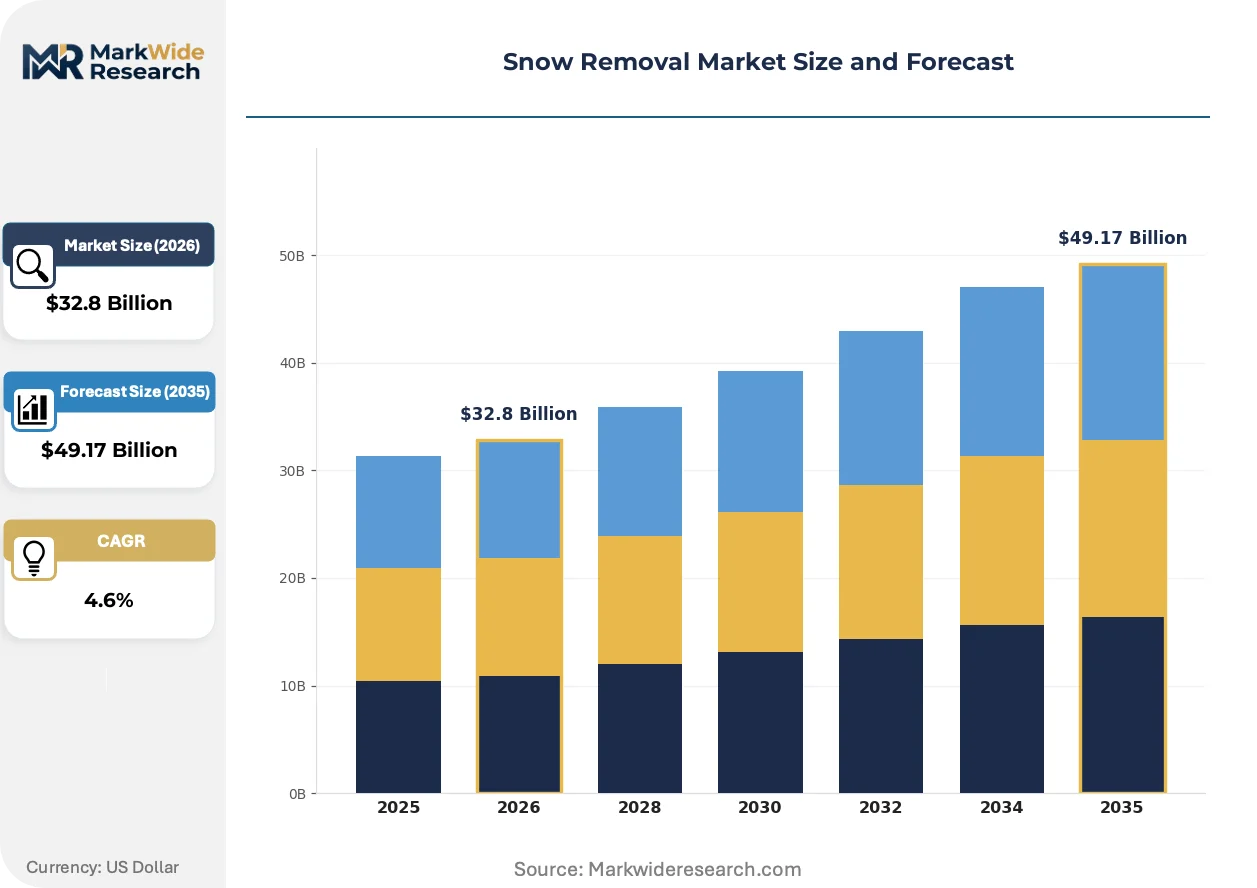
Market Dynamics
The competitive landscape is bifurcating between capital-intensive equipment owners and asset-light service providers. This structural shift is driven by large-scale clients like logistics firms and integrated facility managers demanding bundled, multi-regional service contracts that favor operational scale over localized specialization.
Growth Catalysts
- Supply Chain Continuity:Demand from logistics and e-commerce distribution centers for uninterrupted, 24/7 operations during winter weather events creates a consistent need for reliable, rapid-response snow and ice management services to prevent costly disruptions.
- Environmental Regulations:Stricter chloride runoff rules under frameworks like the US EPA's guidance and Canada's Environmental Protection Act are compelling municipalities and commercial clients to adopt higher-cost, eco-friendly de-icing agents, expanding the market for premium services.
- Commercial Real Estate Expansion:The development of large-scale commercial properties, including retail centers and corporate campuses in major transportation hubs across the United States and Germany, expands the addressable market for contracted snow removal services.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of bulk rock salt and specialty chemical de-icers like calcium chloride directly impact service provider margins, making long-term contract pricing difficult to stabilize.
- Eco-Agent Performance Gaps:Many environmentally-friendly de-icing alternatives exhibit reduced effectiveness at extremely low temperatures compared to traditional chlorides, limiting their application in colder North American and Nordic regions.
- Regulatory Fragmentation:Service providers operating across multiple jurisdictions face a complex and costly web of differing local and state-level regulations concerning snow disposal and chemical usage, hindering operational standardization.
Strategic Opportunities
- Predictive Analytics Integration:The development of software platforms that integrate hyperlocal weather forecasting with GPS fleet data allows providers to optimize crew deployment and material application, creating an opportunity for value-added, efficiency-focused service tiers.
- Renewable Energy Sector:The expansion of large-scale solar energy farms in snowy climates presents a new application for specialized mechanical clearing services to maintain panel efficiency and prevent structural damage from snow accumulation.
- Eastern European Expansion:Growing logistics and industrial infrastructure in countries like Poland and the Czech Republic creates an underpenetrated market for professional, contract-based snow management services beyond basic municipal clearing.
Industry Challenges
- Skilled Labor Scarcity:A persistent seasonal shortage of trained and certified operators for specialized equipment like large front-end loaders and multi-stage snow blowers constrains the capacity of service providers during peak demand periods.
- High Capital Intensity:The significant upfront investment required to acquire and maintain a modern fleet of reliable snow removal equipment acts as a major barrier to entry and growth for smaller, independent contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Removal Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Snow Plows, Snow Blowers, Salt Spreaders, Ice Scrapers, Snow Brushes Application: Residential Driveways, Commercial Parking Lots, Roadways, Industrial Facilities, Public Spaces End User: Municipal Agencies, Facility Management, Property Owners, Snow Removal Contractors, Logistics Companies Distribution Channel: Direct Sales, Online Retailers, Specialty Dealers, Rental Services, Wholesalers |
| Companies Covered | Tovar Snow Professionals, Hub's Landscaping Co., KBS Services, Perfect Lawn & Snow Removal, Bridgettes Landscaping and Snow Removal, Beverly Companies, Krueger Landscaping, Stanner Pave & Plow, Semmer Landscape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Removal Market Strategic Shifts & Innovations
Operational strategies are evolving around the dual pressures of environmental compliance and client demands for greater cost transparency. This is driving investment in technologies that optimize material use and service delivery, fundamentally changing how contracts are structured and performance is measured.
GPS-enabled sensors on plows and spreaders provide real-time data on surface conditions and material application rates. Large municipalities and facility management firms are adopting this technology to verify service level agreement compliance and audit contractor performance. This data-driven oversight is fragmenting the traditional service model, enabling more granular, performance-based contracts instead of fixed-fee seasonal agreements.
The EU's Water Framework Directive is indirectly pressuring member states to implement stricter controls on chloride runoff into surface waters. This regulatory push is forcing service providers to adopt alternative, less corrosive de-icing agents like potassium acetate. The trend is most advanced in Germany and Nordic countries, where providers balance investments in eco-friendly materials with more efficient mechanical clearing to reduce overall chemical use.
A consolidation of property services into bundled contracts is gaining traction among large commercial real estate owners. Rather than sourcing snow removal separately, clients are opting for single-source agreements that include landscaping and general site maintenance from integrated facility management providers. This shift is most visible in the United States and Canada, where national retail chains and corporate campus managers seek to simplify vendor management with year-round contracts.
Snow Removal Market Segmentation
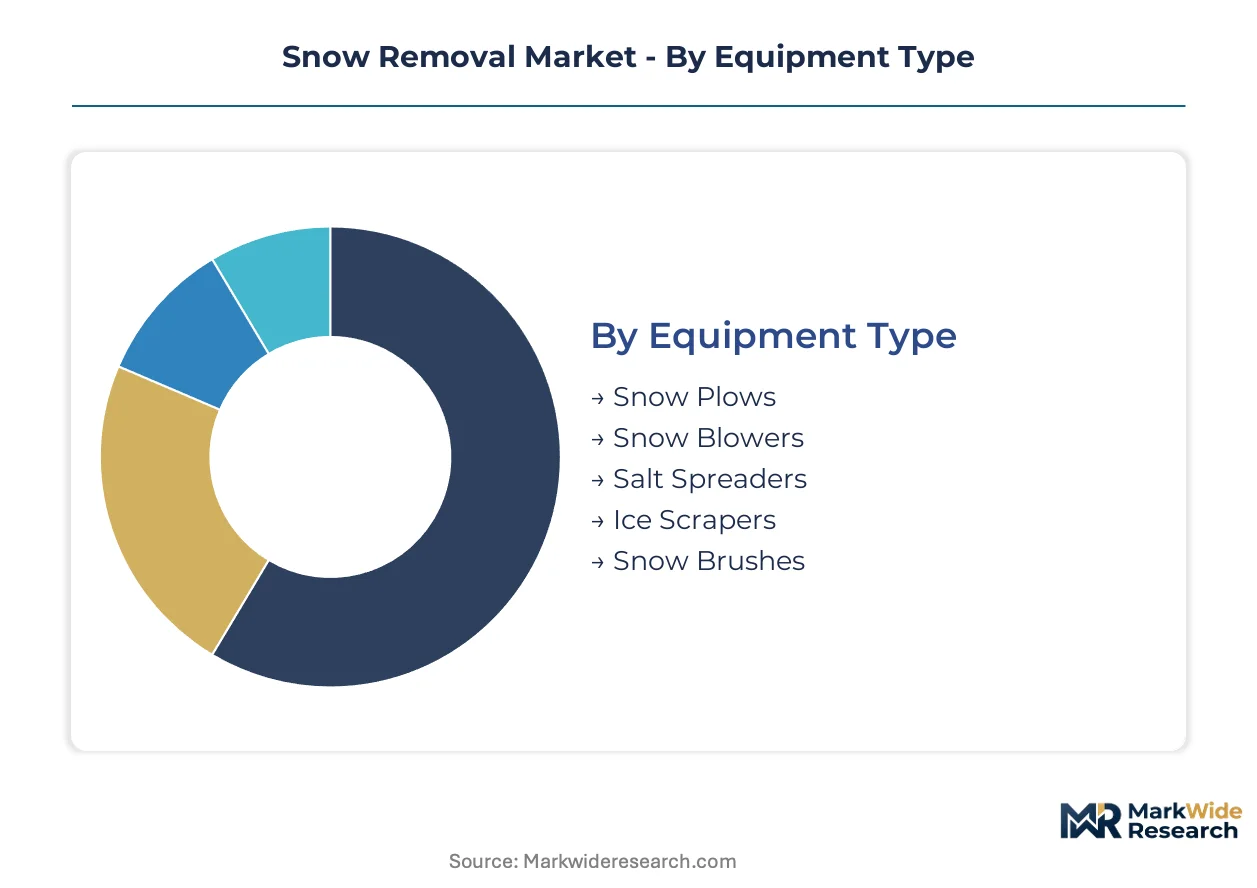
Understanding the Snow Removal Market through detailed segmentation reveals distinct operational models and demand patterns. This granular view helps service providers and equipment manufacturers align their strategies with specific client needs and regional climatic conditions. Segment analysis clarifies where investment generates optimal returns.
Equipment Type:
The geographic spread of snow removal equipment varies significantly, with heavy-duty machinery dominating regions experiencing severe winter weather and lighter tools prevalent in areas with moderate snowfall.
- Snow Plows:These robust attachments, designed for trucks and heavy machinery, efficiently clear large volumes of snow from roadways and expansive commercial properties. Demand for advanced plows with adjustable angles and materials concentrates in Canada and the northern United States.
- Salt Spreaders:Devices that evenly distribute de-icing agents like calcium chloride or eco-friendly alternatives across surfaces to prevent ice formation and aid snow melting. Municipalities and facility managers in Germany and the US Northeast prioritize spreaders capable of precise application to meet environmental regulations.
- Snow Blowers:Self-propelled or walk-behind machines that use an auger to collect snow and an impeller to discharge it, ideal for clearing driveways, sidewalks, and smaller commercial pathways. Property owners in areas like the US Midwest and Nordic countries rely on these for efficient residential clearing.
- Ice Scrapers:Manual or powered tools designed for breaking up and removing stubborn ice layers from various surfaces, often used for detailed clearing around entrances.
- Snow Brushes:Rotary brushes attached to vehicles for light snow removal or clearing fine layers of snow from delicate surfaces like solar panels or pedestrian areas.
Salt Spreaders commands the established base. The steepest expansion runs through Snow Blowers.
Application:
The volume of snow removal services required differs substantially across various applications, from high-traffic public infrastructure to individual property maintenance.
- Roadways:Critical public infrastructure requiring extensive mechanical clearing and de-icing to ensure safe passage for vehicles and emergency services. Municipal agencies in Canada and Germany allocate significant resources to maintaining arterial roads.
- Commercial Parking Lots:Large paved areas associated with retail centers, corporate campuses, and logistics hubs that demand prompt and thorough snow removal to maintain business operations and customer access. Facility management firms in the US prioritize these contracts for business continuity.
- Residential Driveways:Private access routes to homes, typically serviced by smaller equipment or manual labor, with demand concentrated among individual property owners.
- Industrial Facilities:Manufacturing plants, warehouses, and distribution centers requiring clear access for heavy machinery, deliveries, and employee safety, often with specialized needs around loading docks.
- Public Spaces:Parks, pedestrian walkways, and public squares that require snow and ice management to ensure public safety and accessibility, often managed by municipal crews.
Roadways represent the largest application segment. Commercial Parking Lots are expanding most quickly.
End User:
The maturity of procurement processes and service expectations varies widely among different end-user groups, influencing contract structures and technology adoption.
- Municipal Agencies:Government entities responsible for public infrastructure maintenance, including roads, sidewalks, and public facilities, often relying on a combination of in-house crews and contracted services. These agencies in the United States and European Union increasingly demand eco-friendly de-icing solutions.
- Logistics Companies:Enterprises focused on supply chain management and transportation, requiring uninterrupted access to distribution centers and freight routes to prevent costly operational delays. These companies in Germany and Canada seek rapid-response, 24/7 service agreements.
- Facility Management:Firms that manage and maintain commercial and institutional properties, bundling snow removal with other services like landscaping and general maintenance. This segment drives demand for integrated, multi-regional service contracts.
- Property Owners:Individual homeowners or small business owners who procure snow removal services for their private properties, often on an ad-hoc or seasonal contract basis.
- Snow Removal Contractors:Specialized businesses providing snow and ice management services to various clients, from residential to commercial, often acting as subcontractors for larger firms.
Municipal Agencies form a foundational end-user base. Logistics Companies are demonstrating significant acceleration in demand.
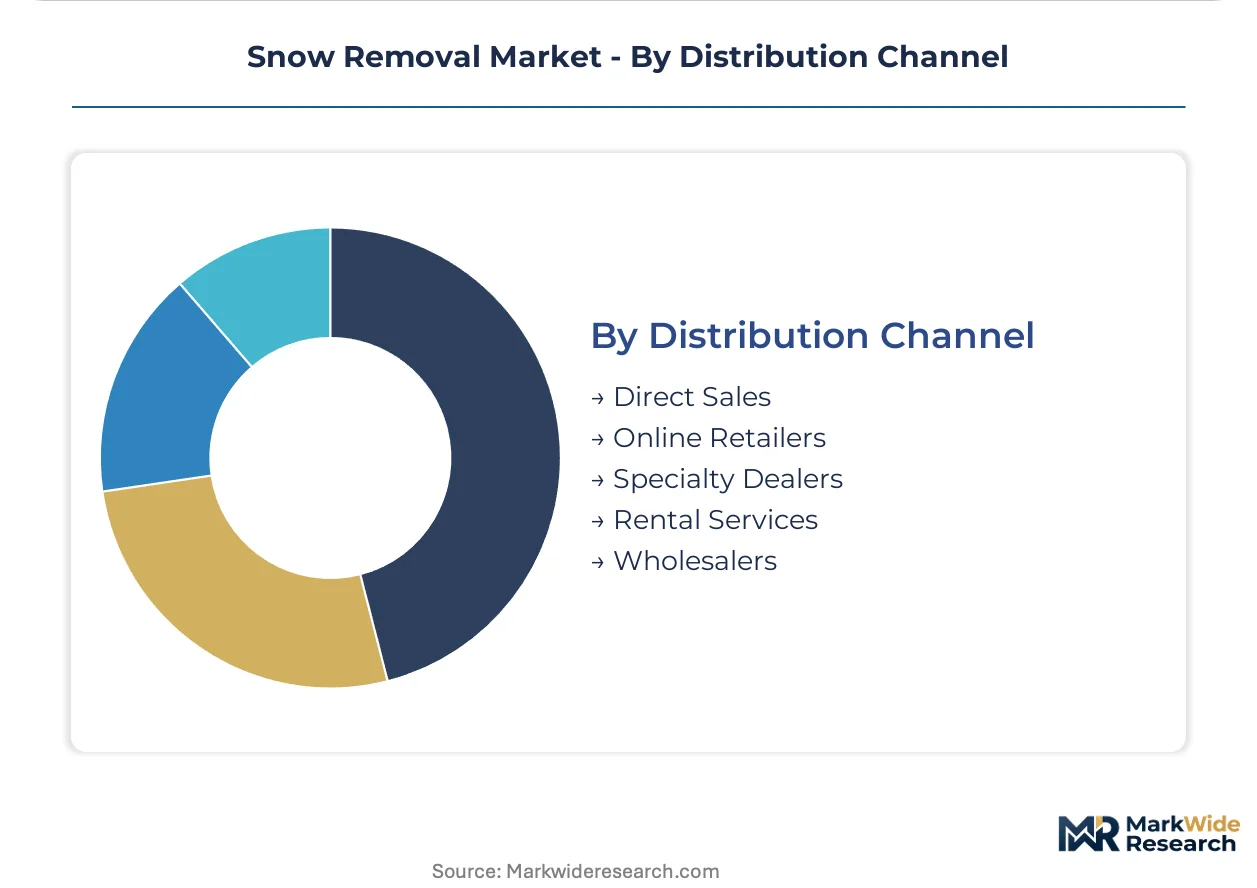
Distribution Channel:
The concentration of supply within different distribution channels reflects the diverse needs of buyers, from large-scale equipment procurement to consumer-level purchases.
- Direct Sales:Manufacturers selling equipment or services directly to large commercial clients or municipal agencies, facilitating custom solutions and bulk purchasing agreements. This channel dominates for heavy-duty snow plows and large salt spreaders.
- Specialty Dealers:Retailers focusing exclusively on outdoor power equipment, including snow removal machinery, offering expert advice, maintenance, and parts. These dealers serve a critical role for professional contractors and high-end residential users.
- Online Retailers:E-commerce platforms offering a wide range of snow removal tools, from small snow blowers to de-icing agents, catering primarily to individual property owners and small businesses.
- Rental Services:Companies providing temporary access to snow removal equipment, often utilized by contractors for peak demand periods or by property owners for infrequent use.
- Wholesalers:Distributors selling bulk quantities of de-icing chemicals and basic snow removal tools to smaller retailers, hardware stores, and service providers.
Direct Sales remains a significant channel for major equipment. Online Retailers are gaining market traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in snow removal services exhibits asymmetry, with higher service premiums in densely populated North American urban centers compared to more cost-sensitive Eastern European markets. This divergence influences investment strategies and service delivery models across different geographies. Environmental regulations and logistical demands primarily shape regional market dynamics.
United States
Logistics firms drive demand for uninterrupted supply chain operations across the United States. The EPA guides chloride usage, compelling providers to invest in eco-friendly de-icing agents. Commercial real estate expansion in hubs like Chicago expands the market for contracted services.
Canada
Canadian demand focuses on supply chain continuity for critical transportation hubs during severe winter weather. The Canadian Environmental Protection Act assesses road salts, influencing de-icing material selection. Major cities like Toronto require extensive mechanical clearing and de-icing for arterial roads.
Germany
Commercial property development fuels demand for professional snow removal services throughout Germany. The EU's Water Framework Directive pressures municipal authorities to enforce stricter controls on chloride runoff. Cities such as Munich balance eco-friendly de-icing with efficient mechanical clearing for public areas.
Sweden
Eco-friendly de-icing agents and stringent snow disposal rules characterize the Swedish snow removal market. European municipal authorities enforce strict anti-icing chemical composition rules. Stockholm and other urban centers prioritize public safety and accessibility through advanced snow and ice management.
Poland
Growing logistics and industrial infrastructure in Poland creates an underpenetrated market for professional, contract-based snow management services. Local regulations focus on environmental impact, pushing for more sustainable practices. Industrial facilities around Warsaw require clear access for heavy machinery and deliveries.
Snow Removal Market Key Industry Players
Concentration sits with integrated facility management firms capable of delivering bundled solutions across multiple geographies, driven by large clients demanding multi-regional service contracts. The competitive landscape bifurcates between capital-intensive equipment owners and asset-light service providers, reorganizing traditional competitive dynamics. Strategic archetypes include large-scale integrators focused on operational scale and specialized regional operators competing on operational depth. Dominant competitive moves involve portfolio diversification into adjacent property services and strategic partnerships to expand geographic reach and service capabilities.
Integrated facility management firms, exemplified by KBS Services, represent the archetype of scale-driven operations, leveraging extensive networks to offer bundled solutions across multiple client sites. In contrast, specialized regional providers such as Tovar Snow Professionals and Semmer Landscape, both US-based firms, occupy a position focused on operational depth and rapid deployment capabilities within specific local markets. These companies anchor the segment of specialized service delivery, contrasting with larger, more diversified players that prioritize multi-regional contract aggregation and vendor simplification.
| Leading Market Players |
|---|
| Tovar Snow Professionals |
| Hub's Landscaping Co. |
| KBS Services |
| Perfect Lawn & Snow Removal |
| Bridgettes Landscaping and Snow Removal |
| Beverly Companies |
| Krueger Landscaping |
| Stanner Pave & Plow |
| Semmer Landscape |
| Others |
Cost & Logistics Intelligence
Large-scale equipment ownership and asset-light service contracting drive economies of scale, shaping supply concentration and influencing price floors across the snow removal market.
Pricing Analysis
Configured-to-order service agreements command premium pricing compared to standard seasonal contracts for snow removal. The market relies on contract-based long-term agreements for commercial clients, with project-based pricing for ad-hoc residential needs. Price differentiation arises from rapid deployment capabilities and the use of eco-friendly de-icing agents. Cost compression in basic services stems from intense regional competition, making property owners highly price-sensitive, while logistics companies prioritize uninterrupted service.
Supply Chain Analysis
Seasonal inventory fluctuations for de-icing agents and equipment parts dictate lead times for snow removal service providers. Geographic supply for specialized equipment and chemical de-icers concentrates in the United States, Canada, and Germany. Raw material dependencies include bulk rock salt, calcium chloride, and specialized equipment components. Input cost volatility directly impacts service provider margins, posing a structural risk, and distribution runs through specialty dealers, direct sales, and wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
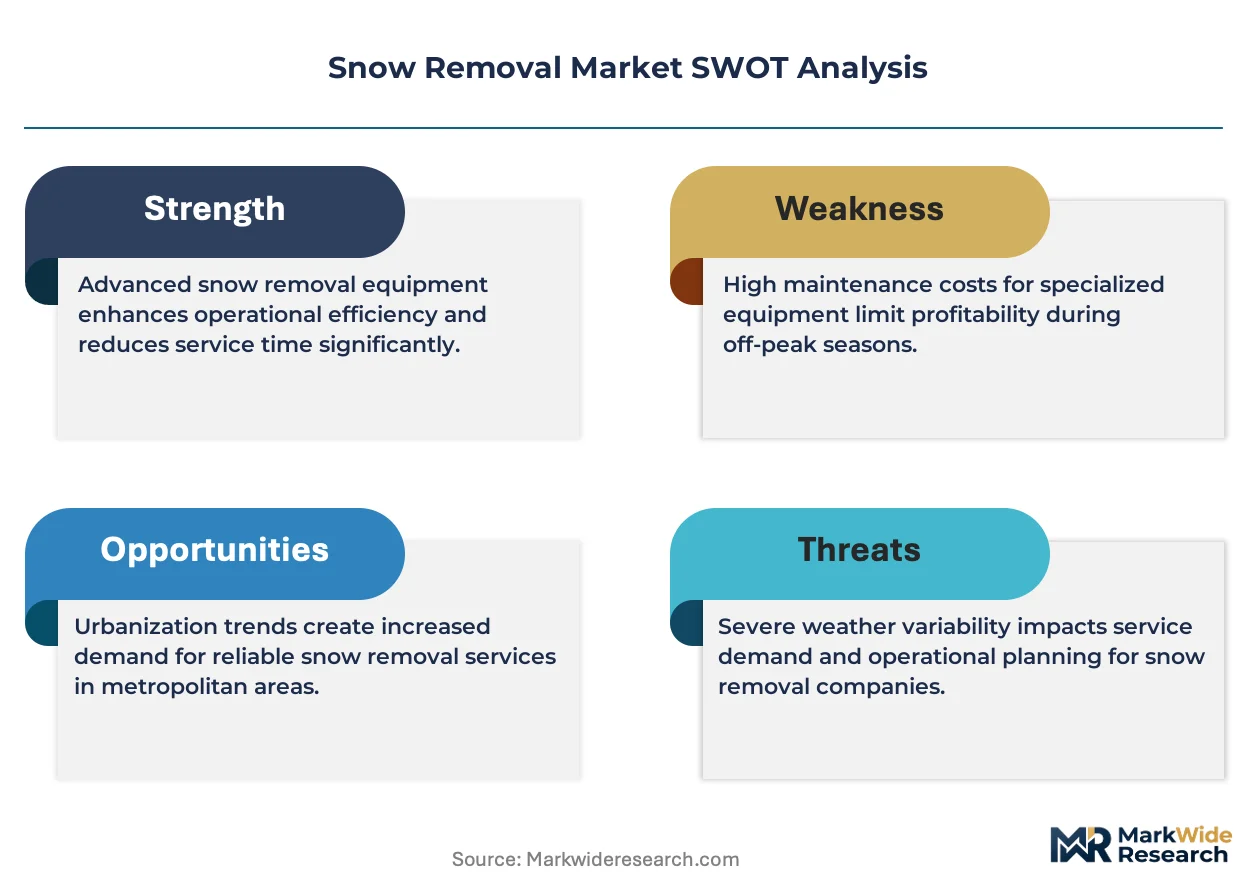
The snow removal market is experiencing high-growth disruption, driven by the integration of predictive analytics for optimized service delivery.
For Market Incumbents:Secure long-term contracts with large logistics and facility management firms to leverage existing operational scale. Invest in eco-friendly de-icing agents and upgrade to more efficient mechanical clearing equipment. This mitigates the threat of stricter environmental regulations like chloride runoff rules. Certification investment in sustainable practices enhances client trust and compliance.
For New Entrants and Emerging Players:Anchor in underpenetrated regional markets, particularly in Eastern Europe, to establish a foothold. Target Poland's growing logistics infrastructure and specialized solar farm clearing services as white-space opportunities. Small commercial properties and industrial facilities represent the most penetrable segments. Offer value-added, efficiency-focused service tiers through predictive analytics as a go-to-market angle.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors integrated facility management firms capable of bundling diverse property services. Long-term viability rests on adapting to regulatory shifts and technological advancements over the next decade. Seek regional specialists with strong operational depth and rapid deployment capabilities as acquisition targets. The rate of adoption of GPS-enabled sensors for performance-based contracts signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Adjacent Property Services | Bundling services like landscaping and maintenance simplifies vendor management for large commercial clients. |
| Investment in Eco-Friendly De-Icing Agents | Compliance with stricter environmental regulations, such as the EU's Water Framework Directive, becomes critical. |
| Integration of Predictive Analytics Platforms | Optimizing crew deployment and material application enhances efficiency and cost transparency for clients. |
| Strategic Partnerships for Geographic Expansion | Accessing new markets like Eastern Europe or specific US transportation hubs expands service reach. |
| Acquisition of Specialized Regional Operators | Gaining operational depth and rapid deployment capabilities within specific local markets strengthens competitive advantage. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors qualitative findings in this snow removal market analysis. Primary research included discussions with facility management executives, logistics operations managers, and municipal agency procurement officers. Secondary data sources comprised government environmental reports, commercial real estate development surveys, and industry association publications. Bottom-up and top-down triangulation ensured data consistency.
Sensitivity analysis across various economic and climatic scenarios informs the forecast framework for the snow removal market. A quantitative modeling approach was employed over the projection horizon. Segmentation dimensions modeled include equipment type, application, end user, distribution channel, and regional climatic severity. Compound annual growth rates were derived from historical trends, using regional snowfall averages and commercial real estate development pipelines as key inputs.
Material uncertainties — including extreme weather pattern shifts and unforeseen regulatory changes — sit outside the modeled envelope for snow removal market forecasts. Forecasts reflect assumptions regarding economic stability and technological adoption, with input cost volatility and skilled labor scarcity representing specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Multi Attachment Loaders Market