
 Automatic Bending Machine Market | 2026-2036
Automatic Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Bending Machine Market Analysis
The capital-intensity divergence between full-system integrators and component suppliers is rotating competitive advantage toward players with captive servo-electric technology. TRUMPF GmbH + Co. KG leverages in-house drive engineering to command premium positioning in fully automated installations. Amada Co., Ltd. anchors its footprint across Asia-Pacific through dedicated regional production facilities. LVD Company nv differentiates via open-architecture CNC platforms that integrate with third-party software ecosystems.
An automatic bending machine is a numerically controlled fabrication system that applies programmable force through servo-electric, hydraulic, or pneumatic actuators to deform metal sheets, pipes, or profiles to specified angles and radii, typically achieving repeatability within 0.01 degrees for aerospace-grade components. Electric bending machines now lead technology substitution as manufacturers target energy efficiency and reduced hydraulic fluid maintenance in metal fabrication operations. CNC controls dominate the technology dimension while fully automated cells capture expanding margin pools in high-volume automotive and HVAC production lines.
ISO 9001 quality management standards and CE marking requirements under EU machinery directives shape product certification and market access for European-bound equipment, while OSHA machine guarding regulations in the United States mandate specific safety interlocks and light-curtain configurations. Japan's METI industrial efficiency guidelines and China's GB standards for metalworking machinery add further compliance layers for exporters. Stakeholders must monitor how evolving carbon-border adjustments and regional content rules reshape sourcing decisions for servo motors and control systems.
Market Dynamics
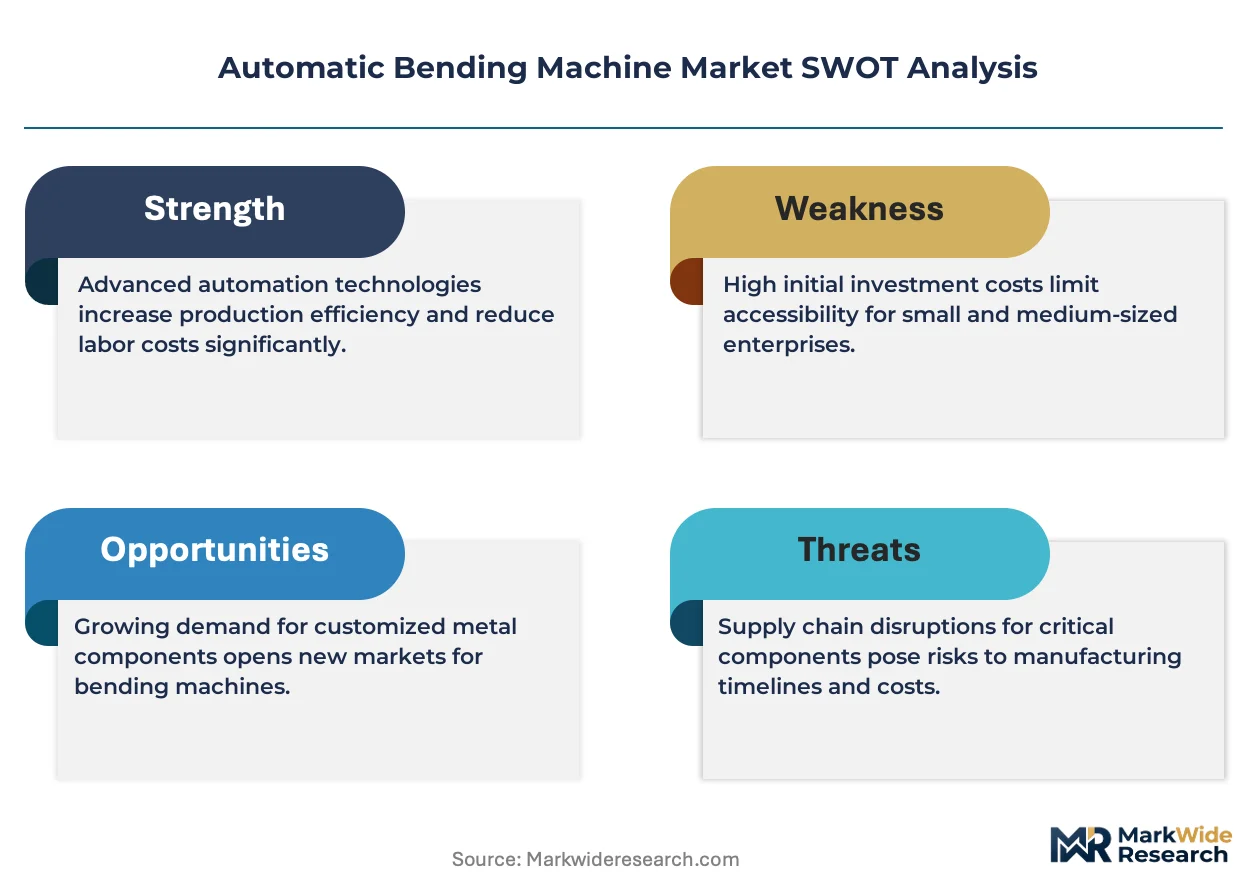
Servo-electric actuation is displacing hydraulic systems across high-precision metal fabrication, compressing maintenance cycles and energy consumption while elevating capital requirements for equipment upgrades.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory safety interlocks and control reliability standards are accelerating replacement of legacy manual equipment across European metalworking facilities.
- Automotive lightweighting mandates:OEMs in Germany, Japan, and the United States are specifying electric bending cells for aluminum and high-strength steel processing to meet emissions thresholds.
- CNC open-architecture platforms:Software ecosystems enabling third-party CAD/CAM integration are reducing programming time and expanding machine utilization rates in job shop environments.
Market Restraints
- Rare-earth magnet supply concentration:Servo motor production depends on neodymium processing concentrated in China, exposing equipment manufacturers to input cost volatility and export restriction risk.
- Technical limitation in thick-wall pipe bending:Electric actuators face torque constraints above 25mm wall thickness in carbon steel, preserving hydraulic dominance in heavy structural applications.
- OSHA machine guarding compliance:Retrofitting existing installations with light-curtain and two-hand control systems imposes substantial downtime and engineering costs for US fabricators.
Strategic Opportunities
- India's PLI scheme for capital goods:Production-linked incentives for precision manufacturing equipment are attracting regional assembly investments to serve South Asian demand.
- Battery enclosure fabrication:Electric vehicle manufacturers require novel aluminum extrusion bending for thermal management housings, creating application-specific equipment demand.
- Digital twin convergence with IoT sensors:Real-time bend angle verification and predictive maintenance integration are opening premium service revenue streams for control system vendors.
Industry Challenges
- Servo-electric technician scarcity:Maintenance and programming of high-precision drive systems requires specialized training that vocational programs in Germany and Japan have not scaled to match deployment rates.
- ISO 9001 certification timeline:Aerospace and medical device suppliers face 12-18 month validation cycles for new bending cell qualifications, delaying revenue recognition on equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Bending Machine Market |
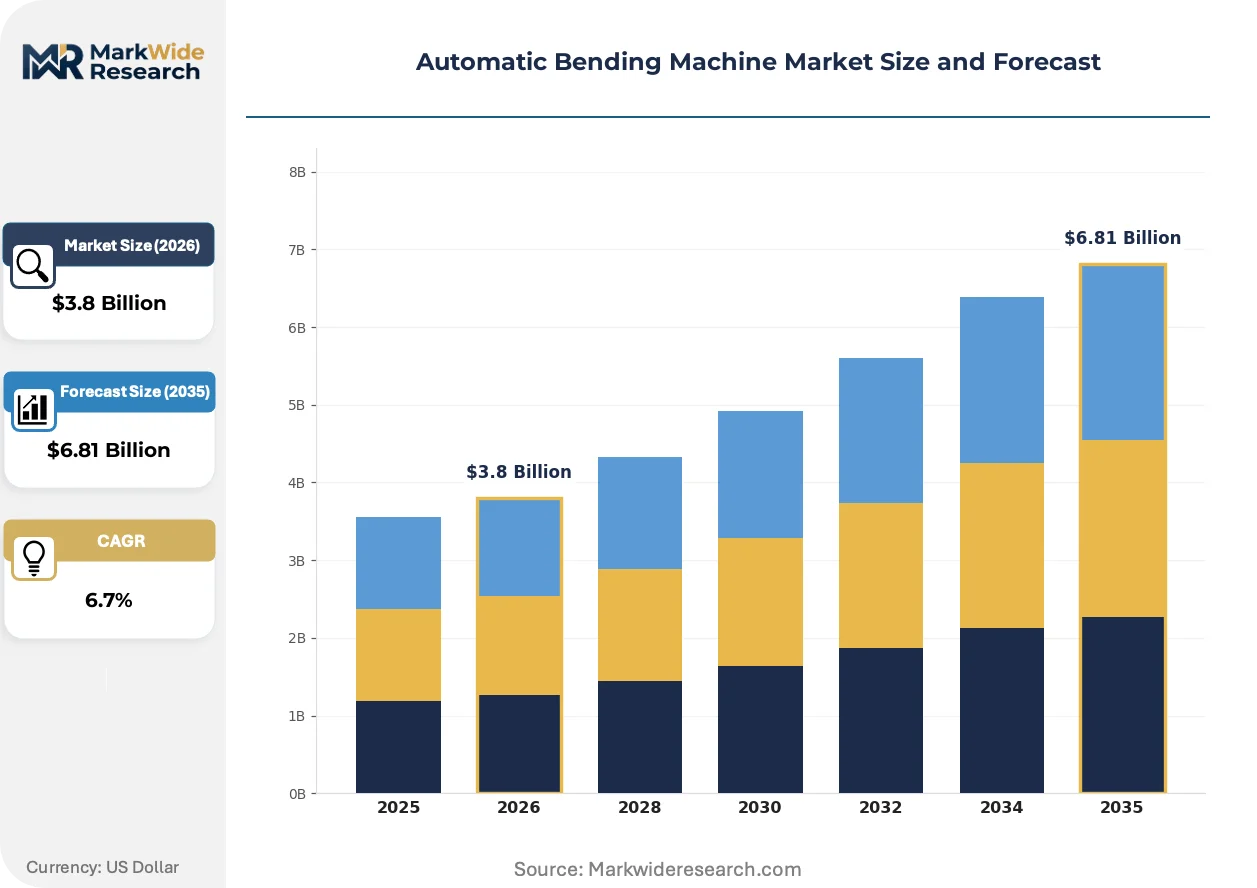
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Pneumatic, Mechanical End User: Aerospace, Automotive Manufacturers, Construction, HVAC Technology: CNC, Manual, Semi-Automatic, Fully Automated Application: Metal Fabrication, Pipe Bending, Sheet Bending, Profile Bending |
| Companies Covered | Amada Co., Ltd., TRUMPF GmbH + Co. KG, Bystronic Laser AG, LVD Company nv, Salvagnini Italia S.p.A., Prima Industrie S.p.A., BLM Group, Soco Machinery, HACO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Bending Machine Market Emerging Trajectories
Control architecture and actuation technology are fragmenting into parallel development tracks, with electric precision systems diverging from heavy-duty hydraulic platforms rather than converging on unified designs.
Servo-electric press brake technology is bifurcating the installed base. High-volume automotive stamping operations in Stuttgart and Detroit are specifying all-electric systems for energy recovery and repeatability below 0.01 degrees. The structural consequence is compressing aftermarket hydraulic service revenue while expanding software and controls margin pools for integrated suppliers.
REACH restrictions on hydraulic fluid formulations are forcing European fabricators to eliminate mineral oil-based systems by 2027. Equipment lessors in Germany and Italy are accelerating write-downs of hydraulic-heavy portfolios. Metal service centers are responding by specifying electric alternatives in new capex cycles to avoid stranded asset risk.
Buyer consolidation among tier-one automotive stamping suppliers is compressing equipment procurement cycles. Volkswagen Group and Toyota Motor are centralizing bending cell specifications across regional subsidiaries, displacing distributed purchasing authority previously held at plant level. This concentration is most visible in Bavaria and Aichi Prefecture, where single-source framework agreements now cover multi-year equipment deployment.
Automatic Bending Machine Market Segmentation
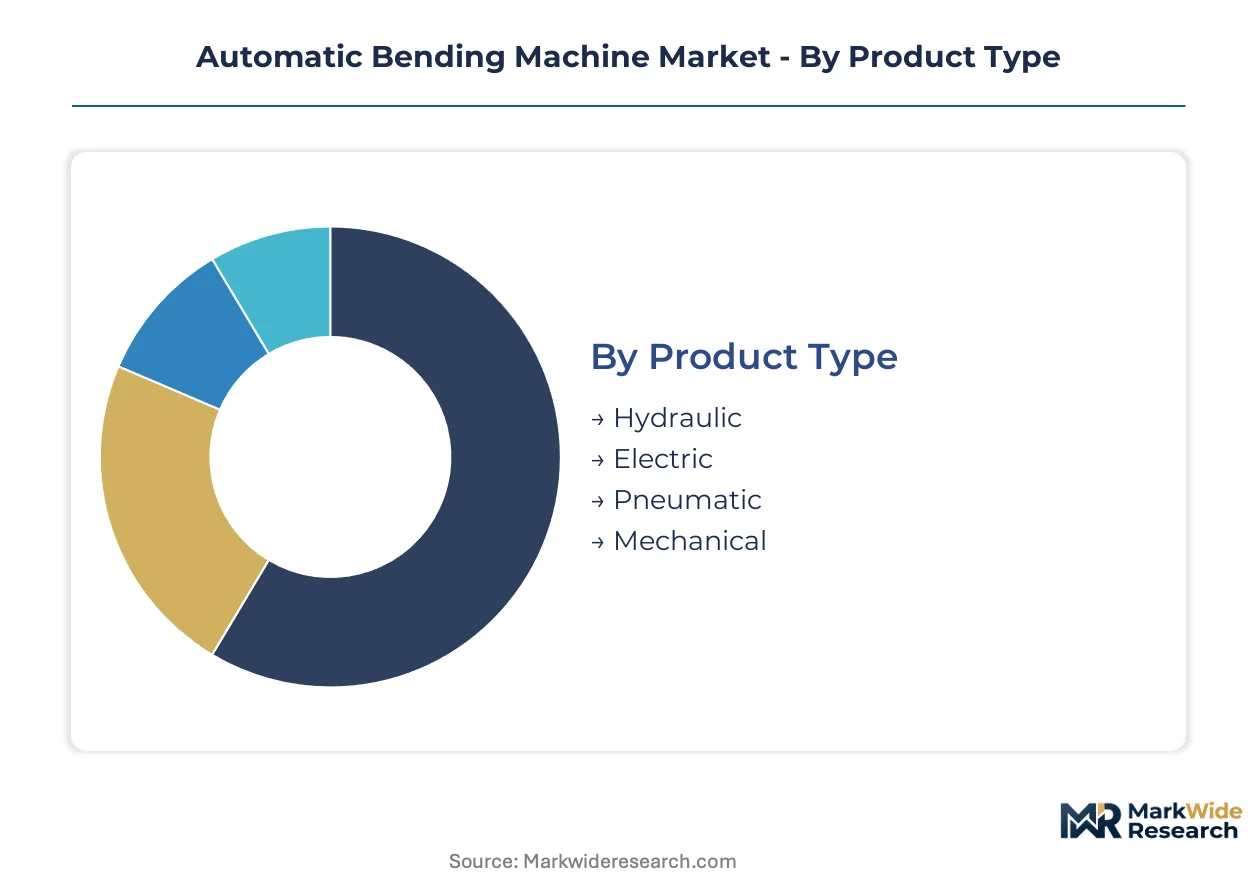
Segmentation in automatic bending machines reveals how technology substitution and end-use specialization concentrate margin pools. Equipment vendors align R&D spending and distribution capacity against these fault lines to defend pricing power and service attach rates.
Product Type:
Margin pools have migrated decisively toward electric architectures as energy efficiency and maintenance reduction command premium positioning in replacement cycles.
- Electric:Servo-electric actuation delivers precision within 0.01 degrees through closed-loop position feedback, eliminating hydraulic fluid handling and enabling energy recovery during deceleration. Automotive stamping operations in Germany and Japan specify these systems for aluminum processing under emissions mandates, compressing payback periods against rising electricity tariffs.
- Hydraulic:Fluid-power systems maintain dominance in thick-wall carbon steel above 25mm wall thickness where torque requirements exceed electric motor scaling limits. Infrastructure and heavy structural fabricators in the United States retain hydraulic fleets for pipe bending applications despite higher maintenance burdens.
- Pneumatic:Compressed-air actuation serves low-force bending in thin-gauge sheet metal for HVAC ductwork and light enclosure fabrication where capital constraints dominate specification decisions.
- Mechanical:Flywheel and clutch mechanisms persist in emerging market job shops with limited automation requirements and minimal CAD/CAM integration needs.
Hydraulic systems hold installed capacity across legacy metalworking facilities. Electric configurations are rotating up the share rankings as REACH deadlines force fluid elimination.
End User:
Application complexity and certification requirements stratify this category, with aerospace and medical device suppliers absorbing the steepest qualification timelines and service premiums.
- Automotive Manufacturers:OEMs centralize procurement of electric bending cells for aluminum and high-strength steel lightweighting programs, specifying open-architecture CNC platforms that integrate with existing CAD/CAM workflows across multi-plant deployments.
- Aerospace:Tier-one suppliers demand repeatability certifications traceable to NIST standards for titanium and inconel forming, with ISO 9001 validation cycles extending equipment revenue recognition over 12-18 months.
- Construction:Structural steel fabricators prioritize hydraulic force capacity for beam and column bending in commercial building projects, accepting lower precision for throughput economics.
- HVAC:Ductwork and thermal management housing producers specify medium-duty electric systems for galvanized sheet forming, with volume procurement concentrated among regional metal service centers.
Automotive Manufacturers anchor current demand volumes. Aerospace is climbing the fastest as commercial aircraft production rates recover and defense spending accelerates precision forging requirements.
Technology:
Control architecture sophistication determines aftermarket revenue potential, with fully automated cells capturing multi-year service contracts and software subscription streams.
- CNC:Numerical control platforms dominate mid-market and high-volume segments, with open-architecture systems from LVD and Amada enabling third-party CAM integration that reduces programming time in job shop environments.
- Fully Automated:Robotic part handling and automatic tool change systems command premium positioning in automotive and appliance manufacturing, where labor cost arbitrage and throughput consistency justify capital intensity.
- Semi-Automatic:Operator-assisted loading with automated bend sequencing serves mixed-model production in contract fabrication shops where batch sizes fluctuate weekly.
- Manual:Hand-cranked and foot-pedal systems persist in maintenance departments and educational institutions, with minimal margin contribution beyond replacement part sales.
CNC controls retain the broadest installed base. Fully Automated is gaining share fastest as labor scarcity and quality consistency requirements intensify across German and Japanese manufacturing clusters.
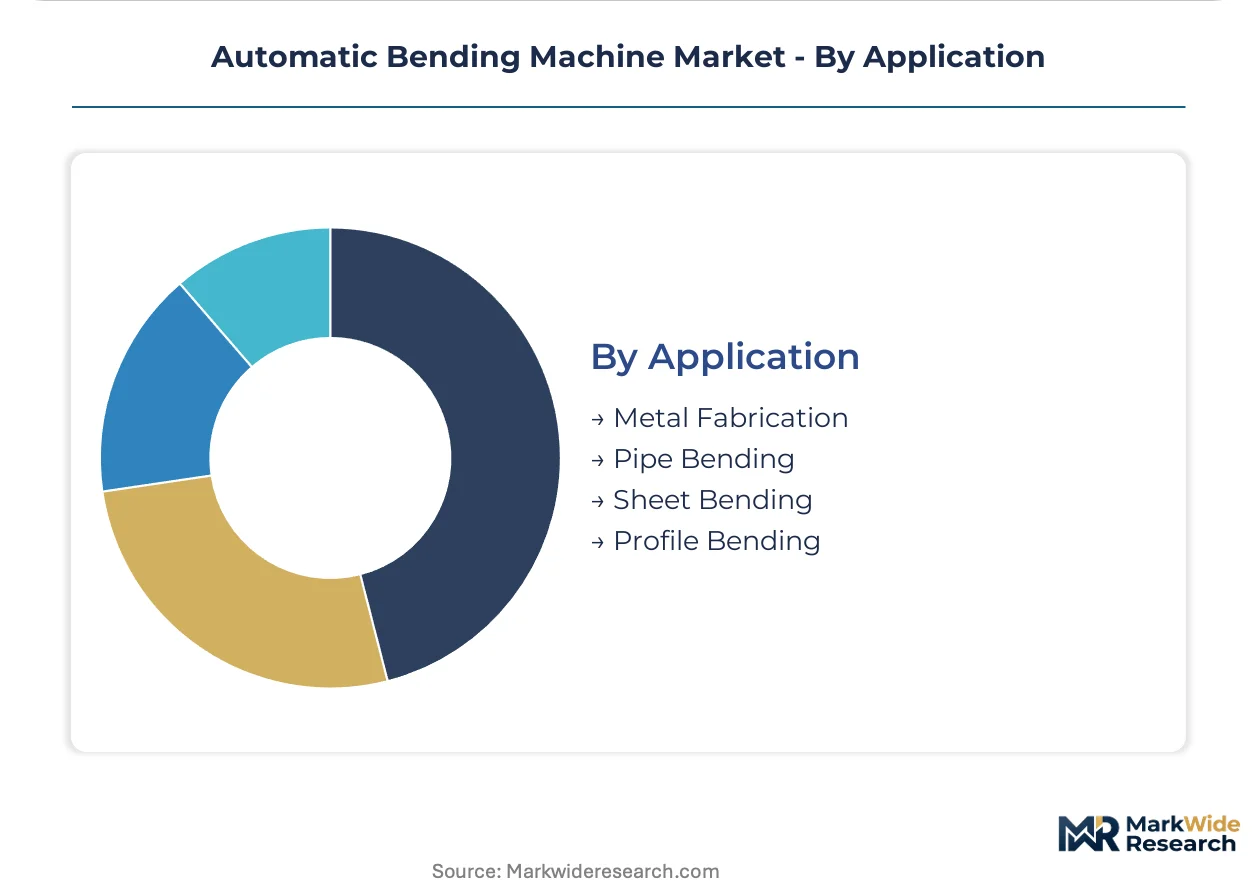
Application:
Material form factor and deformation mechanics segment this dimension, with pipe bending commanding specialized tooling investments that create switching costs for incumbent suppliers.
- Sheet Bending:Press brake operations for flat stock deformation represent the largest equipment population, serving general fabrication, enclosure manufacturing, and appliance production with standardized V-die configurations.
- Pipe Bending:Mandrel and rotary draw systems for tubular stock serve automotive exhaust, aerospace fluid lines, and energy infrastructure, requiring application-specific tooling libraries that lock in supplier relationships.
- Metal Fabrication:General-purpose job shops deploy multi-axis systems capable of mixed sheet, plate, and light structural processing to maximize utilization across fragmented customer demand.
- Profile Bending:Roll and stretch-forming systems for extruded aluminum and steel sections serve architectural metalwork and electric vehicle battery enclosure fabrication, with thermal management housing demand expanding fastest.
Sheet Bending maintains the deepest installed capacity. Profile Bending is rotating up the share rankings as electric vehicle battery platform architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German and Japanese fabricators prioritize electric precision systems for automotive lightweighting, while U.S. structural steel producers retain hydraulic force capacity for heavy-wall applications.
United States
Automotive stamping operations in Detroit and appliance manufacturers in the Midwest specify electric bending cells for aluminum processing under NHTSA emissions mandates. OSHA machine guarding regulations impose retrofit costs on legacy installations. The Southeast manufacturing corridor, particularly Georgia and Tennessee, attracts new capacity for electric vehicle battery enclosure fabrication.
Germany
Stuttgart-based OEMs centralize procurement of fully automated bending cells across multi-plant networks. REACH restrictions on hydraulic fluids force mineral oil elimination by 2027. Bavarian metal service centers accelerate write-downs of hydraulic-heavy portfolios to avoid stranded asset exposure.
Japan
Aichi Prefecture automotive suppliers absorb ISO 9001 validation cycles extending 12-18 months for aerospace-grade titanium forming. METI industrial efficiency guidelines shape equipment specification standards. Kansai region fabricators face technician scarcity for servo-electric maintenance despite deployment acceleration.
China
GB standards for metalworking machinery add compliance layers for domestic and export-bound equipment. Yangtze River Delta fabricators process rare-earth magnets for servo motor production, creating input cost exposure. Pearl River Delta metal service centers specify medium-duty electric systems for HVAC ductwork and enclosure manufacturing.
India
PLI scheme production-linked incentives attract regional assembly investments for precision manufacturing equipment. Maharashtra and Gujarat job shops deploy CNC open-architecture platforms to reduce programming time across fragmented customer demand. Tamil Nadu automotive clusters specify electric bending cells for aluminum extrusion processing.
Automatic Bending Machine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive servo-electric technology separating premium positioning from commodity competition. The upper tier commands multi-year service contracts through fully automated cell integration. Strategic archetypes include full-system integrators with in-house drive engineering, regional production specialists with dedicated Asia-Pacific facilities, and open-architecture control vendors with third-party software ecosystems. Competitive moves concentrate on M&A for servo motor technology access and geographic expansion through regional assembly partnerships.
Within the integrated leader tier, TRUMPF GmbH + Co. KG and Amada Co., Ltd. exemplify divergent geographic anchoring strategies. TRUMPF represents European-centric captive engineering with premium positioning in fully automated installations. Amada occupies a position as Asia-Pacific production specialist with dedicated regional manufacturing footprint. LVD Company nv sits within the open-architecture tier, anchoring software ecosystem differentiation that reduces programming friction in mixed-model job shops.
| Leading Market Players |
|---|
| Amada Co., Ltd. |
| TRUMPF GmbH + Co. KG |
| Bystronic Laser AG |
| LVD Company nv |
| Salvagnini Italia S.p.A. |
| Prima Industrie S.p.A. |
| BLM Group |
| Soco Machinery |
| HACO |
| Others |
Supply Flow & Price Mechanics
Servo-electric actuator substitution for hydraulic systems is redrawing supply geography toward rare-earth processing clusters while compressing aftermarket service margins and elevating upfront capital requirements for fabricators.
Pricing Analysis
Long-term framework agreements dominate procurement between tier-one automotive OEMs and integrated system suppliers, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales bundling. Price differentiation stems from ISO 9001 traceability tiers and captive servo motor production, with premium electric cells commanding substantial uplifts over hydraulic alternatives. Cost compression in mid-market electric configurations is intensifying because Chinese rare-earth export quotas feed input volatility. Job shops and regional metal service centers exhibit highest price sensitivity, while aerospace tier-one suppliers absorb premiums for NIST-traceable repeatability.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Japanese automotive stamping operations, though strategic stockpiling of neodymium magnets and servo drives is expanding among European integrators facing REACH compliance deadlines. Manufacturing concentration centers on China for rare-earth magnet processing, Germany for precision drive engineering, and Japan for CNC control systems. Raw material dependencies include neodymium-iron-boron magnets, high-grade steel alloys, and semiconductor components for motion controllers. Single-source vulnerability in Chinese rare-earth supply creates structural exposure. Distribution runs through authorized dealer networks with regional service hubs, supplemented by direct OEM relationships for fully automated cell deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic bending machine demand sits in early-cycle expansion as electric vehicle battery enclosure fabrication and REACH-mandated hydraulic replacement create simultaneous adoption tailwinds across automotive and general fabrication segments.
For Market Incumbents: Shield installed base revenue by accelerating captive servo motor production to offset Chinese rare-earth supply volatility, while embedding predictive maintenance software subscriptions to capture recurring service streams. Consolidate position through selective acquisition of regional CNC control specialists in India and Southeast Asia. Prioritize ISO 9001 certification pre-investment to compress aerospace qualification timelines. For New Entrants and Emerging Players: Differentiate on open-architecture control platforms that integrate with third-party CAD/CAM ecosystems, targeting mixed-model job shops in India's Maharashtra and Gujarat clusters where programming friction constrains utilization. White-space opportunity concentrates in battery enclosure profile bending for electric vehicle thermal management housings, with regional assembly partnerships offering lowest-capital market entry. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors vertically integrated mid-cap specialists with captive drive engineering and established automotive OEM relationships. Long-term viability over the next decade hinges on software-enabled service revenue attach rates rather than equipment shipment volumes. Acquisition target archetype: electric press brake specialists with regional production footprint in Asia-Pacific. Signal to watch is centralization of procurement authority at Volkswagen Group and Toyota Motor level versus plant-level purchasing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Servo Motor Production | Backward integration into rare-earth magnet supply chains insulates margins from Chinese export restriction volatility. |
| Open-Architecture CNC Platform Development | Third-party software ecosystem integration reduces programming friction and expands addressable job shop base. |
| Regional Assembly Partnership in India | PLI scheme incentives lower capital barriers for serving South Asian precision manufacturing demand growth. |
| Predictive Maintenance Service Launch | IoT sensor integration enables recurring software subscription revenue streams alongside equipment sales. |
| ISO 9001 Pre-Certification Investment | Compressed aerospace qualification timelines accelerate revenue recognition on titanium and inconel forming cells. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers at automotive stamping operations, aftermarket service heads at metal fabrication facilities, OEM procurement teams specifying bending cells, and maintenance directors overseeing legacy hydraulic fleets, then refined through secondary validation against SEC filings from integrated equipment manufacturers, German mechanical engineering association production statistics, Japanese METI industrial efficiency reports, and EU machinery directive compliance databases, with bottom-up equipment shipment tallies triangulated against top-down manufacturing value-added estimates.
Variance decomposition across the projection horizon isolates volume drivers by actuation technology, end-use industry concentration, automation tier, and regional regulatory cluster, with segment-level CAGRs derived from equipment replacement cycle analysis and technology substitution elasticity modeling. Industry-specific forecast inputs include REACH hydraulic fluid phase-out compliance schedules and electric vehicle platform architecture proliferation rates for battery enclosure demand.
Material uncertainties — rare-earth export restriction severity, carbon-border adjustment implementation scope, and servo-electric technician training program scaling — sit outside the modeled envelope. Forecasts reflect assumptions about technology substitution pace and regulatory enforcement consistency. Revision becomes warranted when neodymium price volatility or automotive lightweighting mandate stringency crosses thresholds that alter payback period calculations for electric system adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Winch Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Induction Furnace Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Part Feeder Market
Construction Equipment
United States Crane Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Jackhammer Market
Construction Equipment
India Crane Market